
 Design Collaboration Software Market | 2026-2036
Design Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Design Collaboration Software Market Outlook
Subscription-based pricing for software-defined feature modules is restructuring how design collaboration platforms capture recurring revenue. Figma leverages its browser-native architecture to dominate real-time vector editing workflows. Canva anchors the self-serve graphic design segment through template-driven user acquisition. Monday.com competes in workflow automation by extending its no-code automation engine into creative operations.
Design collaboration software encompasses cloud-native and on-premise platforms that enable synchronous and asynchronous editing, version control, and stakeholder feedback loops across distributed creative teams. These systems operate through WebRTC protocols, vector-based rendering engines, and API-first architectures to maintain sub-100ms latency during multi-cursor editing sessions. Cloud-based deployment leads solution type adoption as enterprises prioritize elastic scaling and zero-touch provisioning over capital-intensive server maintenance. Real-time editing and workflow automation represent the fastest-expanding solution categories, while version control modules command premium pricing from regulated industries requiring immutable audit trails. Product design and architecture planning use cases concentrate the highest-margin deployments due to complex permission hierarchies and BIM integration requirements.
FDA 21 CFR Part 11 guidelines shape validation requirements for design collaboration tools used in medical device development, while ISO 9001 quality management standards mandate documented change control in engineering workflows. The EU AI Act introduces emerging compliance obligations for generative design features that automate creative decision-making. Stakeholders must evaluate how regulatory divergence across jurisdictions affects data residency architectures and cross-border team enablement.
Market Dynamics
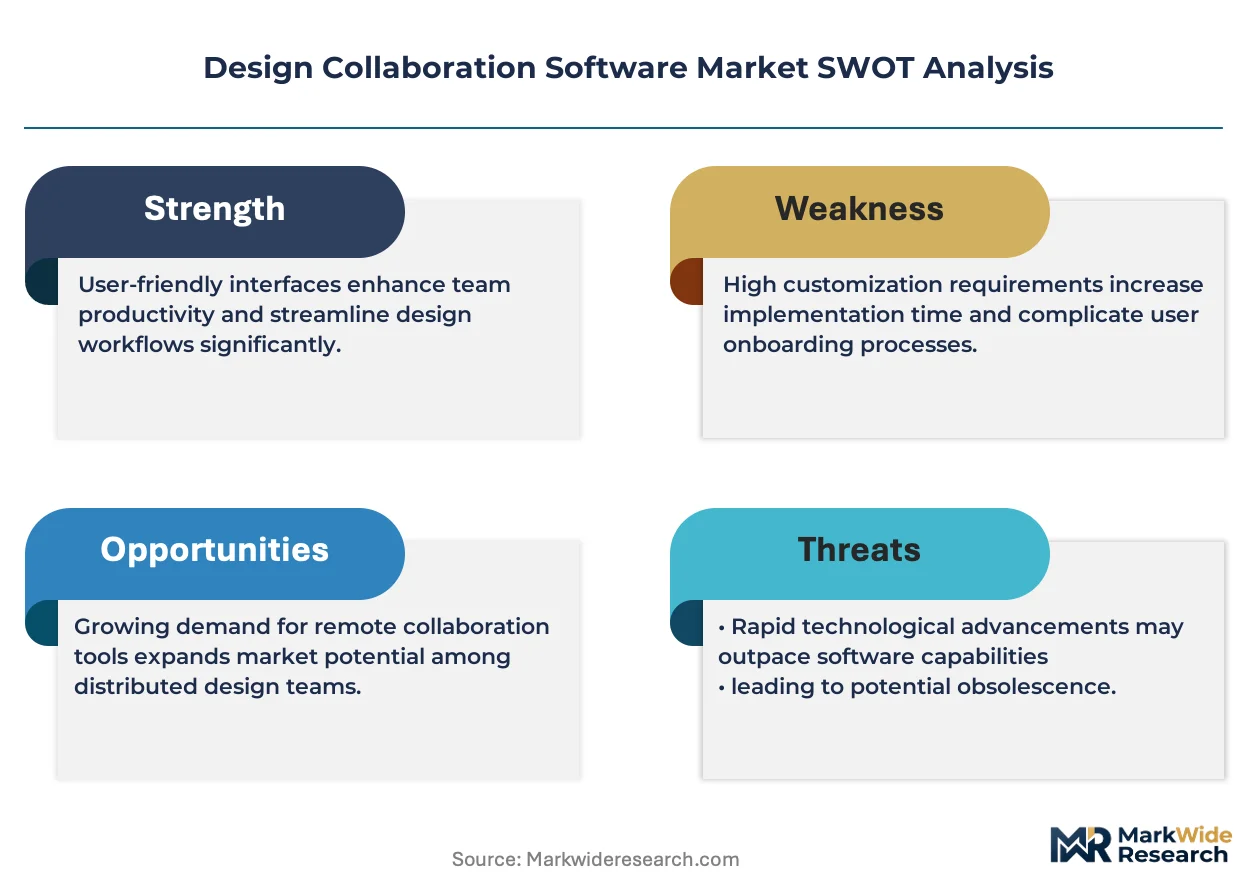
Enterprise IT governance frameworks are mandating cloud-first deployment policies that accelerate displacement of legacy on-premise design systems. This structural shift forces architecture firms and engineering consultancies to consolidate vendor relationships around integrated workflow automation suites.
Growth Catalysts
- Cloud-first mandates:Enterprise IT governance frameworks in the United States are accelerating migration from capital-intensive server maintenance to elastic scaling architectures.
- ISO 9001 compliance:Engineering workflows require documented change control systems that design collaboration platforms provide through immutable audit trail modules.
- BIM integration:Architecture planning use cases demand complex permission hierarchies that drive premium pricing for specialized deployment configurations.
Market Restraints
- Data residency requirements:Cross-border team enablement faces friction from regulatory divergence across jurisdictions affecting cloud architecture decisions.
- WebRTC latency floors:Sub-100ms synchronization thresholds create technical limitations for distributed teams operating on congested networks.
- Legacy system entrenchment:Capital-intensive on-premise investments in regulated industries create switching cost barriers to cloud migration.
Strategic Opportunities
- EU AI Act compliance:Generative design features that automate creative decision-making create new product categories requiring built-in regulatory guardrails.
- Medical device development:FDA 21 CFR Part 11 validation requirements open specialized verticals for platforms with pre-configured compliance modules.
- Workflow automation convergence:No-code automation engines are integrating with creative operations to capture adjacent budget categories.
Industry Challenges
- API architecture complexity:Maintaining interoperability across vector-based rendering engines and third-party systems requires specialized engineering talent.
- Multi-cursor synchronization:Real-time editing sessions demand infrastructure investments that strain mid-market vendor operational margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Design Collaboration Software Market |
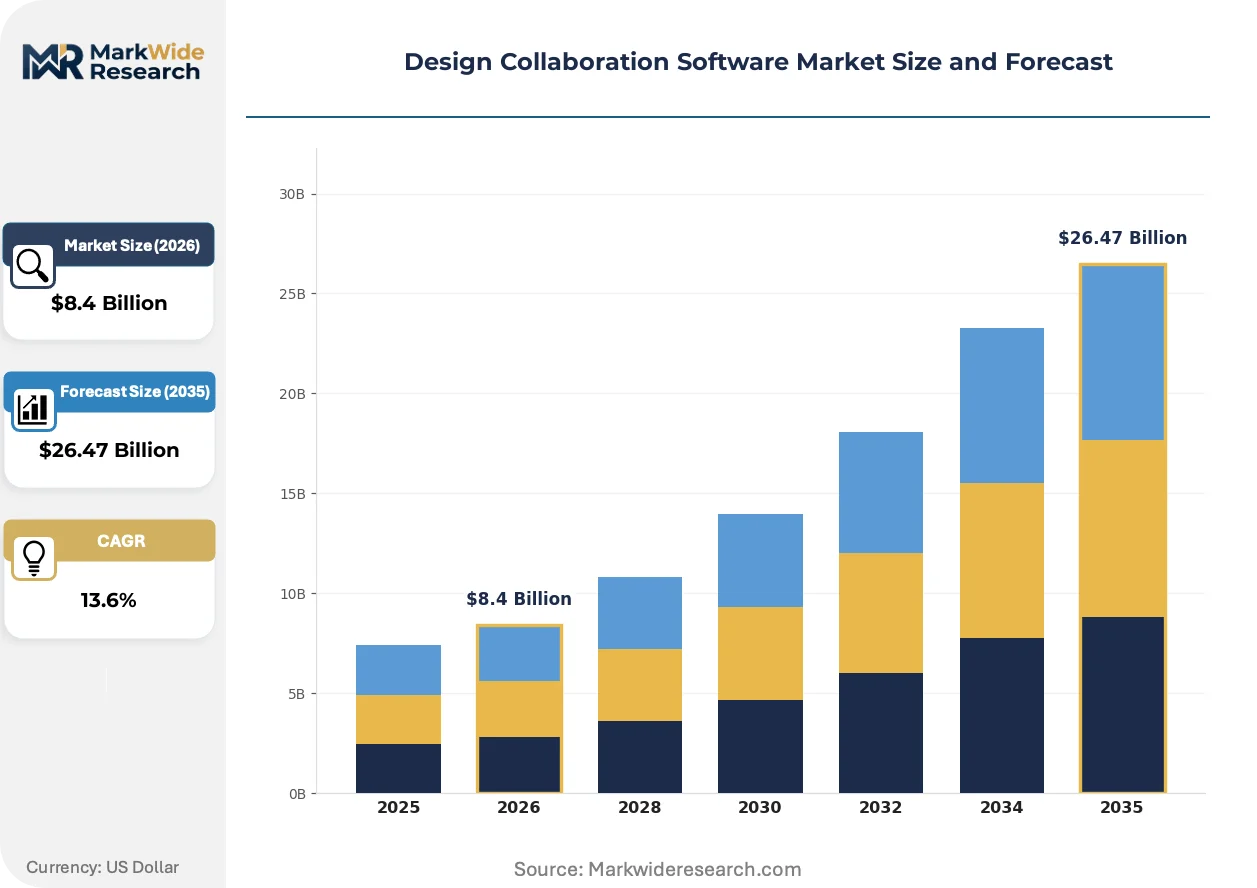
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.47 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Virtual Private Cloud Solution Type: Real-time Editing, Document Management, Workflow Automation, Version Control, Commenting Tools Use Case: Product Design, Architecture Planning, Graphic Design, Engineering Review, Marketing Campaigns End User Industry: Manufacturing, Architecture Firms, Advertising Agencies, Engineering Consultancies, Media Production |
| Companies Covered | Canva, Asana, Figma, ClickUp, Monday.com, Miro, MockFlow, Notion, Mural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Design Collaboration Software Market Strategic Shifts
Vector-based rendering engines are converging with generative AI capabilities to compress creative production cycles. Browser-native architectures are displacing desktop-bound workflows across distributed creative teams.
WebRTC protocols are integrating with vector-based rendering engines to enable sub-100ms multi-cursor editing sessions. Media production studios in the United States are adopting these stacks at accelerated paces to coordinate geographically dispersed talent pools. The technology is integrating synchronous feedback loops into previously asynchronous review cycles, compressing project timelines.
GDPR data residency provisions are mandating regional cloud infrastructure deployment for European creative teams. The regulation forces vendors to maintain separate instance architectures rather than centralized global stacks. Medical device developers in Germany face the strictest interpretation, requiring local audit trail storage that increases operational complexity.
Self-serve template libraries are displacing traditional agency retainer relationships in graphic design procurement. Small and mid-sized marketing teams are adopting browser-based platforms that eliminate onboarding friction. This pattern concentrates in the United States and United Kingdom where SaaS purchasing autonomy has decentralized from central IT departments.
Design Collaboration Software Market Segmentation
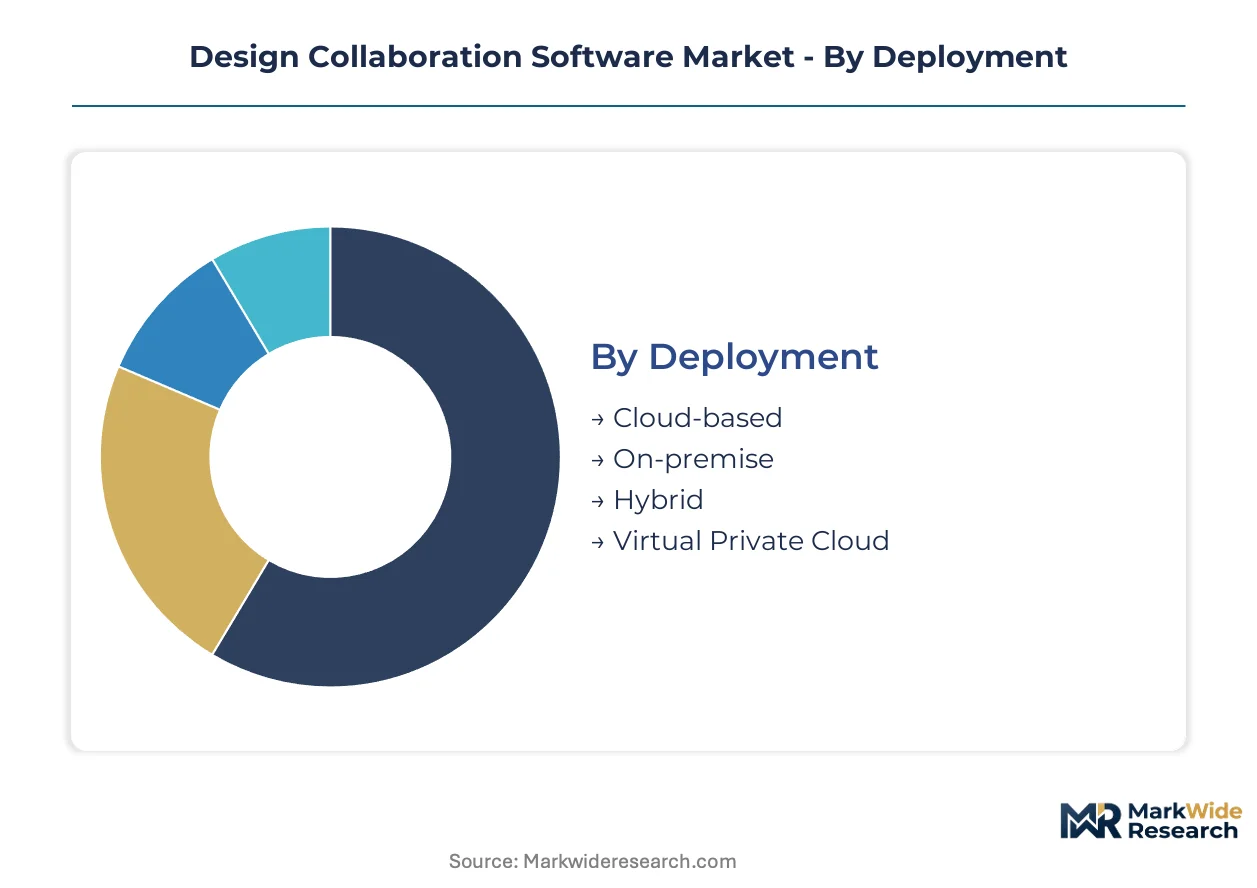
Deployment models and solution architectures fragment the Design Collaboration Software Market into distinct commercial battlegrounds. Each segment carries divergent margin profiles, compliance burdens, and switching cost dynamics that reshape vendor competitive positioning.
Deployment:
Volume concentrates in elastic scaling tiers while premium pricing attaches to sovereign control configurations.
- Cloud-based:Elastic scaling architectures dominate enterprise procurement through zero-touch provisioning and consumption-based billing. United States engineering consultancies and media production studios are consolidating vendor relationships around these stacks as IT governance frameworks mandate cloud-first migration.
- On-premise:Capital-intensive server deployments persist in regulated verticals requiring immutable audit trail custody. Medical device developers in Germany face the strictest data residency interpretations, forcing local infrastructure maintenance that inflates operational complexity.
- Hybrid:Split-stack configurations synchronize sensitive assets on-premise while pushing collaborative layers to cloud edge nodes.
- Virtual Private Cloud:Isolated tenant environments address GDPR data residency provisions through regional instance architectures.
Today's leader: Cloud-based. Tomorrow's challenger: Virtual Private Cloud.
Solution Type:
Functional modules stratify by workflow integration depth and latency tolerance thresholds.
- Real-time Editing:WebRTC protocols enable sub-100ms multi-cursor synchronization across distributed creative teams. Architecture firms expanding adoption of these platforms coordinate BIM-integrated design reviews spanning multiple time zones.
- Workflow Automation:No-code automation engines capture adjacent budget categories by extending into creative operations. Monday.com and competing platforms leverage this expansion path to displace standalone project management tools.
- Document Management:Centralized asset repositories with permission hierarchies serve regulated industries requiring ISO 9001 documented change control.
- Version Control:Immutable audit trail modules command premium pricing from FDA 21 CFR Part 11 validation workflows in medical device development.
- Commenting Tools:Asynchronous feedback loops compress review cycles in marketing campaign workflows with lower synchronization requirements.
Workflow automation is gaining share fastest. Version control maintains the steepest pricing power.
Use Case:
Application complexity determines integration requirements and customer lifetime value trajectories.
- Product Design:Vector-based rendering engines converge with generative AI capabilities to compress production cycles. Manufacturing teams in the United States adopt browser-native architectures to displace desktop-bound workflows.
- Architecture Planning:BIM integration demands complex permission hierarchies and specialized deployment configurations. Engineering consultancies consolidate around integrated suites that span structural modeling through stakeholder presentation.
- Graphic Design:Self-serve template libraries displace traditional agency retainer relationships. Canva anchors this segment through template-driven user acquisition in decentralized SaaS purchasing environments.
- Engineering Review:Synchronous feedback loops compress previously asynchronous review cycles in cross-functional validation workflows.
- Marketing Campaigns:Rapid iteration requirements prioritize low-friction onboarding over deep feature sophistication.
Architecture planning commands the highest contract values. Graphic design delivers the broadest user base expansion.
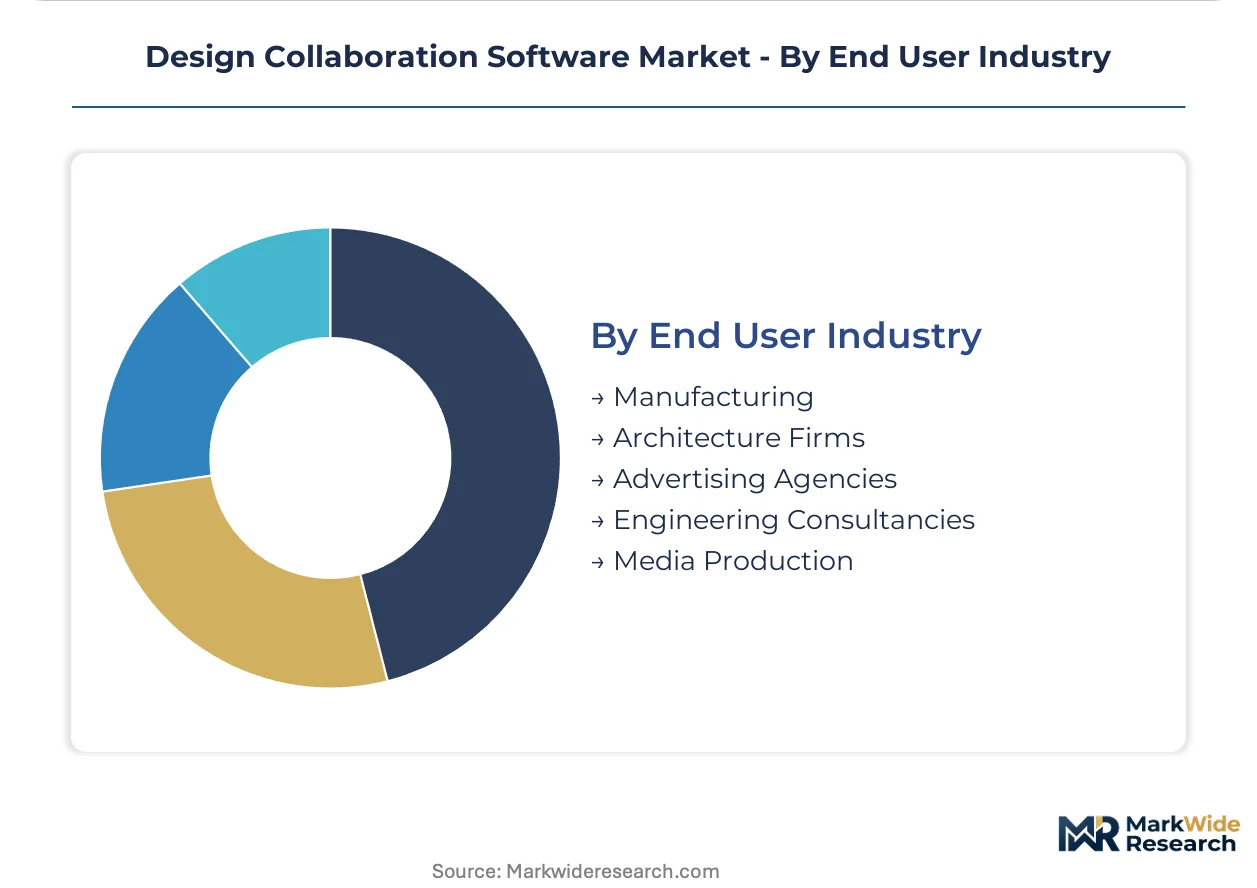
End User Industry:
Vertical specialization drives divergent compliance requirements and procurement autonomy patterns.
- Manufacturing:ISO 9001 quality management standards mandate documented change control systems. Production engineering teams prioritize version control modules with immutable audit trail capabilities.
- Architecture Firms:Real-time editing platforms coordinate distributed design teams across multiple project sites. Cloud-first mandates from enterprise IT governance frameworks accelerate displacement of legacy on-premise systems.
- Advertising Agencies:Template-driven workflows and rapid client turnaround requirements favor browser-native self-serve platforms.
- Engineering Consultancies:Workflow automation convergence captures budget categories previously allocated to standalone project management tools.
- Media Production:Sub-100ms latency requirements for multi-cursor editing strain infrastructure investments across geographically dispersed talent pools.
Architecture firms anchor current deployment velocity. Engineering consultancies present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering consultancies in Germany command higher contract values than their counterparts in India, yet Indian media production studios are deploying real-time editing platforms at comparable velocity to compress project timelines.
United States
Enterprise IT governance frameworks mandate cloud-first deployment policies that accelerate displacement of legacy on-premise systems. FDA 21 CFR Part 11 guidelines shape validation requirements for medical device developers in Minneapolis and Boston medical technology corridors. Media production studios in Los Angeles and New York consolidate vendor relationships around integrated workflow automation suites.
Germany
Architecture firms expand adoption of BIM-integrated design review platforms to coordinate distributed teams across multiple project sites. GDPR data residency provisions mandate regional cloud infrastructure deployment, with medical device developers in Stuttgart facing strict local audit trail storage requirements. Engineering consultancies in Munich and Hamburg prioritize ISO 9001 documented change control systems.
United Kingdom
Self-serve template libraries displace traditional agency retainer relationships as SaaS purchasing autonomy decentralizes from central IT departments. The UK Information Commissioner's Office enforces GDPR-aligned data residency standards for creative teams. Advertising agencies in London and Manchester favor browser-native platforms that eliminate onboarding friction for rapid client turnaround.
India
Media production studios adopt WebRTC-enabled editing stacks to coordinate geographically dispersed talent pools across Bengaluru and Mumbai technology corridors. The country's national data protection framework introduces emerging compliance obligations for cross-border team enablement. Product design teams in Hyderabad leverage browser-native architectures to displace desktop-bound manufacturing workflows.
Japan
Manufacturing engineering teams prioritize version control modules with immutable audit trail capabilities to satisfy METI quality management standards. The PMDA imposes validation requirements on design collaboration tools used in pharmaceutical device development. Industrial design clusters in Nagoya and Osaka integrate vector-based rendering engines with generative AI capabilities.
Design Collaboration Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with browser-native platforms capturing recurring revenue through subscription-based pricing for software-defined feature modules. The vendor base stratifies into three tiers: workflow automation suite providers, real-time vector editing specialists, and self-serve template platform operators. Competitive moves concentrate on API-first architecture investments and regional data residency compliance certifications.
Within the real-time editing tier, Figma exemplifies browser-native architecture dominance, while Canva occupies a position anchoring self-serve graphic design procurement. Monday.com sits within the workflow automation convergence archetype, extending no-code engines into creative operations to capture adjacent budget categories.
| Leading Market Players |
|---|
| Canva |
| Asana |
| Figma |
| ClickUp |
| Monday.com |
| Miro |
| MockFlow |
| Notion |
| Mural |
| Others |
Value Chain & Pricing Dynamics
Browser-native architecture premiums diverge sharply from legacy on-premise maintenance contracts, compressing margins for vendors tethered to capital-intensive server deployments while rewarding elastic scaling providers with recurring SaaS multiples. This bifurcation manifests in procurement patterns where United States engineering consultancies consolidate around consumption-based billing, while German medical device developers absorb inflated operational complexity from local audit trail custody requirements.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for cloud infrastructure tiers, intensifying cost compression in standard subscription bands. Subscription-based SaaS models dominate enterprise procurement, with price differentiation anchored in ISO 9001 certification tiers and BIM integration depth. Pricing pressure stems from WebRTC latency optimization investments that strain mid-market vendor margins. Advertising agencies exhibit highest price sensitivity, while medical device developers demonstrate lowest sensitivity due to FDA 21 CFR Part 11 validation requirements.
Supply Chain Analysis
WebRTC protocol development rests on specialized engineering talent pools concentrated in the United States, Germany, and India. Vector-based rendering engines draw from GPU cloud compute providers, browser compatibility frameworks, and API middleware layers. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies for real-time synchronization workloads. Distribution runs through direct enterprise sales, self-serve browser onboarding, and channel partner integrations with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure cost differentials between India and Germany create geographic-arbitrage opportunities for vendors optimizing data residency architectures against operational expenditure burdens.
For Market Incumbents: Anchor defensive positioning through vertical integration into API middleware layers and preemptive EU AI Act compliance certification. Consolidate vendor relationships by absorbing adjacent workflow automation budget categories. Threaten emerging no-code automation entrants through platform bundling. Leverage BIM integration depth as switching cost moat. For New Entrants and Emerging Players: Mid-market architecture firms in India represent an underserved buyer archetype demanding localized BIM-integrated solutions without enterprise pricing. White-space targets include self-serve template libraries for decentralized SaaS procurement environments and WebRTC-enabled stacks for media production studios compressing project timelines. Go-to-market through browser-native zero-touch provisioning eliminates onboarding friction. For Investors and Strategic Acquirers: Consolidation pressure builds where API architecture complexity outpaces mid-market vendor engineering capacity. Long-term viability favors platforms with pre-configured compliance modules spanning FDA, ISO 9001, and emerging EU AI Act obligations. Acquisition target archetype: specialized version control vendors with immutable audit trail capabilities in regulated verticals. Signal to watch: hyperscaler infrastructure partnership announcements indicating elastic scaling cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Monday.com extends no-code automation into creative operations to capture adjacent budget categories. |
| Geographic Expansion | Virtual Private Cloud deployments address GDPR data residency mandates for European creative teams. |
| Strategic Partnership | WebRTC protocol alliances with hyperscalers reduce sub-100ms latency infrastructure costs. |
| Acquisition of Specialist Firm | Version control vendors with FDA 21 CFR Part 11 modules command premium valuations. |
| Product Launch | Generative AI design features require built-in EU AI Act regulatory guardrails for market entry. |
Study Parameters
Multiple input streams — primary interviews with platform engineers and IT procurement officers, secondary validation against SEC filings and hyperscaler capex disclosures, and technical architecture assessments — were reconciled through bottom-up and top-down triangulation. Stakeholder roles included CTOs at architecture firms, biomedical engineers in medical device development, integration specialists at engineering consultancies, and channel partners distributing workflow automation suites. Secondary sources encompassed FDA 510(k) filings, ISO certification databases, GDPR enforcement actions by national data protection authorities, and cloud infrastructure provider technical documentation.
Data-stream reconciliation applied across the analysis window modeled deployment model transitions, organization size tiers, vertical specialization depth, and regional adoption patterns. CAGRs were derived from segment-level growth trajectory synthesis against macroeconomic elasticity assumptions. Industry-specific forecast inputs incorporated WebRTC protocol adoption curves and BIM integration penetration rates in architecture planning workflows.
Underlying measurement precision varies by segment; cloud-based deployment and real-time editing categories carry tighter precision than emerging hybrid configurations. Forecasts reflect documented assumptions regarding enterprise IT governance mandate velocity and cross-border data residency enforcement consistency. Regulatory divergence across jurisdictions, WebRTC latency technical limitations, and generative AI compliance obligation evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Artwork Management Software Market
Software & Services
Cursor Reviewer Market
Software & Services
Global Policy Management Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Language Translation Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Office Productivity Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Output Management Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Mobile Application Development Platform (MADP) Market