
 Utility Cases Market | 2026-2036
Utility Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Cases Market Analytics
Capital-intensity divergence between injection-molded hard-case producers and fabric-based soft-case assemblers is redrawing competitive boundaries in the protective equipment sector. Pelican Products, Inc. leverages deep vertical manufacturing control over polymer formulations and pressure-valve engineering to command premium positioning in electronics protection. SKB Corporation anchors its position through dedicated music and audio equipment specialization, sustaining loyalty among touring professionals and instrument manufacturers. ZARGES GmbH differentiates through aluminum alloy expertise, dominating industrial and military-grade applications where metal durability outweighs weight penalties.
Utility cases are engineered protective enclosures designed to shield equipment from impact, moisture, dust, and temperature extremes through structural reinforcement, gasket sealing systems, and custom-configured foam interiors. Hard cases fabricated from polypropylene copolymers or ABS composites deliver maximum impact resistance for precision electronics and sensitive instrumentation. Soft cases constructed from ballistic nylon or reinforced polyester occupy the lightweight mobility tier where fabric flexibility and reduced shipping bulk serve field technicians and mobile workers. Hybrid cases combining rigid shells with fabric panels are gaining traction as manufacturers respond to end-user demand for modular protection that adapts across transport modes and storage conditions.
FDA guidelines for medical device transport containers, EPA standards on recycled content in federal procurement, and OSHA workplace equipment protection mandates collectively elevate baseline performance requirements across North American supply chains. REACH chemical restrictions in Europe and RoHS substance limitations are compelling material reformulation investments that favor producers with in-house polymer development capabilities. Stakeholders must monitor evolving customs classification disputes around composite-material cases to anticipate tariff exposure and regional sourcing arbitrage opportunities.
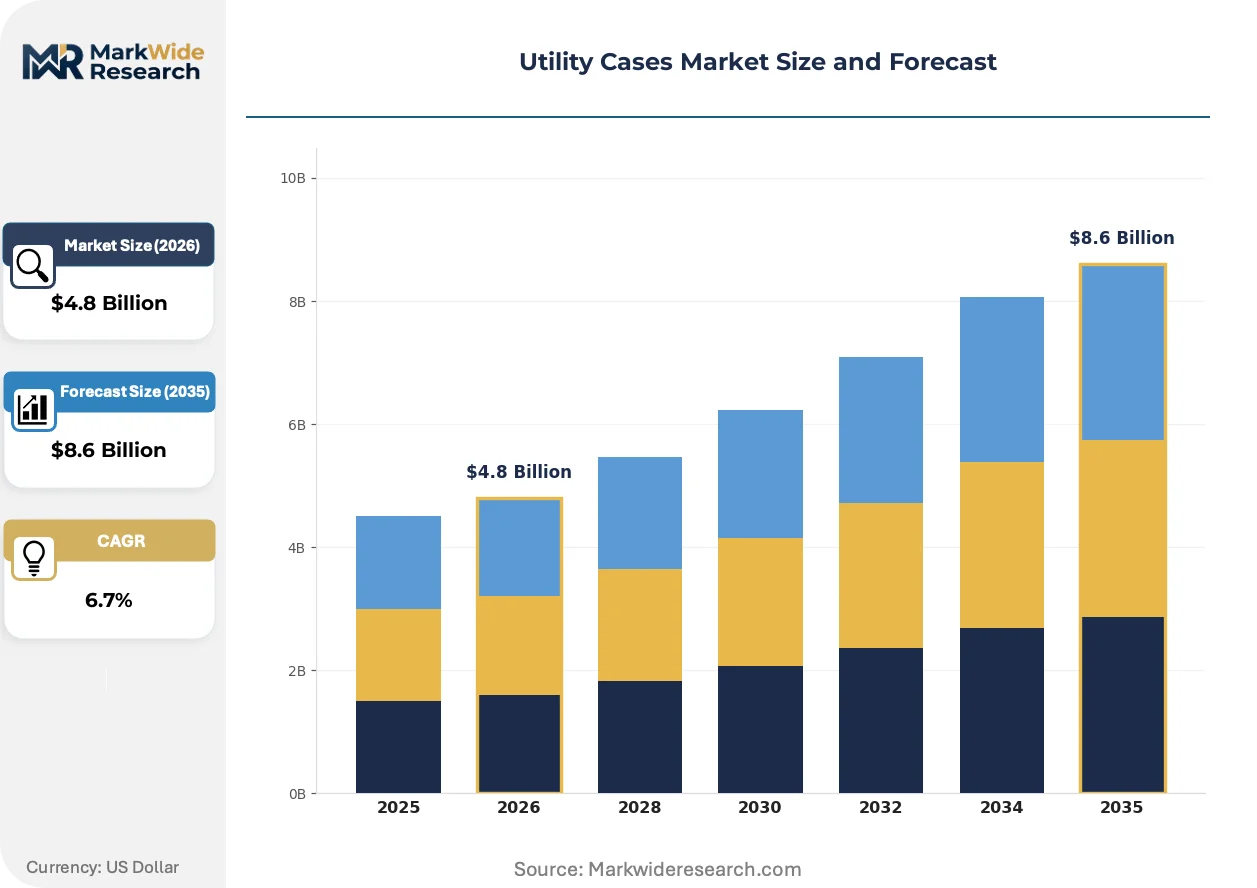
Market Dynamics
Telecom infrastructure expansion is redrawing demand geography for protective enclosures as 5G network deployment accelerates equipment field deployment across rural and urban zones.
Growth Catalysts
- EU Green Deal recycled content mandates:Procurement specifications across European public sectors now require minimum recycled polymer thresholds, redirecting manufacturer R&D toward sustainable formulation chemistry.
- Industrial tool protection standardization:German DIN certification requirements for precision equipment transport are elevating baseline performance specifications across continental supply chains.
- Ballistic nylon material advancement:Fabric weaves with enhanced abrasion resistance are capturing share in field technician mobility applications where weight reduction outweighs hard-shell durability.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene copolymer pricing swings tied to naphtha cracking economics compress margin predictability for injection-molded case producers.
- Aluminum alloy supply concentration:Primary smelter capacity clustering in specific geographies exposes ZARGES-tier metal case manufacturers to tariff and logistics disruption risk.
- REACH chemical restriction compliance:ECHA substance authorization timelines extend product reformulation cycles by 18-24 months, freezing specification updates for EU-bound shipments.
Strategic Opportunities
- India PLI scheme for telecom equipment:Domestic manufacturing incentives for 5G infrastructure are creating localized demand for protective enclosures meeting BIS certification standards.
- Drone delivery logistics integration:Last-mile aerial transport protocols require lightweight cases with aerodynamic profiles and drop-tested latching systems.
- Hybrid case format convergence:Rigid-shell fabric-panel combinations address modular protection needs across multimodal transport chains serving renewable energy field service teams.
Industry Challenges
- Pressure-valve engineering talent scarcity:Specialized mechanical design expertise for altitude-compensating sealing systems remains concentrated among legacy aerospace suppliers.
- FDA medical device container validation timelines:Biocompatibility testing and sterilization protocol verification extend product commercialization cycles for healthcare-focused case lines.
- Custom foam interior digitization:CNC routing and 3D scanning integration for equipment-specific cushioning requires capital investment in additive manufacturing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Cases Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Cases, Soft Cases, Hybrid Cases, Custom Cases Application: Mobile Devices, Electronics, Tools, Storage Solutions Material: Plastic, Metal, Fabric, Foam End User: Consumers, Retailers, Manufacturers, Event Organizers |
| Companies Covered | Pelican Products, Inc., SKB Corporation, Seahorse Protective Equipment Cases, NANUK, Plano Molding Company, ZARGES GmbH, PARAT Beteiligungs GmbH, Cases By Source, Inc., Nefab Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Cases Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are simultaneously compressing legacy formulation advantages while opening modular design architectures.
Modular foam interior systems are fragmenting the traditional custom-cushioning value chain. Field service organizations in renewable energy and medical device sectors are adopting reconfigurable divider kits at accelerating pace. This technology is fragmenting the historical dominance of permanently bonded foam fabricators and enabling case manufacturers to capture aftermarket accessory revenue streams previously ceded to third-party fit-out specialists.
REACH substance restrictions and RoHS substance limitations are compelling polymer reformulation investments across European supply chains. Producers with in-house material development capabilities are securing specification lock-in for electronics and instrumentation protection contracts. Medical device transport container categories face the steepest compliance burden as ECHA authorization timelines intersect with MDR device classification requirements.
Direct procurement from manufacturer digital platforms is compressing traditional distribution markups in the professional audio and industrial tool segments. Rental house operators and field service fleets are bypassing regional distributors to negotiate volume pricing and specification customization. This channel shift is most visible in Germany where industrial procurement centralization and DIN standard familiarity reduce buyer reliance on distributor technical support.
Utility Cases Market Segmentation
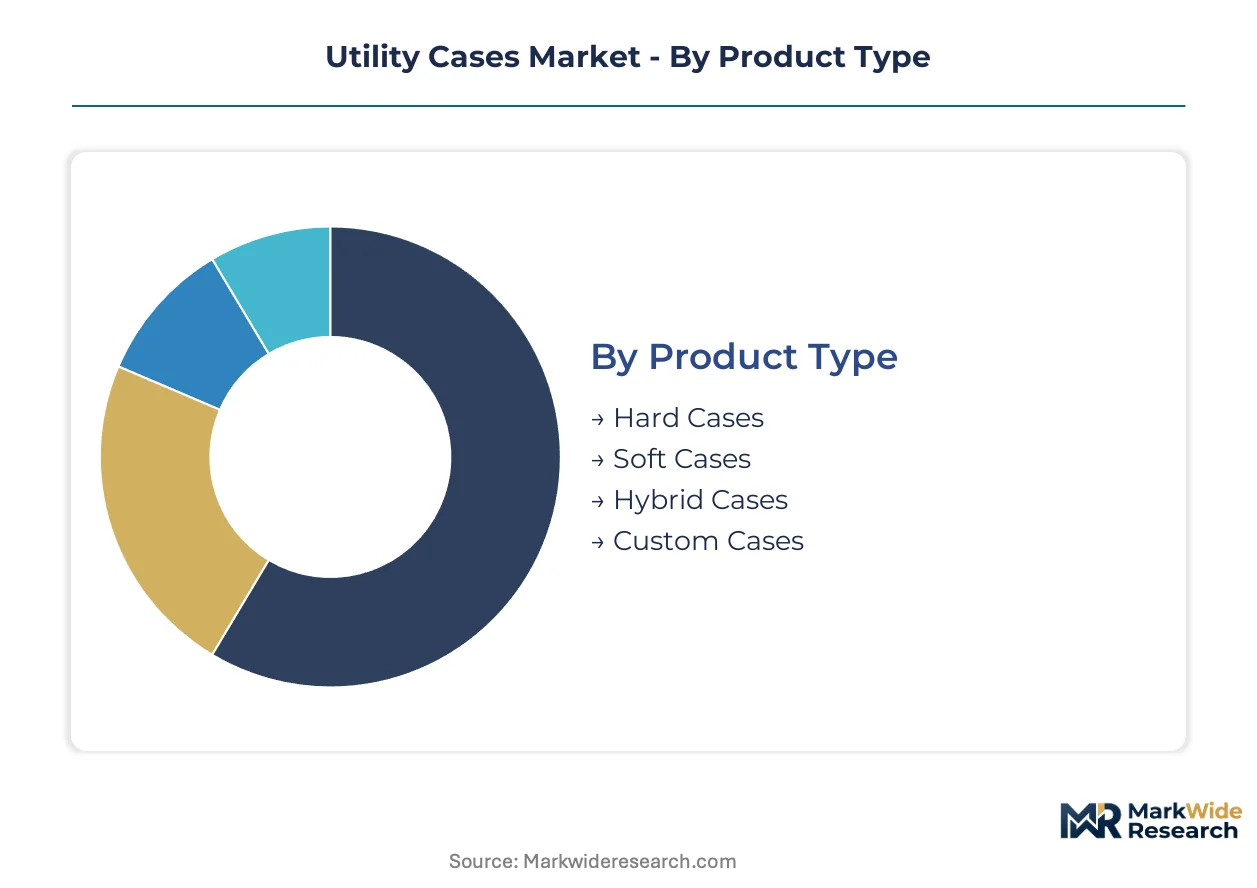
Segmentation in utility cases reveals how protection requirements fragment across equipment sensitivity, transport intensity, and regulatory exposure. Margin capture follows material chemistry control and certification depth rather than volume scale alone.
Product Type:
Margin pools concentrate in hard cases where polymer formulation patents and pressure-valve engineering create specification lock-in for aerospace and medical device contracts.
- Hard Cases:Injection-molded polypropylene copolymers and ABS composites deliver maximum impact resistance through structural ribbing and gasket-sealed lids. Demand concentrates in Germany for precision electronics protection under stringent DIN certification requirements for industrial tool transport.
- Hybrid Cases:Rigid-shell fabric-panel combinations address multimodal transport needs across renewable energy field service chains. These configurations are gaining share fastest among drone logistics operators requiring aerodynamic profiles with drop-tested latching systems.
- Soft Cases:Ballistic nylon and reinforced polyester constructions serve mobile technicians prioritizing weight reduction over hard-shell durability.
- Custom Cases:Equipment-specific foam interiors and CNC-routed cushioning configurations serve medical device manufacturers facing extended FDA biocompatibility validation timelines.
Hard cases hold installed capacity. Hybrid cases are rotating up the share rankings.
Application:
Volume concentration tracks equipment replacement cycles and field deployment intensity across telecom infrastructure and renewable energy maintenance.
- Electronics:Semiconductor test equipment and broadcast cameras require altitude-compensating pressure valves and electrostatic discharge protection. Demand clusters in 5G network deployment zones where rural and urban infrastructure expansion accelerates protective enclosure procurement.
- Tools:Precision measurement instruments and calibrated industrial equipment face DIN standard compliance requirements in Germany. These specifications are elevating baseline performance across continental European supply chains.
- Mobile Devices:Smartphone and tablet protection occupies the consumer-accessible tier with lower certification barriers.
- Storage Solutions:Archival media and document transport cases serve legal and financial services with moderate technical specifications.
Electronics commands the steepest expansion trajectory. Tools maintains specification leadership in European procurement.
Material:
Supply concentration in primary smelters and petrochemical feedstock regions dictates margin volatility and tariff exposure for case manufacturers.
- Plastic:Polypropylene copolymers and ABS composites dominate injection-molded production with REACH and RoHS compliance requirements compelling reformulation investments. Producers with in-house polymer development are securing electronics protection contracts in EU markets.
- Fabric:Ballistic nylon weaves with enhanced abrasion resistance capture field technician mobility applications. EU Green Deal recycled content mandates are redirecting manufacturer priorities toward sustainable polymer formulations.
- Metal:Aluminum alloy cases from concentrated primary smelter geographies expose manufacturers to logistics disruption risk.
- Foam:Custom-cushioning polyurethane and polyethylene configurations face modular disruption from reconfigurable divider kits.
Plastic retains formulation scale. Fabric is climbing the fastest in renewable energy field service adoption.
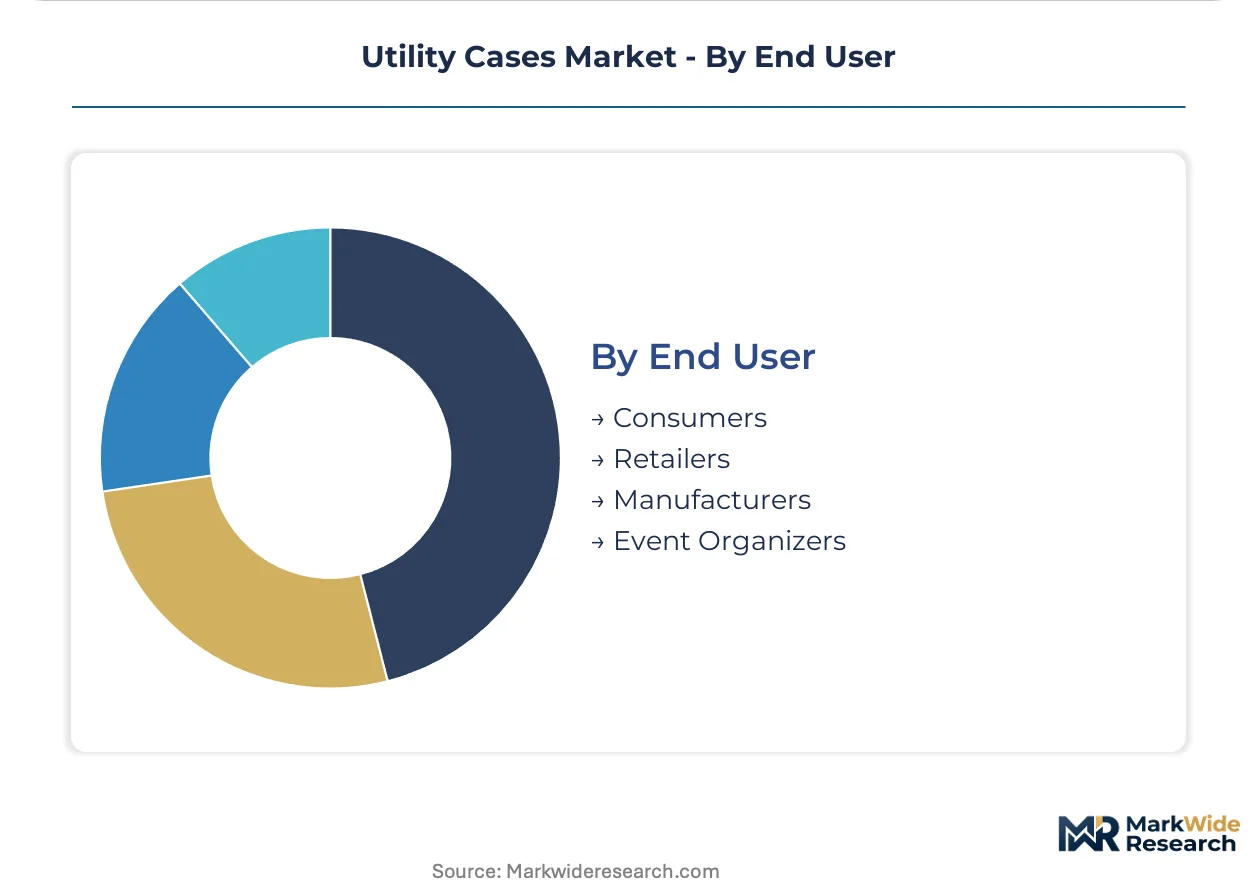
End User:
Procurement centralization and technical specification familiarity determine channel structure and distributor bypass potential.
- Manufacturers:Industrial tool and electronics producers specify DIN-certified transport containers with centralized procurement functions. German industrial buyers are negotiating direct manufacturer relationships, compressing traditional distribution markups.
- Consumers:Individual purchasers drive volume in mobile device protection with price-sensitive specifications and retail channel dependence.
- Retailers:Rental house operators in professional audio bypass regional distributors for volume pricing and customization.
- Event Organizers:Touring production companies prioritize rapid turnaround and logistics coordination over technical specification depth.
Manufacturers anchor contract value. Retailers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing through DIN certification requirements while India captures volume through PLI-enabled telecom infrastructure localization. This asymmetry reflects divergent regulatory burden and manufacturing scale across protective equipment procurement zones.
United States
FAA drone delivery integration and OSHA workplace equipment mandates drive protective enclosure specifications. EPA recycled content standards for federal procurement elevate baseline polymer formulation requirements. Industrial clusters in Texas and California concentrate 5G infrastructure deployment activity with specialized logistics coordination.
Germany
Precision electronics manufacturers specify DIN-certified transport containers with centralized procurement functions. REACH chemical restrictions compel material reformulation investments across polymer supply chains. Bavaria and Baden-Württemberg host automotive and industrial tool producers demanding stringent protection standards.
China
MIIT 5G base station deployment accelerates field equipment protection procurement across rural and urban zones. GB standards for electronics transport containers align with RoHS substance limitations. Yangtze River Delta manufacturers concentrate injection-molded hard-case capacity serving domestic and export markets.
India
PLI scheme incentives for telecom equipment manufacturing create localized demand for BIS-certified protective enclosures. TRAI infrastructure mandates accelerate 5G network equipment field deployment. Maharashtra and Karnataka industrial corridors concentrate electronics assembly and protective equipment sourcing.
Japan
METI industrial equipment protection guidelines elevate baseline specifications for precision instrumentation transport. JIS standards for polymer formulations intersect with RoHS compliance requirements. Kanto and Kansai manufacturing belts concentrate semiconductor test equipment producers with specialized case requirements.
Utility Cases Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the protective equipment sector. Market structure fragments between polymer formulation specialists, metal fabricators, and fabric-based assemblers with divergent capital intensity profiles. Three archetypes dominate: vertically integrated polymer compounders, aluminum alloy specialists, and ballistic nylon assemblers. Competitive moves concentrate on specification lock-in through certification depth and direct procurement platform development bypassing traditional distribution channels.
Among North American protective equipment specialists, Pelican Products, Inc. and SKB Corporation exemplify divergent specialization strategies. Pelican occupies a position representing polymer formulation control and pressure-valve engineering capability. SKB sits within the music and audio equipment specialist tier. ZARGES GmbH anchors the aluminum alloy industrial-grade segment among European metal case fabricators.
| Leading Market Players |
|---|
| Pelican Products, Inc. |
| SKB Corporation |
| Seahorse Protective Equipment Cases |
| NANUK |
| Plano Molding Company |
| ZARGES GmbH |
| PARAT Beteiligungs GmbH |
| Cases By Source, Inc. |
| Nefab Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for polypropylene copolymer feedstock lock in both raw material access and margin predictability for injection-molded hard-case producers serving German industrial tool protection markets. These arrangements insulate vertically integrated compounders from naphtha cracking volatility while exposing fabric-based assemblers to spot market polyester pricing swings.
Pricing Analysis
The customization-premium spread separates DIN-certified configured-to-order cases from standard SKUs by certification depth and foam interior complexity. Three-tier pricing structure across premium, standard, and economy levels stratifies by pressure-valve engineering presence and REACH compliance tier. Price compression runs through the economy tier as Chinese injection-molders expand ABS composite capacity. Industrial manufacturers in Germany show lowest price sensitivity due to centralized procurement and specification familiarity, while field technician segments prioritize weight reduction over hard-shell durability.
Supply Chain Analysis
Gulf Coast petrochemical corridor concentration in the United States underwrites global polypropylene copolymer availability for protective enclosure manufacturers. Primary aluminum smelting clusters in China and Russia feed ZARGES-tier metal case fabricators, while ballistic nylon weaving capacity concentrates in Taiwan and South Korea. Single-source vulnerability in pressure-valve engineering talent from legacy aerospace suppliers constrains altitude-compensating sealing system production. Distribution runs through direct manufacturer digital platforms compressing traditional distributor markups in professional audio and industrial tool segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility case demand sits in early-cycle expansion as 5G network deployment accelerates protective equipment procurement across rural and urban infrastructure zones. Modular foam interior adoption is displacing permanently bonded cushioning fabricators and opening aftermarket revenue capture.
For Market Incumbents: Compound specification lock-in through DIN certification depth and in-house polymer formulation control. Deepen backward integration into recycled polymer chemistry to meet EU Green Deal procurement mandates. Defend against modular foam disruptors by acquiring CNC routing capabilities for equipment-specific cushioning digitization.
For New Entrants and Emerging Players: Aftermarket accessory under-service by legacy hard-case producers creates entry space for reconfigurable divider kit specialists. Target drone logistics operators requiring aerodynamic hybrid cases with drop-tested latching systems. Penetrate through direct procurement platform partnerships with renewable energy field service fleets bypassing regional distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive foam interior production and modular accessory ecosystems. Five-to-ten year viability favors vertically integrated polymer compounders with REACH-compliant formulation pipelines. Watch for BIS certification acceleration in India PLI-enabled telecom equipment manufacturing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polymer Formulation Investment | EU Green Deal procurement mandates redirect R&D toward sustainable chemistry for public sector contracts. |
| Modular Foam Interior Platform Launch | Reconfigurable divider kits fragment bonded foam fabricators and capture aftermarket accessory revenue. |
| Direct Procurement Platform Development | German industrial buyers bypass distributors through centralized DIN-standard familiarity and volume negotiation. |
| Drone Logistics Case Certification | Aerodynamic hybrid configurations with drop-tested latching address last-mile aerial transport protocols. |
| India BIS Certification Localization | PLI scheme incentives for telecom equipment create localized demand for protective enclosures meeting national standards. |
Research Methodology
The analysis maps hard-case polymer formulation, hybrid-shell fabrication, soft-case assembly, and custom foam interior configuration, each validated through plant managers at injection-molding facilities, procurement leads at industrial tool OEMs, and aftermarket service heads at field technician fleet operators. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, DIN certification registries, and ECHA substance authorization databases. Bottom-up capacity assessments and top-down demand triangulation cross-verified market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application sensitivity tier, material chemistry, and end-user procurement centralization. CAGRs derived from equipment replacement cycle analysis and infrastructure deployment intensity. Industry-specific forecast inputs incorporated 5G base station deployment schedules and REACH reformulation timeline constraints.
Underlying assumptions cover polymer feedstock price stability and certification timeline adherence, with deviation risk concentrated in ECHA authorization delays and aluminum alloy tariff exposure. Practitioners should keep alternative scenarios live as EU recycled content thresholds and India PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
Australia ICT Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Data Extraction Market
Digital Solutions
Digital Certificates Market