
 Construction Data Analytics Software Market | 2026-2036
Construction Data Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Data Analytics Software Market Insights
The shift from single-source enterprise suites toward multi-source best-of-breed stacks is rebalancing vendor competitive dynamics. Autodesk anchors its position through deep BIM interoperability and design-to-construction workflow continuity. Procore Technologies extends its cloud-native architecture into field analytics, competing on deployment speed for mid-market contractors. Bentley Systems specializes in infrastructure-scale digital twin integration, occupying the heavy civil and transportation segments where geospatial precision commands premium positioning.
Construction data analytics software encompasses platforms that ingest, process, and visualize structured and unstructured project data to generate actionable intelligence for cost, schedule, safety, and quality optimization. These systems typically integrate with IoT sensors, ERP modules, and BIM repositories to deliver real-time dashboards and predictive models that reduce variance in capital project outcomes. Cloud-based deployment leads in new customer acquisition due to lower upfront infrastructure requirements and faster implementation cycles, while on-premises solutions retain share among defense and critical infrastructure operators with stringent data sovereignty requirements. Project management analytics represents the largest solution offering by installed base, though risk analysis software is expanding fastest as insurers and lenders mandate probabilistic cost forecasting for large-scale developments.
The Federal Acquisition Regulation and OSHA recordkeeping requirements in the United States shape product roadmaps by mandating standardized safety incident reporting and audit trail retention. State-level prevailing wage laws and certified payroll regulations in California, New York, and Illinois create fragmented compliance templates that vendors must map into configurable analytics modules. Stakeholders should monitor how emerging federal infrastructure grant conditions will embed digital delivery standards into funding eligibility, as this linkage will determine which analytics capabilities become table stakes versus differentiators in contractor procurement decisions.
Market Dynamics
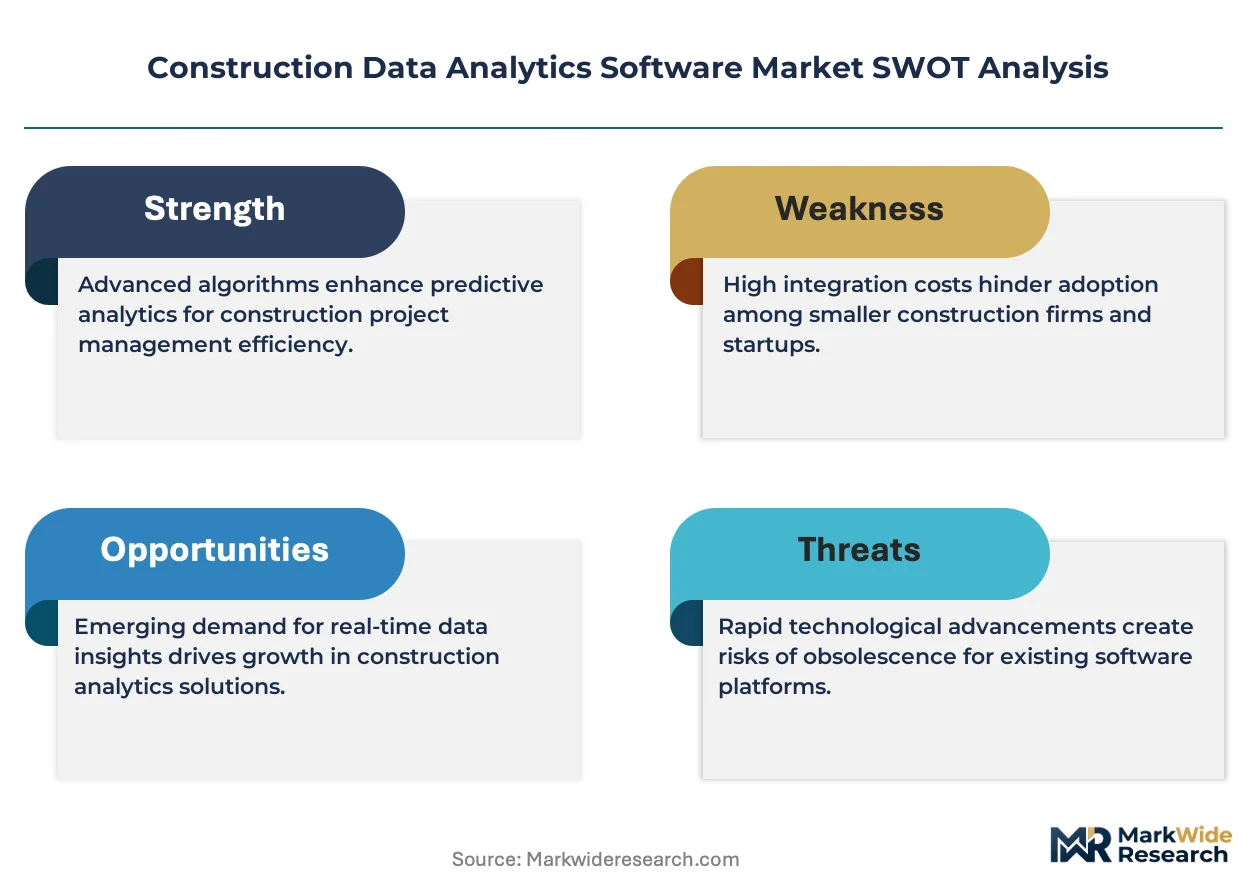
Cloud migration mandates from public infrastructure agencies are compressing software replacement cycles and forcing incumbent vendors to rearchitect legacy platforms for API-first interoperability with BIM repositories and IoT sensor networks.
Growth Catalysts
- BIM Level 2 Compliance:United Kingdom public procurement rules now mandate structured data handover, compelling contractors to adopt analytics platforms that automate compliance documentation and clash detection reporting.
- Heavy Civil Megaprojects:Equipment-intensive developments in the United States and Australia are deploying predictive maintenance algorithms to optimize fleet utilization and reduce idle-time penalties on fixed-price contracts.
- OSHA Recordkeeping Modernization:Digitized safety incident workflows with real-time dashboarding are becoming standard for federal contractors seeking favorable Experience Modification Rate scores.
Market Restraints
- Data Sovereignty Requirements:Defense and critical infrastructure operators in the United States and Saudi Arabia retain on-premises deployment mandates, fragmenting vendor R&D investment across incompatible architectures.
- Interoperability Tax:Proprietary data formats from legacy ERP systems require expensive middleware development, inflating implementation costs for mid-market contractors with thin IT margins.
- Skill Concentration:Data science talent pools cluster in metropolitan technology hubs, creating wage premiums that deter software adoption in secondary construction markets.
Strategic Opportunities
- India Infrastructure Pipeline:National highway and urban metro expansions lack indigenous analytics vendors, creating first-mover positioning for cloud-native platforms with localized compliance modules.
- Insurer-Mandated Risk Modeling:Lloyd's of London and major surety underwriters are embedding probabilistic cost forecasting into bond eligibility, expanding addressable market for specialized risk analytics modules.
- Digital Twin Convergence:Integration of geospatial LiDAR with real-time sensor streams is opening premium positioning for vendors serving transportation and water utility asset managers.
Industry Challenges
- Fragmented Compliance Templates:California prevailing wage laws, New York certified payroll rules, and Illinois reporting requirements force vendors to maintain state-specific analytics configurations.
- Legacy System Entrenchment:Decades-old project management databases resist API extraction, requiring costly manual migration and change management programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Data Analytics Software Market |
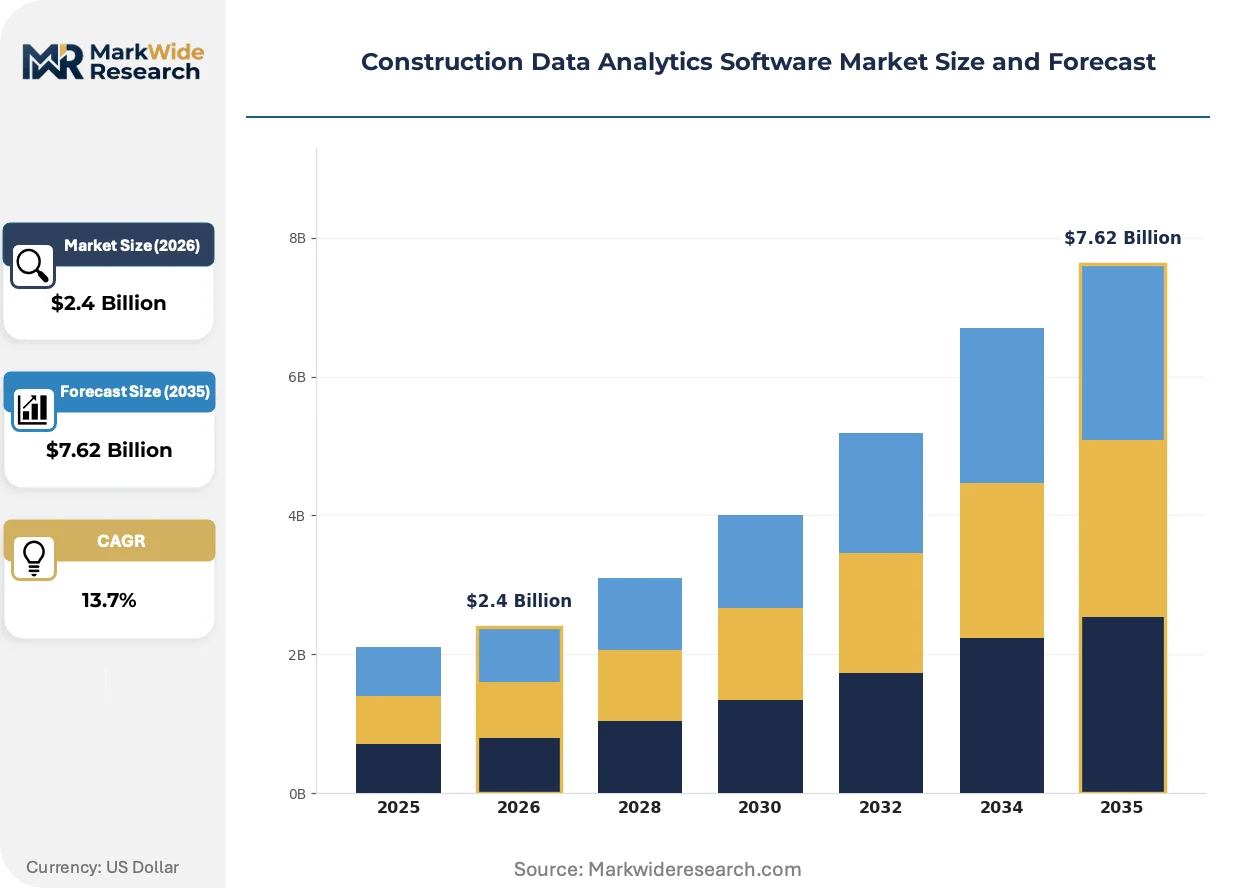
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premises, Hybrid, SaaS Solution Offering: Project Management Analytics, Cost Estimation Tools, Risk Analysis Software, Safety Management Systems Application: Building Information Modeling, Site Monitoring, Resource Allocation, Quality Control End User: Contractors, Real Estate Developers, Engineering Firms, Construction Consultants |
| Companies Covered | Procore Technologies, Autodesk, CMiC, RIB Software, ALICE Technologies, Vitruvi Software, Trimble, Bentley Systems, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Data Analytics Software Market Trends and Innovations
Artificial intelligence architectures are consolidating previously separate point solutions into unified platforms, compressing vendor competitive sets and redefining buyer evaluation criteria around model accuracy rather than feature breadth.
Generative design algorithms paired with construction scheduling engines are consolidating cost estimation and sequencing optimization into single-workflow platforms. Mid-market contractors in the United States are adopting these tools fastest, driven by thin bid margins that punish manual estimation errors. The technology is consolidating what were previously three separate software procurement decisions into integrated subscriptions.
The European Union's Construction Products Regulation and impending Digital Product Passport requirements are mandating embedded carbon tracking across material supply chains. Analytics platforms must now ingest Environmental Product Declaration datasets and generate automated compliance reporting. Heavy civil contractors bidding on EU-funded infrastructure are restructuring procurement teams to prioritize vendors with pre-certified sustainability modules.
Subscription pricing for field analytics is displacing perpetual license models among specialty trade contractors with project-based cash flows. Equipment rental marketplaces and material distributors are embedding white-labeled analytics into customer portals, capturing procurement influence without direct software sales. This channel shift is most visible in the United States, where distributor consolidation has created national platforms with captive contractor relationships.
Construction Data Analytics Software Market Segmentation
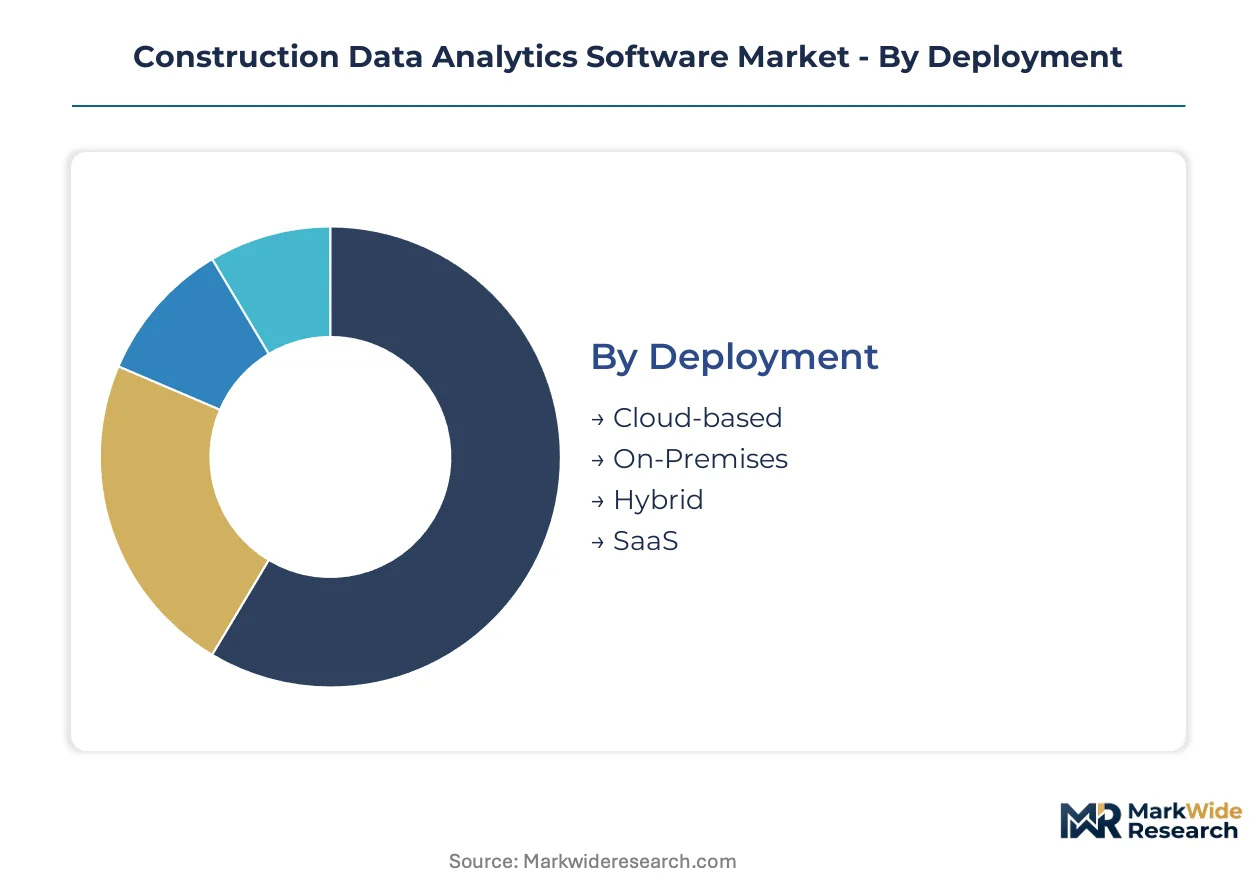
Construction data analytics software segments reflect divergent integration architectures. Deployment mode determines infrastructure ownership. Solution depth shapes procurement authority. Application focus dictates sensor integration requirements. End-user type calibrates workflow complexity.
Deployment:
Cloud-native platforms embed analytics within contractor ERP systems. On-premises installations retain standalone operation for sovereign data environments.
- Cloud-based:Multi-tenant architectures deliver real-time dashboards through browser interfaces. United States federal infrastructure contractors prioritize these platforms for rapid deployment across dispersed project sites. Cloud migration mandates from public agencies compress procurement cycles for this segment.
- On-Premises:Dedicated server installations maintain physical data control. Defense and critical infrastructure operators in Saudi Arabia mandate this architecture for classified project data. Sovereignty requirements fragment vendor R&D investment toward hardened security modules.
- Hybrid:Split architectures process sensitive data locally while syncing analytics to cloud repositories. Mid-market contractors in Germany adopt this model to satisfy GDPR constraints while accessing AI-powered forecasting tools.
- SaaS:Subscription licensing eliminates capital expenditure for specialty trade contractors with project-based cash flows. Equipment rental marketplaces in the United States embed white-labeled SaaS analytics into customer portals.
Cloud-based deployments lead volumes today; SaaS is gaining share fastest.
Solution Offering:
Standalone point solutions compete against unified platforms consolidating multiple functions. Procurement authority varies by organizational maturity and project scale.
- Project Management Analytics:Schedule variance tracking and resource leveling algorithms integrate with Gantt-based planning tools. Heavy civil contractors in Australia deploy these systems on equipment-intensive megaprojects to optimize fleet utilization. The segment commands the largest installed base through legacy ERP integration requirements.
- Cost Estimation Tools:Generative algorithms automate quantity takeoff and unit price forecasting. Mid-market contractors in the United States adopt these fastest where thin bid margins punish manual estimation errors. Integration with scheduling engines consolidates previously separate procurement decisions.
- Risk Analysis Software:Probabilistic cost forecasting models satisfy insurer and surety underwriter requirements. Lloyd's of London mandates these capabilities for bond eligibility on large-scale developments.
- Safety Management Systems:Digitized incident workflows with real-time dashboarding support OSHA recordkeeping compliance. Federal contractors in the United States prioritize these tools for favorable Experience Modification Rate scores.
Project Management Analytics leads volumes today; Risk Analysis Software is expanding most quickly.
Application:
Application segments align with construction phase entry points and data source diversity. BIM integration demands structured data handover capabilities. Field operations require sensor network compatibility.
- Building Information Modeling:Clash detection and design-to-construction workflow continuity anchor vendor positioning. United Kingdom public procurement rules mandate BIM Level 2 compliance, compelling structured data handover automation. Autodesk leverages deep interoperability to defend this segment.
- Site Monitoring:IoT sensor streams from equipment telematics and environmental monitors feed real-time dashboards. Predictive maintenance algorithms reduce idle-time penalties on fixed-price contracts in United States infrastructure projects.
- Resource Allocation:Labor scheduling optimization matches craft availability to activity sequences. Procore Technologies extends cloud-native architecture into field analytics for mid-market deployment speed.
- Quality Control:Automated inspection workflows and non-conformance tracking integrate with digital twin repositories. Bentley Systems specializes in infrastructure-scale precision for transportation and water utility asset managers.
Building Information Modeling leads volumes today; Site Monitoring shows the steepest expansion trajectory.
End User:
End-user segments diverge by procurement sophistication and internal IT capability. Contractors prioritize field deployment speed. Developers emphasize portfolio-level benchmarking.
- Contractors:Field-first analytics demand mobile-optimized interfaces and offline synchronization. Heavy civil specialists in the United States and Australia deploy predictive platforms on megaprojects with concentrated vendor procurement pools.
- Real Estate Developers:Portfolio analytics aggregate project outcomes across multiple developments for investor reporting. Private data center construction in the United States creates concentrated demand for capital efficiency visualization.
- Engineering Firms:Design-stage analytics integrate geospatial LiDAR with structural performance modeling. Digital twin convergence opens premium positioning for transportation infrastructure specialists.
- Construction Consultants:Independent advisory services require multi-platform interoperability to serve diverse client technology stacks. Fragmented compliance templates across California, New York, and Illinois force configurable module maintenance.
Contractors lead volumes today; Real Estate Developers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure spending and private data center construction in the United States concentrate procurement pools for analytics vendors. Cloud migration mandates from public agencies and BIM compliance requirements in Europe accelerate replacement cycles across major economies.
United States
Federal infrastructure grants and private data center construction drive concentrated demand for predictive analytics platforms. OSHA recordkeeping modernization and Federal Acquisition Regulation mandates shape product roadmaps for safety incident reporting. Heavy civil contractors in Texas and California deploy equipment optimization algorithms on megaprojects with fixed-price contracts.
United Kingdom
BIM Level 2 compliance requirements in public procurement compel structured data handover automation. The Construction Products Regulation and impending Digital Product Passport requirements mandate embedded carbon tracking across material supply chains. London-based infrastructure specialists prioritize vendors with pre-certified sustainability modules for EU-funded developments.
Germany
GDPR constraints and data sovereignty requirements favor hybrid deployment architectures among mid-market contractors. The country's national construction regulator enforces rigorous audit trail retention standards for public works. Engineering clusters in Bavaria and North Rhine-Westphalia integrate geospatial LiDAR with digital twin repositories for transportation infrastructure.
Australia
Equipment-intensive developments in mining and heavy civil sectors deploy predictive maintenance algorithms to optimize fleet utilization. State-level procurement rules mandate standardized safety reporting for federal contractors. Sydney and Melbourne contractors concentrate vendor selection around cloud-native platforms with rapid deployment capabilities for dispersed project sites.
India
National highway and urban metro expansions lack indigenous analytics vendors, creating first-mover positioning opportunities. The Bureau of Indian Standards and central public works departments embed digital delivery standards into infrastructure grant eligibility. Maharashtra and Gujarat construction corridors attract cloud-native platforms with localized compliance modules for emerging procurement pools.
Construction Data Analytics Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native architectures and vertical-specific modules. The vendor base stratifies across three tiers: design-originated suites with deep BIM interoperability, cloud-native field platforms optimized for deployment velocity, and infrastructure-scale specialists commanding premium positioning for geospatial precision. Strategic moves concentrate on API-first rearchitectures and sustainability module pre-certification to satisfy emerging regulatory linkages.
Among design-originated incumbents, Autodesk anchors the BIM-centric tier through workflow continuity from design to construction. Cloud-native specialists include Procore Technologies, which exemplifies field-first deployment speed for mid-market contractors. Bentley Systems occupies the infrastructure-scale tier, representing heavy civil and transportation segments where digital twin integration commands premium vendor selection.
| Leading Market Players |
|---|
| Procore Technologies |
| Autodesk |
| CMiC |
| RIB Software |
| ALICE Technologies |
| Vitruvi Software |
| Trimble |
| Bentley Systems |
| Oracle |
| Others |
Pricing and Supply Chain Analysis
The European Union's Digital Product Passport requirements and embedded carbon tracking mandates gate qualified supply for contractors bidding on EU-funded infrastructure, while simultaneously creating premium-tier pricing access for vendors with pre-certified sustainability modules. Heavy civil contractors now face procurement restructuring costs that compress margins for non-compliant suppliers and concentrate pricing power among analytics platforms with automated Environmental Product Declaration ingestion capabilities.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and AI compute resources shapes subscription pricing structures across deployment tiers. SaaS licensing dominates new customer acquisition, with pricing stratifying across enterprise, mid-market, and specialty contractor tiers based on integration complexity and sensor network scale. Cost compression in the mid-market segment is intensifying because thin bid margins punish software procurement overhead. Specialty trade contractors with project-based cash flows exhibit highest price sensitivity, while federal infrastructure contractors with multi-year deployment mandates show lowest sensitivity to annual subscription escalations.
Supply Chain Analysis
Freight cost volatility and data center energy pricing in the United States, Germany, and India influence cloud-native platform operating margins and regional pricing differentials. Software development draws from specialized talent pools concentrated in metropolitan technology hubs, with API middleware development resting on third-party integration specialist networks. Single-source vulnerability exists for geospatial LiDAR hardware and IoT sensor components sourced from concentrated manufacturing bases. Distribution runs through direct enterprise sales teams for large contractors and embedded white-label partnerships with equipment rental marketplaces for specialty trade access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where federal infrastructure grant conditions and insurer-mandated risk modeling are shifting procurement authority toward premium-specification analytics platforms with certified compliance modules.
For Market Incumbents: Lock in API-first architecture investments to defend against cloud-native entrants exploiting interoperability gaps in legacy ERP integrations. Prioritize sustainability module pre-certification to capture EU-funded infrastructure procurement pools where Digital Product Passport compliance gates vendor eligibility. Channel control through distributor white-label partnerships protects against direct sales cost escalation in fragmented mid-market segments. For New Entrants and Emerging Players: Specialty trade contractors with project-based cash flows represent the most penetrable buyer archetype currently underserved by enterprise-focused deployment models. Target India infrastructure corridors where indigenous analytics vendors are absent and cloud-native platforms with localized compliance modules can establish first-mover positioning. Pursue embedded partnership routes through equipment rental marketplaces to bypass direct customer acquisition costs. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific AI-native platforms because fragmented compliance templates across California, New York, and Illinois create acquisition opportunities for configurable module specialists. Long-term viability centers on vendors capturing infrastructure-scale digital twin integration premiums in transportation and water utility segments. Monitor federal infrastructure grant condition releases as the inflection indicator for which analytics capabilities become table stakes versus differentiated procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Re-architecture | Enables seamless BIM repository and IoT sensor network interoperability demanded by public agency cloud migration mandates. |
| Sustainability Module Pre-certification | Satisfies EU Construction Products Regulation and Digital Product Passport requirements for carbon tracking compliance. |
| Geographic Expansion into India | Captures first-mover positioning in national highway and urban metro expansions lacking indigenous analytics vendors. |
| Strategic Partnership with Equipment Rental Marketplaces | Embeds white-labeled analytics into customer portals for specialty trade contractor access without direct sales overhead. |
| Acquisition of Risk Analytics Specialist | Consolidates probabilistic cost forecasting capabilities required by Lloyd's of London for large-scale development bond eligibility. |
Research Methodology
Direct dialogue with construction technology executives, federal infrastructure procurement officers, BIM integration specialists, and equipment fleet managers grounded the qualitative foundation, supplemented by secondary validation through SEC filings from publicly traded software vendors, OSHA regulatory guidance documents, EU Construction Products Regulation technical standards, and federal infrastructure grant condition releases. Bottom-up triangulation across deployment mode, solution offering, application focus, and end-user type segments converged with top-down market sizing from public agency IT expenditure disclosures and contractor software procurement surveys.
Segment-level value outputs across cloud-based, on-premises, hybrid, and SaaS deployment architectures were modeled against organization size tiers, vertical specialization patterns, and regional adoption trajectories throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycle compression rates and forward-projected compliance mandate implementation timelines, with specific inputs including BIM Level 2 adoption velocity in United Kingdom public procurement and OSHA recordkeeping modernization compliance deadlines for federal contractors.
Underlying measurement precision varies by segment; cloud-based deployment and project management analytics carry tighter precision due to transparent vendor disclosure practices, while hybrid architectures and construction consultant end-user categories exhibit wider confidence intervals. Forecasts reflect documented assumptions regarding regulatory implementation schedules and infrastructure spending authorization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
North America HR Analytics Market
Analytics
Israel ICT Market
Analytics
UK Geospatial Analytics Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Data Discovery Market
Analytics
Network Analytics Services Market
Analytics
Global Enterprise Performance Management Market
Analytics
Global Systems of Insight Market
Analytics
Embedded Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Sweden ICT Market
Analytics
Canada Contact Center Analytics Market
Analytics
Global Data Prep Market
Analytics
Connected Device Analytics Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
United Kingdom Business Intelligence Market