
 United Kingdom Business Intelligence Market | 2026-2036
United Kingdom Business Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Business Intelligence Market Analytics
England is reshaping the United Kingdom Business Intelligence Market through concentrated cloud infrastructure investment and fintech cluster density. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise-grade analytics deployments across British banking groups. SAS Institute differentiates through advanced statistical computing modules that sustain loyalty among pharmaceutical and government research buyers. ThoughtSpot competes via natural language query interfaces that reduce technical barriers for mid-market procurement teams.
Business intelligence encompasses software platforms and services that aggregate, process, and visualize structured and unstructured data to support operational and strategic decision-making, typically integrating SQL-based querying, extract-transform-load pipelines, and in-memory processing architectures with sub-second response thresholds. The primary commercial purpose centers on converting raw enterprise data into actionable intelligence for revenue optimization, risk mitigation, and supply chain coordination. Self-service BI and cloud BI command the largest addressable bases as British enterprises retire legacy on-premises warehouses, while embedded BI represents the fastest expansion vector as software vendors integrate native analytics into vertical applications. Financial services and healthcare verticals concentrate margin pools due to stringent compliance requirements that elevate pricing for audit-ready reporting modules.
The UK Information Commissioner's Office enforces GDPR-aligned data governance standards that compel BI vendors to embed granular consent management and lineage tracking into platform architectures. BSI standards for information security management further condition procurement eligibility for public sector contracts. The Financial Conduct Authority's operational resilience directives mandate real-time dashboard availability for systemic financial institutions. Stakeholders must monitor evolving UK AI regulation and its intersection with automated analytics outputs to anticipate compliance-driven product redesign cycles.
Market Dynamics
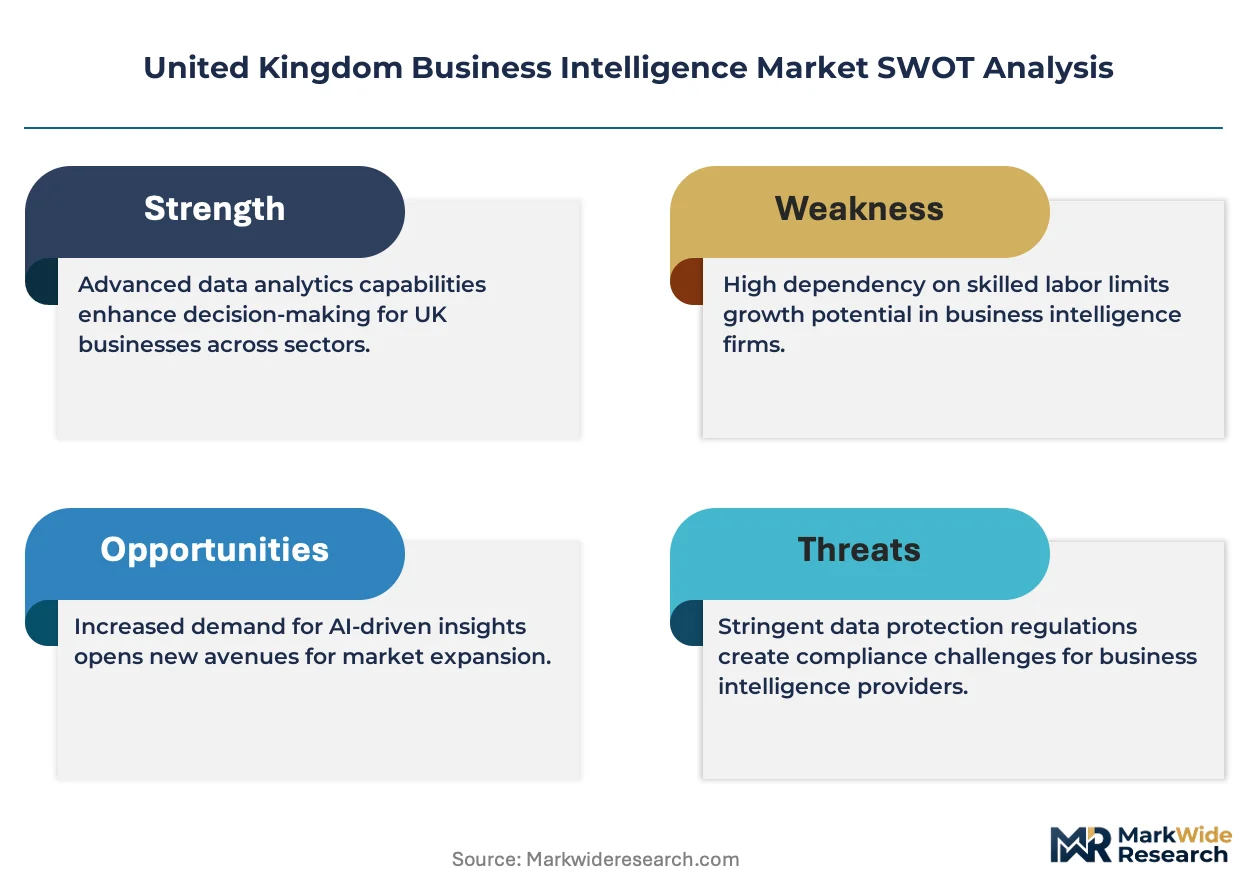
The UK Business Intelligence Market pivots on the forced retirement of on-premises data warehouses as British enterprises face GDPR-mandated data sovereignty requirements that cloud-native architectures resolve more cleanly than legacy stacks.
Growth Catalysts
- Self-service analytics platforms:Retail chains deploy these tools to bypass IT bottlenecks and accelerate decision velocity across store operations and inventory management.
- FCA operational resilience directives:Systemic financial institutions must maintain real-time dashboard availability, creating procurement mandates for high-availability BI infrastructure.
- Healthcare data integration:NHS trusts consolidate patient records and operational metrics, driving demand for HIPAA-aligned analytics modules with audit-ready lineage tracking.
Market Restraints
- Specialized talent scarcity:Data engineering and governance expertise concentrates in London's financial corridor, inflating implementation costs for regional deployments.
- Legacy system entrenchment:Established on-premises warehouses at major British banks resist full cloud migration due to sunk capital and internal compliance review cycles.
- GDPR enforcement uncertainty:The UK Information Commissioner's Office maintains ambiguous guidance on cross-border data transfers, chilling multi-region analytics investments.
Strategic Opportunities
- Embedded analytics in vertical software:Independent software vendors across legaltech and proptech integrate native BI to differentiate subscription offerings.
- Natural language query interfaces:Mid-market procurement teams adopt conversational analytics to reduce dependency on SQL-trained analysts.
- Northern England tech corridors:Manchester and Leeds enterprise clusters show underpenetrated demand relative to London saturation, offering first-mover expansion potential.
Industry Challenges
- Multi-cloud governance complexity:Enterprises operating across Azure, AWS, and GCP environments struggle to maintain unified data lineage and access controls.
- Skills pipeline gaps:British universities produce insufficient graduates with combined statistical computing and cloud architecture competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Business Intelligence Market |
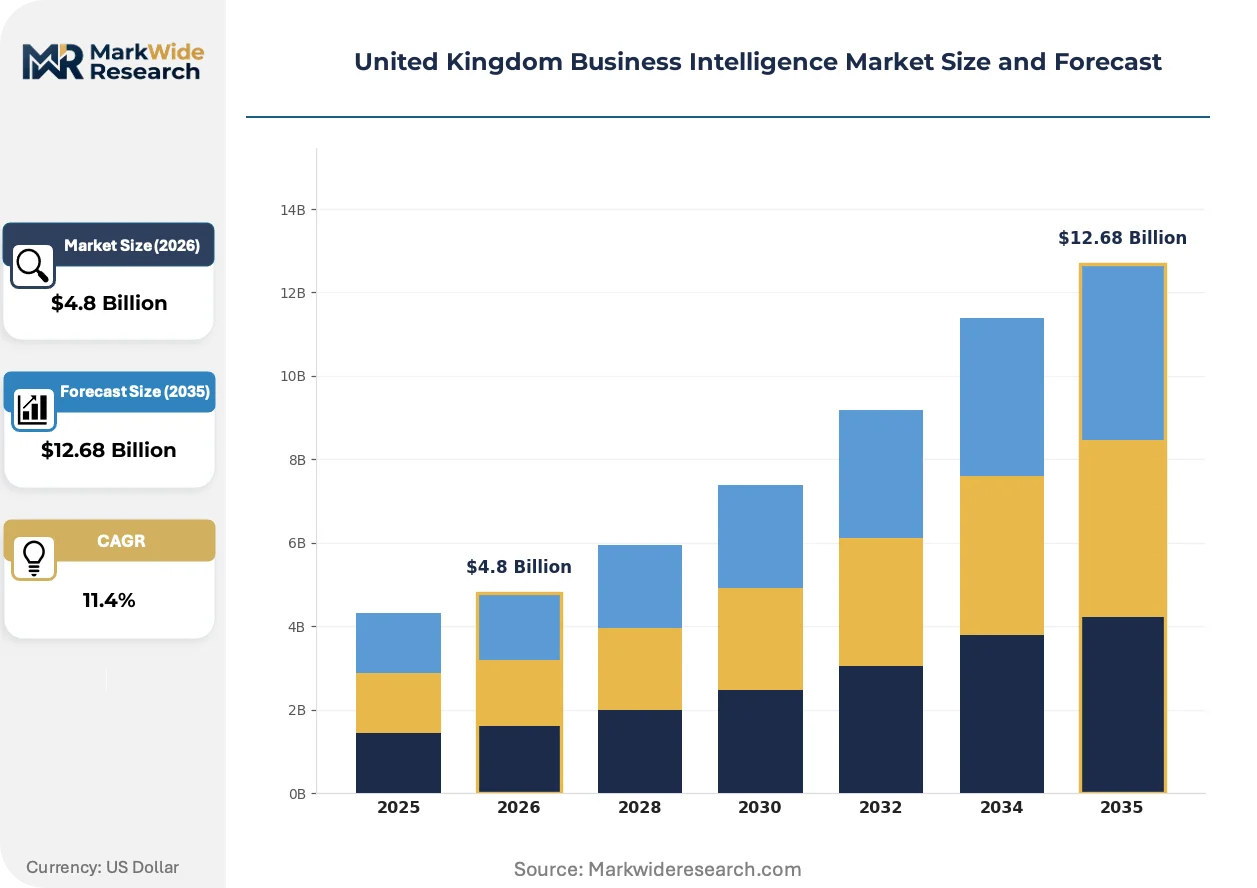
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Self-Service BI, Embedded BI, Cloud BI, On-Premises BI Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises User Type: Small Enterprises, Medium Enterprises, Large Enterprises, Government Agencies Industry Vertical: Healthcare, Retail, Manufacturing, Financial Services |
| Companies Covered | IBM Corporation, Qlik, Microsoft Corporation, SAS Institute, Tableau Software, SAP SE, Oracle Corporation, ThoughtSpot, Salesforce Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Business Intelligence Market Evolving Landscape
Automation is compressing traditional BI implementation timelines while regulatory pressure and shifting buyer expectations reshape platform requirements across British enterprises.
Natural language processing is collapsing the technical barrier between business users and data exploration. Mid-market procurement teams now query datasets through conversational interfaces rather than submitting tickets to centralized analytics functions. This shift is collapsing the traditional IT bottleneck that delayed insight generation by weeks.
The UK Information Commissioner's Office enforcement posture on GDPR-aligned consent management compels vendors to embed granular tracking into platform architectures. BI deployments now require automated lineage documentation as a procurement prerequisite. Financial services and healthcare verticals face the steepest compliance burden, driving premium pricing for audit-ready modules.
Subscription-based consumption models displace perpetual licensing across British enterprise procurement. Finance and operations teams prefer operational expenditure treatment for analytics infrastructure, aligning vendor revenue to actual usage volumes. This pattern concentrates among scale-ups and mid-market firms in London's fintech and insurtech clusters.
United Kingdom Business Intelligence Market Segmentation
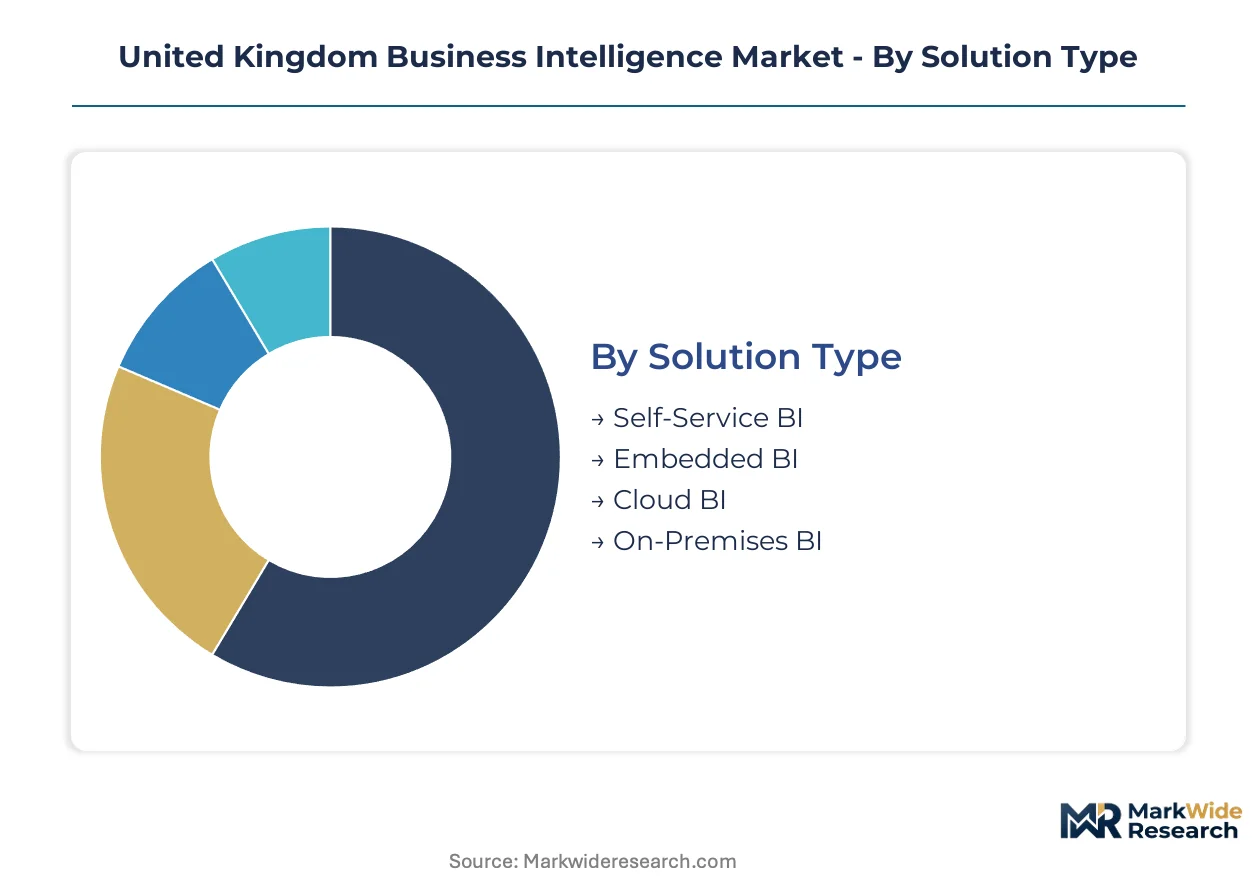
Segmentation reveals how procurement patterns diverge across British enterprises. Cloud migration velocity, compliance burden, and technical maturity create distinct buyer clusters with incompatible platform requirements.
Solution Type:
Replacement cycles vary dramatically — self-service platforms refresh every 18-24 months while on-premises installations persist for 7-10 years.
- Self-Service BI:Browser-based interfaces enable business users to build dashboards without SQL expertise. Retail chains across England deploy these tools to accelerate inventory decisions and bypass centralized IT queues.
- Cloud BI:Multi-tenant architectures with auto-scaling compute pools support variable query loads. London's financial services corridor drives concentration here due to FCA mandates for operational resilience and real-time availability.
- Embedded BI:Native analytics modules integrated into vertical applications. Legaltech vendors in Manchester embed contract analytics to differentiate subscription tiers.
- On-Premises BI:Legacy warehouse architectures retained by major British banks with sunk capital investments and internal compliance review cycles.
Cloud BI anchors the volume base while self-service platforms gain share at the steepest rate.
Deployment Model:
Cost structures stratify sharply — public cloud minimizes upfront commitment while hybrid deployments demand the highest professional services spend.
- Public Cloud:Shared infrastructure with consumption-based billing. Scale-ups in London's fintech clusters prefer operational expenditure treatment for analytics infrastructure.
- Hybrid Cloud:Sensitive data remains on-premises while compute-intensive processing shifts to cloud. NHS trusts adopt this model to maintain patient record sovereignty while leveraging elastic analytics capacity.
- Private Cloud:Single-tenant environments dedicated to one organization. Pharmaceutical manufacturers with GxP validation requirements select this path for audit trail control.
- On-Premises:Fully captive hardware and software stacks. Established British banks with legacy entrenchment resist full migration due to sunk capital.
Public cloud captures the widest adoption base while hybrid deployments command the highest average contract values.
User Type:
Procurement sophistication scales with organizational complexity — government agencies run the longest evaluation cycles while small enterprises purchase through self-serve channels.
- Large Enterprises:Centralized procurement functions with dedicated analytics centers of excellence. British banking groups negotiate enterprise-wide Azure contracts that bundle BI infrastructure.
- Medium Enterprises:Finance and operations teams with limited dedicated IT support. Mid-market manufacturers in the Midlands adopt natural language query interfaces to reduce dependency on SQL-trained analysts.
- Government Agencies:Public sector procurement governed by BSI standards for information security management. NHS trusts consolidate patient records and operational metrics under strict audit requirements.
- Small Enterprises:Founder-led decisions with minimal governance overhead. Proptech startups in Leeds deploy lightweight embedded analytics within vertical SaaS tools.
Large enterprises anchor contract value while medium enterprises expand most quickly as self-service tools collapse technical barriers.
Industry Vertical:
Compliance intensity creates pricing power — financial services and healthcare tolerate premium modules for audit-ready lineage tracking.
- Financial Services:Real-time risk dashboards and regulatory reporting pipelines. Systemic institutions face FCA operational resilience directives mandating high-availability infrastructure.
- Healthcare:Patient record integration with HIPAA-aligned governance modules. NHS trusts drive demand for automated lineage documentation as procurement prerequisite.
- Retail:Store-level inventory optimization and demand forecasting. Chains across England accelerate adoption to bypass IT bottlenecks and accelerate decision velocity.
- Manufacturing:Supply chain coordination and predictive maintenance analytics. Midlands industrial clusters consolidate operational metrics from legacy shop-floor systems.
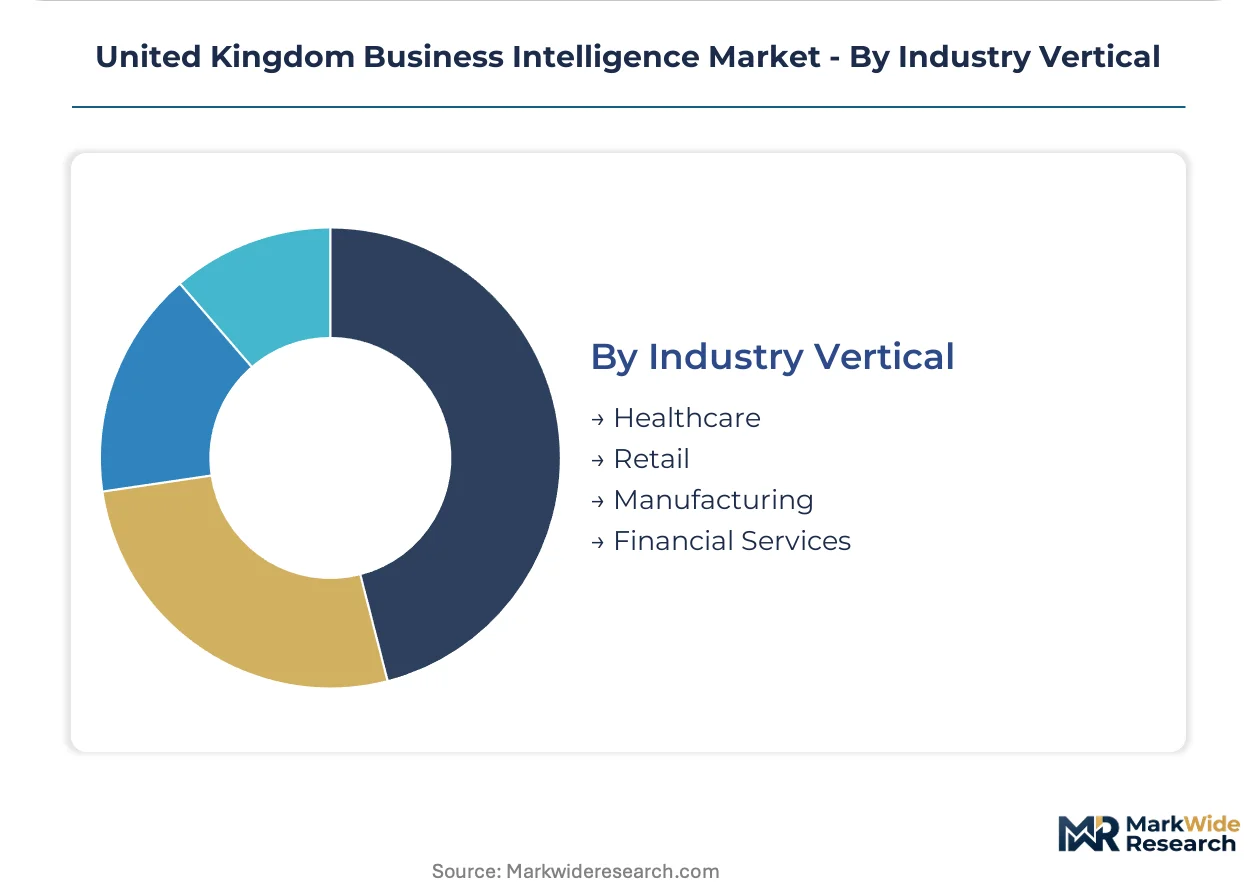
Financial services anchors margin pools while healthcare climbs the fastest as NHS digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London Internet Exchange anchors United Kingdom data traffic, underwriting the country's dominance in European cloud infrastructure and enterprise analytics demand.
London and the Southeast
Financial services institutions drive concentrated BI procurement for real-time risk dashboards and regulatory reporting pipelines. The Financial Conduct Authority's operational resilience directives mandate high-availability infrastructure for systemic banks. The Square Mile and Canary Wharf clusters host Azure-anchored analytics deployments across major banking groups.
Midlands
Manufacturing enterprises consolidate operational metrics from legacy shop-floor systems into unified analytics platforms. NHS trusts in Birmingham and Nottingham adopt hybrid cloud architectures to maintain patient record sovereignty while leveraging elastic compute capacity. The region's automotive and aerospace supply chains coordinate predictive maintenance analytics through embedded BI modules.
North England
Manchester and Leeds enterprise clusters show underpenetrated demand relative to London saturation, offering first-mover expansion potential for self-service platform vendors. The UK government's Northern Powerhouse investment program channels infrastructure funding toward tech corridor development. Legaltech vendors in Manchester embed contract analytics to differentiate subscription tiers.
Scotland
Edinburgh's fintech cluster and Glasgow's public sector institutions generate steady procurement for cloud-native analytics with GDPR-aligned governance. The Scottish Government's digital strategy emphasizes data-driven policy delivery, creating demand for audit-ready reporting modules. Aberdeen's energy sector deploys supply chain coordination tools amid North Sea transition investments.
Wales
Cardiff's emerging insurtech sector and Swansea's university research partnerships stimulate mid-market BI adoption. Welsh Government innovation funding supports data science skills development to address regional talent scarcity. The region's manufacturing base in South Wales integrates lightweight embedded analytics for operational visibility.
United Kingdom Business Intelligence Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying statistical engines and visualization modules. The vendor base stratifies between hyperscale cloud providers with bundled analytics stacks and independent software vendors with vertical specialization. Three archetypes dominate: infrastructure-anchored platforms, statistical computing specialists, and conversational interface disruptors. Competitive moves concentrate on strategic partnerships with system integrators and geographic expansion into underpenetrated regional clusters.
Within the infrastructure-anchored tier, Microsoft Corporation and IBM Corporation exemplify platform bundling strategies that embed analytics within broader cloud service contracts. SAS Institute occupies a distinctive position among statistical computing specialists, sustaining loyalty in pharmaceutical and government research segments through advanced analytical modules. ThoughtSpot represents the conversational interface archetype, reducing technical barriers for mid-market procurement teams through natural language query capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| Qlik |
| Microsoft Corporation |
| SAS Institute |
| Tableau Software |
| SAP SE |
| Oracle Corporation |
| ThoughtSpot |
| Salesforce Inc. |
| Others |
Value Network & Pricing Analysis
GDPR-mandated data sovereignty requirements determine both pricing tier spreads and supply chain shape across the United Kingdom Business Intelligence Market, as British enterprises force-retire legacy on-premises warehouses and cloud-native architectures command premium positioning for compliance-ready deployments.
Pricing Analysis
Volume-discount tiering structures dominate procurement across British enterprises, with subscription-based SaaS models displacing perpetual licensing. Pricing stratifies across premium, standard, and economy tiers based on compliance certification level and customization depth for vertical applications. Cost compression in the standard tier is intensifying because hyperscale cloud providers bundle analytics infrastructure within broader enterprise contracts. Mid-market manufacturers in the Midlands exhibit highest price sensitivity, while systemic financial institutions in London tolerate premium modules for FCA-aligned operational resilience.
Supply Chain Analysis
Upstream feedstock for BI platforms draws from cloud infrastructure provisioning concentrated in Ireland, the Netherlands, and the United Kingdom itself, with hyperscale data centers anchoring compute capacity delivery. Core dependencies span SQL query engines, in-memory processing architectures, and visualization rendering libraries. Single-source vulnerability persists around specialized statistical computing modules from established vendors. Distribution runs through direct enterprise sales teams and systems integrator partnerships, with channel partners capturing mid-market procurement in regional tech corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Business Intelligence Market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning, as GDPR alignment and FCA operational resilience mandates embed switching costs that resist vendor displacement.
For Market Incumbents: Pre-empt conversational interface disruption by acquiring natural language query specialists before mid-market procurement teams complete platform selections. Fortify Azure-anchored deployments across British banking groups through deeper integration with compliance automation modules. Prioritize certification investment for BSI standards to maintain public sector procurement eligibility as NHS digitization accelerates. For New Entrants and Emerging Players: Northern England tech corridors offer underpenetrated demand relative to London saturation, with Manchester and Leeds enterprise clusters showing first-mover expansion potential for self-service platform vendors. Target legaltech and proptech verticals with embedded analytics modules that differentiate subscription tiers. Pursue channel partnerships with regional systems integrators to bypass direct competition against hyperscale bundled offerings. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with compliance-ready lineage tracking capabilities over horizontal generalists. Five-to-ten year viability hinges on automated governance feature depth rather than visualization sophistication alone. Acquisition targets should demonstrate NHS trust or FCA-regulated financial services referenceability. Monitor UK AI regulation evolution as the inflection indicator for platform redesign cycles and compliance-driven procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure ecosystem bundling anchors enterprise-grade analytics deployments across British banking groups. |
| Acquisition of Specialist Firm | Natural language query capabilities reduce technical barriers for mid-market procurement teams in underpenetrated regions. |
| Strategic Partnership | Systems integrator alliances channel cloud-native deployments into NHS trusts facing HIPAA-aligned governance requirements. |
| Geographic Expansion | Manchester and Leeds enterprise clusters offer first-mover positioning before London saturation extends northward. |
| Product Launch | Embedded analytics modules differentiate legaltech and proptech subscription tiers in competitive vertical software markets. |
Research Methodology
A spread of perspectives from CTOs at British banking groups, IT procurement officers in NHS trusts, platform engineers at cloud service providers, and channel partners in regional tech corridors converged on the working assumptions that shape this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed vendors, hyperscaler capex disclosures, and BSI standards documentation. Bottom-up sizing of deployment instances triangulated against top-down market value estimates across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning deployment model, organization size, vertical industry, and integration complexity. CAGRs were derived from elasticity modeling of replacement cycles and cloud migration velocity. Industry-specific inputs included FCA operational resilience directive compliance timelines and NHS digitization program procurement patterns throughout the projection horizon.
Practitioners should monitor UK AI regulation evolution and Information Commissioner's Office enforcement posture on cross-border data transfers for early signals of platform redesign requirements. Forecasts reflect assumptions about cloud migration velocity and self-service analytics adoption curves that external shocks could revise. Cross-checking against hyperscaler earnings call commentary on British enterprise consumption trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Pandemic Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Italy Geospatial Analytics Market
Analytics
Dark Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Emotion Analytics Market
Analytics
Israel ICT Market
Analytics
Web Analytics Market
Analytics
Europe Crowd Analytics Market
Analytics
Big Data Analytics in Retail Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Contact Center Analytics Market