
 Canada Contact Center Analytics Market | 2026-2036
Canada Contact Center Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Contact Center Analytics Market Insights
Post-call analytics revenue is reshaping margin pools away from traditional quality assurance staffing toward automated sentiment scoring platforms. NICE Ltd leverages its AI-driven workforce optimization suite to dominate enterprise deployments across Canadian financial institutions. Genesys anchors its position through cloud-native routing infrastructure that integrates predictive analytics into omnichannel workflows. Five9 specializes in rapid-deployment speech analytics for mid-market BPO operators seeking compliance automation without heavy capital expenditure.
Contact center analytics encompasses the collection, processing, and interpretation of voice, text, and behavioral data from customer service interactions, typically employing natural language processing engines that process audio at 8-16 kHz sampling rates and real-time streaming architectures with sub-200-millisecond latency. The technology serves commercial purposes by converting unstructured interaction data into operational intelligence for agent coaching, regulatory compliance, and customer churn prediction. Speech analytics occupies the mature core of the product mix, while predictive analytics segments are capturing expanding margin pools as enterprises deploy next-best-action algorithms during live customer conversations. Cloud-based deployment configurations are displacing on-premises infrastructure fastest among mid-tier enterprises, though hybrid architectures retain strength in sectors with stringent data residency requirements.
Health Canada and the Office of the Privacy Commissioner of Canada enforce data handling standards that shape encryption requirements and cross-border data flow restrictions for customer interaction recordings. PIPEDA compliance obligations compel vendors to embed consent management and automated redaction capabilities directly into analytics pipelines. Stakeholders must monitor evolving provincial privacy legislation in Quebec and British Columbia that may impose stricter localization mandates than federal baselines.
Market Dynamics
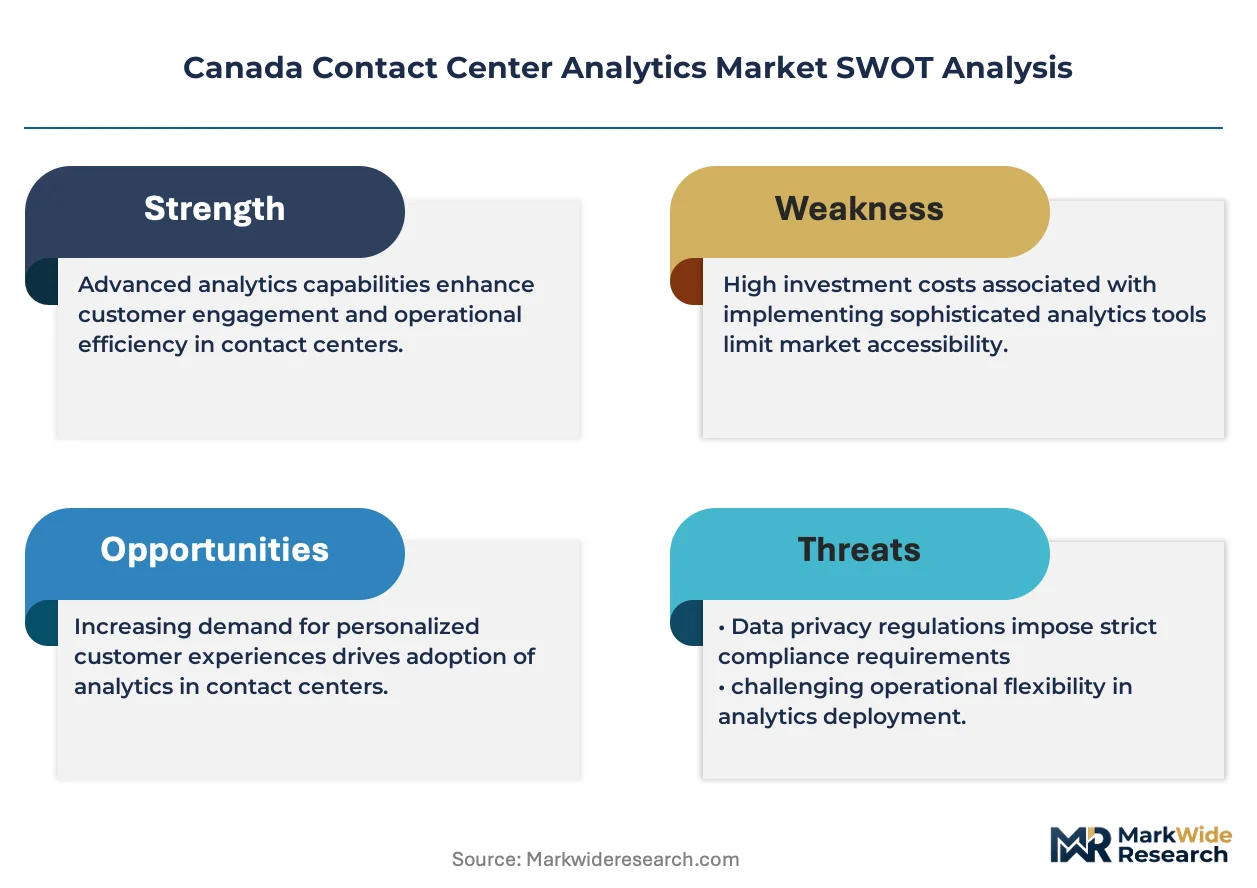
Federal cloud migration mandates under PIPEDA are forcing legacy on-premises contact center infrastructure toward hybrid architectures, compressing deployment timelines and reshaping vendor procurement criteria across Canadian financial services.
Growth Catalysts
- PIPEDA Compliance Automation:Privacy Commissioner enforcement of consent management and automated redaction capabilities is accelerating replacement of legacy recording systems with analytics-integrated platforms.
- Real-Time Speech Analytics:Canadian banks and insurance providers are deploying sub-200-millisecond latency streaming architectures to enable live agent coaching and churn intervention during active customer conversations.
- Toronto-Waterloo Corridor Consolidation:Enterprise contact center consolidation in Ontario's technology corridor is concentrating demand for cloud-native workforce optimization suites among mid-market BPO operators.
Market Restraints
- Data Residency Infrastructure Costs:Health Canada encryption requirements and cross-border data flow restrictions compel redundant domestic cloud capacity investment, elevating total cost of ownership versus pure SaaS alternatives.
- Quebec Provincial Localization:Evolving provincial privacy legislation in Quebec imposes stricter data localization mandates than federal PIPEDA baselines, fragmenting national deployment architectures.
- Legacy System Interoperability:Hybrid cloud configurations face integration friction with decades-old automatic call distribution hardware still operational at major Canadian financial institutions.
Strategic Opportunities
- British Columbia Provincial Mandates:Anticipated privacy legislation expansion in British Columbia creates first-mover positioning for vendors pre-integrating enhanced localization and consent workflows.
- Predictive-Analytics Convergence:Integration of natural language processing engines with next-best-action algorithms during live conversations opens premium pricing for real-time decisioning platforms.
- Mid-Market BPO Channel:Rapid-deployment speech analytics without heavy capital expenditure requirements addresses compliance automation demand among underserved mid-tier outsourcing operators.
Industry Challenges
- Specialized NLP Engineering Talent:Scarce expertise in 8-16 kHz audio sampling optimization and real-time streaming architecture development constrains vendor scaling and implementation velocity.
- Hybrid Integration Complexity:Enterprises struggle to synchronize on-premises quality assurance workflows with cloud-based sentiment scoring platforms without disrupting existing agent performance metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Contact Center Analytics Market |
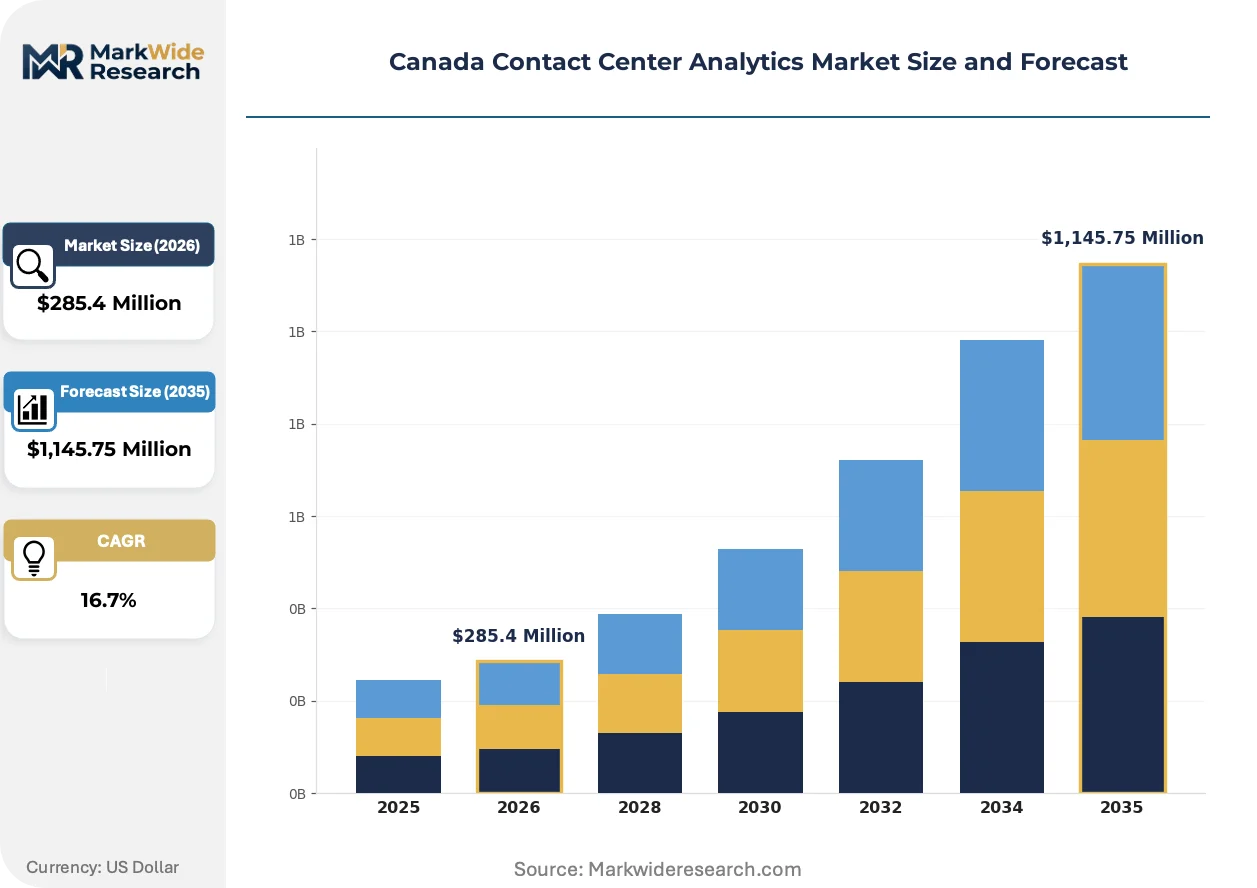
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,145.75 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speech Analytics, Predictive Analytics, Text Analytics, Workforce Optimization Deployment: On-premises, Cloud-based, Hybrid, Private Cloud Use Case: Customer Experience Management, Quality Assurance, Compliance Monitoring, Performance Management End User: Telecommunications, BFSI, Retail, Healthcare |
| Companies Covered | NICE Ltd, Genesys, Cisco Systems, Five9, 8x8 Inc, Genpact, Enghouse Systems, CallMiner, Verint Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Contact Center Analytics Market Trends and Innovations
Real-time processing architectures and privacy-centric compliance automation are compressing competitive differentiation toward sub-second latency performance and embedded regulatory adherence.
Speech analytics infrastructure is hybridizing across deployment models. Natural language processing engines now operate across edge, private cloud, and public cloud nodes to satisfy Health Canada data residency requirements. Major Canadian banks are adopting this architecture to maintain on-premises voice capture while leveraging cloud-based model training. This three-tier configuration is hybridizing vendor competitive positioning away from pure SaaS toward managed hybrid service offerings.
PIPEDA consent management mandates are reshaping analytics pipeline design. The Office of the Privacy Commissioner requires automated redaction and purpose-limitation controls embedded directly into customer interaction processing. Financial institutions and insurance providers face the steepest compliance burden, responding by procuring platforms with native consent orchestration rather than retrofitting legacy systems.
Agent performance evaluation is pivoting from post-call sampling to continuous behavioral scoring. Quality assurance departments are unbundling traditional supervisor review cycles in favor of automated sentiment and compliance flagging integrated into daily coaching workflows. This shift is most visible among Ontario-based enterprises with consolidated contact center operations, where labor cost pressures accelerate automation adoption.
Canada Contact Center Analytics Market Segmentation
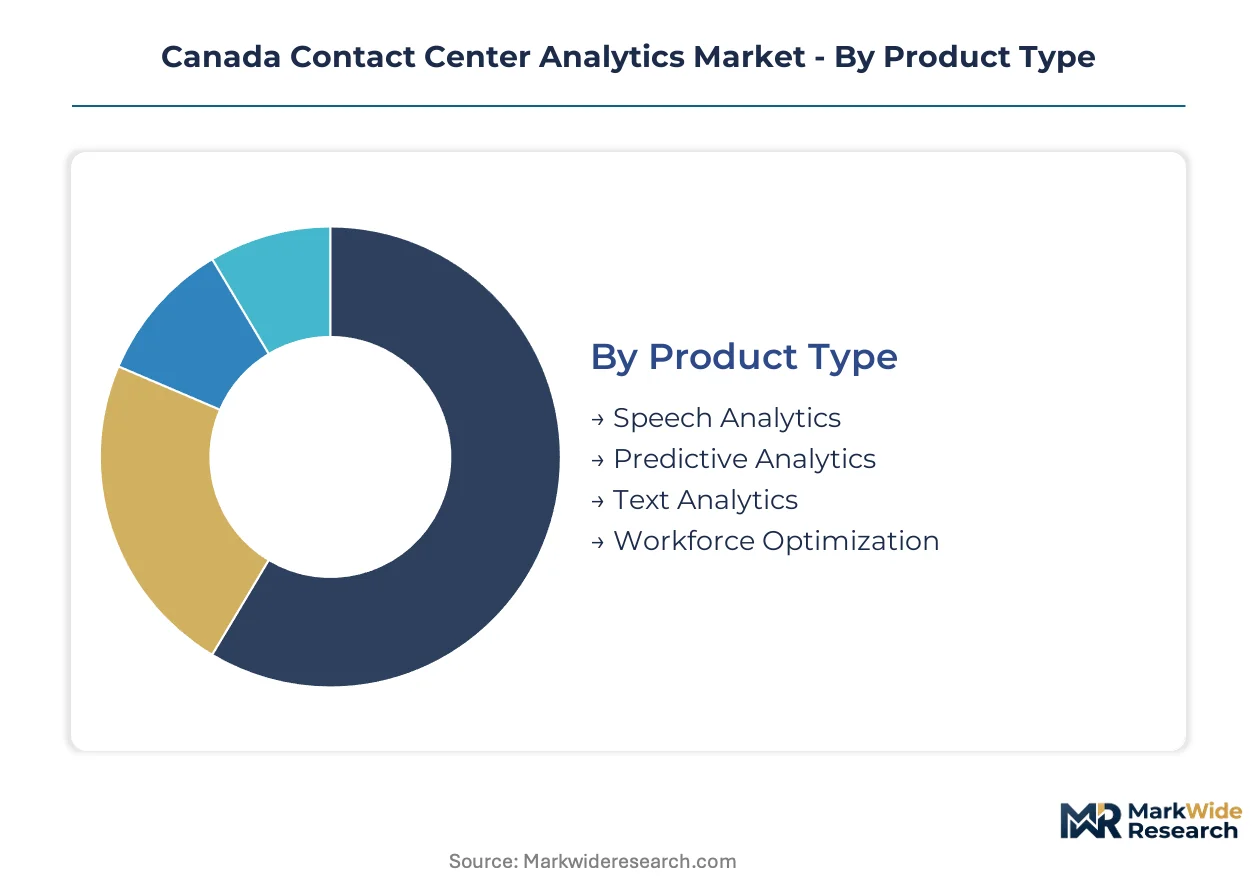
Segmentation in the Canadian contact center analytics market reveals how privacy regulations, latency requirements, and data residency constraints reshape procurement patterns across technology tiers and operational models. Understanding these divides exposes where federal PIPEDA mandates compress deployment timelines and where hybrid architectures retain structural advantages.
Product Type:
Cost tier differentiation separates mature speech infrastructure from emerging predictive platforms with premium pricing power.
- Speech Analytics:Processes 8-16 kHz audio streams through natural language processing engines for sentiment extraction and keyword detection. Canadian banks in Toronto-Waterloo concentrate demand here, driven by real-time churn intervention requirements and sub-200-millisecond latency mandates for live agent coaching.
- Predictive Analytics:Deploys machine learning models to forecast customer behavior and recommend next-best-actions during active conversations. Insurance providers across Ontario are accelerating procurement of these platforms, pressured by customer retention targets and competitive differentiation in digital service channels.
- Text Analytics:Analyzes chat transcripts, email threads, and social media interactions through NLP classification pipelines.
- Workforce Optimization:Integrates scheduling, quality management, and performance analytics into unified agent management suites.
Speech analytics commands the established base. The steepest expansion runs through predictive analytics.
Deployment:
Application architecture determines how Health Canada encryption requirements and cross-border data flow restrictions translate into infrastructure investment levels.
- Cloud-based:Delivers analytics through multi-tenant SaaS platforms with rapid deployment and automatic model updates. Mid-market BPO operators in Ontario favor this model for compliance automation without capital expenditure, though federal data residency rules constrain pure public cloud adoption.
- Hybrid:Maintains on-premises voice capture while routing analytics processing to cloud nodes. Major Canadian financial institutions are standardizing on this three-tier configuration—edge, private cloud, and public cloud—to satisfy PIPEDA consent management while leveraging cloud-based model training.
- On-premises:Houses entire analytics stack within enterprise data centers with full hardware control.
- Private Cloud:Deploys dedicated cloud infrastructure with single-tenant isolation and customizable security policies.
Hybrid architectures command the established base. The steepest expansion runs through cloud-based deployment among mid-tier enterprises.
Use Case:
Customer type priorities reflect how regulatory pressure versus operational efficiency drives procurement sequencing across Canadian sectors.
- Compliance Monitoring:Automates consent tracking, call recording redaction, and purpose-limitation enforcement within analytics pipelines. Financial institutions and insurance providers face the steepest Office of the Privacy Commissioner enforcement burden, compelling native consent orchestration rather than legacy system retrofitting.
- Customer Experience Management:Unifies interaction data across voice, chat, and digital channels to map journey friction and satisfaction drivers. Retail contact centers in Ontario's consolidated operations concentrate demand here, pressured by labor cost optimization and automated sentiment scoring.
- Quality Assurance:Replaces supervisor sampling with continuous automated evaluation of agent performance.
- Performance Management:Links individual agent metrics to coaching workflows and incentive structures.
Compliance monitoring commands the established base. The steepest expansion runs through customer experience management.
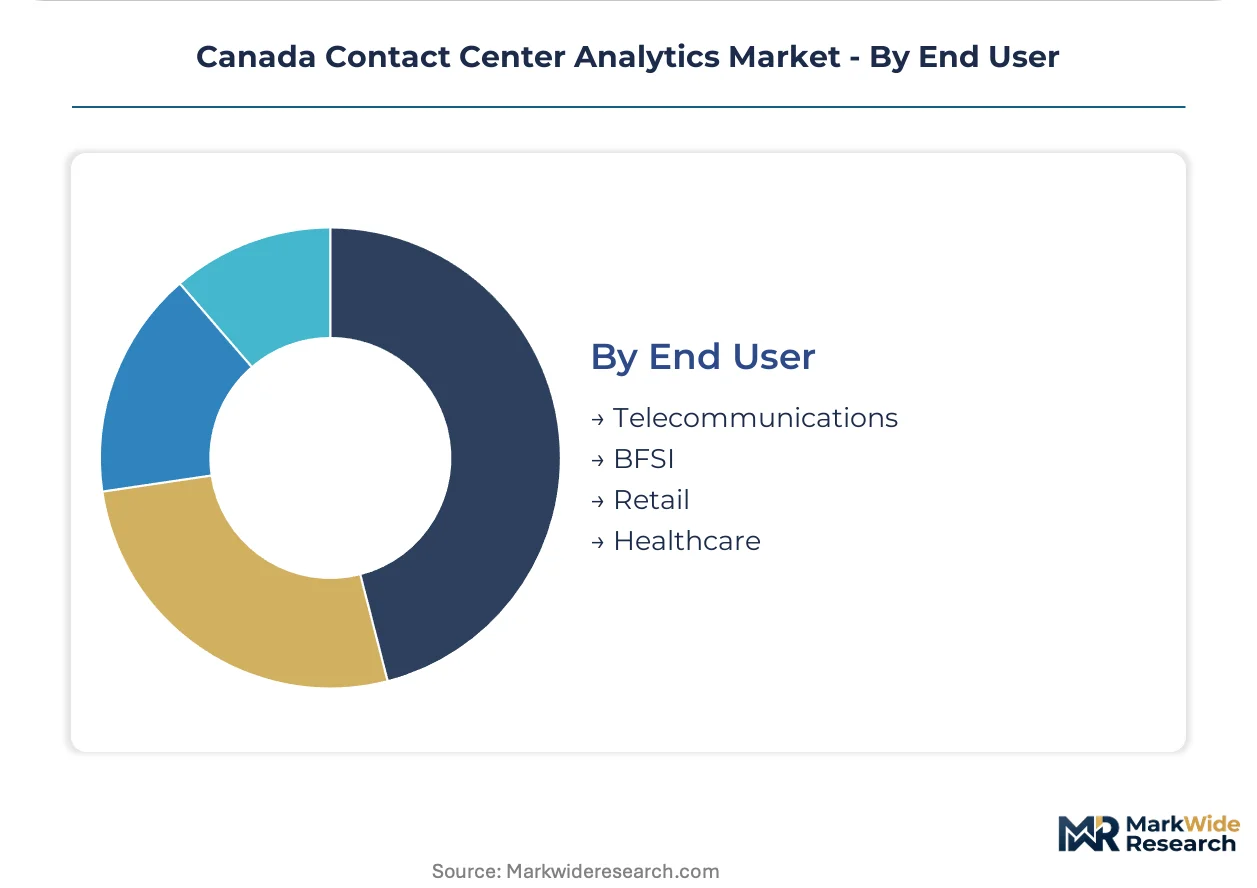
End User:
Geographic concentration within Canada maps regulatory exposure and technology corridor density onto sector-specific adoption timelines.
- BFSI:Banking, financial services, and insurance sectors deploy the most sophisticated real-time analytics stacks. Toronto-Waterloo corridor consolidation concentrates enterprise procurement here, with federal PIPEDA mandates and Health Canada encryption requirements driving hybrid architecture standardization.
- Telecommunications:Carriers manage massive interaction volumes across billing, technical support, and retention functions. Quebec and British Columbia operations face additional provincial localization constraints beyond federal baselines, fragmenting national deployment architectures.
- Retail:Omnichannel merchants apply analytics to seasonal demand spikes and customer service scaling.
- Healthcare:Patient engagement and appointment management operations navigate stricter data handling standards.
BFSI commands the established base. The steepest expansion runs through telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market BPO operators in Ontario exhibit the highest price elasticity, while federally regulated banks accept premium hybrid infrastructure costs to satisfy PIPEDA mandates. Geographic demand patterns concentrate where provincial privacy regimes diverge from federal baselines.
Ontario
Toronto-Waterloo corridor enterprises drive enterprise-grade procurement for real-time speech analytics with sub-200-millisecond latency requirements. Health Canada encryption standards and federal data residency rules compel hybrid cloud architectures among major financial institutions. Enterprise contact center consolidation in the corridor accelerates automated sentiment scoring adoption for agent coaching workflows.
Quebec
Provincial privacy legislation imposes stricter data localization mandates than PIPEDA federal baselines, fragmenting national deployment architectures for telecommunications carriers. The Office of the Privacy Commissioner enforcement of consent management requirements elevates procurement criteria for native redaction capabilities. Montreal-based insurance operations concentrate demand for compliance-integrated analytics platforms with embedded purpose-limitation controls.
British Columbia
Anticipated provincial privacy expansion creates first-mover positioning opportunities for vendors pre-integrating enhanced localization workflows. Health Canada cross-border data flow restrictions compel redundant domestic cloud capacity investment among healthcare patient engagement operations. Vancouver technology clusters concentrate mid-market demand for rapid-deployment speech analytics without heavy capital expenditure.
Alberta
Energy sector customer service operations navigate compliance automation requirements with moderate price sensitivity relative to federally regulated financial services. PIPEDA consent orchestration mandates reshape procurement toward platforms with automated redaction rather than legacy system retrofitting. Calgary-based enterprise contact centers standardize on cloud-native workforce optimization suites for seasonal demand spike management.
Canada Contact Center Analytics Market Competitive Landscape
Enterprise-suite incumbents and cloud-native specialists split the market between hybrid infrastructure dominance and rapid-deployment mid-market penetration. The vendor base concentrates around three strategic archetypes: full-stack workforce optimization providers, pure-play speech analytics specialists, and telecommunications-heritage infrastructure vendors. Consolidation pressure intensifies as federal privacy mandates compress deployment timelines and elevate compliance-integrated platform requirements. Dominant competitive moves include strategic partnerships with domestic cloud providers for data residency certification and portfolio diversification into predictive-analytics convergence.
Within the enterprise-suite tier, NICE Ltd and Genesys anchor competitive positioning through AI-driven workforce optimization and cloud-native routing infrastructure respectively. Five9 occupies a specialist position serving mid-market BPO operators seeking compliance automation without heavy capital expenditure. These three exemplify how vendor archetypes map onto divergent buyer price elasticity and regulatory exposure across Canadian provincial markets.
| Leading Market Players |
|---|
| NICE Ltd |
| Genesys |
| Cisco Systems |
| Five9 |
| 8x8 Inc |
| Genpact |
| Enghouse Systems |
| CallMiner |
| Verint Systems |
| Others |
Pricing and Supply Chain Analysis
The Toronto-Waterloo technology corridor's fiber backbone and cross-border connectivity costs compress margin structures for cloud-native vendors while amplifying price differentiation between hybrid-certified incumbents and rapid-deployment SaaS challengers. PIPEDA compliance automation requirements concentrate procurement power among federally regulated financial institutions willing to absorb premium infrastructure costs, fragmenting national pricing architectures across provincial privacy regimes.
Pricing Analysis
After-sales revenue from managed compliance services and automated redaction subscriptions drives lifetime value beyond initial platform licensing. The dominant structure is tiered SaaS pricing stratifying across enterprise, mid-market, and BPO-operator levels, with differentiation anchored in Health Canada encryption certification and real-time latency performance. Pricing pressure stems from Quebec's stricter localization mandates fragmenting national deployment economies. Mid-market BPO operators in Ontario exhibit highest price sensitivity, while federally regulated banks accept premium hybrid infrastructure costs.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates supply chain risk for edge-computing hardware and specialized NLP processing chips. Component sourcing concentrates in Taiwan, South Korea, and the United States for GPU clusters and audio sampling hardware. Domestic cloud capacity investment hinges on redundant data center builds in Ontario and British Columbia to satisfy Health Canada cross-border data flow restrictions. Distribution runs through systems integrators with federal security clearance and direct vendor relationships with Toronto-Waterloo financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring compliance-automation subscriptions expand faster than perpetual speech-analytics licenses. The fastest-growing revenue layer is automated redaction and consent-orchestration services embedded within analytics pipelines.
For Market Incumbents: Pre-empt provincial fragmentation by pre-integrating Quebec-grade localization workflows into standard product architectures before British Columbia mandates replicate Quebec's stricter baseline. Consolidate channel control through exclusive partnerships with Toronto-Waterloo systems integrators holding federal security clearance. Deepen backward integration into domestic cloud infrastructure to capture data-residency premium pricing.
For New Entrants and Emerging Players: Build out rapid-deployment speech-analytics offerings targeting mid-market BPO operators in Vancouver and Calgary underserved by enterprise-suite complexity. British Columbia's anticipated privacy expansion creates first-mover positioning for vendors with pre-integrated localization. The most penetrable entry point is compliance-automation-as-a-service with sub-30-day deployment timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications-heritage infrastructure vendors with stranded on-premises contact-center assets and captive financial-services customer bases. Long-term viability centers on predictive-analytics convergence capabilities and federal certification moats. The signal to watch is Office of the Privacy Commissioner enforcement velocity accelerating replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Certification | Health Canada encryption compliance unlocks federally regulated bank procurement. |
| Real-Time Latency Optimization | Sub-200-millisecond streaming architectures enable live churn intervention pricing. |
| Provincial Localization Pre-Integration | Quebec-grade data residency workflows capture British Columbia expansion timing. |
| Predictive-Analytics Convergence | Next-best-action algorithm integration opens premium real-time decisioning tiers. |
| Mid-Market BPO Channel Partnership | Rapid-deployment positioning addresses underserved compliance automation demand. |
Research Methodology
A standing panel of contact-center operations directors, PIPEDA compliance officers, cloud procurement leads, and BPO managing directors provided ongoing calibration across primary fieldwork. Secondary validation drew from Office of the Privacy Commissioner enforcement disclosures, Health Canada data-handling guidance, hyperscaler Canadian capex announcements, and provincial legislative tracking databases. Bottom-up deployment counts across Ontario, Quebec, and British Columbia were triangulated against top-down vendor revenue attribution.
Scenario bracketing across conservative, baseline, and accelerated PIPEDA enforcement trajectories shaped projection outputs across the analysis window. Segmentation dimensions modeled include deployment architecture, product type tier, end-use vertical, and provincial regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating real-time latency requirements and hybrid infrastructure cost trajectories. Forecast inputs included federal cloud-migration mandate timelines and provincial privacy legislative velocity.
Stress conditions across PIPEDA enforcement intensity, Quebec localization mandate expansion, and cross-border data flow restriction tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding mid-market BPO price elasticity and federal bank procurement cycle timing. Material shifts in Office of the Privacy Commissioner enforcement posture or British Columbia legislative trajectory would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Service Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
North America Operational Intelligence Market
Analytics
Latin America Big Data Analytics Market
Analytics
Complex Event Processing Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Web Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Global Customer Analytics Market
Analytics
Business Analytics Market
Analytics
Data Analytics Market
Analytics
APAC Retail Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Descriptive Analytics (Descriptive Statistics) Market
Analytics
Global Cognitive Analytics Market
Analytics
Asia Pacific Speech Analytics Market