
 Descriptive Analytics (Descriptive Statistics) Market | 2026-2036
Descriptive Analytics (Descriptive Statistics) Market Size, Share, and Industry Trends Forecast 2026-2036
Descriptive Analytics (Descriptive Statistics) Market Outlook
Cloud infrastructure provisioning in the United States is decoupling from traditional on-premise data center economics. IBM Corporation leverages mainframe-to-cloud integration expertise to sustain enterprise accounts with legacy statistical workloads. Microsoft Corporation anchors its position through Azure-native descriptive analytics services embedded across Office 365 and Power BI ecosystems. SAS Institute Inc. differentiates through specialized statistical computing environments that dominate regulated industries requiring audit-ready analytical lineage.
Descriptive analytics encompasses the quantitative summarization of historical data through measures of central tendency, dispersion, and distribution shape to reveal patterns within structured datasets. The discipline employs frequency analysis, cross-tabulation, and basic inferential indicators to transform raw operational records into interpretable business intelligence for commercial decision-making. Business Intelligence applications lead solution demand as organizations prioritize self-service reporting capabilities over IT-dependent query environments. Statistical Analysis Platforms represent the fastest-expanding solution category, driven by Python and R integration requirements among data scientist end users who demand programmatic flexibility beyond graphical interfaces. Healthcare and Finance verticals concentrate margin pools due to compliance-driven documentation standards and risk quantification mandates that necessitate rigorous descriptive statistical protocols.
FDA audit trail requirements for pharmaceutical analytics shape product development priorities for vendors serving healthcare verticals, while HIPAA safeguards dictate data handling architectures across cloud and hybrid deployments. The European GDPR framework imposes purpose limitation and storage minimization constraints that vendors must engineer into automated descriptive pipeline workflows. Stakeholders should monitor evolving SEC climate disclosure rules, which will extend descriptive analytics obligations to environmental metric summarization for publicly traded filers.
Market Dynamics
Cloud migration mandates from federal agencies and HIPAA-aligned healthcare providers are forcing legacy statistical software vendors to rearchitect delivery models around containerized, API-first platforms.
Growth Catalysts
- FDA 21 CFR Part 11:Pharmaceutical manufacturers must maintain electronic audit trails for statistical analyses, driving demand for compliant descriptive analytics platforms with immutable logging capabilities.
- Python and R ecosystems:Data science teams in financial services firms are rejecting GUI-only tools in favor of programmatic statistical environments that integrate with Jupyter notebooks and version control systems.
- Germany:Industrial Mittelstand manufacturers are deploying descriptive analytics for supply chain visibility, pressured by the EU Supply Chain Due Diligence Directive's documentation requirements.
Market Restraints
- GDPR purpose limitation:European enterprises face structural constraints on historical data retention for longitudinal statistical analysis, forcing shorter observation windows and reduced analytical depth.
- Specialized statistical talent scarcity:The shallow pool of practitioners fluent in both frequentist methods and modern Bayesian frameworks limits deployment velocity for complex descriptive projects.
- On-premise sunk costs:Large healthcare systems with capitalized SAS and SPSS installations exhibit delayed cloud migration timelines, slowing subscription revenue conversion for SaaS-native vendors.
Strategic Opportunities
- SEC climate disclosure rules:Public filers must summarize environmental metrics using standardized descriptive frameworks, creating new vertical demand for carbon accounting analytics.
- Edge computing convergence:Manufacturing facilities are deploying lightweight descriptive engines directly on production equipment, enabling real-time quality control without cloud latency.
- India:The PLI scheme for electronics manufacturing is generating demand for statistical process control systems among contract manufacturers serving export markets.
Industry Challenges
- Legacy system integration:Mainframe-hosted historical datasets in banking and insurance resist seamless extraction for modern cloud analytics pipelines, requiring expensive middleware development.
- Statistical literacy gaps:Business users misinterpret confidence intervals and p-values embedded in self-service dashboards, creating organizational risk and eroding trust in analytical outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Descriptive Analytics (Descriptive Statistics) Market |
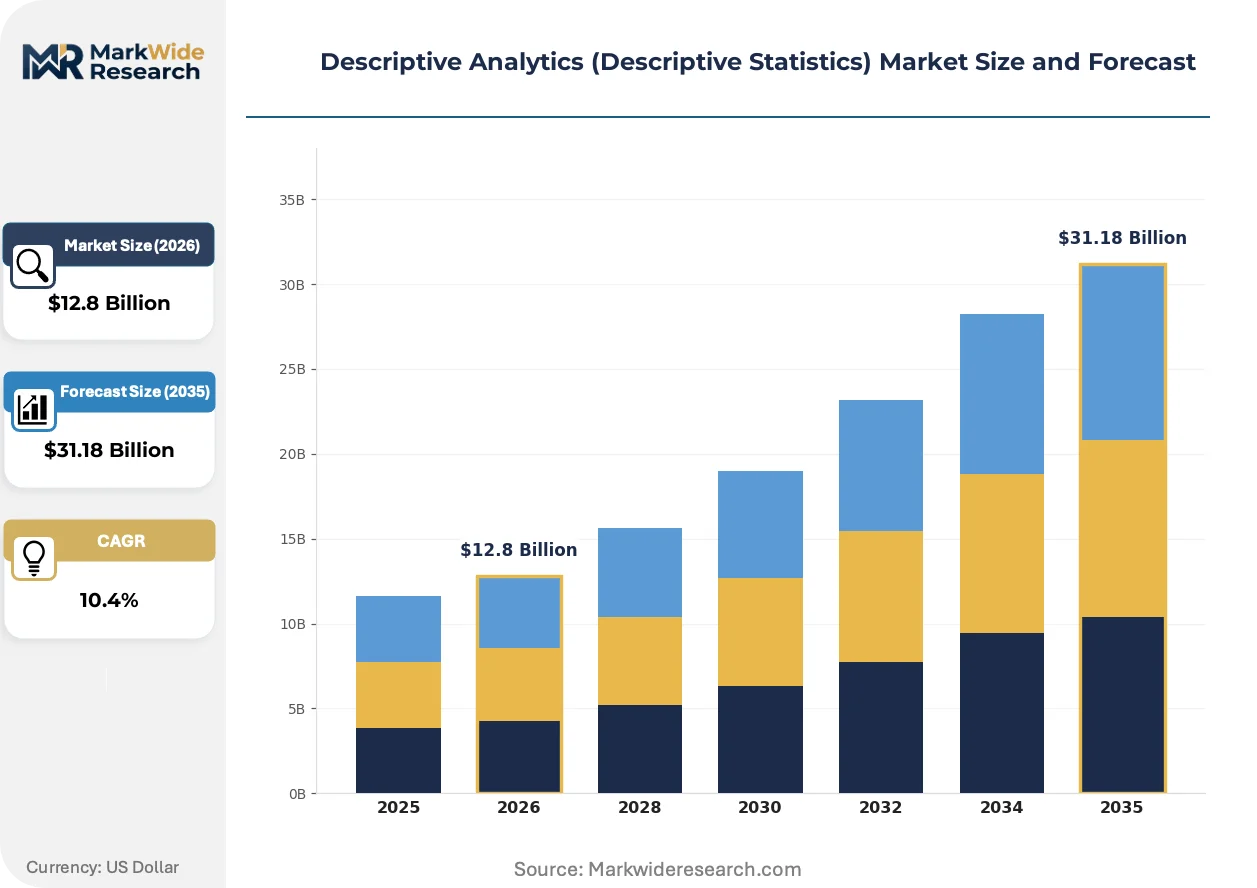
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $31.18 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Business Intelligence, Market Research, Risk Management, Social Media Analysis Industry Vertical: Healthcare, Finance, Retail, Education Solution: Data Visualization Tools, Reporting Software, Dashboard Solutions, Statistical Analysis Platforms End User: Analysts, Decision Makers, Researchers, Data Scientists |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Oracle Corporation, SAS Institute Inc., Tableau Software, Salesforce, Amazon Web Services, Inc., Accenture plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Descriptive Analytics (Descriptive Statistics) Market Strategic Shifts
Automated statistical pipeline construction and embedded governance controls are compressing the time from raw data ingestion to certified business intelligence, reshaping vendor competitive dynamics.
Generative AI copilots for code generation are electrifying how data scientists build descriptive workflows. Python users at mid-market retailers are adopting natural language interfaces to auto-generate pandas and scipy scripts, collapsing the iteration cycle from hours to minutes. This capability is compressing pricing power for traditional statistical consulting services and forcing platform vendors to embed AI assistance as a table-stakes feature.
The EU AI Act's risk-based classification system is redefining documentation obligations for statistical models used in credit scoring and hiring decisions. High-risk applications must maintain complete analytical lineage and human oversight protocols, extending descriptive analytics requirements into algorithmic accountability infrastructure. Financial services firms in France and the Netherlands are restructuring data science teams to embed compliance reviewers earlier in the exploratory analysis phase.
Self-service visualization tools are displacing IT-ticket reporting cultures in North American healthcare systems. Clinical operations managers at hospital networks now build their own census and throughput dashboards using drag-and-drop interfaces, bypassing centralized BI departments. This shift concentrates purchasing authority with departmental budgets rather than enterprise IT procurement, fragmenting vendor contract sizes and complicating account management strategies.
Descriptive Analytics (Descriptive Statistics) Market Segmentation
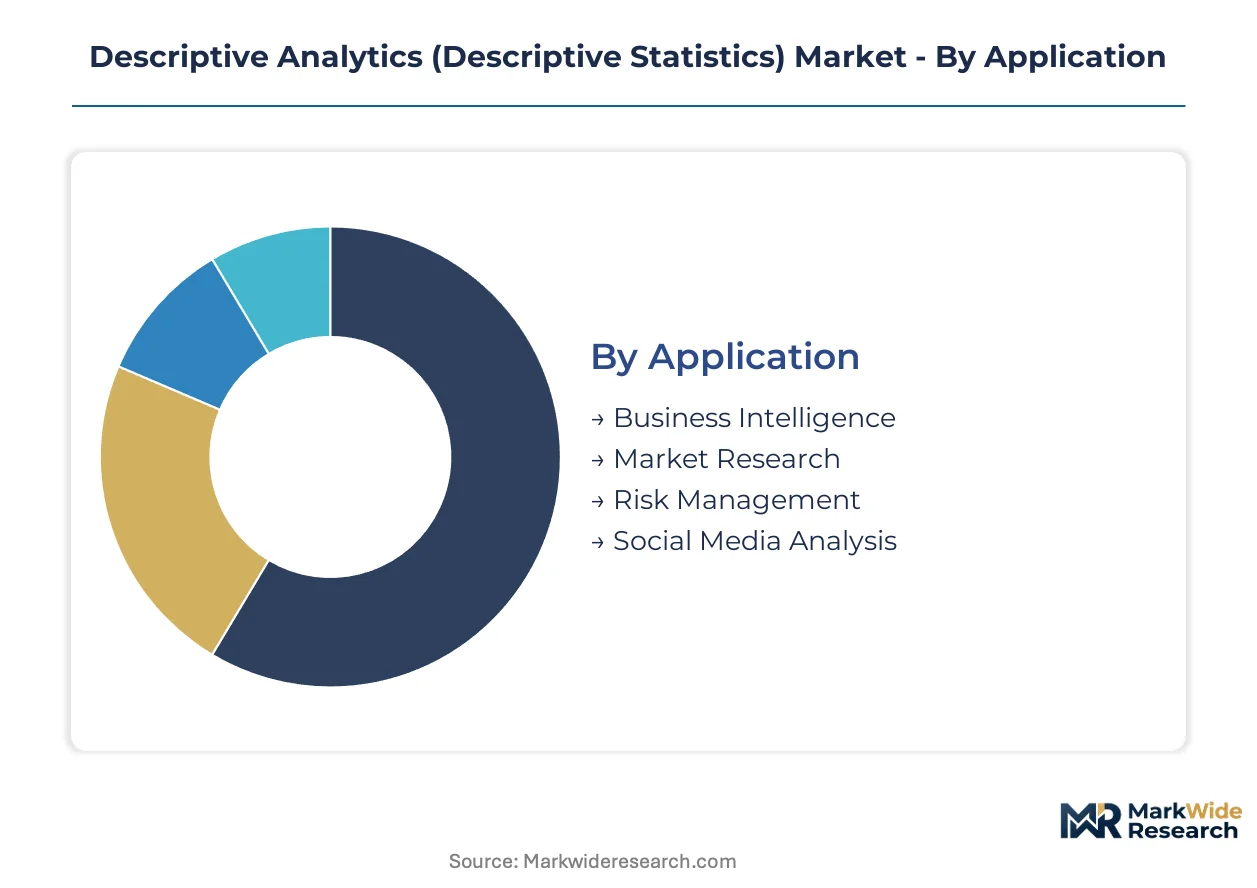
Descriptive analytics procurement patterns diverge sharply by organizational maturity and regulatory exposure. Segmentation reveals how capital allocation, compliance burden, and technical sophistication reshape vendor selection across distinct buyer profiles.
Application:
Capital intensity varies dramatically across use cases, with infrastructure-heavy deployments demanding multi-year cloud commitments and specialized hardware.
- Business Intelligence:Self-service reporting platforms aggregate historical operational metrics into executive dashboards through automated ETL pipelines. Demand clusters among United States hospital networks modernizing legacy SAS environments under HIPAA cloud migration mandates.
- Market Research:Cross-tabulation and frequency analysis tools process survey panels and transactional records to identify consumer behavioral patterns. European CPG firms under GDPR purpose limitation constraints are shortening data retention windows, compressing longitudinal study feasibility.
- Risk Management:Quantile analysis and volatility modeling for credit and operational risk scoring.
- Social Media Analysis:Sentiment summarization and engagement metric aggregation for brand monitoring.
Most installed capacity flows through Business Intelligence. Expansion is steepest in Risk Management.
Industry Vertical:
Margin structures and procurement authority differ fundamentally between regulated and unregulated sectors, with compliance-driven documentation requirements commanding premium pricing.
- Healthcare:FDA 21 CFR Part 11 mandates immutable audit trails for clinical trial statistical analyses, forcing pharmaceutical sponsors toward validated platforms with electronic signature capabilities. United States health systems dominate procurement volume as federal interoperability rules accelerate legacy system replacement.
- Finance:Basel III liquidity coverage ratio calculations and CCAR stress testing documentation require rigorous descriptive statistical protocols with full analytical lineage. United States regional banks are consolidating fragmented Excel-based reporting onto centralized platforms ahead of SEC climate disclosure rule implementation.
- Retail:Inventory turnover and customer segmentation analytics for demand forecasting.
- Education:Student outcome tracking and institutional performance benchmarking.
Healthcare captures the largest contract values. Finance is gaining share fastest as climate disclosure obligations expand.
Solution:
Deployment complexity and integration burden separate turnkey SaaS offerings from environments requiring extensive professional services.
- Statistical Analysis Platforms:Programmable environments supporting Python, R, and Julia execution with version control integration. Data science teams at United States mid-market retailers are rejecting GUI-only tools in favor of Jupyter-compatible pipelines that collapse iteration cycles from hours to minutes.
- Data Visualization Tools:Drag-and-drop interfaces for exploratory chart generation without coding requirements. German Mittelstand manufacturers under EU Supply Chain Due Diligence Directive pressure are deploying lightweight descriptive engines for supplier visibility without dedicated data science headcount.
- Reporting Software:Scheduled distribution of standardized tabular outputs to stakeholder lists.
- Dashboard Solutions:Real-time metric monitoring with alerting thresholds for operational KPIs.
Statistical Analysis Platforms absorb the most R&D investment. Dashboard Solutions are climbing the fastest as departmental purchasing authority fragments.
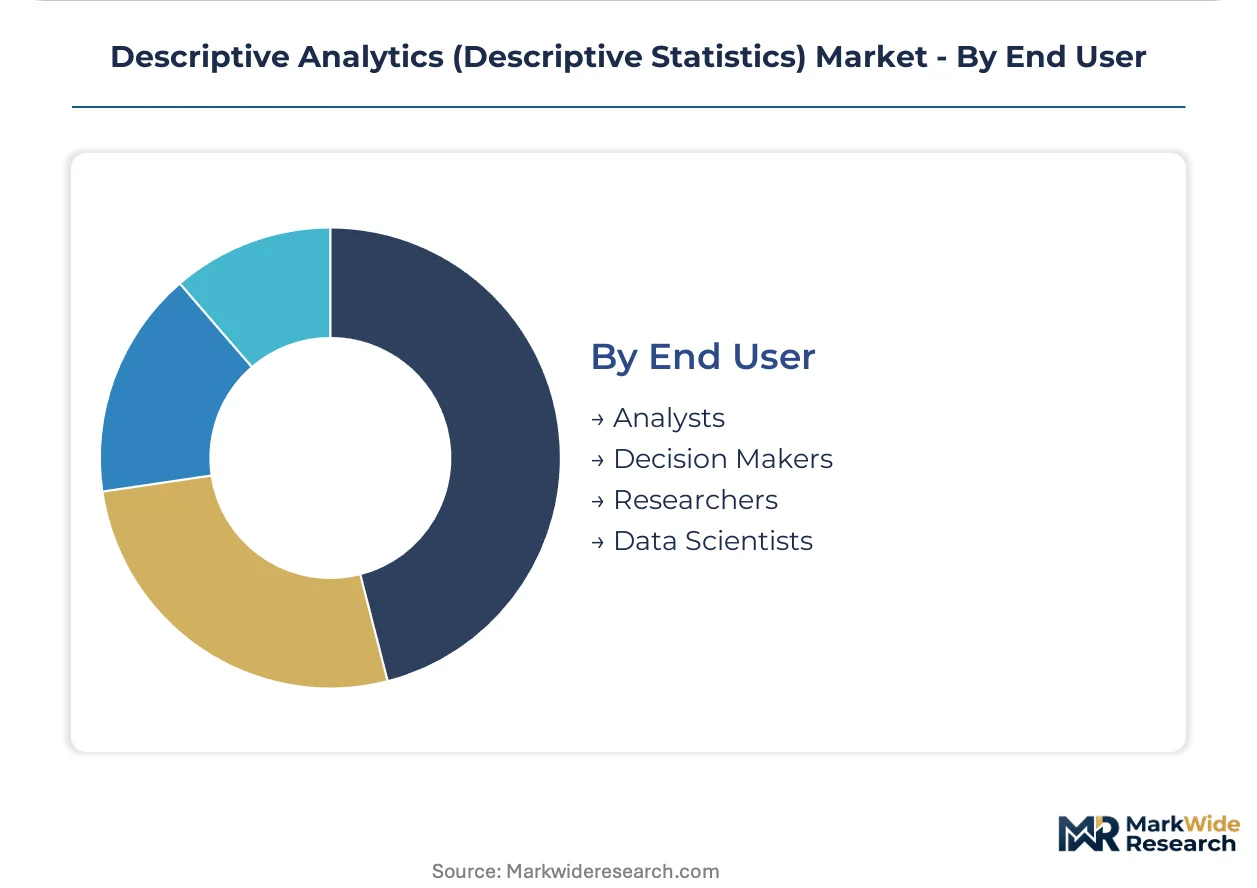
End User:
Technical fluency and organizational influence determine platform selection criteria, with programmatic users demanding API flexibility and business users prioritizing intuitive interfaces.
- Data Scientists:Advanced practitioners requiring Bayesian and frequentist method libraries with custom package installation. United States financial services firms are restructuring teams to embed compliance reviewers earlier in exploratory analysis phases under EU AI Act documentation obligations.
- Analysts:Technical staff producing recurring reports with moderate statistical sophistication. India's contract electronics manufacturers under PLI scheme incentives are adopting statistical process control systems for export quality certification.
- Decision Makers:Executives consuming pre-aggregated insights without direct platform interaction.
- Researchers:Academic and clinical investigators requiring publication-grade output formatting.
Data Scientists drive platform roadmap priorities. Analysts represent the largest addressable headcount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting descriptive analytics procurement toward jurisdictions with clearer data governance frameworks. The United States maintains cost-of-compliance advantages through sector-specific exemptions, while European enterprises absorb GDPR overhead that compresses vendor margins.
United States
Federal cloud migration mandates and HIPAA-aligned healthcare provider requirements are accelerating legacy statistical platform replacements. FDA 21 CFR Part 11 audit trail obligations for pharmaceutical sponsors are forcing validated platform selections with electronic signature capabilities. Hospital networks in the Boston-Cambridge corridor are consolidating fragmented Excel-based reporting onto centralized cloud analytics infrastructure.
Germany
Industrial Mittelstand manufacturers under EU Supply Chain Due Diligence Directive pressure are deploying descriptive engines for supplier visibility documentation. GDPR purpose limitation constraints are shortening permissible data retention windows, forcing vendors to engineer automated deletion workflows into statistical pipelines. Manufacturing clusters in Baden-Württemberg are adopting lightweight edge-computing descriptive engines for real-time quality control on production equipment.
India
PLI scheme incentives for electronics manufacturing are generating demand for statistical process control systems among contract manufacturers seeking export certification. The country's national data protection framework is crystallizing procurement criteria for cloud-hosted analytics vendors. Electronics manufacturing clusters in Karnataka and Tamil Nadu are integrating Python-based statistical environments with existing ERP systems for defect tracking.
United Kingdom
Post-Brexit divergence from EU GDPR enforcement patterns is creating regulatory clarity for longitudinal health data analysis projects. NHS digital transformation programs are reallocating capital toward self-service BI platforms that bypass centralized IT departments. London-based financial services firms are restructuring data science teams to embed compliance reviewers earlier in exploratory analysis phases.
France
EU AI Act risk-based classification requirements are extending documentation obligations into credit scoring and hiring decision workflows. ANSM and CNIL joint guidance on health data secondary use is clarifying permissible statistical analysis scopes for hospital networks. Pharmaceutical research clusters in the Île-de-France region are prioritizing platforms with immutable analytical lineage for clinical trial submissions.
Descriptive Analytics (Descriptive Statistics) Market Competitive Environment
United States technology conglomerates anchor the enterprise-tier segment; European specialists and cloud-native challengers occupy differentiated positions beneath. Market structure exhibits moderate consolidation around vertically integrated platform providers with adjacent cloud infrastructure assets. Three archetypes dominate: legacy statistical computing vendors with regulatory compliance expertise, hyperscale cloud providers embedding analytics into productivity suites, and open-source-centric challengers targeting data scientist end users. Competitive intensity concentrates on M&A activity to acquire specialized statistical talent and API-first platform architectures, alongside strategic partnerships bridging legacy mainframe datasets with modern cloud pipelines.
Within the legacy compliance-tier, IBM Corporation and SAS Institute Inc. represent entrenched positions in regulated verticals requiring audit-ready analytical lineage. Microsoft Corporation exemplifies the hyperscale productivity-embedded archetype through Azure-native services. Among cloud-native challengers, Amazon Web Services, Inc. occupies a scale-driven position. These three anchors collectively illustrate how vendor selection criteria diverge between risk-averse regulated enterprises prioritizing documentation depth and agile data science teams demanding programmatic flexibility.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| SAS Institute Inc. |
| Tableau Software |
| Salesforce |
| Amazon Web Services, Inc. |
| Accenture plc |
| Others |
Value Chain & Pricing Dynamics
Bayesian statistical talent scarcity in the Boston-Cambridge corridor compresses vendor margins at the premium tier while Python-skilled labor pools in India and Eastern Europe enable aggressive SaaS pricing for mid-market segments. Labor-cost differentials between legacy SAS-certified practitioners and open-source data scientists drive 40-60 point spreads across subscription tiers.
Pricing Analysis
Distributor margins for on-premise statistical software deployments absorb 15-25 points before reaching hospital procurement committees, while direct-to-OEM SaaS channels bypass intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels segments by audit-trail depth and regulatory validation tier. Pricing pressure stems from open-source Python and R ecosystems commoditizing core descriptive functions. Mid-market retailers exhibit highest price sensitivity; FDA-regulated pharmaceutical sponsors show lowest sensitivity due to compliance substitution costs.
Supply Chain Analysis
Refurbishment flows for legacy mainframe statistical environments create secondary markets for IBM and SAS Institute maintenance contracts, extending asset life cycles in capital-constrained health systems. Cloud infrastructure provisioning concentrates in the United States, Ireland, and Singapore, with compute and storage forming primary cost inputs. Single-source vulnerability rests on hyperscaler concentration for GPU-accelerated statistical workloads. Distribution runs through direct enterprise sales for regulated verticals and self-service app marketplaces for data scientist end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The descriptive analytics market functions as a stable compounder, with regulatory documentation mandates across healthcare and finance creating recurring revenue stickiness that outpaces discretionary software spend.
For Market Incumbents: Hedge against open-source displacement by embedding governance controls that satisfy FDA 21 CFR Part 11 and EU AI Act lineage requirements. Acquire API-first platform architectures to bridge legacy mainframe datasets with modern cloud pipelines. Vertical integration into containerized delivery preserves margin structure against pure-play SaaS challengers. For New Entrants and Emerging Players: Cloud-native distribution channels bypass incumbent sales cycles and procurement lock-in. Target India's PLI-scheme electronics manufacturers with lightweight statistical process control systems for export certification. Pursue white-space in German Mittelstand supply chain visibility under EU Supply Chain Due Diligence Directive pressure. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirers in this space, seeking statistical computing talent and regulatory compliance IP. Long-term viability rests on documentation-depth moats rather than algorithmic sophistication. Monitor SEC climate disclosure rule implementation velocity as inflection indicator for carbon accounting analytics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native descriptive services embedded across Office 365 collapse procurement friction for enterprise accounts. |
| Acquisition of Specialist Firm | IBM's mainframe-to-cloud integration expertise sustains legacy statistical workloads under HIPAA migration mandates. |
| Regulatory Compliance Investment | SAS Institute's audit-ready analytical lineage dominates pharmaceutical verticals facing FDA 21 CFR Part 11 obligations. |
| Geographic Expansion | AWS scale positions enable aggressive pricing in India's PLI-scheme electronics manufacturing clusters. |
| Strategic Partnership | Microsoft's Power BI ecosystem partnerships fragment departmental purchasing authority away from centralized IT procurement. |
Study Parameters
Direct dialogue with data science directors, hospital procurement managers, regulatory affairs leads at pharmaceutical sponsors, and cloud platform engineers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, SEC climate disclosure draft rules, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up modeling aggregated deployment counts by organization size, vertical regulatory exposure, and solution complexity tier across the projection horizon. Top-down analysis calibrated aggregate market expansion against IT software spend elasticity and compliance-driven substitution patterns. CAGRs derived from segment growth rate differentials weighted by revenue concentration. Forecast inputs included HIPAA cloud migration velocity and EU AI Act implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for generative AI copilot integration would alter the outlook for traditional statistical consulting services. Forecasts reflect assumptions about regulatory enforcement consistency and open-source ecosystem maturation. Practitioners should monitor FDA audit trail guidance updates and SEC climate rule finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Statistical Analytics Market
Analytics
Load (ETL) Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Global Big Data Market
Analytics
Pandemic Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Face Analytics Market
Analytics
APAC Retail Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
UAE Geospatial Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
North America Location Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
Global Talent Intelligence Software Market