
 Global Systems of Insight Market | 2026-2036
Global Systems of Insight Market Size, Share, and Industry Trends Forecast 2026-2036
Global Systems of Insight Market Foresight
Buyer concentration among BFSI institutions is hardening as tier-one banks consolidate vendor relationships around integrated insight stacks. Microsoft Corporation leverages its Azure cloud fabric to embed analytics directly into enterprise workflows, while IBM Corporation sustains mainframe-to-cloud data pipelines that anchor legacy modernization programs. Oracle Corporation competes through database-adjacent intelligence layers that control enterprise data gravity.
Systems of Insight denote integrated technology architectures that aggregate multi-source data streams, apply algorithmic processing at sub-second latency thresholds, and render actionable intelligence to operational decision layers. These platforms serve commercial and industrial users by collapsing the gap between raw data accumulation and contextual business response. Cloud-Based deployment now captures the fastest expansion trajectory as edge-to-core synchronization demands outpace on-premises capacity planning. Predictive Analytics and Machine Learning solutions concentrate margin pools where proprietary model training creates switching costs against standardized visualization tools.
The US SEC, EU GDPR enforcement networks, and Japan's METI data governance guidelines collectively shape product roadmaps through cross-border transfer restrictions and algorithmic accountability mandates. Compliance certification has become a prerequisite for procurement eligibility in regulated end-user segments. Stakeholders must monitor divergence between regional AI transparency standards and their impact on model deployment architectures.
Market Dynamics
Cloud-to-edge data synchronization mandates are compressing procurement cycles across financial services and industrial automation sectors, forcing vendors to pre-integrate compliance architectures before contract eligibility.
Growth Catalysts
- EU Data Sovereignty Mandates:GDPR enforcement networks and the Digital Operational Resilience Act require localized data processing, accelerating replacement of legacy analytics infrastructure in Frankfurt and Paris banking clusters.
- Predictive Model Deployment:BFSI institutions embed real-time scoring engines into payment authorization workflows, collapsing decision latency from minutes to sub-second thresholds.
- Japan METI Guidelines:Algorithmic accountability frameworks for automated lending decisions create procurement specifications that favor explainable AI architectures over black-box alternatives.
Market Restraints
- Specialized Talent Scarcity:Shortages of MLOps engineers and data governance specialists in Germany and the United States extend implementation timelines and inflate service contract premiums.
- Input Cost Volatility:GPU and specialized AI accelerator pricing fluctuations disrupt capacity planning for on-premise model training deployments.
- Technical Limitation:Edge-to-core bandwidth constraints in industrial IoT environments throttle real-time inference for predictive maintenance applications.
Strategic Opportunities
- India Manufacturing Digitization:PLI scheme incentives for smart factory adoption create first-mover advantage for vendors offering localized insight platforms with Hindi and regional language interfaces.
- Converging Architectures:Digital twin visualization layers merging with predictive analytics engines open new contract categories in aerospace supply chain optimization.
- US CLOUD Act Compliance:Cross-border data access provisions drive demand for sovereign cloud configurations that segment jurisdictional processing without duplicating infrastructure.
Industry Challenges
- Certification Timeline Compression:EU AI Act conformity assessments for high-risk financial applications extend vendor qualification periods beyond typical sales cycle expectations.
- Integration Complexity:Mainframe data pipeline modernization at tier-one banks demands bespoke middleware that fragments vendor standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Systems of Insight Market |
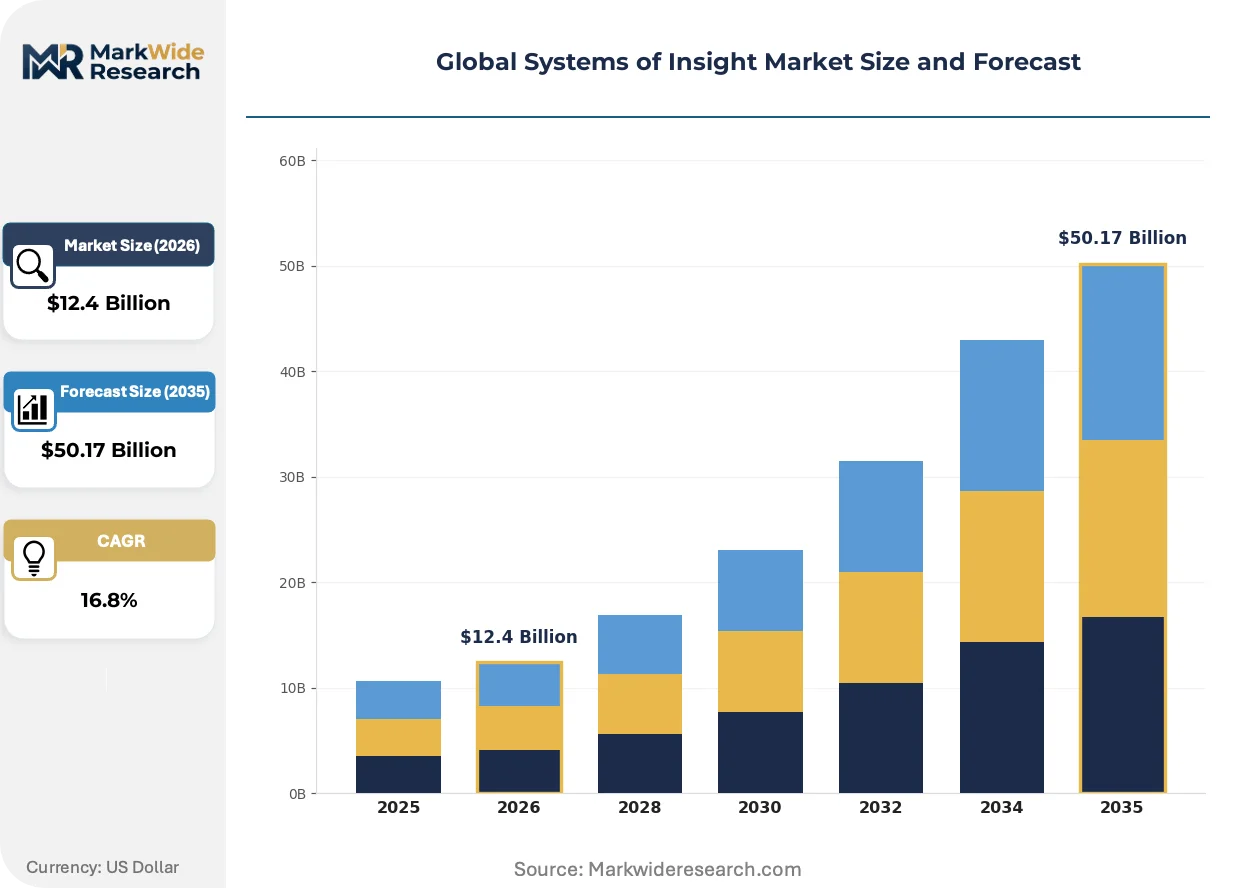
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $50.17 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Solution: Data Integration, Predictive Analytics, Business Intelligence, Data Visualization, Machine Learning Application: Customer Experience Management, Risk Assessment, Supply Chain Optimization, Fraud Detection, Market Trend Analysis End User: BFSI Institutions, Telecommunication Providers, Government Agencies, Manufacturing Enterprises, Energy Corporations |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., TIBCO Software Inc., GoodData Corporation, Splunk Inc., NGDATA SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Systems of Insight Market Shifts & Advancements
Real-time inference architectures are displacing batch-processing workflows across capital markets and industrial operations, compressing the gap between signal detection and automated response.
Unified analytics fabrics are unifying data lakehouse architectures with streaming processing engines. Capital markets firms in New York and London deploy these stacks to correlate alternative data feeds with core transaction records. The technology is unifying previously siloed risk and trading functions into single-pane operational views.
EU AI Act risk classification tiers are reshaping product development roadmaps for vendors serving automated credit decisioning and insurance underwriting segments. High-risk system designations trigger mandatory human oversight modules and audit trail specifications. German automotive finance subsidiaries face accelerated compliance deadlines that favor pre-certified platform procurement over custom builds.
Subscription pricing for insight platforms is displacing perpetual license models in mid-market manufacturing verticals. Industrial buyers in Japan and South Korea favor consumption-based arrangements that scale with sensor deployment counts. This shift concentrates margin pressure on vendors lacking granular usage metering infrastructure.
Global Systems of Insight Market Segmentation
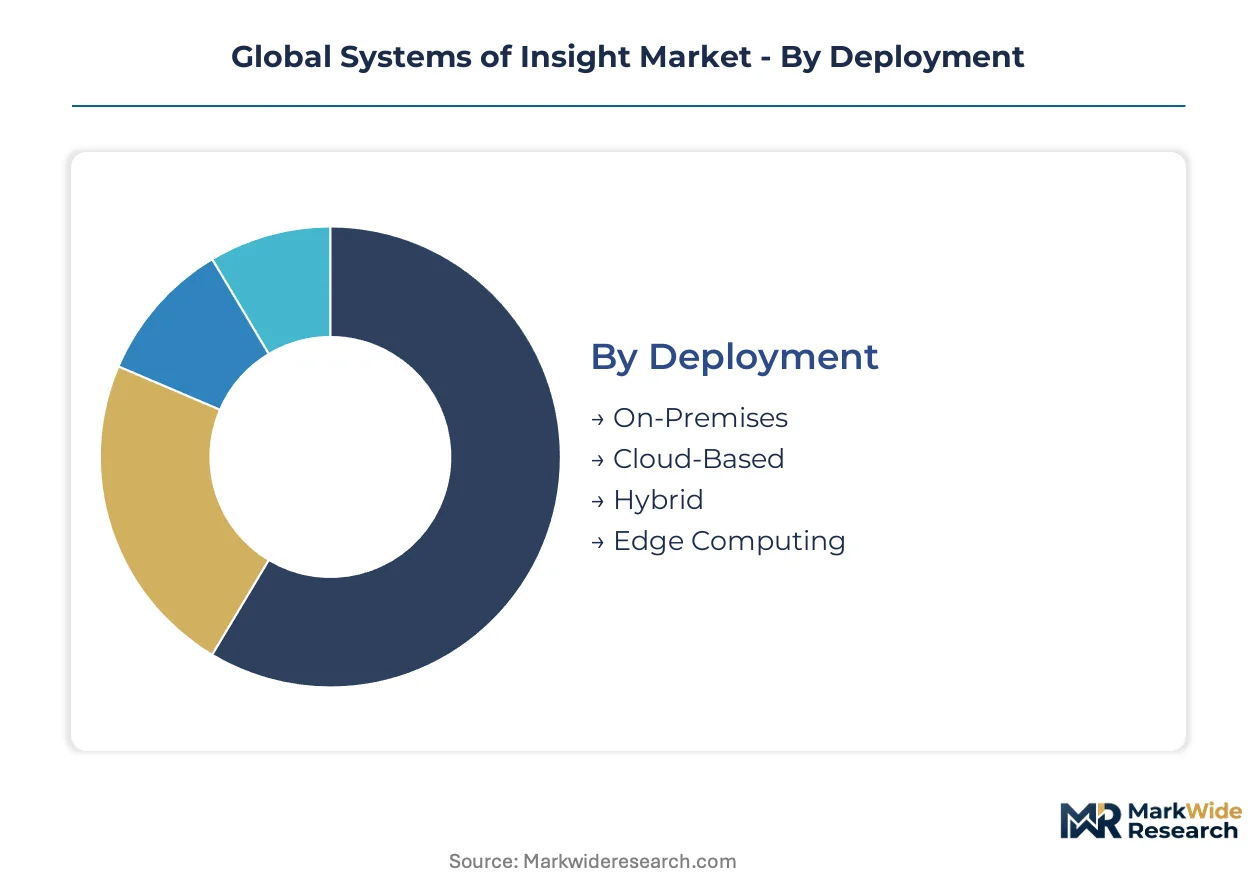
Architectural choices in Systems of Insight deployment determine latency thresholds, compliance postures, and total cost of ownership across operational technology stacks. Segment boundaries reflect competing pressures between real-time inference demands and data sovereignty mandates that fragment procurement specifications by jurisdiction.
Deployment:
Replacement cycles for legacy analytics infrastructure are accelerating as edge-to-core synchronization requirements outpace on-premises capacity planning.
- On-Premises:Dedicated hardware installations within enterprise data centers deliver sub-millisecond latency for high-frequency trading workflows. Tier-one banks in Frankfurt and Tokyo maintain these configurations for core transaction processing despite rising operational overhead.
- Cloud-Based:Distributed compute fabrics enable elastic scaling for variable inference workloads without capital-intensive provisioning. Financial services firms in the United States and Germany are migrating customer analytics workloads to these environments to satisfy EU data residency requirements.
- Hybrid:Architectures partition sensitive data processing on-site while bursting non-critical analytics to public cloud tiers.
- Edge Computing:Localized inference nodes deployed at manufacturing facilities and retail locations reduce backhaul bandwidth consumption.
Cloud-Based deployments sit at the top of the volume ranking, with Edge Computing climbing the fastest as industrial IoT sensor densities expand.
Solution:
Cost tier differentiation separates enterprise-grade platforms with proprietary model training from standardized visualization tools competing on per-seat pricing.
- Predictive Analytics:Algorithmic engines scoring future states from historical pattern recognition anchor real-time decisioning in payment authorization and credit underwriting. BFSI procurement teams in Japan prioritize these solutions under METI algorithmic accountability guidelines.
- Machine Learning:Self-optimizing model architectures create switching costs through proprietary training pipelines and domain-specific feature engineering. Manufacturing enterprises in Germany deploy these for predictive maintenance across automotive supply chains.
- Data Integration:Pipeline orchestration layers normalize multi-source streams into unified analytical schemas.
- Business Intelligence:Dashboard and reporting modules translate processed data into executive-facing metrics.
- Data Visualization:Interactive charting and exploration tools serve analyst workflows with lower technical barriers.
Predictive Analytics commands the largest revenue share, while Machine Learning gains share fastest as automated model retraining capabilities mature.
Application:
Customer maturity varies sharply across use cases, with fraud detection representing established procurement categories and market trend analysis emerging as experimental budget lines.
- Fraud Detection:Real-time pattern recognition identifies anomalous transactions across payment networks before settlement completion. United States card issuers embed these engines directly into authorization streams to minimize chargeback exposure.
- Risk Assessment:Multi-factor scoring models quantify counterparty exposure and operational vulnerabilities for capital allocation decisions. EU banking supervisors mandate these capabilities under Digital Operational Resilience Act stress-testing protocols.
- Customer Experience Management:Behavioral analytics personalize engagement across digital touchpoints.
- Supply Chain Optimization:Demand forecasting and inventory positioning algorithms reduce working capital requirements.
- Market Trend Analysis:Alternative data correlation identifies shifting consumer preferences before traditional indicators register movement.
Fraud Detection leads deployment volumes, with Market Trend Analysis expanding most quickly as alternative data sourcing proliferates.
End User:
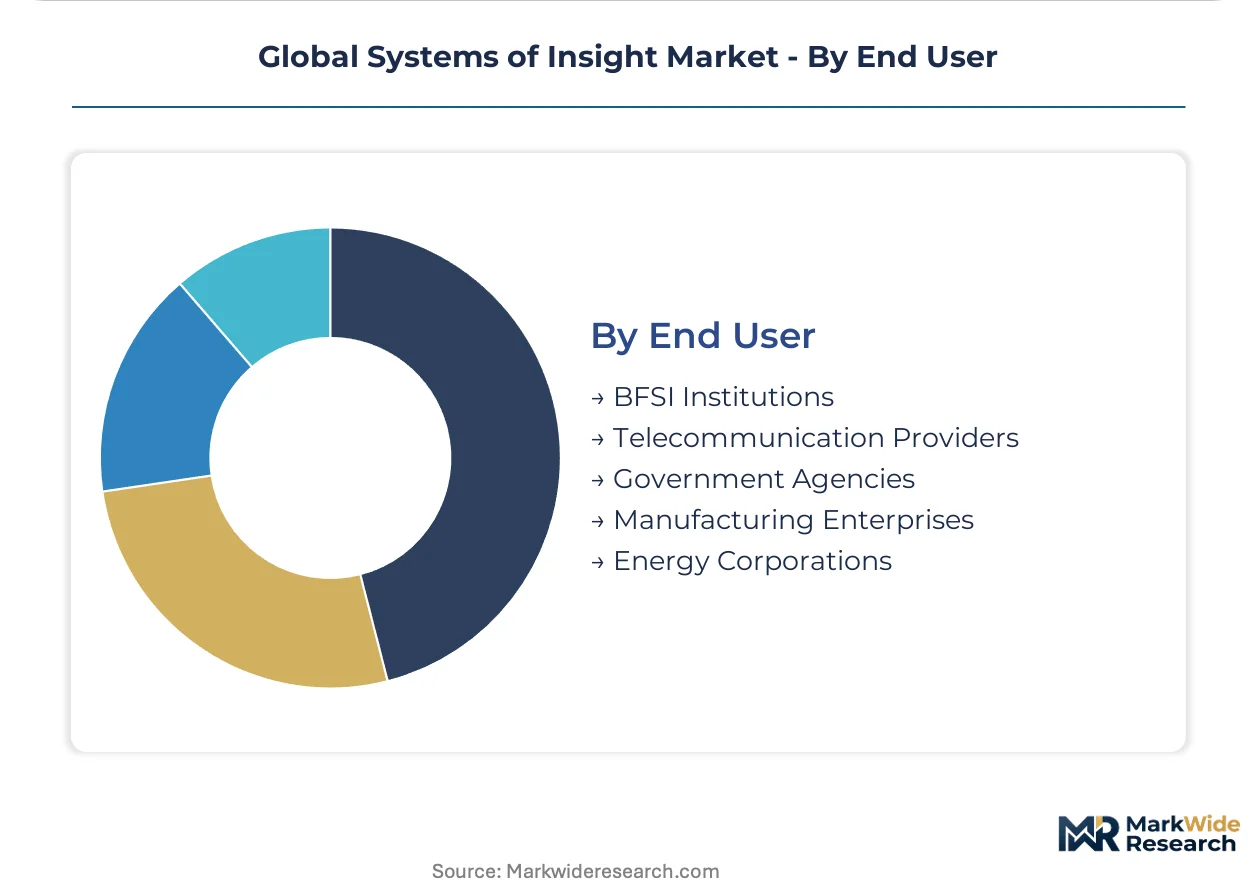
Application concentration determines margin structures, with BFSI institutions commanding premium pricing for compliance-certified configurations and manufacturing buyers driving standardization.
- BFSI Institutions:Banks, insurers, and asset managers deploy comprehensive insight stacks across trading, risk, and regulatory reporting functions. GDPR enforcement networks and SEC examination priorities shape procurement specifications toward audit-ready architectures.
- Manufacturing Enterprises:Smart factory operators integrate sensor data with enterprise resource planning for predictive maintenance and quality optimization. Japan and South Korea lead adoption as labor cost pressures accelerate automation investments.
- Telecommunication Providers:Network operators analyze subscriber behavior and infrastructure performance for churn reduction and capacity planning.
- Government Agencies:Public sector entities deploy citizen-facing analytics and internal operational intelligence under procurement transparency mandates.
- Energy Corporations:Grid operators and oilfield services firms optimize asset performance and demand forecasting across distributed infrastructure.
BFSI Institutions dominate current spending, with Manufacturing Enterprises showing the steepest expansion trajectory as Industry 4.0 digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's banking clusters drive stricter data localization requirements than Japan's algorithmic accountability frameworks, yet both markets command premium pricing for compliance-certified platforms. United States financial institutions balance SEC examination priorities against cross-border data transfer constraints. India manufacturing digitization creates parallel demand trajectories for localized insight platforms.
United States
Capital markets firms in New York deploy unified analytics fabrics to correlate alternative data feeds with core transaction records. SEC examination priorities and CLOUD Act cross-border access provisions shape procurement toward sovereign cloud configurations. Chicago and Boston banking clusters anchor real-time scoring engine deployments for payment authorization workflows.
Germany
Frankfurt banking clusters accelerate replacement of legacy analytics infrastructure under GDPR enforcement networks and Digital Operational Resilience Act timelines. Automotive finance subsidiaries face compressed compliance deadlines favoring pre-certified platform procurement. Munich and Stuttgart industrial zones deploy predictive maintenance architectures across automotive supply chains.
Japan
Tokyo financial institutions embed METI algorithmic accountability frameworks into automated lending decision systems. Manufacturing enterprises in Osaka and Nagoya favor consumption-based pricing arrangements scaling with sensor deployment counts. Explainable AI architectures displace black-box alternatives under regulatory procurement specifications.
India
Maharashtra and Gujarat smart factory operators integrate PLI scheme incentives with localized insight platforms featuring Hindi and regional language interfaces. Mumbai banking clusters pilot real-time inference architectures for fraud detection workloads. Bangalore technology corridors anchor cloud migration programs for mid-market manufacturing verticals.
United Kingdom
London capital markets firms unify risk and trading functions into single-pane operational views through streaming processing engines. Financial Conduct Authority operational resilience requirements intersect with EU AI Act risk classification tiers for cross-border institutions. Edinburgh and Manchester banking subsidiaries navigate divergence between regional AI transparency standards.
Global Systems of Insight Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. Cloud hyperscalers embed analytics directly into enterprise workflows while database-centric vendors leverage data gravity to anchor legacy modernization programs. Three archetypes dominate: integrated platform providers, specialized analytics engines, and compliance-forward middleware specialists. Competitive moves concentrate on strategic partnerships for edge-to-core synchronization and portfolio diversification into explainable AI modules.
Within the integrated platform tier, Microsoft Corporation and Oracle Corporation exemplify divergent approaches to enterprise data architecture. Microsoft Corporation leverages Azure cloud fabric to collapse deployment friction for financial services workloads. Oracle Corporation sustains database-adjacent intelligence layers that control enterprise data gravity through existing infrastructure relationships. IBM Corporation occupies a distinct position anchoring mainframe-to-cloud data pipelines for tier-one banking modernization programs. These three entities represent the competitive spectrum from cloud-native delivery through legacy-integrated transformation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| GoodData Corporation |
| Splunk Inc. |
| NGDATA SA |
| Others |
Supply & Pricing Matrix
Compliance-grade certification divergence separates premium-tier platforms from commodity analytics bundles, concentrating pricing power with vendors holding EU AI Act pre-certification while compressing margins for standardized visualization tools lacking sovereign cloud architectures.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for mid-market manufacturing deployments. Subscription SaaS-tiered structures dominate, with premium-mid-economy pricing differentiation anchored by GDPR certification grade and explainable AI module inclusion. Cost compression in standardized visualization tiers is intensifying because hyperscaler bundling erodes standalone vendor margins. Mid-market manufacturing buyers in Japan and South Korea exhibit highest price sensitivity, while tier-one BFSI institutions in Frankfurt and New York accept premium positioning for audit-ready architectures.
Supply Chain Analysis
GPU and specialized AI accelerator supply rests on Taiwanese foundry output and South Korean memory fabrication. Cloud infrastructure hardware draws from United States, China, and Germany server assembly clusters. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with compliance consulting overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates where explainable AI modules command premium positioning and cloud migration services capture recurring revenue streams from legacy modernization programs.
For Market Incumbents: Acquire specialized MLOps engineering teams to anchor proprietary model training pipelines against hyperscaler commoditization. Consolidate around integrated insight stacks that embed compliance architectures pre-contract. Defensive positioning demands certification investment in EU AI Act conformity assessment frameworks before competitor qualification timelines compress.
For New Entrants and Emerging Players: Regional banking subsidiaries in tier-two German cities present underserved buyer archetype penetration opportunities. White-space concentration sits with Hindi-interface manufacturing platforms under India's PLI scheme and explainable AI modules for Japan METI algorithmic accountability procurement. Go-to-market leverage through channel partnerships with system integrators holding existing mainframe modernization relationships accelerates contract access.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance certification timelines extend beyond typical sales cycles, favoring pre-certified platform acquisitions over organic build. Long-term viability frames around five-to-ten year regulatory divergence trajectories across EU AI Act, US CLOUD Act, and Japan METI frameworks. Target acquisition archetype: specialized analytics engines with domain-specific feature engineering in automotive finance or industrial IoT predictive maintenance. Signal to monitor: divergence between regional AI transparency standards and their impact on model deployment architecture portability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies data lakehouse architectures with streaming engines for capital markets firms in New York and London. |
| Strategic Partnership | Embeds compliance architectures through system integrator relationships with tier-one banking modernization programs. |
| Acquisition of Specialist Firm | Captures proprietary model training pipelines and domain-specific feature engineering in automotive supply chains. |
| Geographic Expansion | Localizes insight platforms with Hindi and regional language interfaces for Maharashtra and Gujarat smart factories. |
| Product Launch | Introduces explainable AI modules satisfying Japan METI algorithmic accountability procurement specifications. |
Research Methodology
Coverage spans Germany, United States, Japan, India, and United Kingdom, with primary inputs from each market cluster. Data synthesis combined structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across financial services and manufacturing verticals. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and industry association reports. Bottom-up deployment volume estimates triangulated against top-down market sizing from cloud infrastructure spending disclosures.
Granularity-level modeling captured deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from trend extrapolation of cloud migration velocity and compliance-driven replacement cycles. Industry-specific inputs included GPU pricing volatility indices and EU AI Act implementation timeline assumptions.
Inputs from regulatory filing databases and hyperscaler infrastructure disclosures were available through the study window; gaps in private company deployment metrics introduce uncertainty bands around mid-market manufacturing segment estimates. Forecasts reflect documented assumptions regarding compliance timeline adherence and cloud migration acceleration rates. Material deviation in EU AI Act enforcement intensity or GPU supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Operational Intelligence Market
Analytics
Global AI Video Analytics Market
Analytics
India Big Data Technology and Service Market
Analytics
Global Development Analytics Tools Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Workforce Analytics Market
Analytics
Global System Monitoring Market
Analytics
Sales Intelligence Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Audio and Video Analytics Software Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
Geospatial Analytics Market
Analytics
Active Data Warehousing Market