
 Network Analytics Services Market | 2026-2036
Network Analytics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Network Analytics Services Market Foresight
Enterprise buyer concentration around cloud-native infrastructure is hardening as Fortune 500 technology procurement teams consolidate vendor rosters. Cisco Systems leverages its ThousandEyes platform to anchor observability across hybrid WAN environments. IBM Corporation sustains competitive relevance through Watson AIOps integration with Red Hat OpenShift deployments. Juniper Networks dominates the service provider segment with Mist AI-driven campus and branch analytics.
Network analytics services encompass software platforms and professional engagements that collect, process, and visualize telemetry from routers, switches, firewalls, and endpoints to optimize performance, detect anomalies, and automate remediation. These systems ingest flow records, SNMP metrics, packet captures, and synthetic test data at millisecond granularity to generate actionable intelligence for network operations centers. Security Analytics commands premium pricing due to zero-trust architecture mandates and breach disclosure requirements. Cloud-Based deployment is expanding fastest as organizations retire on-premises collectors in favor of elastic SaaS observability stacks.
FCC net neutrality restoration proceedings and SEC cybersecurity disclosure rules in the United States are reshaping compliance-driven analytics procurement. EMA and GDPR cross-border data transfer restrictions in Europe constrain where telemetry may be processed and stored. ISO 27001 and IEC 62443 certifications have become table stakes for vendor qualification in regulated verticals. Stakeholders must evaluate whether their analytics architecture satisfies emerging jurisdictional data-sovereignty requirements before committing to multi-year platform contracts.
Market Dynamics
EU AI Act compliance timelines are compressing procurement cycles for predictive maintenance platforms, forcing telecom operators to accelerate vendor selection before enforcement deadlines activate in 2026.
Growth Catalysts
- EU AI Act enforcement:Telecom operators in Germany face mandatory algorithmic transparency requirements for network automation, driving managed analytics contracts.
- RBI cybersecurity directives:India's banking sector must deploy real-time traffic monitoring, creating concentrated demand for security analytics services.
- Cloud-native telemetry:Elastic SaaS observability stacks are displacing on-premises collectors as enterprises retire fixed-capacity infrastructure.
Market Restraints
- GDPR cross-border friction:EMA restrictions on telemetry data transfer force vendors to maintain redundant processing infrastructure across European jurisdictions.
- Specialized talent scarcity:Shortage of ML operations engineers with telco domain expertise extends deployment timelines for AIOps platforms.
- Legacy collector sunk costs:Enterprises with depreciated on-premises SNMP infrastructure delay cloud migration despite SaaS operational advantages.
Strategic Opportunities
- India enterprise corridor:TRAI QoS mandates and RBI cybersecurity rules create a concentrated procurement window for managed analytics providers.
- Zero-trust architecture convergence:Network performance monitoring is converging with security analytics, enabling unified platform positioning.
- ISO 27001 certification premium:Regulated verticals now require certified vendors, creating qualification barriers that favor established providers.
Industry Challenges
- Multi-vendor integration complexity:Enterprises operating hybrid Cisco-Juniper-Aruba environments struggle to normalize telemetry formats for unified dashboards.
- Skills gap in explainable AI:Network operations teams lack personnel capable of interpreting ML-driven anomaly alerts for root-cause analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Analytics Services Market |
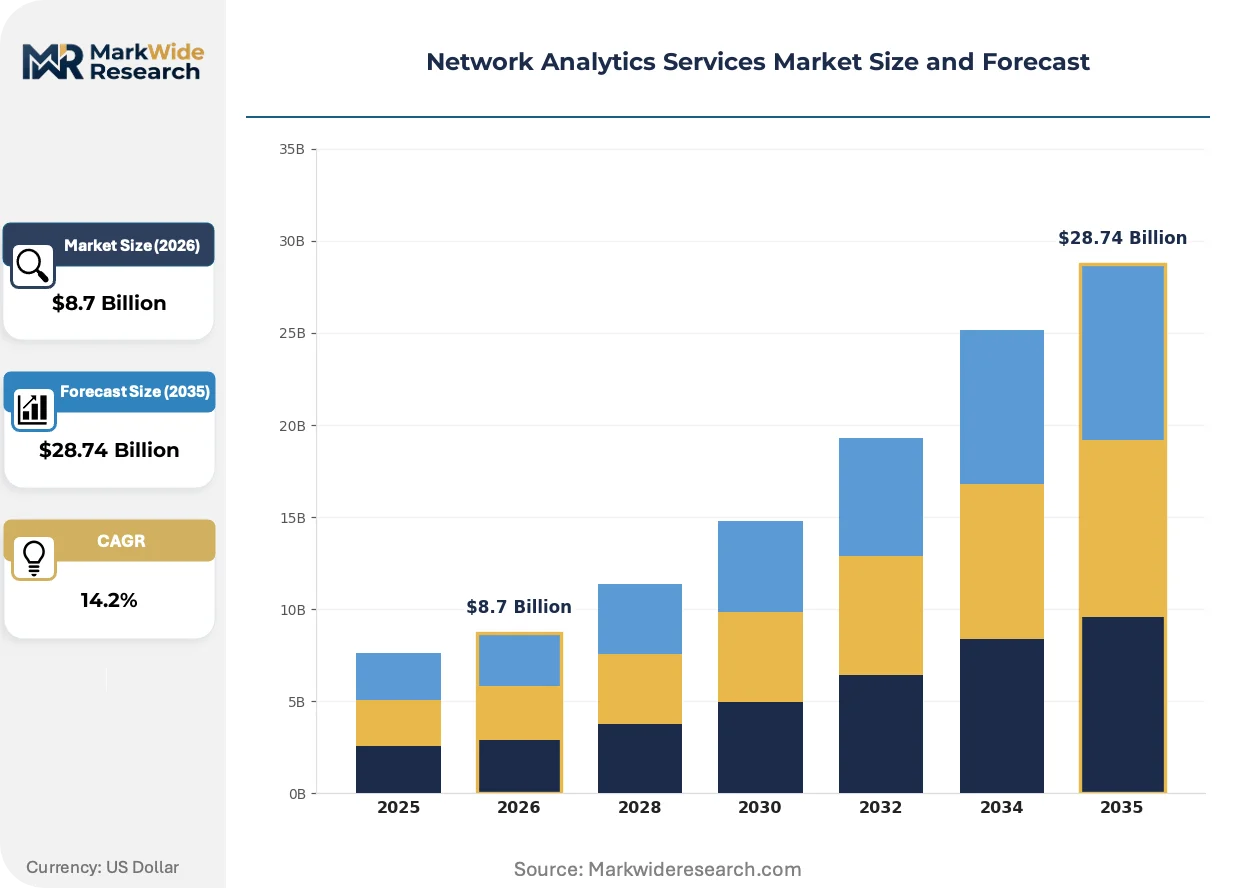
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Monitoring, Security Analytics, Traffic Analysis, User Behavior Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunication Providers, Enterprises, Government Agencies, Managed Service Providers Technology: Machine Learning, Artificial Intelligence, Big Data, Network Monitoring Tools |
| Companies Covered | Cisco Systems, Inc., IBM Corporation, Hewlett Packard Enterprise Development LP, Juniper Networks, Inc., Broadcom, Inc., Huawei Technologies Co., Ltd., Accenture, Fortinet, Inc., NETSCOUT Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Analytics Services Market Shifts & Advancements
Observability platforms are absorbing adjacent security functions as buyers consolidate vendor relationships, compressing the traditional separation between network operations and cybersecurity tooling.
Streaming telemetry protocols are converging with edge computing architectures, enabling millisecond-granularity analysis without centralized collector bottlenecks. Manufacturing facilities with time-sensitive networking requirements are adopting these architectures fastest. This convergence is compressing the latency-performance tradeoff that previously favored cloud-only processing.
FCC net neutrality restoration proceedings are reshaping how broadband providers instrument their networks for traffic management transparency. The proposed rules mandate detailed disclosure of congestion management practices. Service providers in the United States are responding by upgrading flow record collection systems to satisfy evidentiary requirements.
Enterprise technology procurement teams are consolidating vendor rosters around integrated observability stacks, displacing point-solution specialists. Fortune 500 infrastructure teams now require WAN, campus, and security analytics from unified platforms. This concentration is most visible in North American financial services, where CISO-NOC organizational alignment drives platform standardization.
Network Analytics Services Market Segmentation
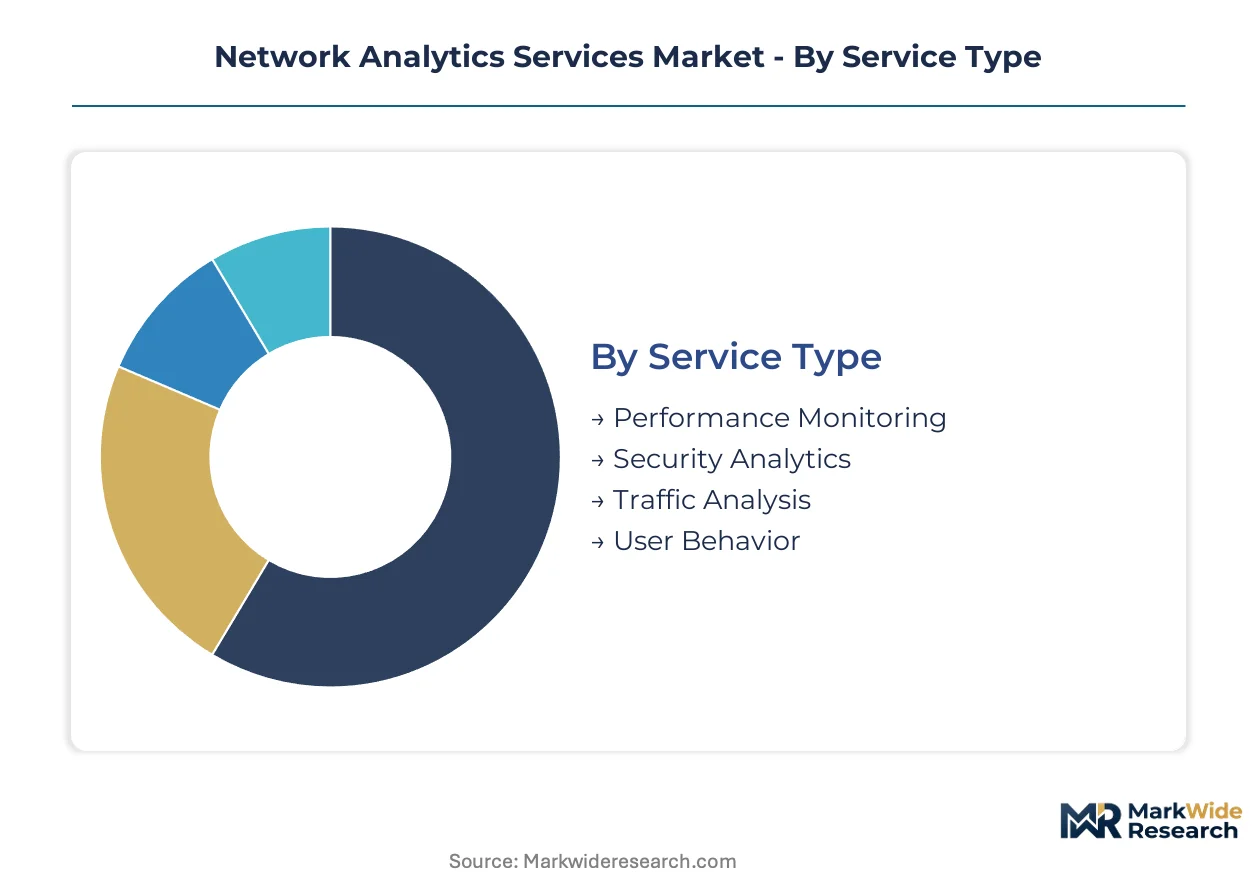
Network analytics services fragment across four functional dimensions that determine procurement patterns and vendor positioning. Deployment architecture and service type concentrate margin capture, while end-user verticals and underlying technology stacks dictate integration complexity and sales cycle duration.
Service Type:
Supply concentration among specialized platform vendors varies sharply across functional categories, with security and performance segments commanding premium engineering talent.
- Performance Monitoring:Real-time telemetry collection from routers, switches, and WAN links to detect latency, jitter, and packet loss anomalies. Deutsche Telekom and Bharti Airtel drive concentrated demand as they instrument 5G core networks for TRAI and EU AI Act compliance deadlines.
- Security Analytics:Correlation of flow records, DNS logs, and endpoint telemetry to identify breach indicators and policy violations. RBI cybersecurity directives for Indian banks and SEC disclosure rules for US financial services create urgent procurement windows for zero-trust visibility platforms.
- Traffic Analysis:Deep packet inspection and flow record aggregation for capacity planning and quality-of-service enforcement.
- User Behavior:Session-level tracking of application performance and network access patterns for digital experience optimization.
Security Analytics absorbs the bulk of installed capacity; Performance Monitoring is expanding most quickly.
Deployment Model:
Cost tier differentiation separates elastic consumption models from fixed-capital infrastructure, with cloud-native architectures displacing depreciated on-premises collectors.
- Cloud-Based:SaaS observability stacks with elastic telemetry ingestion and ML-driven anomaly detection delivered via subscription. North American financial services and Indian enterprise digitization corridors drive adoption as organizations retire fixed-capacity SNMP infrastructure.
- Hybrid:Split architectures retaining sensitive telemetry processing on-premises while leveraging cloud analytics for non-critical workloads. German automotive manufacturers and French healthcare networks favor this model under GDPR data-sovereignty constraints.
- On-Premises:Dedicated collector hardware and licensed software deployed within customer data centers.
- Edge Computing:Distributed processing nodes enabling millisecond-granularity analysis without centralized bottlenecks.
On-Premises retains legacy installed base; Cloud-Based is gaining share fastest.
End User:
Application intensity varies by vertical, with regulated industries demanding certified platforms and managed service providers seeking multi-tenant scalability.
- Telecommunication Providers:Nationwide backbone and 5G RAN instrumentation requiring carrier-grade scale and sub-second alerting. German operators under EU AI Act timelines and Indian providers responding to TRAI QoS mandates represent concentrated procurement clusters.
- Enterprises:Hybrid WAN, campus, and data center visibility for Fortune 500 technology procurement teams consolidating vendor rosters.
- Government Agencies:Classified network monitoring with sovereign data processing requirements.
- Managed Service Providers:Multi-tenant platforms delivering analytics-as-a-service to mid-market clients.
Telecommunication Providers anchor current revenue; Enterprises are climbing the fastest.
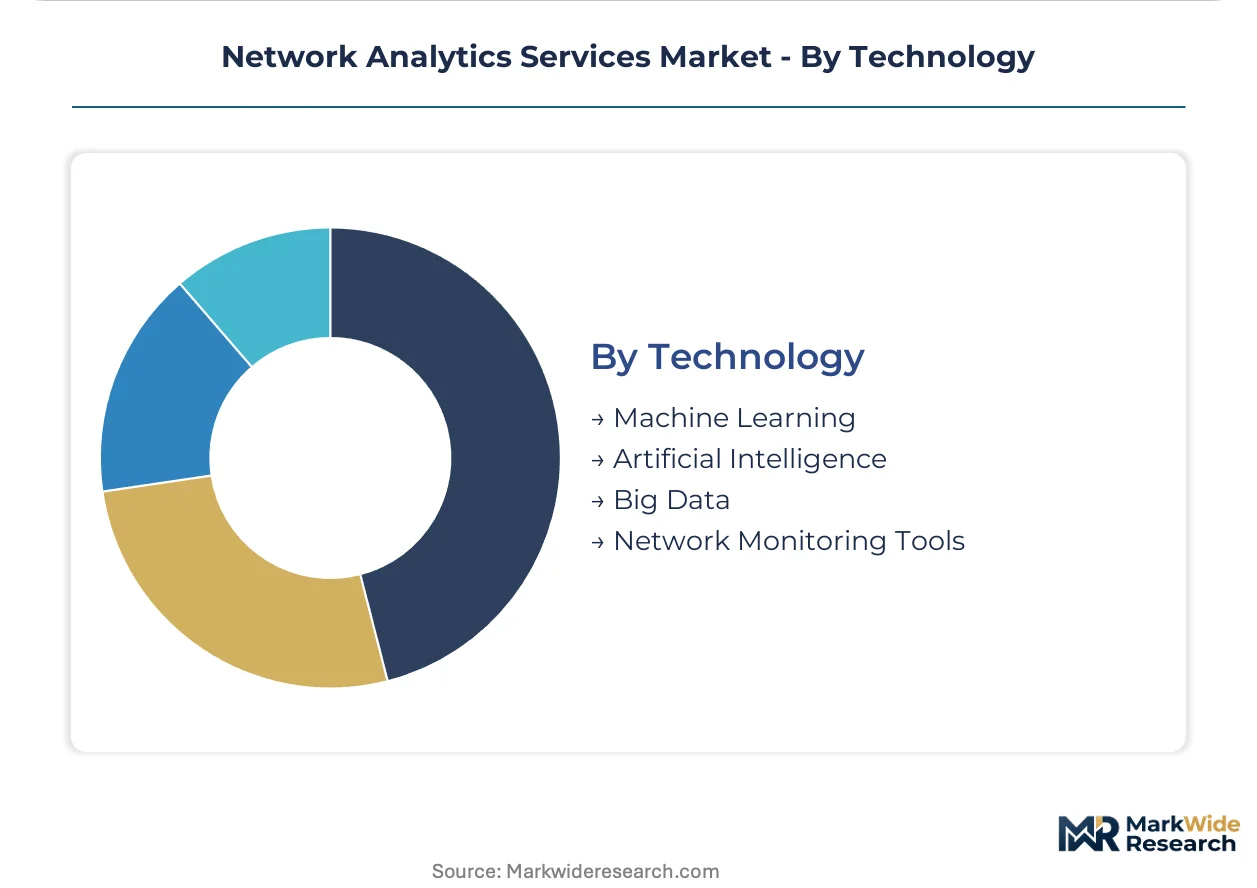
Technology:
Margin structure stratifies across maturity levels, with ML and AI platforms commanding implementation premiums while conventional monitoring tools face commoditization pressure.
- Machine Learning:Supervised and unsupervised models for anomaly detection, capacity forecasting, and root-cause analysis. Telco domain expertise scarcity extends deployment timelines for AIOps platforms at Vodafone and Reliance Jio.
- Artificial Intelligence:Natural language interfaces and automated remediation workflows reducing mean-time-to-resolution. Explainable AI requirements under EU AI Act compliance create qualification barriers favoring established vendors.
- Big Data:Distributed storage and stream processing architectures for petabyte-scale telemetry retention.
- Network Monitoring Tools:Conventional SNMP polling, flow collection, and synthetic testing without predictive capabilities.
Network Monitoring Tools dominate legacy deployments; Artificial Intelligence shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's data center corridor anchors North American demand for cloud-native observability platforms. German automotive telemetry clusters and Indian banking digitization hubs concentrate procurement velocity for predictive network analytics.
United States
FCC net neutrality restoration proceedings and SEC cybersecurity disclosure rules drive broadband provider instrumentation upgrades. Financial services CISO-NOC alignment in New York and Chicago accelerates unified platform consolidation. Dallas-Fort Worth data center clusters host elastic SaaS observability stacks for Fortune 500 hybrid WAN deployments.
Germany
EU AI Act compliance deadlines compress procurement cycles for telecom predictive maintenance platforms. BMW and Volkswagen manufacturing networks in Bavaria deploy edge-computing telemetry for time-sensitive networking. Frankfurt financial exchanges demand sub-millisecond anomaly detection under BaFin operational resilience mandates.
India
RBI cybersecurity directives and TRAI QoS mandates create concentrated procurement windows for managed analytics. Mumbai banking consortiums deploy real-time traffic monitoring for zero-trust architecture compliance. Bengaluru enterprise digitization corridors displace on-premises SNMP infrastructure with elastic cloud-native stacks.
China
MIIT data sovereignty requirements and GB standards for critical information infrastructure shape domestic vendor selection. Shenzhen telecom equipment manufacturers integrate streaming telemetry with 5G RAN instrumentation. Shanghai financial district deploys sovereign processing architectures under cross-border data transfer restrictions.
United Kingdom
FCA operational resilience rules and GDPR data localization requirements constrain telemetry processing locations. London fintech clusters demand certified ISO 27001 platforms for WAN visibility. Edinburgh government data centers retain sensitive flow analysis on-premises while leveraging cloud analytics for non-critical workloads.
Network Analytics Services Market Competitive Landscape
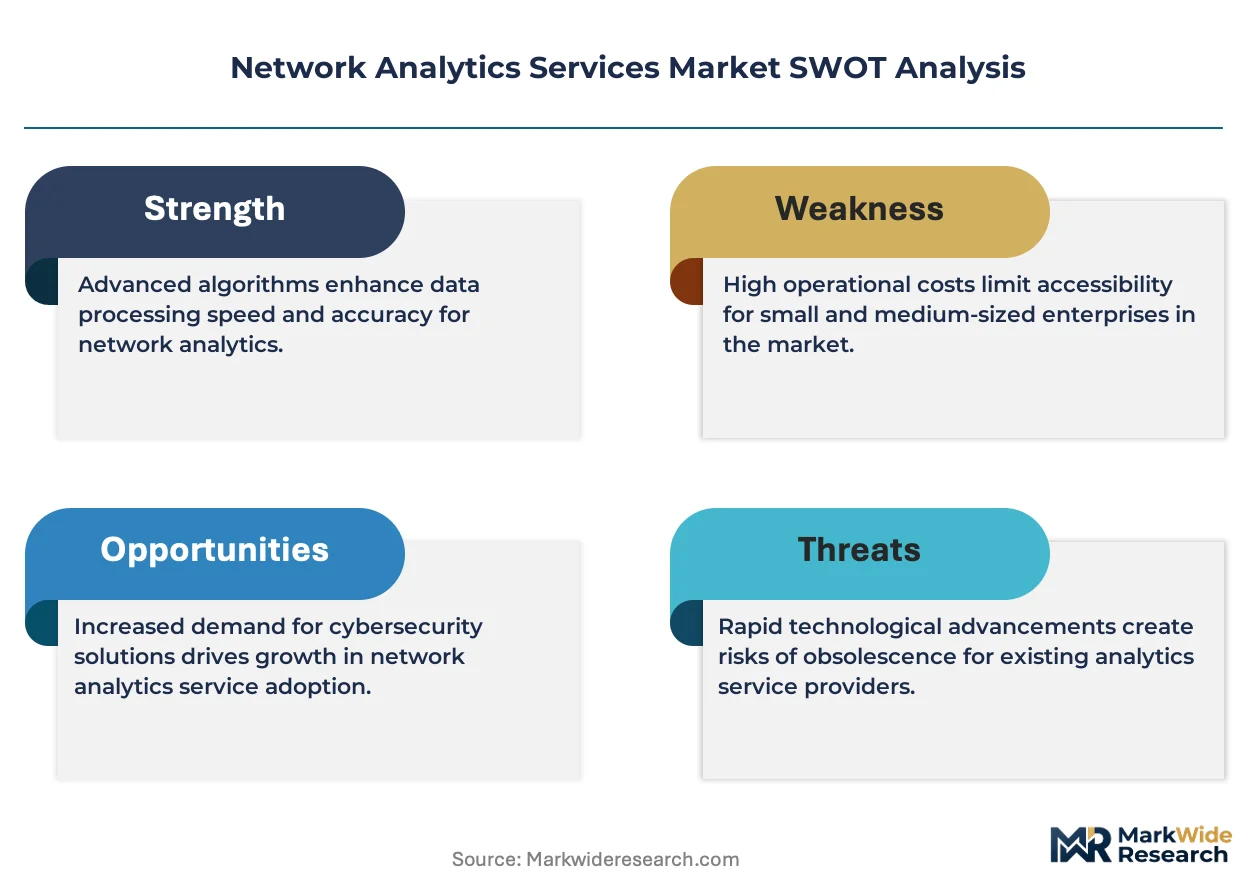
Established producers occupy the standard tier; emerging entrants pursue edge-native telemetry specialization. The vendor base stratifies across three maturity tiers: legacy infrastructure incumbents with depreciated collector installed bases, cloud-native challengers with elastic SaaS architectures, and telecom-specialist providers with carrier-grade scale credentials. Strategic archetypes include platform consolidators anchoring hybrid WAN observability, security convergence specialists absorbing adjacent cybersecurity functions, and managed service providers delivering multi-tenant analytics-as-a-service. Dominant competitive moves encompass vertical integration into streaming telemetry hardware and strategic partnerships with hyperscale cloud providers for elastic infrastructure.
Within the platform consolidator tier, Cisco Systems and IBM Corporation exemplify hybrid-cloud observability positioning. Juniper Networks occupies a position among telecom-specialist providers with AI-driven campus and branch analytics. These three entities represent distinct competitive archetypes: infrastructure incumbents leveraging installed base relationships, services conglomerates integrating AIOps with container orchestration platforms, and networking pure-plays dominating service provider procurement cycles.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| IBM Corporation |
| Hewlett Packard Enterprise Development LP |
| Juniper Networks, Inc. |
| Broadcom, Inc. |
| Huawei Technologies Co., Ltd. |
| Accenture |
| Fortinet, Inc. |
| NETSCOUT Systems, Inc. |
| Others |
Supply & Pricing Matrix
Semiconductor memory pricing indices cascade through network analytics hardware supply chains, compressing margins on on-premises collector appliances while elastic SaaS consumption models capture residual value through subscription tiering. Cloud-native observability vendors absorb this input cost volatility through usage-based metering, whereas appliance-dependent providers face margin pressure from fixed-cost legacy infrastructure.
Pricing Analysis
Warranty bundling separates premium-tier managed analytics contracts from self-service SaaS subscriptions, with ISO 27001-certified platforms commanding 40-60% uplifts over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by telemetry retention depth, ML inference volume, and after-hours support coverage. Pricing pressure stems from hyperscaler-backed observability entrants subsidizing customer acquisition through infrastructure cross-leverage. Fortune 500 technology procurement teams exhibit lowest price sensitivity due to consolidated vendor roster mandates, while mid-market enterprises drive hardest bargain compression.
Supply Chain Analysis
ISO 27001 and IEC 62443 certification gating constrains vendor qualification pools, filtering supply concentration toward established platform providers with audit-ready compliance documentation. Hardware component sourcing concentrates in Taiwan for semiconductors, China for edge-computing enclosures, and Ireland for European data residency-compliant cloud infrastructure. Supply chain risk centers on single-source vulnerability for carrier-grade telemetry processing ASICs. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by hyperscale cloud marketplaces for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The network analytics market occupies a technology-transition phase as streaming telemetry protocols displace legacy SNMP polling architectures, forcing vendor repositioning across deployment models.
For Market Incumbents: Deepen vertical integration into edge-computing hardware to defend against hyperscaler observability encroachment. Incumbents must accelerate Red Hat OpenShift-native certification investments to maintain platform stickiness as container orchestration becomes default infrastructure. Threat substitution from elastic SaaS observability stacks demands captive supply of millisecond-granularity processing silicon. For New Entrants and Emerging Players: Capture the India enterprise digitization corridor where RBI cybersecurity directives and TRAI QoS mandates create urgent procurement windows without entrenched incumbent relationships. White-space targets include sovereign data-processing deployments for German automotive manufacturers under GDPR constraints. Go-to-market angle should emphasize EU AI Act explainable-AI compliance as a qualification wedge against black-box ML incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor telecom-specialist analytics providers with carrier-grade scale credentials in European jurisdictions facing EU AI Act enforcement compression. Long-term viability across the projection horizon hinges on cloud-native architecture migration completion. Acquisition target archetype: edge-native telemetry specialists with automotive manufacturing facility deployments. Signal to watch: hyperscaler capex disclosure shifts toward sovereign cloud infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies WAN, campus, and security analytics under single Cisco ThousandEyes architecture. |
| Strategic Partnership | Hyperscale cloud alliances enable elastic SaaS observability stacks for Fortune 500 procurement. |
| Acquisition of Specialist Firm | Edge-computing telemetry providers accelerate millisecond-granularity manufacturing facility deployments. |
| Geographic Expansion | India enterprise corridor entry captures RBI-mandated banking sector security analytics demand. |
| Product Launch | EU AI Act-compliant explainable AI modules satisfy BaFin operational resilience mandates in Frankfurt. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, telecom operator RFP patterns, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with network operations center directors, CISO-NOC alignment leads, cloud infrastructure procurement officers, and managed service provider platform engineers. Secondary validation drew from SEC cybersecurity disclosure filings, TRAI QoS compliance reports, EU AI Act implementation guidance, and hyperscaler earnings call transcripts. Bottom-up telemetry volume modeling and top-down enterprise IT spend allocation triangulated market sizing across deployment architectures.
Input-output matrices mapped subscription revenue flows against elastic infrastructure costs, segmentation dimensions spanned service type, deployment model, end-user vertical, and underlying technology stack across the analysis window. CAGRs were derived from curve-fitting observed procurement cycle compression against regulatory deadline enforcement patterns. Industry-specific forecast inputs included 5G RAN instrumentation timelines and zero-trust architecture mandate adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement severity and hyperscaler pricing aggression. Model assumptions reflect current regulatory trajectories without anticipating unannounced mandate delays. A model refresh is warranted upon material change in FCC net neutrality restoration proceedings or RBI cybersecurity directive implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Social Business Intelligence Market
Analytics
APAC Data Wrangling Market
Analytics
Lead Intelligence Software Market
Analytics
Connected Device Analytics Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Data Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Sweden ICT Market
Analytics
Cyprus ICT Market
Analytics
Cognitive Analytics Solutions Market
Analytics
Global Telco Data Monetization Market
Analytics
Geospatial Analytics Market