
 Global Data Prep Market | 2026-2036
Global Data Prep Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Prep Market Analysis
Open-source Apache Spark is recalibrating total cost of ownership for enterprise data pipelines, compressing pricing power for legacy ETL vendors. IBM Corporation sustains deep mainframe integration expertise that defends its position in regulated industries. Microsoft Corporation leverages Azure-native connectivity to dominate cloud-born deployments. Alteryx Inc. specializes in code-adjacent workflows that occupy the mid-market analyst segment.
Data preparation encompasses the technical processes of profiling, cleansing, transforming, and structuring raw data into analysis-ready formats through automated pipelines operating at petabyte scale with sub-minute latency SLAs. Its primary commercial purpose is eliminating the engineering bottleneck between data ingestion and business intelligence consumption. Cloud-based Solutions capture the dominant margin pool as recurring SaaS revenue displaces perpetual license models. Among Use Case segments, Data Governance is expanding fastest as GDPR enforcement and SEC climate disclosure rules mandate auditable lineage. Hybrid Solutions remain structurally important for enterprises navigating sovereign data requirements across jurisdictions.
The EU AI Act imposes conformity assessments on high-risk automated decision systems, directly expanding demand for traceable data provenance tools. The SEC's cybersecurity disclosure rules and India's DPDP Act create parallel compliance obligations that favor platforms with built-in policy enforcement. China's PIPL and GB standards add a third regulatory vector for multinationals operating across data localization boundaries. Stakeholders must evaluate whether their current data prep architecture can absorb emerging algorithmic accountability mandates without wholesale platform replacement.
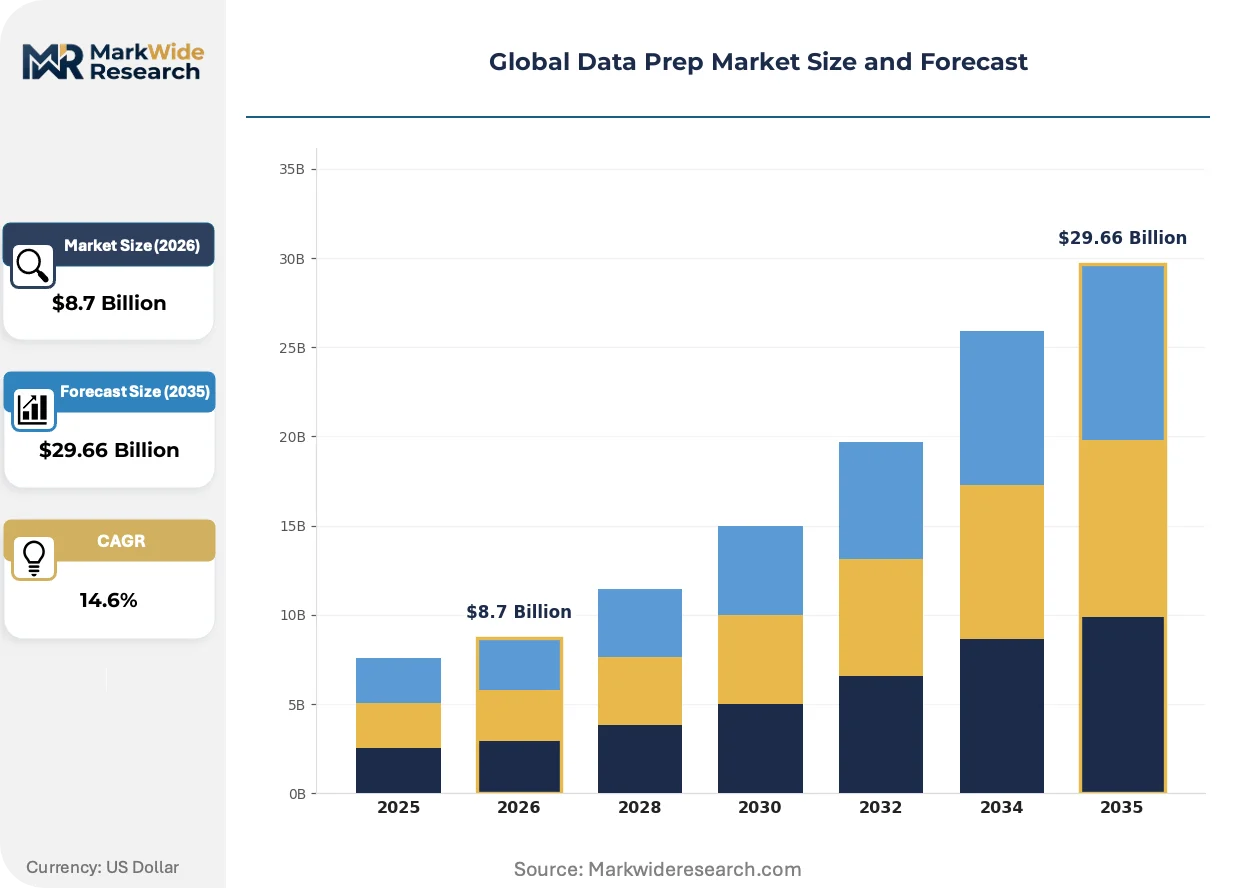
Market Dynamics
Apache Spark's open-source architecture is compressing pricing power across enterprise data pipelines while regulatory mandates from the EU AI Act force platform modernization investments.
Growth Catalysts
- EU AI Act Conformity Assessments:High-risk automated decision systems now require traceable data provenance, expanding demand for governance-integrated preparation platforms in financial services and healthcare.
- Self-Service Analytics Expansion:Financial services firms are deploying code-adjacent workflows that eliminate engineering bottlenecks between ingestion and business intelligence consumption.
- Cloud Migration Mandates:Germany's BSI technical guidelines and India's MeitY cloud-first policies are accelerating displacement of perpetual license models with recurring SaaS revenue structures.
Market Restraints
- Mainframe Integration Inertia:Regulated industries face structural switching costs from decades-old ETL architectures, particularly in US banking and insurance sectors.
- Input Talent Scarcity:Data engineering skill shortages in India and Eastern Europe are inflating implementation costs for hybrid cloud deployments.
- Sovereign Data Fragmentation:China's PIPL localization requirements and Russia's data residency laws force redundant platform instances, duplicating capital expenditure.
Strategic Opportunities
- SEC Climate Disclosure Alignment:Auditable lineage tools that map carbon data from source to report are capturing premium pricing in US industrial and energy verticals.
- Generative AI Data Pipelines:Convergence of large language model training workflows with traditional BI preparation is opening new product categories for unstructured data structuring.
- Brazilian Enterprise Modernization:Underpenetrated mid-market manufacturers in São Paulo and Minas Gerais present first-mover advantages for cloud-native deployment models.
Industry Challenges
- GDPR-CCPA Reconciliation Complexity:Multinationals operating across EU and California jurisdictions face conflicting deletion and portability mandates that strain policy engine architectures.
- Petabyte-Scale Latency Engineering:Sub-minute SLA requirements for streaming pipelines demand specialized hardware configurations that extend sales cycles and certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Prep Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Solutions, Hybrid Solutions, Data Integration Tools End User: Large Enterprises, SMEs, Government Agencies, Educational Institutions Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Local Servers Use Case: Data Analysis, Data Cleaning, Data Transformation, Data Governance |
| Companies Covered | Informatica LLC, IBM Corporation, SAS Institute Inc., Alteryx Inc., SAP SE, Microsoft Corporation, Tableau Software LLC, Qlik, TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Prep Market Emerging Trajectories
Automated pipeline orchestration is displacing manual transformation workflows while regulatory fragmentation across jurisdictions forces modular compliance architectures.
Generative AI-powered data profiling is automating schema inference and anomaly detection at ingestion points. US healthcare payers and pharmaceutical manufacturers are deploying these tools to compress preparation cycles for clinical trial datasets. The technology is automating previously manual quality assurance steps that consumed 40% of data engineering hours.
REACH chemical substance tracking extensions in Europe now mandate lineage documentation for supply chain emissions data. Industrial chemical manufacturers must retrofit preparation platforms to capture cradle-to-gate carbon intensity. German automotive suppliers are responding by embedding ISO 14044-compliant calculation engines directly into their data pipelines.
Subscription-based consumption models are displacing capacity-licensed procurement in mid-market deployments. Value-added resellers and systems integrators in India and Southeast Asia are unbundling implementation services from software licensing. This shift is most visible among Mumbai and Bangalore-based analytics consultancies serving domestic fintech clients.
Global Data Prep Market Segmentation
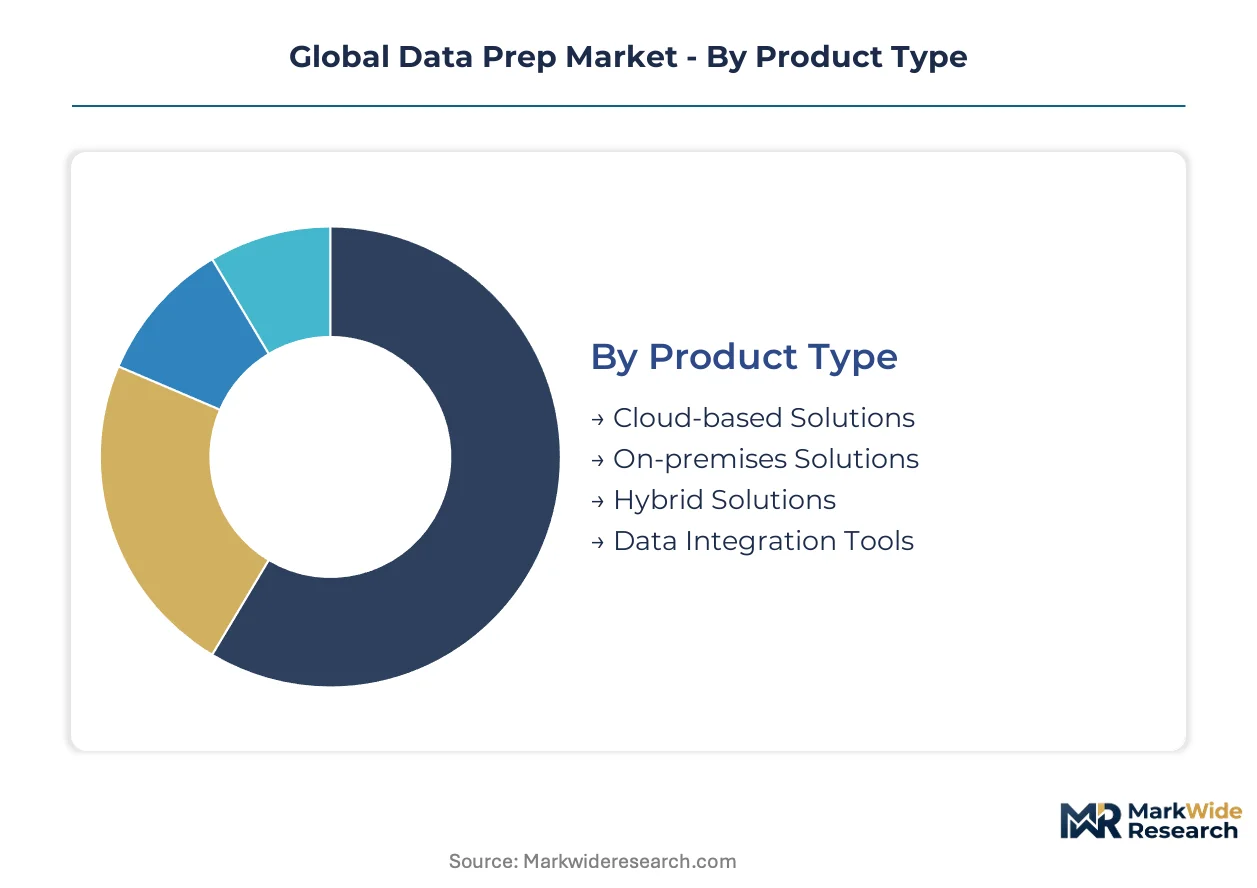
Data preparation platforms fragment across infrastructure maturity, organizational scale, and compliance intensity. Each segmentation axis reveals distinct procurement patterns and vendor specialization strategies that shape competitive positioning.
Product Type:
Customization versus standardization tension peaks in delivery architecture, where cloud-native elasticity competes with governed on-premises control for enterprise preference.
- Cloud-based Solutions:Multi-tenant SaaS architectures with API-native connectivity and auto-scaling compute pools. Demand concentrates among US fintechs and German automotive suppliers modernizing under BSI cloud guidelines, driven by EU AI Act traceability mandates that favor centralized governance layers.
- On-premises Solutions:Air-gapped deployments with dedicated hardware stacks for sovereign data requirements. US banking and insurance sectors maintain these installations due to mainframe integration inertia and FedRAMP-adjacent security postures.
- Hybrid Solutions:Policy-orchestrated workloads spanning private and public infrastructure. India's MeitY cloud-first policies and China's PIPL localization rules force redundant instances for multinationals operating across data residency boundaries.
- Data Integration Tools:Specialized middleware for legacy system connectivity. Embedded calculation engines serve German chemical manufacturers tracking REACH-compliant supply chain emissions.
Leading the category by volume: Cloud-based Solutions. Growing fastest: Hybrid Solutions.
End User:
Procurement sophistication escalates with organizational scale, from centralized IT governance in multinationals to shadow-IT proliferation in mid-market segments.
- Large Enterprises:Centralized data engineering functions with petabyte-scale pipelines and sub-minute latency SLAs. US healthcare payers and pharmaceutical manufacturers deploy generative AI profiling tools to compress clinical trial preparation cycles.
- SMEs:Subscription-based consumption with unbundled implementation services. Mumbai and Bangalore-based analytics consultancies serve domestic fintech clients through value-added reseller channels.
- Government Agencies:Sovereign cloud mandates with certification-heavy procurement. India's DPDP Act and SEC cybersecurity disclosure rules create parallel compliance obligations favoring platforms with built-in policy enforcement.
- Educational Institutions:Research-oriented deployments with grant-funded infrastructure. Open-source Apache Spark adoption recalibrates total cost of ownership for academic data science workflows.
Dominating procurement value: Large Enterprises. Expanding most quickly: SMEs.
Deployment:
Latency requirements and data gravity determine infrastructure placement, with streaming workloads favoring edge proximity and archival workloads accepting centralized consolidation.
- Public Cloud:Shared infrastructure with consumption-based metering. Azure-native connectivity dominates cloud-born deployments through Microsoft Corporation's enterprise relationships.
- Private Cloud:Dedicated single-tenant environments with custom security postures. German BSI technical guidelines accelerate displacement of perpetual license models in regulated industries.
- Hybrid Cloud:Workload portability across sovereignty boundaries. Russian data residency laws and China's PIPL force redundant capital expenditure for multinationals.
- Local Servers:Bare-metal installations for ultra-low-latency requirements. Sub-minute SLA engineering demands specialized hardware configurations that extend sales cycles.
Highest revenue concentration: Public Cloud. Steepest expansion trajectory: Hybrid Cloud.
Use Case:
Functional specialization deepens as regulatory pressure elevates provenance documentation from operational convenience to legal necessity.
- Data Analysis:Business intelligence consumption layers with self-service visualization. Code-adjacent workflows eliminate engineering bottlenecks between ingestion and analyst consumption in financial services.
- Data Cleaning:Automated anomaly detection and quality assurance. Generative AI-powered profiling automates schema inference at ingestion points, compressing preparation cycles.
- Data Transformation:ETL pipeline orchestration with lineage tracking. ISO 14044-compliant calculation engines embed directly into German automotive supplier pipelines for carbon intensity mapping.
- Data Governance:Auditable provenance with policy enforcement. GDPR enforcement and SEC climate disclosure rules mandate traceable lineage, expanding demand fastest in this segment.
Widest functional adoption: Data Analysis. Gaining share fastest: Data Governance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for data preparation platforms concentrates in the United States, Germany, and India as enterprises build centralized data engineering capabilities. Financial services firms across these markets are expanding adoption of self-service analytics platforms. Cloud migration mandates under the EU AI Act and similar frameworks are accelerating platform modernization investments.
United States
Healthcare payers and pharmaceutical manufacturers deploy generative AI profiling tools to compress clinical trial preparation cycles. SEC cybersecurity disclosure rules create compliance obligations favoring platforms with built-in policy enforcement. The Boston biotech cluster and New York financial services corridor drive concentrated procurement of cloud-native solutions.
Germany
Automotive suppliers embed ISO 14044-compliant calculation engines into pipelines for carbon intensity mapping. BSI technical guidelines accelerate displacement of perpetual license models with recurring SaaS structures. The Stuttgart industrial basin and Munich technology corridor host dense concentrations of hybrid cloud deployments.
India
Mumbai and Bangalore-based analytics consultancies serve domestic fintech clients through value-added reseller channels. MeitY cloud-first policies and the DPDP Act create parallel compliance obligations for data governance platforms. The Hyderabad pharmaceutical corridor expands demand for traceable data provenance tools.
China
Multinationals operating across data localization boundaries face redundant platform instances under PIPL requirements. GB standards and dual carbon goals mandate auditable lineage for supply chain emissions tracking. The Yangtze River Delta manufacturing belt drives specialized middleware procurement for legacy system connectivity.
Brazil
Underpenetrated mid-market manufacturers in São Paulo and Minas Gerais present first-mover advantages for cloud-native deployment models. ANVISA pharmaceutical traceability requirements expand demand for governance-integrated preparation platforms. The São Paulo financial services corridor accelerates self-service analytics adoption among domestic banks.
Global Data Prep Market Vendor Landscape
Platform consolidation dominates the current landscape as vendors absorb specialized tooling into unified suites. The vendor base separates into three tiers: hyperscale cloud providers with native integration advantages, legacy ETL specialists defending mainframe-connected accounts, and code-adjacent workflow vendors capturing mid-market analyst segments. Strategic archetypes include governance-first platforms targeting regulated industries, elasticity-first architectures serving cloud-born enterprises, and hybrid orchestration specialists navigating sovereign data requirements. M&A activity and API-native ecosystem expansion represent the dominant competitive vectors reshaping market structure.
Within the legacy integration tier, IBM Corporation and Informatica LLC occupy positions defending regulated industry accounts through deep mainframe connectivity. Microsoft Corporation anchors the cloud-native vector through Azure-native enterprise relationships. Alteryx Inc. exemplifies the code-adjacent workflow archetype that eliminates engineering bottlenecks for mid-market financial services analysts.
| Leading Market Players |
|---|
| Informatica LLC |
| IBM Corporation |
| SAS Institute Inc. |
| Alteryx Inc. |
| SAP SE |
| Microsoft Corporation |
| Tableau Software LLC |
| Qlik |
| TIBCO Software Inc. |
| Others |
Supply Flow & Price Mechanics
Large enterprise procurement teams in US healthcare and German automotive sectors anchor pricing power toward subscription-based SaaS tiers with governance-integrated feature bundles. Their concentrated buying volume compresses margin elasticity for vendors while mandating sub-minute latency SLAs that feed hardware configuration costs back into total contract value.
Pricing Analysis
Volume concentrates in cloud-native SaaS tiers while margin pools in hybrid deployments with sovereign data orchestration. Price differentiation hinges on ISO 27001 certification tier and customization depth for legacy mainframe connectivity. Cost compression in mid-market segments intensifies because open-source Apache Spark recalibrates total cost of ownership benchmarks. SMEs exhibit highest price sensitivity; regulated financial services firms show lowest, accepting premium positioning for EU AI Act traceability compliance.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India form hub-and-spoke patterns for cloud infrastructure provisioning. Compute hardware draws from Taiwan, South Korea, and domestic US fabrication. Open-source middleware and API-native connectivity components rest on Apache Foundation and cloud hyperscaler ecosystems. Single-source vulnerability concentrates in specialized semiconductor supply for edge-deployment latency engineering. Distribution runs through value-added resellers in Mumbai and Bangalore serving domestic fintech clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over data lineage engines and mainframe connectivity layers determines sustainable margin capture. Players are pursuing downstream integration into managed services and compliance consulting to lock in recurring revenue.
For Market Incumbents: To counter open-source Apache Spark compression on pricing power, deepen captive supply of governance-integrated calculation engines and expand certification investment for FedRAMP-adjacent security postures in US banking. Acquire specialized middleware vendors defending mainframe-connected accounts against displacement.
For New Entrants and Emerging Players: Begin with underpenetrated mid-market manufacturers in São Paulo and Minas Gerais, where cloud-native deployment models face limited incumbent saturation. Target generative AI-powered data profiling for unstructured clinical trial datasets as the most penetrable application. Pursue channel partnerships with Bangalore-based analytics consultancies unbundling implementation from licensing.
For Investors and Strategic Acquirers: The window for entry favors governance-first platforms with pre-built EU AI Act conformity assessment modules. Long-term viability centers on algorithmic accountability mandate absorption without platform replacement. Watch SEC climate disclosure enforcement intensity as the inflection signal for auditable lineage tool premium pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-native connectivity consolidates cloud-born enterprise deployments through Microsoft Corporation's relationships. |
| Acquisition of Specialist Firm | Middleware vendors with REACH-compliant carbon calculation engines capture German automotive supplier procurement. |
| Geographic Expansion | Cloud-first policies under India's MeitY accelerate SaaS displacement of perpetual licenses in Mumbai fintech. |
| Strategic Partnership | Reseller channel control through Bangalore consultancies unbundles implementation from software licensing. |
| Product Launch | Generative AI profiling tools automate schema inference for US healthcare clinical trial preparation cycles. |
Methodological Framework
Independent corroboration across data engineering executives, cloud procurement officers, compliance leads, and systems integrators underwrites the qualitative findings. Primary fieldwork combined CTO interviews at US healthcare payers, platform engineering leads at German automotive suppliers, and channel partner discussions in Mumbai and Bangalore. Secondary validation drew from SEC cybersecurity disclosure filings, EU AI Act conformity assessment guidance, MeitY cloud policy circulars, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing from SaaS revenue recognition patterns.
Comparable-period anchoring used historical subscription renewal rates and migration timeline data across the projection horizon. The analytical framework modeled deployment architecture, organizational scale, compliance intensity, and regional regulatory cluster as segmentation dimensions. CAGRs derived from elasticity-adjusted adoption curves incorporating EU AI Act enforcement phase-ins and SEC climate disclosure rulemakings. Industry-specific inputs included petabyte-scale pipeline latency requirements and mainframe integration inertia coefficients for US banking.
Underlying measurement precision varies by segment; cloud-native SaaS deployments carry tighter precision than hybrid sovereign data configurations. Forecasts reflect documented assumptions around regulatory enforcement timelines and open-source competitive intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Crowd Analytics Market
Analytics
Analytics Sandbox Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Global Business Intelligence and Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Customer Journey Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Data Analysis Tools Market
Analytics
Contact Center Intelligence Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Assortment Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Legal Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Procurement Analytics Market