
 UK Geospatial Analytics Market | 2026-2036
UK Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Geospatial Analytics Market Insights
Geospatial data science talent scarcity is bifurcating the competitive landscape between firms that cultivate in-house capability and those dependent on vendor ecosystems. Hexagon leverages its sensor-to-software stack to dominate precision measurement workflows across UK utilities. Bluesky International Ltd. anchors its position through proprietary aerial survey coverage of British urban corridors. IQGeo Group competes by specializing in telecom network geospatial management for fibre and 5G rollouts.
Geospatial analytics encompasses the computational processing of location-referenced data through coordinate-based algorithms, spatial statistics, and remote sensing integration to generate actionable intelligence for asset management, risk assessment, and operational planning. Platforms typically process raster and vector datasets with sub-metre accuracy requirements, enabling real-time decision support for infrastructure operators. Cloud Computing deployments are capturing the fastest expansion as UK agencies migrate from legacy on-premise GIS installations to elastic, API-first architectures. Environmental Monitoring applications sustain premium pricing due to the Environment Agency's mandated floodplain digitisation and biodiversity net-gain tracking requirements. Government Agencies remain the dominant end-user segment, though Agriculture Sector adoption is accelerating through DEFRA-backed precision farming subsidies.
The Geospatial Commission's National Geospatial Strategy shapes procurement standards across Whitehall departments, while the UK Space Agency's Earth observation funding programs steer R&D priorities toward domestic satellite downstream capabilities. Ordnance Survey's Public Sector Geospatial Agreement mandates open data licensing terms that reshape vendor business models and platform interoperability requirements. Stakeholders must monitor how the UK's emerging AI regulatory framework intersects with automated geospatial inference tools to anticipate compliance burdens on algorithmic land-use classification systems.
Market Dynamics
The Environment Agency's flood risk mapping mandates are forcing infrastructure operators to replace legacy GIS installations with real-time, cloud-native platforms that integrate satellite-derived terrain data with operational sensor networks.
Growth Catalysts
- Geospatial Commission Mandate:The National Geospatial Strategy compels Whitehall departments to adopt interoperable location intelligence standards, creating baseline demand across transport, housing, and environmental agencies.
- Offshore Energy Corridor Expansion:The East Anglia offshore wind zone requires sub-metre accuracy seabed surveys and cable route optimization, pulling precision measurement workflows from utilities into marine construction.
- Smart City Procurement:London's congestion charging and low-emission zone enforcement systems generate recurring platform upgrades as boroughs integrate real-time vehicle tracking with urban planning databases.
Market Restraints
- Specialist Talent Scarcity:The bifurcation between firms with in-house geospatial data science capability and vendor-dependent operators limits execution speed for complex spatial algorithm deployments.
- Legacy System Entrenchment:Ordnance Survey's historic dominance in British mapping creates switching friction as agencies negotiate data licensing transitions under the Public Sector Geospatial Agreement.
- Sensor Hardware Costs:Aerial LiDAR and hyperspectral imaging equipment require capital commitments that constrain mid-tier survey firms from competing on data freshness with Bluesky International's proprietary coverage.
Strategic Opportunities
- DEFRA Precision Farming Subsidies:The Agriculture Sector's accelerating adoption of variable-rate application mapping creates whitespace for platforms processing soil moisture and yield data at field-scale resolution.
- AI-Geospatial Convergence:Automated land-use classification tools intersect with the UK's emerging AI regulatory framework, positioning first-movers to shape compliance standards for algorithmic spatial inference.
- Telecom Network Modernization:IQGeo Group's fibre and 5G rollout specialization demonstrates how telecom asset geospatial management can expand into utility and transport infrastructure verticals.
Industry Challenges
- Interoperability Certification Burden:Vendors must validate platform compliance against Ordnance Survey's open data licensing terms while maintaining proprietary feature differentiation.
- Cloud Migration Complexity:Elastic API-first architectures demand retraining of GIS teams accustomed to on-premise Esri installations, compressing implementation timelines for public sector procurement cycles.
- Biodiversity Net-Gain Tracking:The Environment Agency's habitat offset monitoring requirements force developers to integrate ecological survey data with construction planning workflows, straining legacy project management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Geospatial Analytics Market |
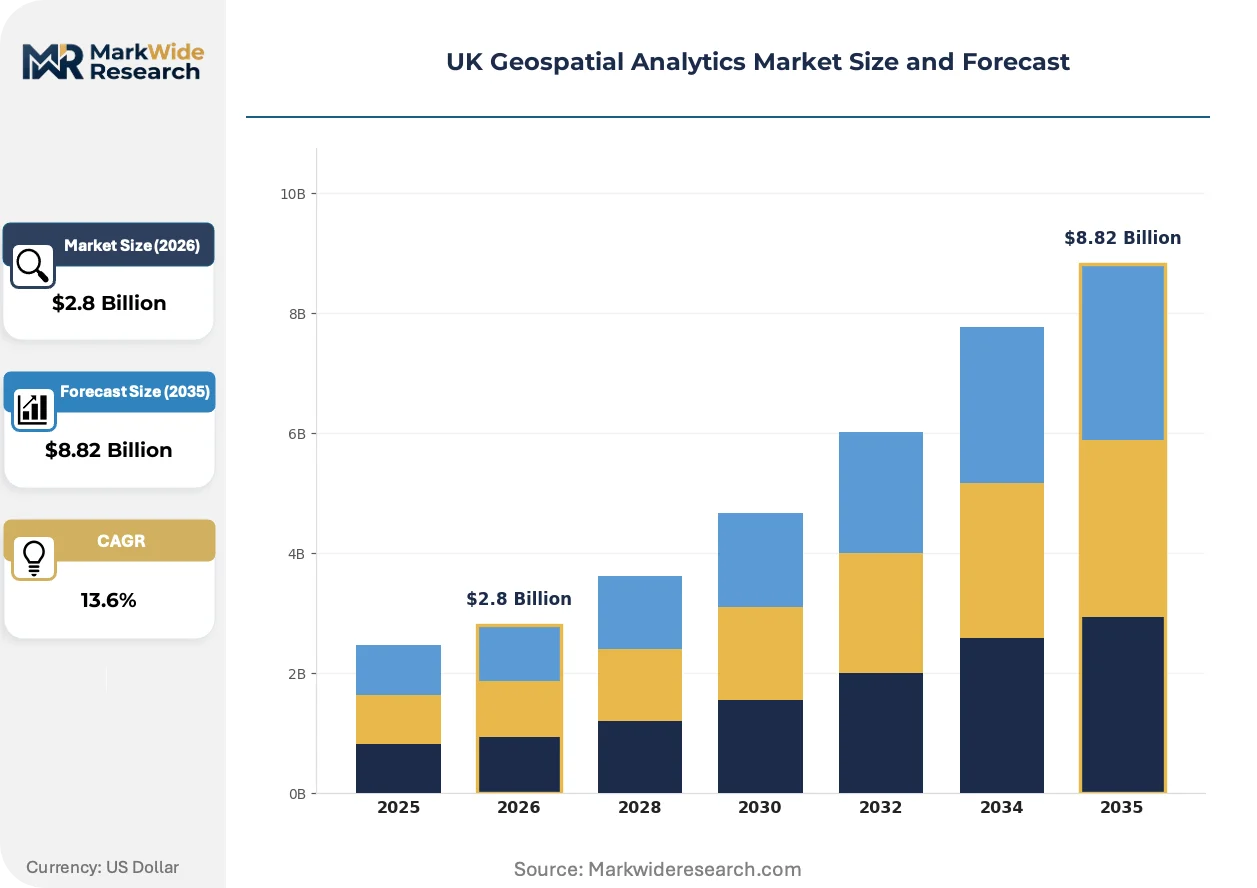
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Transportation Management, Land Use Technology: GIS, Remote Sensing, Spatial Data Analysis, Cloud Computing End User: Government Agencies, Mining Industry, Agriculture Sector, Retail Businesses Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Platforms |
| Companies Covered | Hexagon, Trimble, ESRI, Bentley Systems, General Electric, IQGeo Group, Bluesky International Ltd., Oracle Corporation, SAS Institute, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Geospatial Analytics Market Trends and Innovations
Cloud-native geospatial platforms are compressing the latency between raw sensor capture and operational decision support, while regulatory pressure on environmental disclosure accelerates demand for automated spatial analytics.
Digital twin architectures are supplanting static map visualizations as the primary interface for infrastructure operators. Network utilities in England deploy real-time 3D facility models that synchronize SCADA feeds with georeferenced asset registries. This convergence is compressing maintenance scheduling from quarterly cycles to condition-triggered interventions.
The Environment Agency's mandated floodplain digitisation is tightening accuracy requirements for terrain models used in planning applications. Developers now face rejection risks for submissions lacking LiDAR-verified elevation data at 25cm vertical resolution. Residential and commercial construction in Thames Gateway corridors bears the heaviest compliance burden.
Subscription-based platform access is displacing perpetual license purchases among local authorities. Procurement teams in Greater Manchester and West Midlands Combined Authorities now prioritize operational expenditure models that bundle software, data refreshes, and technical support. This shift pressures traditional GIS vendors to restructure revenue recognition and customer success functions.
UK Geospatial Analytics Market Segmentation
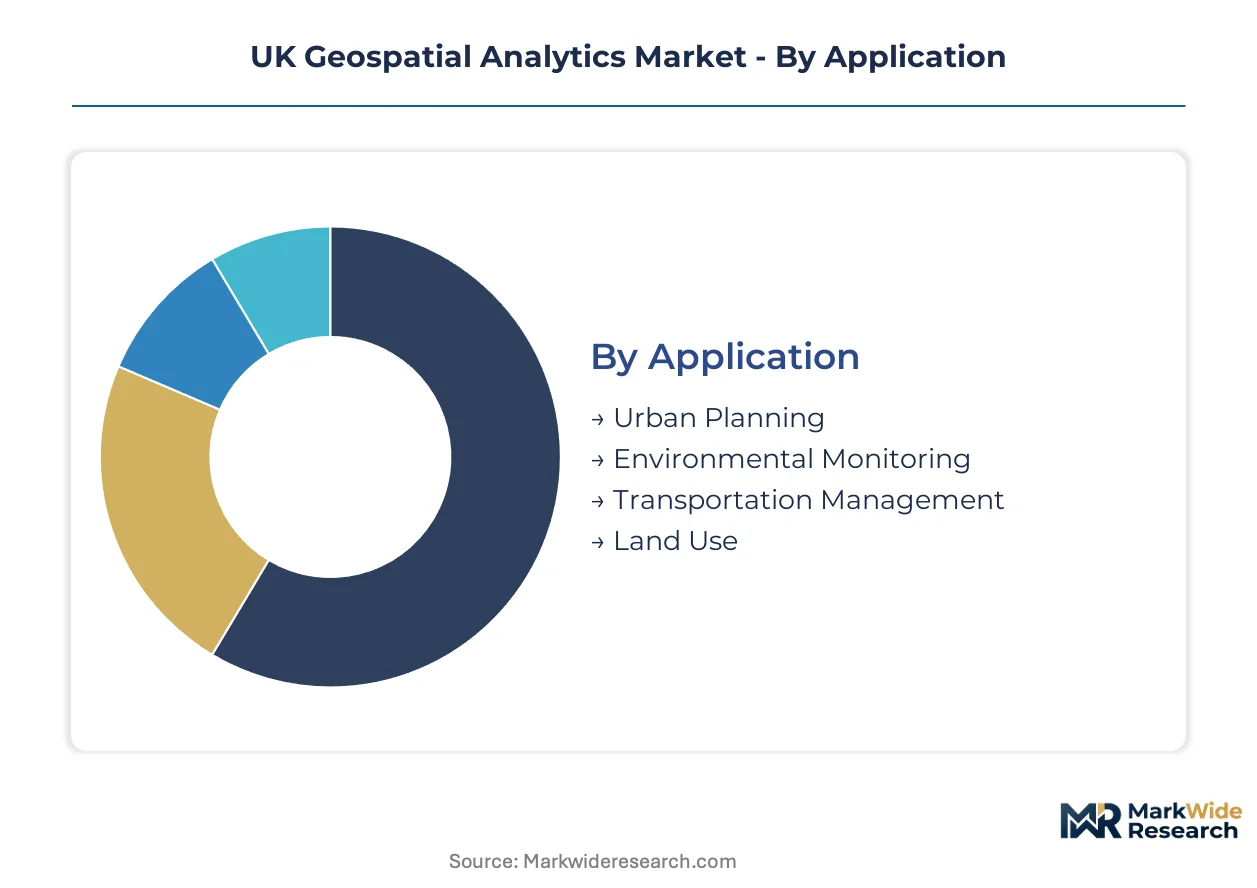
Segmentation in UK geospatial analytics reveals how regulatory mandates reshape procurement patterns across infrastructure operators. The Environment Agency's flood risk mapping requirements and Ordnance Survey's open data licensing terms create distinct compliance tiers that vendors must navigate.
Application:
The Environment Agency's biodiversity net-gain tracking mandates differentiate premium platform tiers from baseline offerings.
- Urban Planning:London boroughs deploy real-time 3D facility models integrating SCADA feeds with georeferenced asset registries. Westminster and Camden councils compress maintenance scheduling from quarterly cycles to condition-triggered interventions through digital twin architectures.
- Environmental Monitoring:Raster and vector datasets process at sub-metre accuracy for floodplain digitisation and habitat offset monitoring. Thames Gateway developers face planning rejection without LiDAR-verified elevation data at 25cm vertical resolution.
- Transportation Management:Congestion charging and low-emission zone enforcement systems generate recurring upgrades across Greater London.
- Land Use:Construction planning workflows integrate ecological survey data under mandated offset requirements.
Established volume favors Urban Planning; emerging adoption favors Environmental Monitoring.
Technology:
Cost tiering separates legacy on-premise installations from elastic API-first architectures that dominate new procurement.
- GIS:Traditional coordinate-based algorithms and spatial statistics power asset management workflows. Ordnance Survey's historic mapping dominance creates switching friction as agencies negotiate data licensing transitions under the Public Sector Geospatial Agreement.
- Cloud Computing:Elastic deployments capture expansion as UK agencies migrate from legacy installations. Greater Manchester and West Midlands Combined Authorities prioritize operational expenditure models bundling software, data refreshes, and technical support.
- Remote Sensing:Satellite-derived terrain data integrates with operational sensor networks for real-time decision support.
- Spatial Data Analysis:Automated inference tools intersect with the UK's emerging AI regulatory framework.
GIS retains incumbent share; Cloud Computing climbs the fastest as procurement shifts toward subscription models.
End User:
Customer type determines whether platforms serve compliance mandates or operational optimization objectives.
- Government Agencies:Whitehall departments adopt interoperable location intelligence standards under the National Geospatial Strategy. Transport, housing, and environmental agencies generate baseline demand through mandated platform upgrades.
- Agriculture Sector:DEFRA-backed precision farming subsidies accelerate variable-rate application mapping adoption. Soil moisture and yield data processing at field-scale resolution creates whitespace for specialized platforms.
- Mining Industry:Sub-metre accuracy seabed surveys support marine construction in the East Anglia offshore wind zone.
- Retail Businesses:Location intelligence optimizes supply chain and site selection decisions.
Government Agencies anchor procurement volume; Agriculture Sector gains share fastest through subsidy-driven adoption.
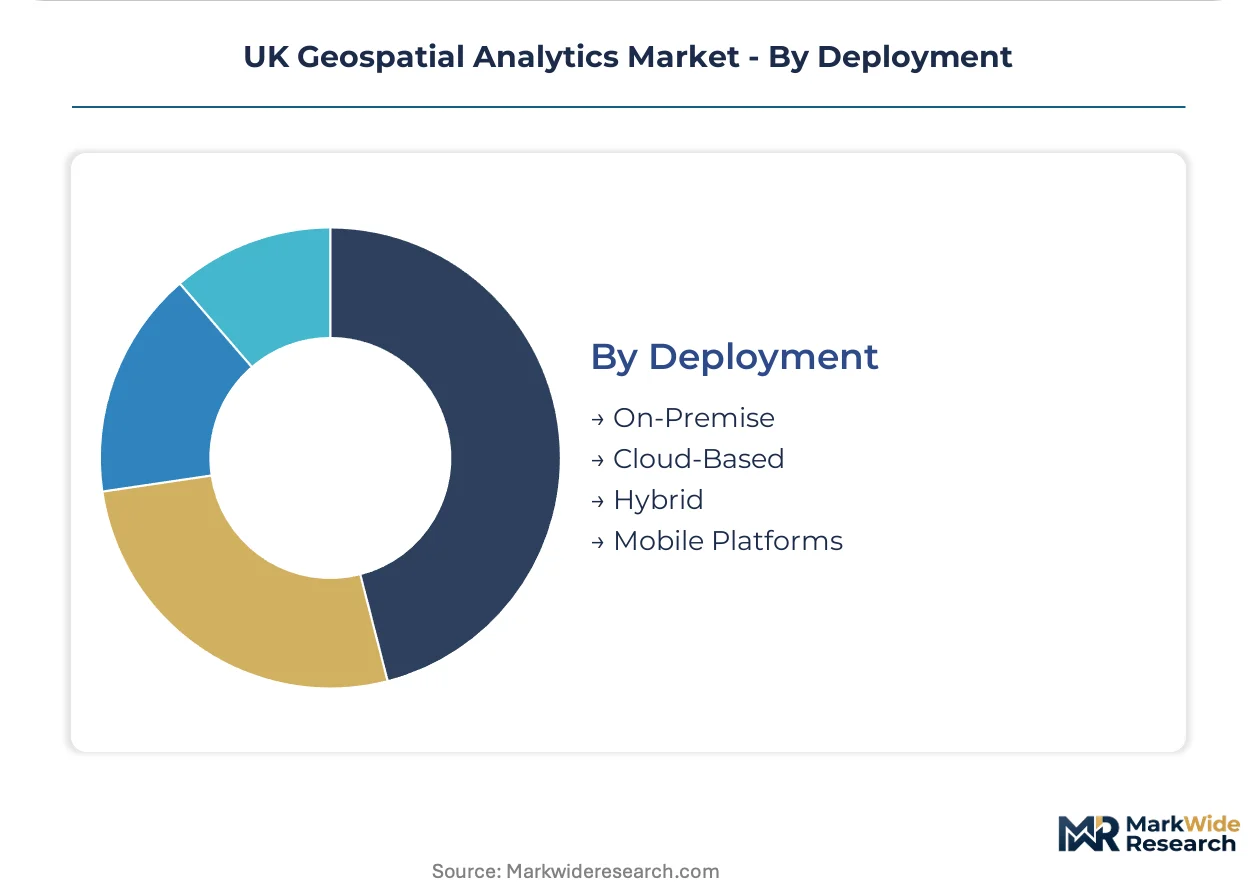
Deployment:
Maturity levels separate entrenched on-premise Esri installations from emerging mobile and hybrid configurations.
- On-Premise:Legacy GIS teams require retraining for cloud migration, compressing implementation timelines for public sector procurement cycles.
- Cloud-Based:API-first architectures demand new technical competencies from agencies accustomed to perpetual license purchases.
- Hybrid:Configurations balance sensitive asset data on-premise with scalable processing in elastic environments.
- Mobile Platforms:Field survey crews access real-time terrain models and synchronized asset registries through handheld devices.
On-Premise retains installed base; Cloud-Based represents the fastest-growing trajectory as subscription access displaces perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London commands premium platform pricing while Scottish procurement operates on tighter budget cycles, creating a two-tier demand structure across the UK geospatial analytics landscape.
London and the Southeast
Smart city congestion charging systems and low-emission zone enforcement drive recurring platform upgrades across Westminster and Camden councils. The Greater London Authority mandates real-time vehicle tracking integration with urban planning databases. Digital twin deployments in Thames Gateway corridors synchronize SCADA feeds with georeferenced asset registries for condition-triggered maintenance interventions.
East Anglia
Offshore wind construction in the East Anglia zone pulls precision measurement workflows from traditional utilities into marine engineering applications. Sub-metre accuracy seabed surveys and cable route optimization dominate procurement specifications. Developers face planning rejection risks without LiDAR-verified elevation data meeting 25cm vertical resolution standards.
Scotland
Public sector bodies in Edinburgh and Glasgow expand location intelligence procurement for infrastructure resilience planning under devolved environmental mandates. The Scottish Government's climate adaptation programs accelerate flood risk mapping platform upgrades. Highlands and Islands councils deploy remote sensing for rural connectivity and renewable energy site assessment.
Midlands
West Midlands Combined Authorities prioritize operational expenditure models bundling software, data refreshes, and technical support over perpetual license purchases. Birmingham's transport integration programs generate demand for interoperable location intelligence standards. DEFRA-backed precision farming subsidies accelerate variable-rate application mapping adoption across Warwickshire and Leicestershire agricultural zones.
North England
Greater Manchester's procurement teams favor subscription-based platform access displacing legacy Esri installations. Yorkshire floodplain digitisation mandates under Environment Agency requirements tighten accuracy specifications for terrain models. Teesside industrial clusters integrate geospatial asset management with operational sensor networks for real-time decision support.
UK Geospatial Analytics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK geospatial analytics market. The vendor base stratifies between sensor-hardware specialists, cloud-native platform providers, and legacy GIS incumbents with entrenched public sector relationships. Three archetypes dominate: precision measurement workflow providers, proprietary aerial survey operators, and telecom network geospatial specialists. Competitive moves concentrate on cloud migration partnerships and API-first architecture certifications.
Within the precision measurement tier, Hexagon leverages its sensor-to-software stack dominance across UK utilities. Bluesky International Ltd. anchors the proprietary aerial survey segment through exclusive urban corridor coverage. IQGeo Group occupies the telecom specialization vector, with its fibre and 5G rollout focus demonstrating vertical expansion potential into adjacent infrastructure sectors.
| Leading Market Players |
|---|
| Hexagon |
| Trimble |
| ESRI |
| Bentley Systems |
| General Electric |
| IQGeo Group |
| Bluesky International Ltd. |
| Oracle Corporation |
| SAS Institute |
| Others |
Pricing and Supply Chain Analysis
Ordnance Survey's Public Sector Geospatial Agreement gates vendor qualification and price differentiation simultaneously, forcing platform providers to absorb open data licensing costs while competing on proprietary feature tiers. The compliance burden compresses margins for mid-tier survey firms unable to amortize certification investments across large public sector contracts.
Pricing Analysis
Configured-to-order pricing for bespoke digital twin deployments commands three-to-five multiples over standard SaaS subscriptions for baseline GIS functionality. Three-tier pricing structure across premium, standard, and economy levels separates API-first cloud architectures from legacy on-premise installations and entry-level mobile field tools. Cost compression in the standard tier intensifies as Greater Manchester and West Midlands Combined Authorities consolidate procurement around bundled operational expenditure models. Government Agencies exhibit lowest price sensitivity due to mandated compliance budgets, while mid-tier survey firms face acute margin pressure from sensor hardware capital requirements.
Supply Chain Analysis
Extended lead times for aerial LiDAR and hyperspectral imaging equipment constrain data freshness competition, privileging operators with captive sensor fleets over hardware-dependent competitors. Hardware manufacturing concentrates in the United States, Germany, and China, while cloud processing infrastructure draws from hyperscaler regions in Ireland, the Netherlands, and the United Kingdom. Supply chain vulnerability hinges on single-source dependency for precision GNSS chipsets used in sub-metre accuracy surveying. Distribution runs through direct vendor relationships with Whitehall departments and combined authorities, supplemented by systems integrator channels for mid-market infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
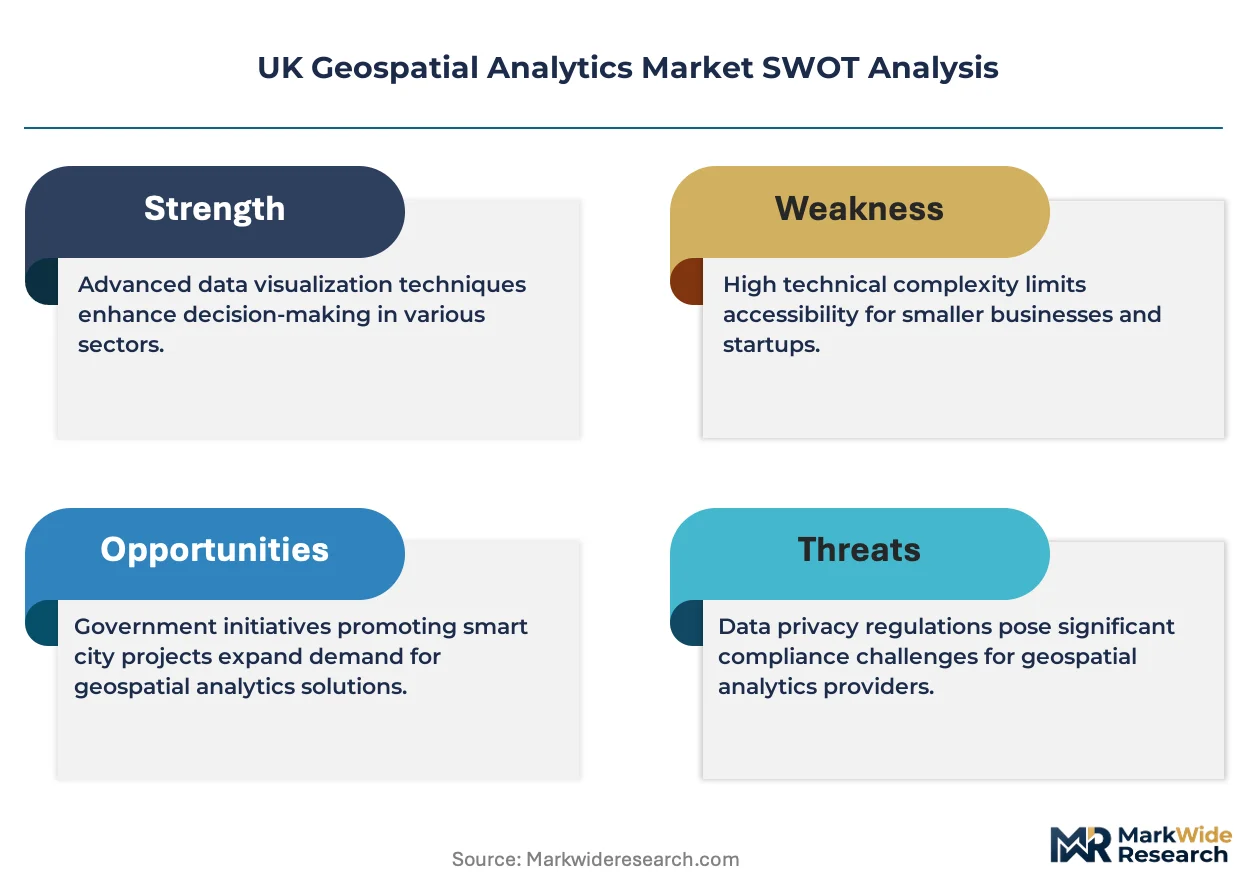
The UK geospatial analytics market sits at a platform-economics inflection where Ordnance Survey's open data mandate forces interoperability investments that reshape competitive moats around ecosystem integration rather than proprietary data lock-in.
For Market Incumbents: Secure cloud-native architecture certifications ahead of Environment Agency procurement deadlines to preempt switching costs from legacy Esri installations. Deepen backward integration into sensor hardware production to match Bluesky International's proprietary aerial coverage advantages. Prioritize API-first platform development that bundles real-time SCADA integration with subscription pricing models favored by combined authorities. For New Entrants and Emerging Players: Ordnance Survey's interoperability certification fast-track offers entry velocity for specialized platforms targeting DEFRA precision farming subsidies in Warwickshire and Leicestershire agricultural zones. White-space concentration sits in field-scale soil moisture analytics where incumbent GIS vendors lack agronomic workflow depth. Go-to-market leverage should anchor through agricultural cooperative channels rather than direct public sector procurement cycles. For Investors and Strategic Acquirers: The Environment Agency's biodiversity net-gain tracking mandate reshapes the acquisition landscape toward platforms with ecological survey data integration capabilities. Long-term viability centers on vendors positioned for algorithmic land-use classification compliance under the UK's emerging AI regulatory framework. Acquisition target archetype: cloud-native specialists with proven public sector interoperability and vertical workflow depth in environmental monitoring. Signal to monitor: DEFRA subsidy expansion into carbon soil sequestration measurement tools.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Migration Partnership | Elastic API-first architectures displace legacy Esri installations across Greater Manchester procurement cycles. |
| Sensor Hardware Acquisition | Captive aerial LiDAR fleets match Bluesky International's proprietary urban corridor coverage freshness. |
| Interoperability Certification | Ordnance Survey compliance validates platform access to Whitehall department procurement pipelines. |
| Vertical Workflow Expansion | IQGeo Group's telecom specialization demonstrates replicability into utility and transport infrastructure. |
| Subscription Model Restructuring | Operational expenditure bundling aligns with West Midlands Combined Authority procurement preferences. |
Research Methodology
A spread of perspectives from platform engineering leads, public sector procurement officers, environmental agency technical directors, and agricultural cooperative data managers converged on the working assumptions. Primary field engagement combined with secondary validation against Ordnance Survey licensing disclosures, Environment Agency flood risk mapping specifications, DEFRA subsidy program documentation, and combined authority procurement records. Bottom-up triangulation across vendor revenue segmentation and top-down reconciliation against public sector IT expenditure frameworks anchored the analytical foundation.
Segmentation dimensions modeled encompass deployment architecture, end-user vertical, application workflow complexity, and regional procurement authority type across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves for cloud migration and compliance-mandated platform replacement cycles. Forecast inputs incorporate Environment Agency floodplain digitisation timelines and Scottish Government climate adaptation program allocations.
Decision-makers should treat outputs as directional under sustained public sector budget commitment to infrastructure resilience planning; material deviation would warrant model refresh. Revision becomes warranted when DEFRA precision farming subsidy expansion crosses thresholds that reallocate agricultural sector procurement volumes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Big Data and Business Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Speech Analytics Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Data Visualization Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Tourism Industry Big Data Analytics Market
Analytics
Global Social Intelligence Market
Analytics
Global in-Memory Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
HR Analytics Market