
 North America HR Analytics Market | 2026-2036
North America HR Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America HR Analytics Market Insights
The direct enterprise sales channel is narrowing as cloud-based deployment options shift purchasing authority toward procurement teams and line-of-business leaders. Workday, Inc. leverages its native HCM architecture to embed analytics within transactional workflows. Oracle Corporation competes through database-layer integration that sustains performance at scale across hybrid environments. SAP SE anchors its position through pre-built connectors to existing ERP estates, reducing implementation friction for large corporations.
North America HR Analytics encompasses software platforms that ingest human capital data from payroll, recruitment, performance, and engagement systems to generate workforce intelligence through statistical modeling and visualization dashboards. These platforms apply machine learning algorithms to attrition prediction, skills gap analysis, and compensation benchmarking, serving primarily to reduce voluntary turnover and optimize talent deployment. Cloud-based deployment leads segment traction due to lower upfront infrastructure commitment and faster iteration cycles, while predictive analytics functionality captures expanding margin pools as buyers prioritize forward-looking workforce scenarios over retrospective reporting. Talent acquisition solutions within the solution segment show particular momentum as labor market tightness elevates sourcing efficiency priorities.
The U.S. Equal Employment Opportunity Commission and the Office of Federal Contract Compliance Programs enforce audit requirements that shape algorithmic transparency mandates for HR technology vendors serving federal contractors. State-level legislation in California and New York imposes additional data retention and bias-testing obligations that elevate compliance costs for on-premises deployments relative to certified cloud alternatives. Stakeholders must monitor emerging state patchworks of AI governance to determine whether centralized SaaS architectures or jurisdictional data residency configurations better mitigate regulatory exposure.
Market Dynamics
Predictive workforce planning tools are compressing decision cycles across U.S. enterprises, forcing vendors to embed analytics directly within transactional HCM workflows rather than operate as standalone BI layers.
Growth Catalysts
- Algorithmic Fairness Enforcement:The U.S. Equal Employment Opportunity Commission's audit mandates for federal contractors accelerate certified cloud platform adoption over on-premises alternatives.
- West Coast Technology Corridor:San Francisco and Seattle metropolitan areas concentrate demand as large technology employers expand predictive attrition modeling across engineering and product functions.
- Skills Gap Analytics:Machine learning applications for internal mobility and reskilling pathway identification pull procurement authority toward line-of-business leaders seeking workforce deployment optimization.
Market Restraints
- State-Level Compliance Fragmentation:California and New York data retention and bias-testing obligations elevate implementation costs for multi-state employers relative to single-jurisdiction deployments.
- Legacy System Integration Friction:On-premises ERP estates require custom connector development that extends deployment timelines and strains IT resource availability.
- Talent Data Sensitivity:Cross-border data residency requirements for Canadian provincial privacy frameworks constrain centralized SaaS architectures serving North American operations.
Strategic Opportunities
- Mid-Market Underpenetration:U.S. employers with 500-5,000 employees lack dedicated people analytics functions, creating whitespace for verticalized solutions with pre-built workforce templates.
- Talent Acquisition Convergence:Tight labor market conditions elevate sourcing efficiency priorities, expanding margin pools for predictive candidate quality scoring and time-to-fill optimization.
- Hybrid Deployment Architectures:Jurisdictional data residency configurations offer compliance arbitrage against state patchworks of AI governance for risk-sensitive federal contractors.
Industry Challenges
- Interpretability Skill Scarcity:HR business partners lack statistical literacy to translate model outputs into workforce interventions, creating adoption friction and underutilization.
- Algorithmic Audit Preparedness:Documentation requirements for disparate impact testing demand specialized compliance functions that most organizations have not staffed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America HR Analytics Market |
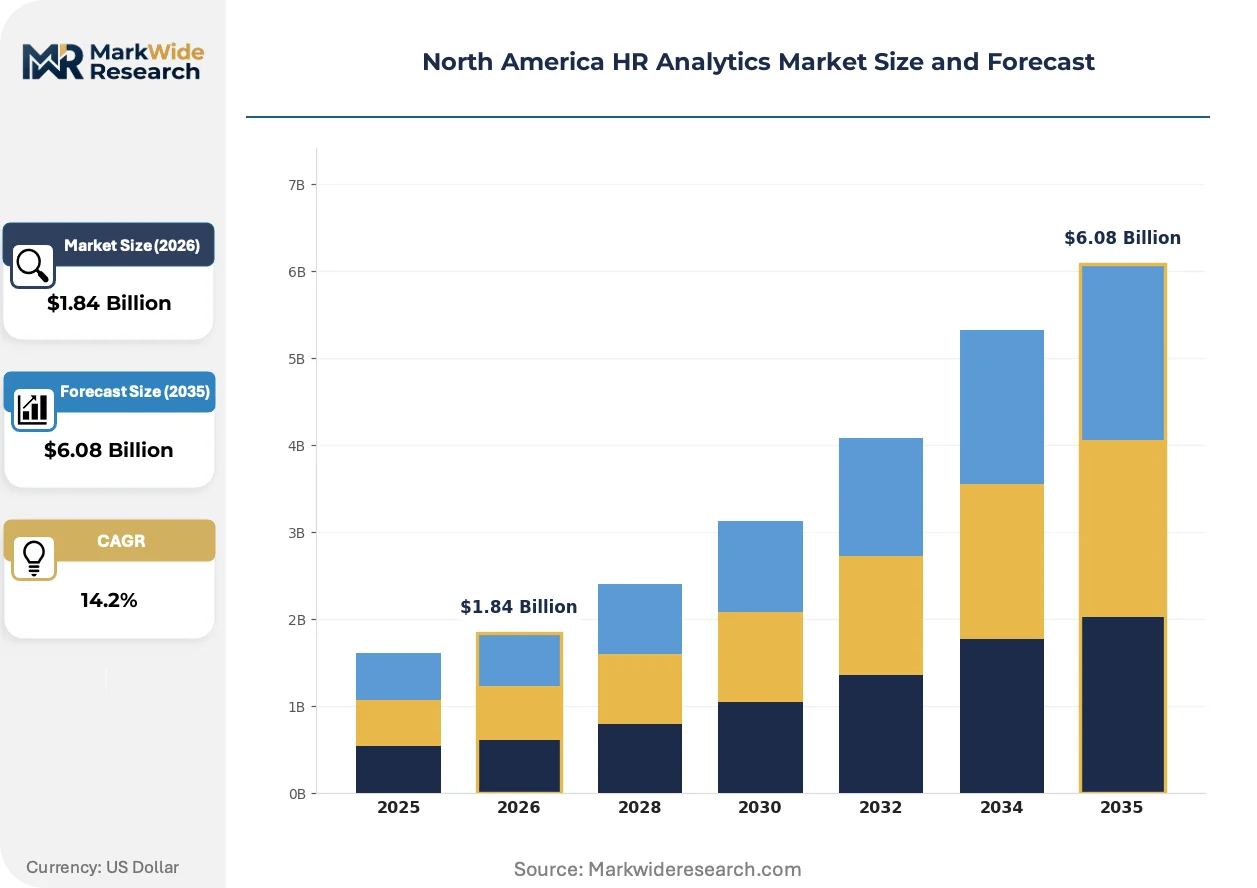
| Market Size in 2026 | $1.84 Billion |
| Market Size in 2035 | $6.08 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Workforce Planning, Talent Acquisition, Performance Management, Employee Engagement End User: Small Enterprises, Medium Enterprises, Large Corporations, Government Agencies Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Functionality: Data Analytics, Reporting Tools, Predictive Analytics, Benchmarking |
| Companies Covered | Workday, Inc., Oracle Corporation, SAP SE, ADP Inc., IBM Corporation, Paycom Software, Inc., Visier, Inc., Infor, Inc., SAS Institute, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America HR Analytics Market Trends and Innovations
Native embedding of analytics within core HCM transactional flows is collapsing the distinction between operational reporting and strategic workforce intelligence, compressing vendor competitive differentiation around workflow integration depth.
Natural language interfaces for workforce query and visualization are collapsing the technical barrier between HR business partners and predictive model outputs. Large U.S. employers in technology and financial services are deploying conversational analytics tools that allow non-technical users to interrogate attrition drivers and compensation equity without dedicated data science support. This compression of the analytics consumption layer is forcing standalone BI vendors to reposition around specialized statistical depth or cede ground to embedded platform providers.
The U.S. Equal Employment Opportunity Commission's algorithmic fairness guidelines are reshaping product development roadmaps for vendors serving federal contractors. Enforcement patterns now require documented disparate impact testing and explainability features that elevate engineering investment for transparency tooling. Federal contractor segments are responding by consolidating procurement around certified cloud architectures that offer pre-built compliance documentation rather than assuming audit risk with custom on-premises configurations.
Subscription-based pricing for workforce intelligence modules is displacing perpetual license models across U.S. enterprise procurement. Line-of-business leaders now control analytics budgets outside centralized IT, favoring consumption-aligned cost structures that scale with employee headcount and module activation. This shift is most visible in West Coast technology employers where rapid workforce fluctuation makes fixed-cost analytics investments economically unattractive relative to elastic SaaS arrangements.
North America HR Analytics Market Segmentation
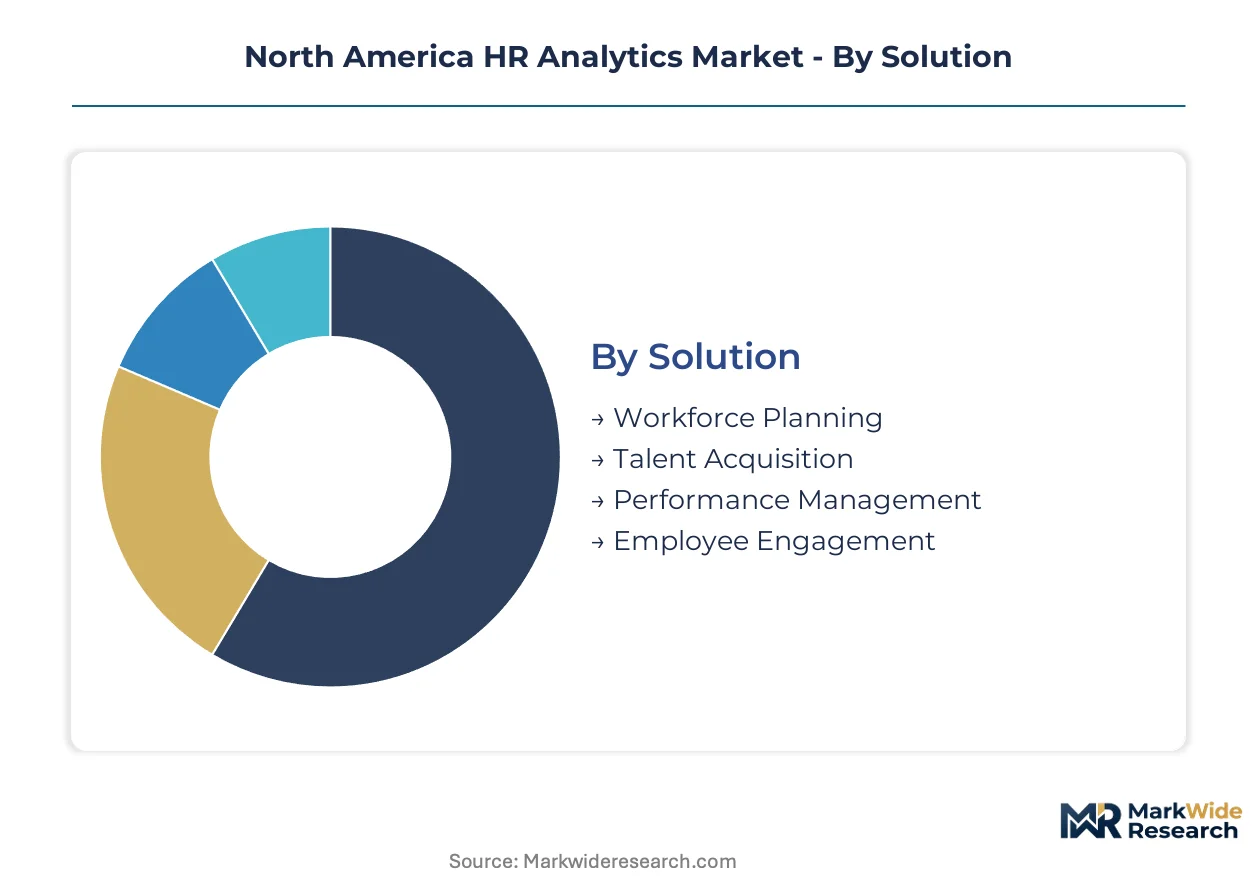
Segmentation in North America HR Analytics reveals distinct procurement rhythms across solution types and buyer profiles. Cloud deployment cycles compress faster than on-premises implementations, while large corporations drive predictive functionality roadmaps ahead of mid-market adoption curves.
Solution:
Workforce Planning solutions refresh on 18-24 month enterprise cycles, while Talent Acquisition modules turn over faster as labor market volatility demands continuous reconfiguration.
- Workforce Planning:These platforms integrate headcount forecasting, succession modeling, and scenario planning across multi-year horizons. Large technology employers in the San Francisco Bay Area deploy these tools to align engineering staffing with product roadmap milestones.
- Talent Acquisition:Predictive candidate scoring and time-to-fill optimization dominate functionality roadmaps here. Seattle metropolitan employers prioritize sourcing efficiency analytics as competition for software engineering talent intensifies.
- Performance Management:Continuous feedback and goal-cascade analytics serve mid-market employers seeking to replace annual review cycles.
- Employee Engagement:Pulse survey and sentiment analysis tools concentrate in financial services and healthcare verticals with distributed workforces.
Workforce Planning dominates installed base. Talent Acquisition is where expansion concentrates.
End User:
Large Corporations absorb premium pricing for predictive depth, while Medium Enterprises represent the steepest expansion trajectory as pre-configured templates reduce implementation friction.
- Large Corporations:These buyers demand native HCM embedding and custom model development for attrition prediction across 10,000-plus employee bases. U.S. federal contractors in this tier face EEOC audit mandates that shape vendor selection criteria.
- Medium Enterprises:Organizations with 500-5,000 employees lack dedicated people analytics functions, creating demand for verticalized solutions with pre-built workforce templates and managed service layers.
- Small Enterprises:Point solutions for recruiting metrics and basic turnover reporting serve this price-sensitive tier through self-service configurations.
- Government Agencies:Federal and state entities require FedRAMP-authorized cloud architectures and documented disparate impact testing for algorithmic tools.
Large Corporations anchor vendor revenue. Medium Enterprises are climbing the fastest.
Deployment:
Cloud-Based options compress procurement cycles to weeks versus quarters, while Hybrid architectures gain traction among multi-state employers navigating California and New York data residency obligations.
- Cloud-Based:Multi-tenant SaaS architectures eliminate infrastructure overhead and accelerate iteration cycles. West Coast technology employers favor these deployments for elastic scaling across volatile hiring periods.
- SaaS:Subscription pricing aligns costs with headcount fluctuations, appealing to line-of-business leaders controlling analytics budgets outside centralized IT procurement.
- Hybrid:Jurisdictional data residency configurations address Canadian provincial privacy frameworks and U.S. state-level AI governance patchworks.
- On-Premises:Custom configurations persist in defense contractors and financial institutions with legacy ERP estates requiring bespoke connector development.
Cloud-Based deployments dominate new procurement. Hybrid is gaining share fastest.
Functionality:
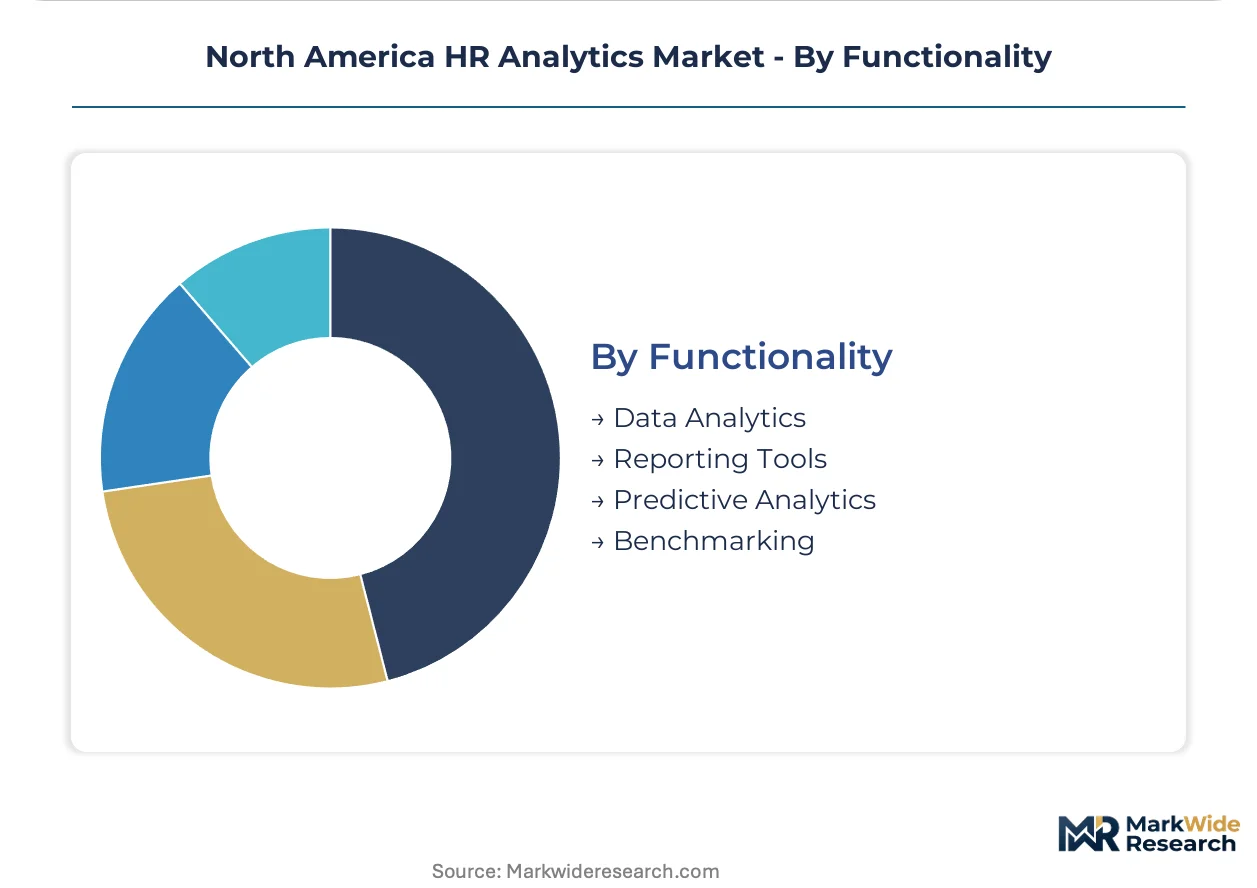
Predictive Analytics commands premium pricing as buyers prioritize forward-looking workforce scenarios, while Reporting Tools face commoditization pressure from native HCM dashboards.
- Predictive Analytics:Machine learning models for attrition forecasting and skills gap identification differentiate vendor offerings. These capabilities concentrate procurement authority with line-of-business leaders seeking workforce deployment optimization.
- Data Analytics:Statistical modeling and visualization dashboards form the foundational layer, with demand concentrating among employers consolidating disparate HRIS sources.
- Benchmarking:External compensation and engagement comparisons serve retained search firms and compensation committees.
- Reporting Tools:Retrospective workforce metrics face displacement by embedded operational analytics within core HCM platforms.
Data Analytics dominates current deployments. Predictive Analytics is where vendor investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Canadian levels by roughly one-third, reflecting concentrated demand from federal contractors facing EEOC audit mandates. Mexican employers absorb lower-cost workforce planning modules as nearshoring operations expand human capital management requirements.
United States
Federal contractors drive premium platform adoption as EEOC algorithmic fairness enforcement tightens vendor selection criteria. The Office of Federal Contract Compliance Programs mandates disparate impact documentation for AI-enabled hiring tools. San Francisco and Seattle metropolitan areas concentrate predictive attrition modeling investment among technology employers scaling engineering teams.
Canada
Provincial privacy frameworks in Quebec and British Columbia constrain centralized SaaS architectures serving North American operations. Health Canada coordinates with provincial regulators on workforce data protection standards. Toronto and Vancouver financial services clusters deploy engagement analytics for distributed pandemic-era workforces.
Mexico
Nearshoring manufacturing expansion elevates Spanish-language workforce planning module demand. The Secretariat of Labor and Social Welfare implements digital reporting standards affecting HRIS integration requirements. Monterrey and Guadalajara industrial corridors absorb mid-market talent acquisition solutions as automotive and electronics employers scale operations.
California
State-level AI governance legislation imposes bias-testing obligations exceeding federal contractor requirements. The California Consumer Privacy Act shapes data retention configurations for multi-state employers. Silicon Valley technology employers compress procurement cycles through elastic cloud deployments aligned with volatile hiring patterns.
North America HR Analytics Market Competitive Landscape
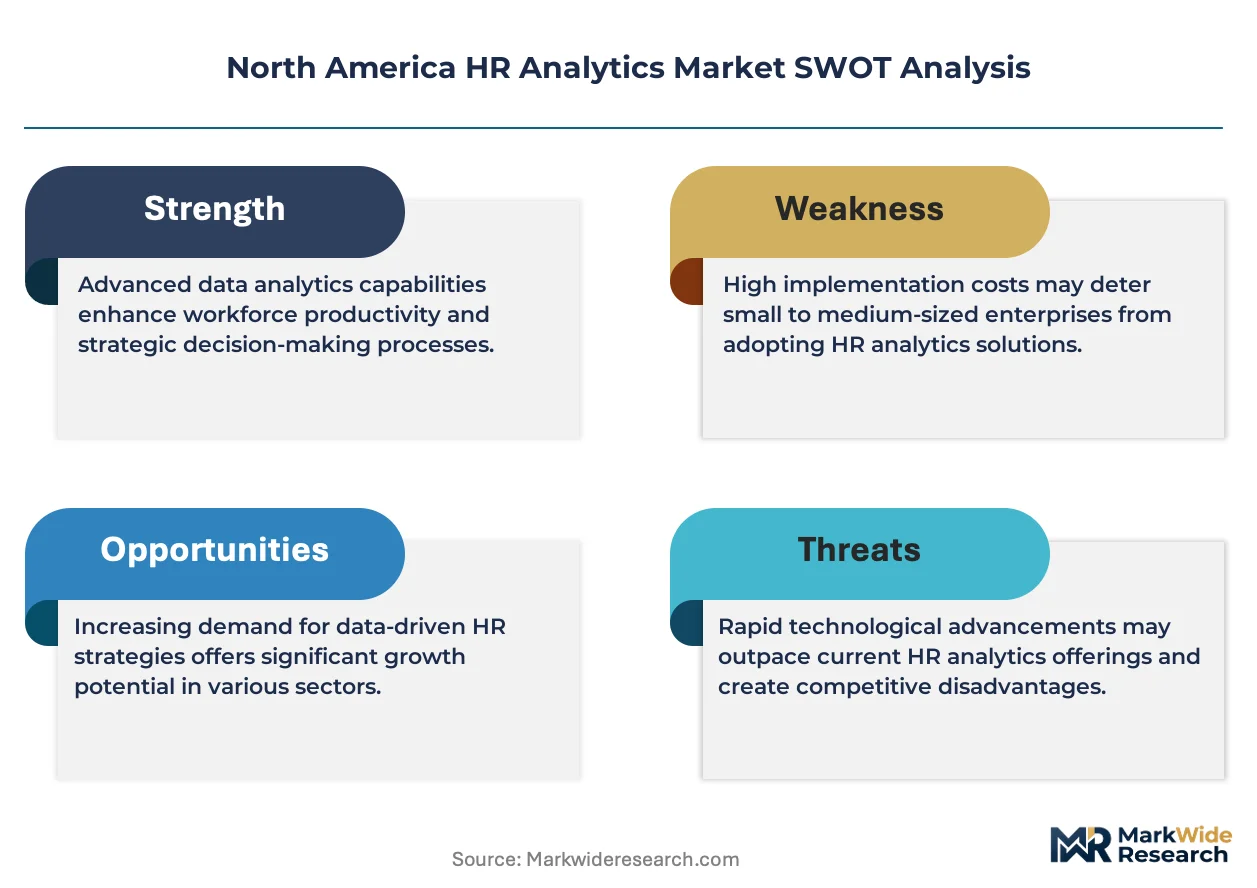
Platform integrators command the system tier; component specialists sit upstream with statistical depth and visualization tooling. The vendor base consolidates around three strategic layers: native HCM embedders, database-layer specialists, and standalone analytics pure-plays. Dominant competitive moves include workflow integration deepening and compliance certification racing as federal contractor requirements tighten.
Within the native embedder tier, Workday, Inc. and Oracle Corporation occupy positions reflecting architectural integration depth. SAP SE anchors the pre-built connector segment. These three exemplify divergent technical approaches to workforce intelligence deployment: transactional workflow embedding, database-layer performance, and ERP estate integration respectively.
| Leading Market Players |
|---|
| Workday, Inc. |
| Oracle Corporation |
| SAP SE |
| ADP Inc. |
| IBM Corporation |
| Paycom Software, Inc. |
| Visier, Inc. |
| Infor, Inc. |
| SAS Institute, Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cloud hyperscaler infrastructure determines both the premium-to-standard pricing spread and the geographic configuration of vendor delivery architectures. EEOC algorithmic fairness enforcement concentrates procurement authority among certified providers, compressing margins for uncertified alternatives while elevating compliance-premium tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order predictive analytics deployments from standard SaaS workforce planning modules. Subscription-based tiered pricing dominates, with differentiation anchored in FedRAMP certification level and native HCM embedding depth. Pricing pressure stems from line-of-business procurement authority shifting spend toward consumption-aligned elastic arrangements. Small enterprises exhibit highest price sensitivity, while federal contractors absorb compliance premiums without volume negotiation leverage.
Supply Chain Analysis
Tariff exposure between the United States and China on semiconductor components constrains AI accelerator availability for on-premises predictive modeling deployments. Vendor infrastructure draws from hyperscaler data centers in the United States, Ireland, and Singapore, with GPU compute and enterprise storage arrays as critical inputs. Single-source vulnerability in NVIDIA chip supply creates procurement queue risk for custom model training workloads. Distribution runs through direct enterprise sales teams and cloud marketplace procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Native HCM platform substitution threatens standalone analytics vendors as Workday, Oracle, and SAP embed predictive capabilities within transactional workflows. Incumbents must articulate defensible differentiation beyond workflow integration depth.
For Market Incumbents: Entrench through FedRAMP certification investment and pre-built compliance documentation for federal contractor segments. Deepen vertical integration into specialized attrition modeling for technology sector buyers. Counter native HCM substitution by positioning around statistical depth and multi-source data consolidation capabilities that embedded platforms cannot replicate.
For New Entrants and Emerging Players: Build out verticalized workforce planning templates targeting U.S. mid-market employers with 500-5,000 employees lacking dedicated people analytics functions. Penetrate the California state agency segment where AI governance legislation exceeds federal contractor requirements. Pursue channel partnerships with regional HCM implementation consultancies rather than direct enterprise sales buildout.
For Investors and Strategic Acquirers: EEOC algorithmic fairness guideline enforcement reshapes the acquisition landscape toward certified cloud architectures with documented disparate impact testing capabilities. Long-term viability centers on vendors serving federal contractor segments with recurring compliance audit requirements. Monitor California AI governance legislation expansion as the signal indicating accelerated consolidation around jurisdictional data residency configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native HCM embedding collapses procurement friction for Workday and Oracle customers. |
| FedRAMP Certification | Federal contractor eligibility gates revenue access for cloud analytics vendors. |
| Vertical Solution Development | Pre-built technology sector templates capture mid-market employers without analytics functions. |
| Strategic Partnership | Channel alliances with regional HCM consultancies accelerate mid-market penetration. |
| Acquisition of Specialist Firm | Natural language interface capabilities address interpretability skill scarcity among HR business partners. |
Research Methodology
A spread of perspectives from chief people officers, HR technology procurement leads, federal compliance officers, and cloud platform engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, FedRAMP authorization databases, EEOC enforcement guidance documents, and state-level AI governance legislation trackers. Bottom-up deployment estimates triangulated against top-down vendor revenue segmentation across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation modeled across deployment architecture, organization size tier, solution type, and regulatory compliance burden. CAGRs derived from elasticity-adjusted adoption curves incorporating federal contractor procurement cycles and West Coast technology employer hiring volatility. Workforce planning module refresh rates and talent acquisition solution turnover patterns informed solution-specific trajectory assumptions throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by Oracle or SAP would shift outcomes toward embedded analytics consolidation. Material shifts in EEOC enforcement intensity or California AI governance legislation expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Embedded Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
China Contact Center Analytics Market
Analytics
Speech Analytics Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Europe Mobile Analytics Market
Analytics
Dark Analytics Market
Analytics
Global System Monitoring Market
Analytics
Procurement Analytics Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Multichannel Analytics Market
Analytics
Global Sentiment Analytics Software Market
Analytics
Contact Center Analytics Market
Analytics
Content Analytics and Discovery Software Market