
 Connected Device Analytics Market | 2026-2036
Connected Device Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Device Analytics Market Analysis
Data engineering talent scarcity is rotating enterprise priorities toward managed analytics services that reduce in-house complexity. Microsoft Corporation leverages its Azure IoT stack to anchor industrial workloads across manufacturing verticals. Cisco Systems Inc. specializes in edge-to-cloud networking architectures that sustain real-time telemetry pipelines. Amazon Web Services Inc. dominates cloud-based deployment segments with serverless analytics offerings that extend customer data lakes.
Connected Device Analytics encompasses the ingestion, processing, and interpretation of telemetry streams from networked sensors, embedded systems, and IoT endpoints, typically operating at latencies below 100 milliseconds for time-critical industrial control loops. The discipline serves to convert raw device signals into operational intelligence for asset optimization, anomaly detection, and automated intervention triggering. Cloud-based deployment leads in revenue contribution due to elastic scaling economics, while edge computing represents the fastest-expanding architecture as latency-sensitive applications in predictive maintenance and remote monitoring outpace centralized processing tolerance. Machine learning technology anchors margin pools where proprietary algorithmic differentiation commands premium pricing against commoditized data visualization layers.
FDA scrutiny of connected medical devices shapes healthcare provider demand for audit-ready analytics pipelines, while GDPR and ISO 27001 compliance requirements constrain cross-border data routing architectures in European deployments. The EU AI Act introduces additional conformity obligations for automated decision systems processing device telemetry, forcing platform vendors to embed explainability modules. Stakeholders must weigh sovereign cloud commitments against interoperability standards when selecting analytics infrastructure partners.
Market Dynamics
Edge computing architectures are fragmenting data gravity patterns as manufacturing operators reject cloud-only pipelines for sub-100-millisecond control loops, forcing platform vendors to redistribute inference workloads across factory floors.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare providers in Germany and France now require explainable inference modules for connected medical devices, accelerating procurement of audit-ready analytics stacks.
- Predictive maintenance platforms:Automotive supplier networks across Stuttgart and Wolfsburg are deploying vibration-sensor analytics to compress unplanned downtime intervals.
- GDPR data sovereignty frameworks:Stringent cross-border routing constraints are compelling enterprises to localize telemetry processing within national boundaries.
Market Restraints
- Specialized data engineering talent scarcity:Pipeline architecture skills concentrate in Berlin and Munich, inflating compensation premiums for in-house platform builds.
- Edge hardware cost volatility:Industrial-grade GPU and FPGA modules face supply concentration from Taiwanese foundries, destabilizing deployment budgets.
- ISO 27001 certification timelines:Healthcare and automotive sectors face 8-14 month audit cycles that delay production rollouts.
Strategic Opportunities
- Underpenetrated pharmaceutical cold chain:Temperature-sensitive biologics distribution in Bavaria lacks real-time deviation alerting, opening sensor-analytics integration.
- 5G-TSN convergence:Time-sensitive networking over private cellular is enabling microsecond-synchronized machine control in precision manufacturing.
- CSRD sustainability reporting:Industrial asset energy telemetry now feeds mandatory disclosure requirements, creating new analytics subscription tiers.
Industry Challenges
- OT-IT integration complexity:Brownfield manufacturing environments run proprietary SCADA protocols that resist standard MQTT ingestion without middleware development.
- Algorithmic IP fragmentation:Proprietary anomaly detection models from equipment OEMs create licensing conflicts with third-party analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Device Analytics Market |
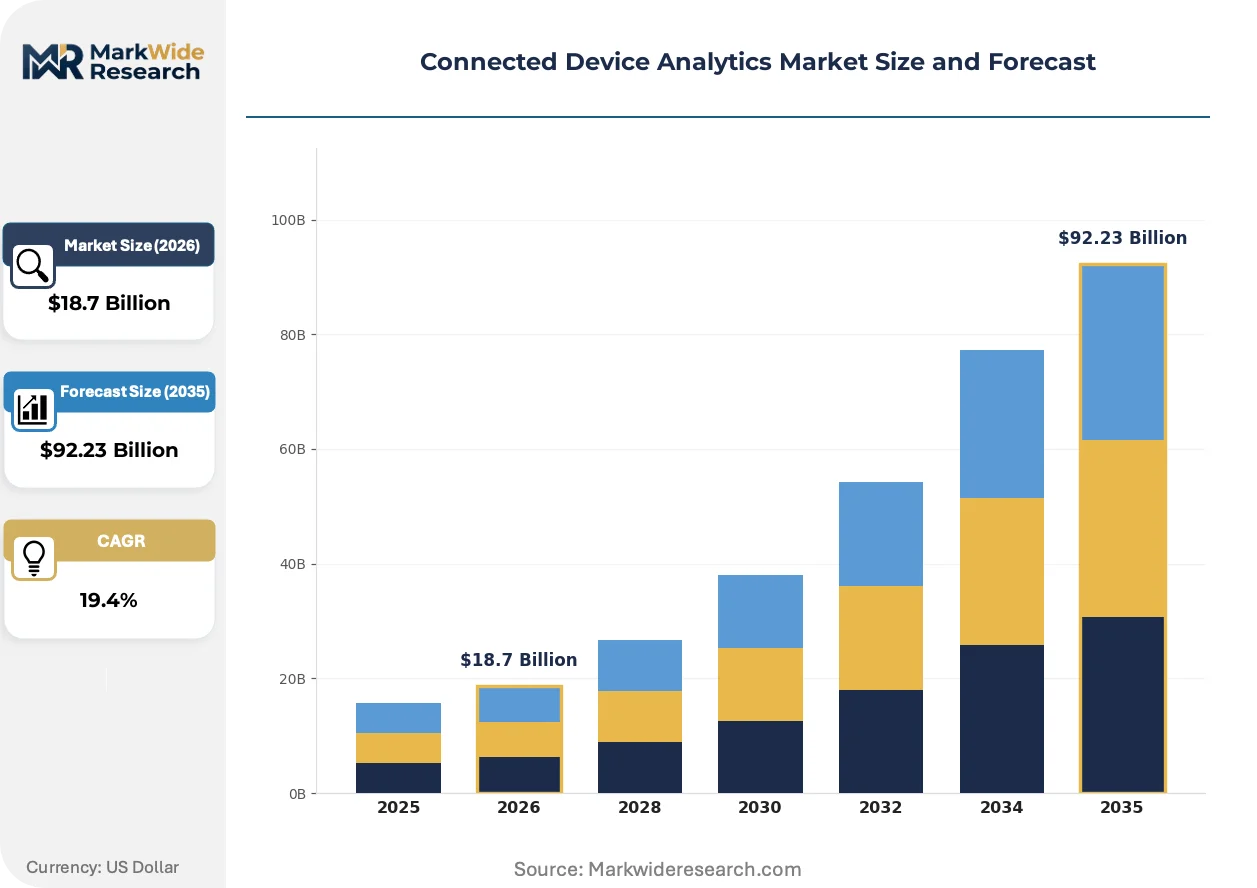
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Healthcare Providers, Industrial Manufacturers, Retailers, Smart Home Users Application: Predictive Maintenance, Asset Tracking, Smart Metering, Remote Monitoring Technology: Machine Learning, IoT Platforms, Big Data Analytics, Data Visualization |
| Companies Covered | Oracle Corporation, Cisco Systems Inc., Microsoft Corporation, Adobe Inc., SAP SE, Amazon Web Services Inc., Google LLC, PTC Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Device Analytics Market Emerging Trajectories
Telemetry processing architectures are bifurcating as latency tolerance thresholds harden across industrial control applications, splitting vendor roadmaps between centralized cloud scaling and distributed edge inference.
Federated learning for device analytics is supplanting centralized model training in privacy-sensitive deployments. Pharmaceutical manufacturers in Basel and Frankfurt are piloting collaborative anomaly detection across supplier networks without raw data centralization. This architecture is compressing compliance overhead for cross-border telemetry sharing while preserving algorithmic accuracy.
REACH substance restrictions are reshaping sensor hardware supply chains for industrial IoT endpoints. Manufacturers must now certify that vibration and temperature probes exclude restricted heavy metals and persistent organic pollutants. Automotive tier-one suppliers in Germany are accelerating qualification of compliant MEMS accelerometer alternatives ahead of 2026 enforcement windows.
Service unbundling is fragmenting traditional platform contracts. Discrete pricing for data ingestion, model training, and inference execution is replacing all-inclusive SaaS subscriptions among mid-market manufacturers. This pattern is most visible in Baden-Württemberg, where precision engineering firms negotiate component-level analytics procurement to match project-based capital cycles.
Connected Device Analytics Market Segmentation
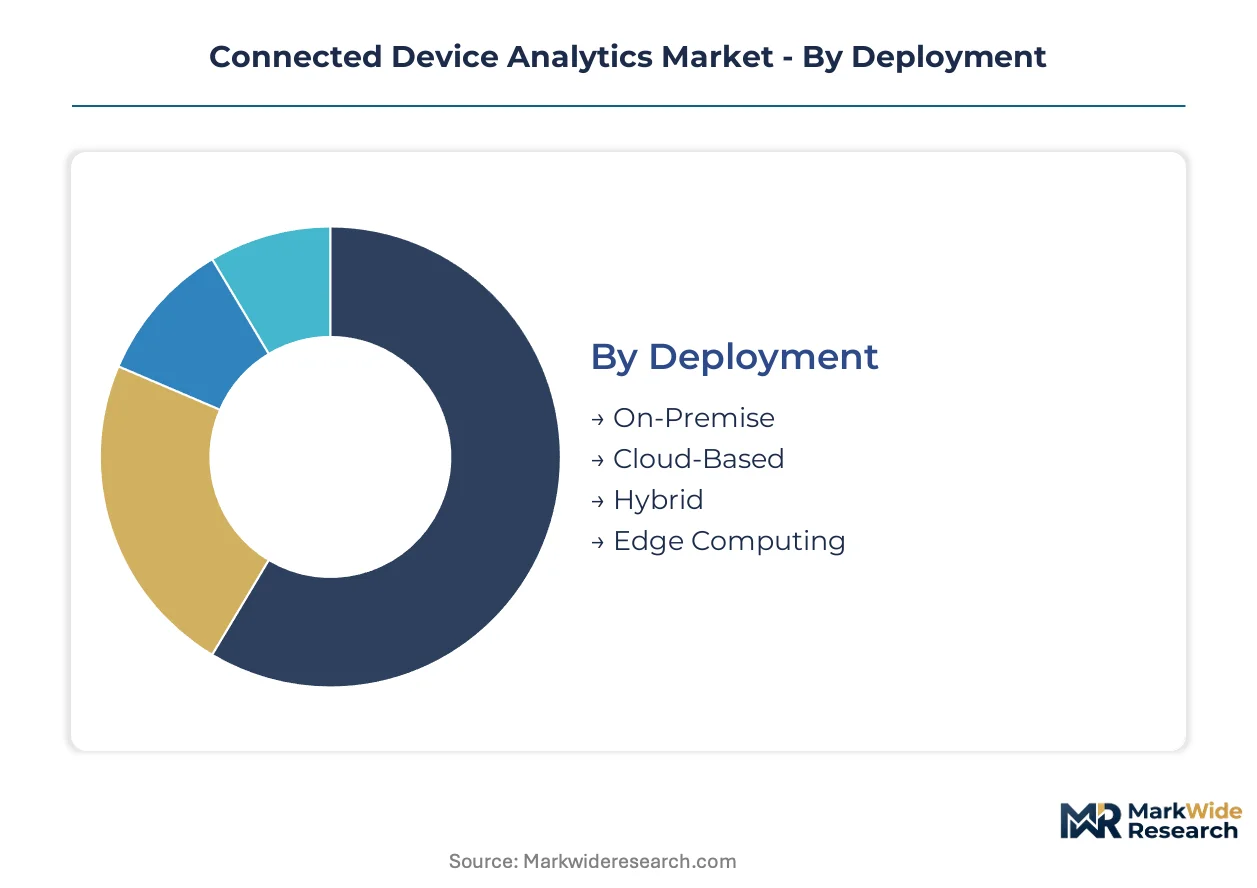
Deployment architecture determines latency tolerance and data sovereignty compliance for telemetry pipelines. End-use verticals impose distinct regulatory burdens and integration complexity. Application focus shapes margin structure and renewal economics.
Deployment:
Channel mix splits between direct enterprise sales for on-premise installations and partner-led distribution for cloud-based consumption, with edge computing increasingly flowing through systems integrators.
- On-Premise:Dedicated hardware stacks within facility data centers process sensitive telemetry without external data egress. German automotive suppliers in Stuttgart and Wolfsburg favor this architecture to satisfy GDPR localization mandates and ISO 27001 audit requirements.
- Cloud-Based:Elastic compute resources scale ingestion throughput without capital deployment. Healthcare providers in France leverage this channel to compress time-to-value for connected medical device analytics while outsourcing infrastructure maintenance to managed service partners.
- Hybrid:Workload partitioning between local preprocessing and cloud aggregation balances latency against storage economics.
- Edge Computing:Distributed inference nodes on factory floors sustain sub-100-millisecond control loops for predictive maintenance triggers.
Cloud-Based deployments dominate installed base. Edge Computing is where expansion concentrates.
End User:
Customer-type concentration varies sharply by procurement sophistication and compliance maturity.
- Healthcare Providers:Hospital networks and clinic chains deploy telemetry analytics for connected medical device monitoring and patient flow optimization. FDA and EU AI Act scrutiny forces investment in explainable inference modules and audit-ready pipeline documentation.
- Industrial Manufacturers:Automotive and precision engineering facilities across Baden-Württemberg integrate vibration-sensor analytics to compress unplanned downtime. Brownfield SCADA protocol complexity inflates middleware development costs for MQTT ingestion.
- Retailers:Cold chain operators and inventory management platforms apply asset tracking to perishable goods logistics.
- Smart Home Users:Consumer-grade deployments prioritize data privacy controls and subscription affordability over industrial-grade latency specifications.
Industrial Manufacturers anchor current revenue. Healthcare Providers are climbing the fastest as regulatory pressure hardens.
Application:
Margin pools concentrate where proprietary algorithmic differentiation commands premium pricing against commoditized visualization layers.
- Predictive Maintenance:Vibration, thermal, and acoustic sensor fusion enables failure prediction before functional degradation. Automotive supplier networks in Germany deploy this application most intensively to protect just-in-sequence production schedules.
- Asset Tracking:Real-time location systems and geofencing telemetry optimize fleet and inventory utilization. Pharmaceutical cold chain operators in Bavaria lack sufficient real-time deviation alerting, creating integration opportunities.
- Smart Metering:Utility-scale consumption analytics support demand response and grid balancing programs.
- Remote Monitoring:Distributed equipment oversight reduces field service dispatch frequency for industrial OEMs.
Predictive Maintenance holds the deepest installed base. Asset Tracking is gaining share fastest from underpenetrated pharmaceutical logistics.
Technology:
Supply concentration for specialized hardware and talent scarcity rotate procurement toward managed service wrappers.
- Machine Learning:Proprietary anomaly detection and predictive models differentiate platform offerings. Federated learning architectures are supplanting centralized training in cross-border pharmaceutical deployments around Basel and Frankfurt.
- IoT Platforms:Device management, protocol translation, and telemetry ingestion middleware form the connectivity substrate. REACH substance restrictions are accelerating qualification of compliant MEMS sensor alternatives ahead of enforcement windows.
- Big Data Analytics:Distributed storage and stream processing infrastructure handle high-velocity telemetry volumes.
- Data Visualization:Dashboard and reporting layers face commoditization pressure as open-source alternatives proliferate.
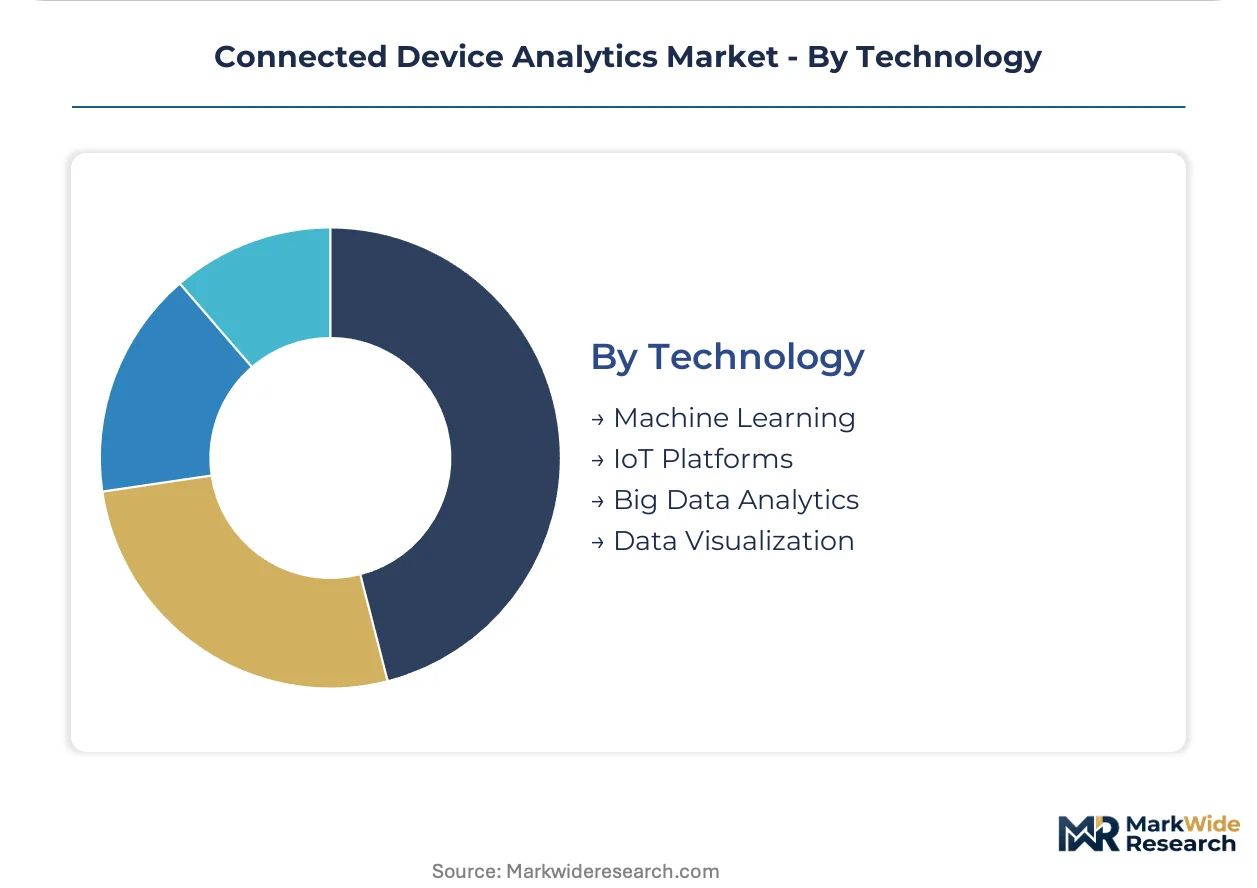
Machine Learning commands premium pricing. IoT Platforms represent the steepest expansion trajectory as edge deployment proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement by European data protection authorities anchors demand concentration in Germany, where industrial IoT infrastructure and automotive supplier networks drive platform procurement. Manufacturing facilities across Stuttgart and Wolfsburg accelerate predictive maintenance adoption to reduce unplanned downtime. Edge computing deployments proliferate as data sovereignty requirements tighten under EU regulatory frameworks.
Germany
Automotive supplier networks in Stuttgart and Wolfsburg deploy vibration-sensor analytics to compress unplanned downtime intervals. The EU AI Act introduces conformity obligations for automated decision systems processing device telemetry, forcing platform vendors to embed explainability modules. Baden-Württemberg precision engineering firms negotiate component-level analytics procurement to match project-based capital cycles.
United States
Healthcare providers deploy telemetry analytics for connected medical device monitoring under FDA scrutiny. HIPAA compliance requirements shape audit-ready analytics pipeline demand across hospital networks. Industrial manufacturers in the Midwest integrate brownfield SCADA protocol translation to enable MQTT ingestion for predictive maintenance platforms.
France
Healthcare providers leverage cloud-based deployments to compress time-to-value for connected medical device analytics. ANSM and CNIL oversight forces investment in explainable inference modules for automated decision systems. Pharmaceutical manufacturers in the Île-de-France region pilot federated learning architectures for collaborative anomaly detection across supplier networks.
China
Industrial IoT infrastructure expansion accelerates edge computing deployment for latency-sensitive manufacturing control loops. MIIT standards and dual carbon goals drive energy telemetry analytics for mandatory sustainability disclosure. Yangtze River Delta manufacturing clusters localize telemetry processing to satisfy data sovereignty requirements.
United Kingdom
Healthcare providers invest in audit-ready analytics pipelines under NHS digital transformation programs. The UK Information Commissioner's Office enforces GDPR-aligned data routing constraints for cross-border telemetry. London-based financial services firms deploy connected device analytics for operational risk monitoring in critical infrastructure.
Connected Device Analytics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Connected Device Analytics Market. Cloud hyperscalers and industrial software incumbents command premium positioning through managed service wrappers that reduce in-house data engineering complexity. Strategic archetypes include full-stack platform vendors, edge-to-cloud networking specialists, and vertical-focused analytics pure-plays. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through sovereign cloud commitments.
Within the integrated platform tier, Microsoft Corporation and Amazon Web Services Inc. exemplify cloud-native deployment dominance, while Cisco Systems Inc. occupies a position anchoring edge-to-cloud networking architectures. These three entities represent the convergence of infrastructure scale with industrial vertical expertise, sitting within a competitive set where proprietary algorithmic differentiation commands premium pricing against commoditized data visualization layers.
| Leading Market Players |
|---|
| Oracle Corporation |
| Cisco Systems Inc. |
| Microsoft Corporation |
| Adobe Inc. |
| SAP SE |
| Amazon Web Services Inc. |
| Google LLC |
| PTC Inc. |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
GDPR certification tiers gate both supply qualification and price differentiation simultaneously. Healthcare providers in Germany and France demand ISO 27001-compliant pipelines, forcing vendors to absorb audit costs that stratify offerings across certified premium and uncertified economy tiers. Automotive suppliers in Stuttgart negotiate component-level procurement that fragments traditional SaaS bundles into discrete ingestion and inference pricing.
Pricing Analysis
German automotive buyers command 15-25% discounts against French healthcare providers for equivalent edge-computing deployments. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in GDPR certification depth and explainable AI module inclusion. Cost compression in the economy tier is intensifying because open-source visualization alternatives commoditize dashboard layers. Mid-market manufacturers in Baden-Württemberg exhibit highest price sensitivity, while FDA-scrutinized hospital networks accept premium positioning for audit-ready stacks.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for industrial-grade GPU and FPGA modules. Taiwan, South Korea, and Germany concentrate supply for specialized edge hardware, with Taiwanese foundries feeding 60% of European FPGA demand. The chain rests on MEMS sensor silicon, rare earth magnet components, and proprietary inference chip architectures. Single-source vulnerability concentrates in Taiwanese advanced packaging capacity. Distribution runs through systems integrators for edge deployments and direct enterprise sales for cloud-based consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive supplier networks in Germany, where Wolfsburg and Stuttgart procurement coalitions extract volume discounts that fragment vendor margin pools.
For Market Incumbents: Consolidate algorithmic IP through exclusive licensing agreements with equipment OEMs to lock out third-party analytics platforms. Deepen edge hardware partnerships with Taiwanese foundries to secure FPGA allocation priority against emerging cloud-native entrants. ISO 27001 certification investment represents the priority defensive lever as healthcare procurement hardens compliance gates.
For New Entrants and Emerging Players: ANSM fast-track certification for explainable inference modules opens immediate access to French hospital networks bypassing incumbent audit backlogs. Pharmaceutical cold chain operators in Bavaria present the most penetrable white-space target, with real-time deviation alerting gaps across temperature-sensitive biologics distribution. Federated learning pilots with Basel and Frankfurt manufacturers offer a differentiated go-to-market angle that sidesteps GDPR cross-border friction.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by devaluing non-explainable algorithmic assets and elevating audit-ready platform valuations. Long-term viability favors verticalized edge-to-cloud stacks with sovereign cloud commitments across the 5-10 year regulatory horizon. Target acquisition archetype: mid-cap specialists with embedded healthcare compliance documentation. The signal to watch is ANSM and FDA warning letter velocity against connected medical device analytics vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure IoT stack anchoring by Microsoft captures Stuttgart automotive workloads through middleware consolidation. |
| Strategic Partnership | Cisco edge-to-cloud networking alliances with German systems integrators sustain real-time telemetry pipeline dominance. |
| Acquisition of Specialist Firm | Proprietary anomaly detection algorithm purchases resolve licensing conflicts with equipment OEMs in predictive maintenance. |
| Geographic Expansion | Sovereign cloud commitments in France and Germany satisfy GDPR localization mandates for healthcare procurement. |
| Product Launch | Explainable inference module releases by AWS align with EU AI Act conformity obligations for automated decision systems. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, hospital procurement committees, and biomedical engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA device registrations, EU AI Act implementation guidance, and German automotive supplier association reports. Bottom-up telemetry pipeline deployment estimates triangulated against top-down platform vendor revenue disclosures.
Sensitivity analysis across deployment architecture, end-use vertical, and application focus shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cloud-edge-hybrid deployment patterns, healthcare-industrial-retail end-use stratification, and predictive maintenance versus asset tracking application splits. CAGRs derived from elasticity-adjusted adoption curves incorporating GDPR enforcement timelines and REACH substance restriction phase-ins.
Decision-makers should treat outputs as directional under sustained EU AI Act implementation and stable Taiwan semiconductor supply assumptions; material deviation would warrant model refresh. Specific risk factors include edge hardware cost volatility from foundry concentration and pharmaceutical cold chain regulatory acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
UK Geospatial Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Global Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Document Analytics Market
Analytics
North America Speech Analytics Market
Analytics
App Analytics Tools Market
Analytics
Data Preparation Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Data Discovery Market
Analytics
North America Crowd Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Practice Analytics Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Business Analytics Market
Analytics
Predictive and Prescriptive Analytics Market