
 North America Operational Intelligence Market | 2026-2036
North America Operational Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
North America Operational Intelligence Market Foresight
Manufacturing end user demand is hardening as the dominant vertical pull in the North America Operational Intelligence Market, with transportation and healthcare following at narrower scale. Splunk Inc. leverages its data-to-everything platform architecture to anchor enterprise security and observability workloads across Fortune 500 accounts. SAP SE sustains deep ERP integration advantages that embed operational intelligence directly into production planning workflows. Schneider Electric SE dominates the industrial edge, where its EcoStruxure platform competes on OT-IT convergence in energy-intensive process environments.
Operational intelligence denotes the discipline of capturing, correlating, and analyzing real-time data streams from distributed operational systems to generate actionable situational awareness, typically processing events within sub-second latency windows to trigger automated responses or alert human operators. Its primary commercial purpose centers on reducing mean-time-to-resolution for operational disruptions while optimizing asset utilization rates across complex physical-digital infrastructures. Cloud-based deployment now leads segment growth as enterprises exit capital-intensive on-premises data centers, though hybrid architectures retain margin concentration where regulated industries require localized data sovereignty. Within application segments, supply chain management commands the largest installed base while fraud detection registers the fastest expansion as financial services and insurance carriers harden real-time transaction monitoring against synthetic identity schemes.
US federal agencies including NIST and the Cybersecurity and Infrastructure Security Agency shape operational intelligence demand through zero-trust architecture mandates and critical infrastructure protection standards that compel continuous monitoring investments. State-level regulators in California and New York impose data privacy and breach notification requirements that influence how operational intelligence platforms architect data retention and cross-border flow controls. Canadian entities under Health Canada and the Office of the Privacy Commissioner face parallel pressures in healthcare and personal data governance, tightening procurement specifications for vendors serving cross-border deployments. Stakeholders must weigh the accelerating tension between cloud scalability and jurisdictional compliance complexity as they select platform architectures and geographic hosting strategies.
Market Dynamics
The North America Operational Intelligence Market pivots on federal infrastructure mandates compressing procurement timelines, with the Infrastructure Investment and Jobs Act forcing utilities and transportation operators into accelerated digital modernization cycles.
Growth Catalysts
- Zero-trust architecture mandates:CISA directives compel continuous monitoring investments across critical infrastructure operators, hardening real-time observability requirements.
- Great Lakes manufacturing density:Heavy industrial concentration across Michigan, Ohio, and Illinois generates concentrated deployment pull for predictive maintenance platforms.
- Cloud migration acceleration:Enterprises exiting capital-intensive data centers favor subscription-based operational intelligence delivery models.
Market Restraints
- OT-IT integration complexity:Industrial control system retrofitting demands specialized skill sets that remain scarce across the US Midwest and Canadian Prairies.
- Cross-border data friction:Divergent breach notification requirements between California, New York, and Canadian provincial regulators fragment platform architectures.
- Edge hardware supply concentration:Semiconductor and industrial sensor sourcing concentrates in East Asian foundries, exposing deployment timelines to geopolitical volatility.
Strategic Opportunities
- Healthcare operational intelligence:Health Canada compliance pressures create white space for real-time patient flow and equipment utilization analytics.
- AI-driven anomaly detection:Machine learning convergence with time-series databases enables sub-second automated response in energy grid management.
- Mid-market manufacturing penetration:Tier-two automotive suppliers across Ontario and Indiana remain underpenetrated relative to Fortune 500 adoption rates.
Industry Challenges
- Data engineering talent scarcity:Stream processing and complex event processing expertise lags platform deployment demand across US federal contractor pools.
- Legacy SCADA integration:Decades-old industrial control protocols resist seamless API connectivity, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Operational Intelligence Market |
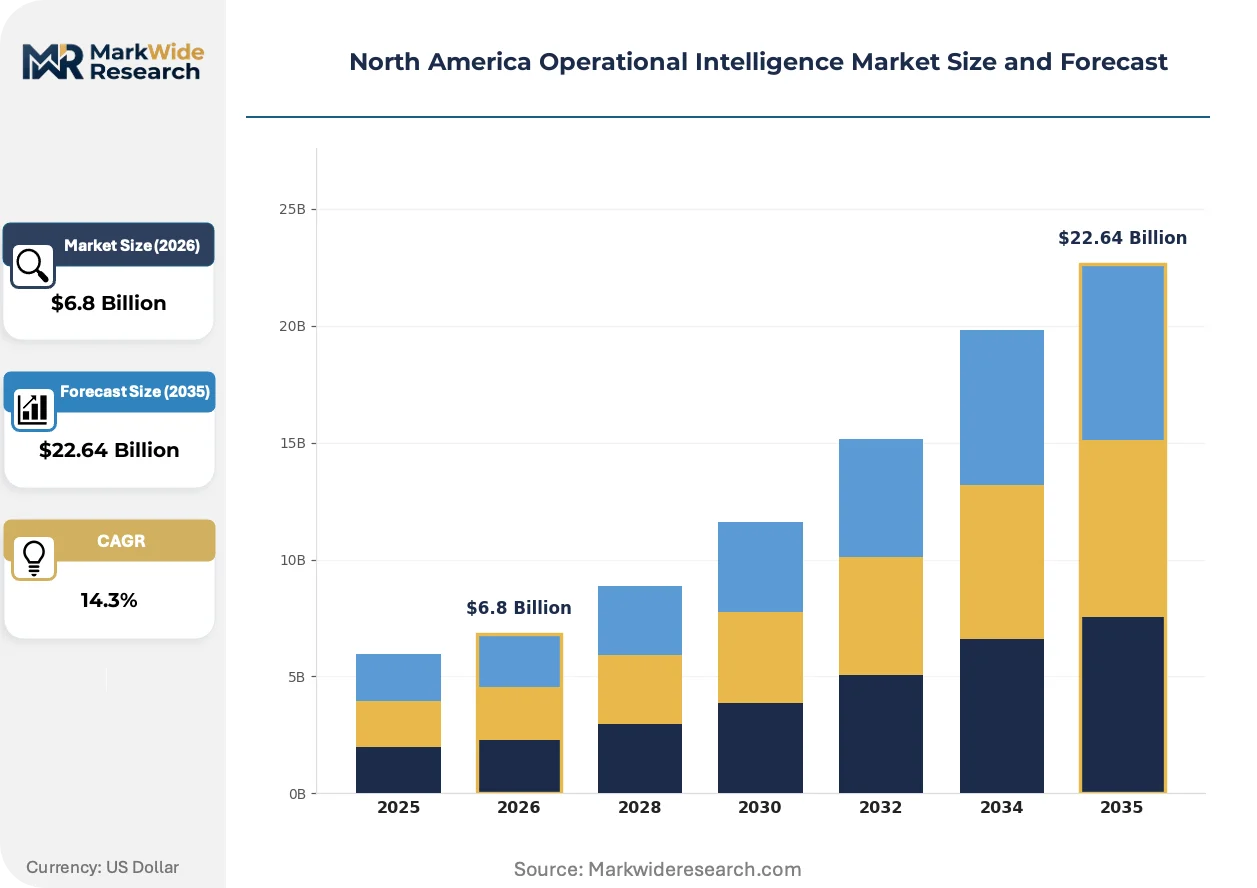
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.64 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Supply Chain Management, Fraud Detection, Risk Management, Asset Management End User: Manufacturing, Transportation, Retail, Healthcare Technology: Machine Learning, Big Data Analytics, IoT, Data Visualization |
| Companies Covered | Vitria Technology Inc., Splunk Inc., SAP SE, Software AG, Schneider Electric SE, OpenText Corporation, Hewlett Packard Enterprise Co., International Business Machines Corp., Starview Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Operational Intelligence Market Shifts & Advancements
Real-time streaming architectures are compressing decision latency windows across North American industrial operations, with sub-second event processing becoming the baseline expectation rather than premium capability.
Event-driven microservices architectures are overtaking batch-oriented data pipelines in operational intelligence deployments. Manufacturing and logistics operators in the US Great Lakes corridor adopt these frameworks to enable automated production line adjustments. This shift is overtaking traditional ETL-based business intelligence platforms that required hours for operational visibility.
US federal zero-trust security mandates from CISA and NIST reshape platform procurement specifications. Critical infrastructure operators must now demonstrate continuous verification of every data access request. Energy utilities and transportation authorities face the steepest compliance curves, driving demand for identity-aware operational intelligence stacks.
Outcome-based platform contracting is displacing traditional perpetual license models among mid-market manufacturers. Buyers now demand consumption-aligned pricing tied to measurable downtime reduction or throughput improvement. This pattern concentrates most visibly among automotive suppliers across Ohio and Michigan seeking to conserve working capital.
North America Operational Intelligence Market Segmentation
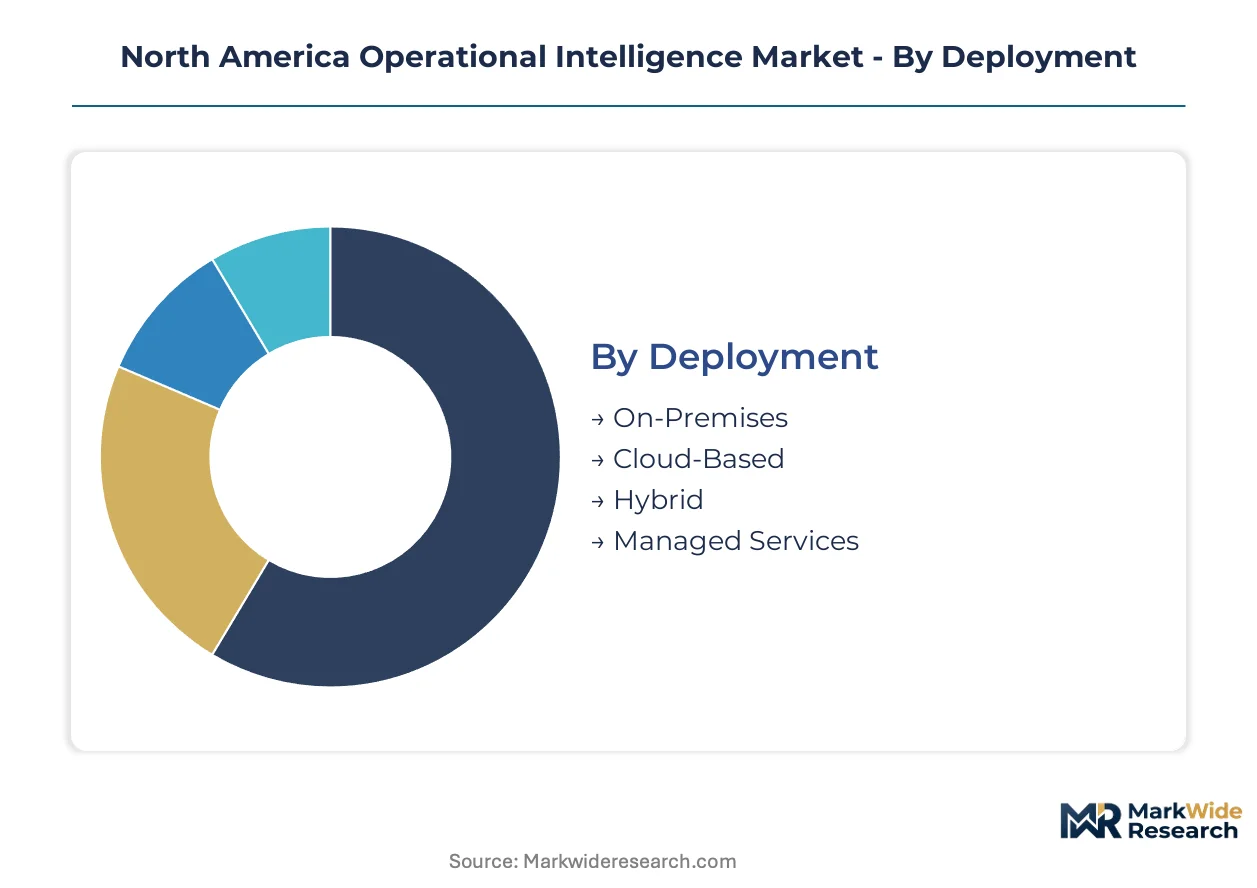
Operational intelligence platforms fragment across deployment architectures, application workloads, industry verticals, and underlying technology stacks. Each segmentation axis carries distinct procurement patterns, margin profiles, and integration complexity that shape vendor positioning and buyer decision frameworks across the US Great Lakes corridor and Canadian industrial centers.
Deployment:
Volume deployments concentrate in standardized cloud configurations, while premium capture sits with hybrid and managed service arrangements that address data sovereignty constraints.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure burdens for mid-market manufacturers. Demand clusters among automotive suppliers across Ohio and Indiana seeking rapid deployment without infrastructure overhead. Subscription economics align procurement with operational expenditure budgets.
- Hybrid:Split architectures retain sensitive operational technology data on-premises while pushing analytics workloads to cloud elasticity. Energy utilities under FERC reliability mandates favor this model for grid management systems requiring localized control with centralized intelligence.
- On-Premises:Fully captive infrastructure persists in defense contractors and classified federal facilities where air-gapped networks are mandatory.
- Managed Services:Third-party operational intelligence operations address talent scarcity in stream processing and complex event processing expertise.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Application:
Functional specialization divides procurement between operational optimization and protective intelligence, with risk and fraud workloads commanding premium pricing.
- Supply Chain Management:Real-time inventory positioning, demand sensing, and logistics orchestration dominate installed base across retail distribution networks. Walmart-scale operators and regional 3PL providers in Illinois deploy these systems for warehouse-to-shelf visibility compression.
- Fraud Detection:Synthetic identity schemes and transaction anomaly detection drive steepest expansion trajectory among financial services carriers. Real-time scoring engines process payment streams with sub-second latency requirements.
- Risk Management:Operational risk quantification and predictive failure modeling concentrate in process industries with catastrophic loss exposure.
- Asset Management:Condition-based maintenance and utilization optimization target heavy manufacturing equipment across Michigan automotive assembly plants.
Revenue concentration favors Supply Chain Management. Fastest capability maturation is occurring in Fraud Detection.
End User:
Industry verticals exhibit divergent latency tolerance, data granularity requirements, and regulatory overlay density that shape platform configuration.
- Manufacturing:Predictive maintenance and throughput optimization anchor the dominant vertical pull. Heavy industrial concentration across Michigan, Ohio, and Illinois generates concentrated deployment opportunities for real-time production line analytics.
- Healthcare:Patient flow optimization and equipment utilization analytics face Health Canada compliance pressures in Ontario and HIPAA constraints across US hospital systems. Real-time bed management and OR scheduling command premium pricing.
- Transportation:Fleet telematics and route optimization serve logistics density in the Great Lakes freight corridor.
- Retail:Demand forecasting and inventory positioning systems serve omnichannel fulfillment networks.
Procurement maturity sits with Manufacturing. Fastest budget expansion is occurring in Healthcare.
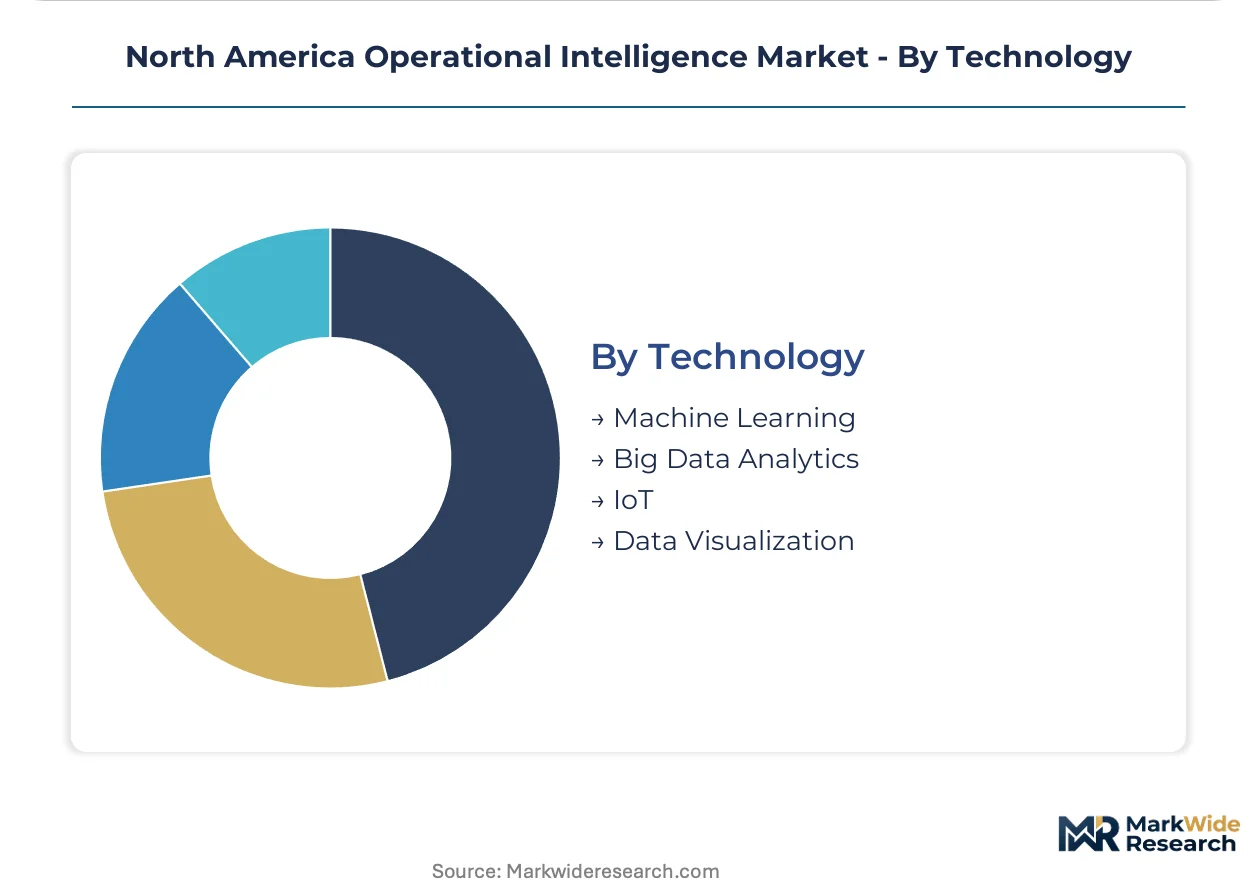
Technology:
Core technology layers stack from data ingestion through inference to presentation, with machine learning and IoT edge processing driving architectural differentiation.
- Machine Learning:Supervised and unsupervised models for anomaly detection, demand forecasting, and automated decisioning. Time-series forecasting and predictive maintenance algorithms concentrate development investment.
- IoT:Sensor data ingestion, edge preprocessing, and device management for industrial control system integration. OT-IT convergence demands specialized protocol adapters for decades-old SCADA environments.
- Big Data Analytics:Distributed stream processing and complex event processing engines handle velocity and volume requirements.
- Data Visualization:Operational dashboards and alerting interfaces compress decision latency for control room operators.
Platform differentiation sits with Machine Learning. Fastest infrastructure buildout is occurring in IoT.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes industrial corridor functions as North America's dominant operational intelligence concentration zone, with federal infrastructure incentives compressing procurement timelines across heavy manufacturing and energy utilities.
United States
The Infrastructure Investment and Jobs Act channels federal investment toward digital infrastructure modernization, accelerating demand for operational intelligence systems. CISA zero-trust architecture mandates compel continuous monitoring investments across critical infrastructure operators. Demand concentrates most intensively across the US Great Lakes industrial corridor spanning Michigan, Ohio, and Illinois, where heavy manufacturing and logistics density create concentrated deployment opportunities.
Canada
Health Canada compliance pressures create white space for real-time patient flow and equipment utilization analytics in Ontario and Quebec hospital systems. The Office of the Privacy Commissioner imposes data privacy requirements that influence how operational intelligence platforms architect data retention and cross-border flow controls. Canadian entities under federal and provincial regulators face parallel pressures in healthcare and personal data governance, tightening procurement specifications for vendors serving cross-border deployments.
Mexico
Automotive manufacturing expansion across Nuevo León and the Bajío Region generates demand for predictive maintenance platforms as tier-one suppliers modernize production lines. Mexico's federal economic development programs incentivize smart factory investments near US border logistics corridors. Industrial clusters in Tijuana and Monterrey are adopting real-time analytics to optimize production throughput and reduce unplanned downtime for export-oriented assembly operations.
North America Operational Intelligence Market Competitive Landscape
Top-tier vendors anchor the enterprise platform tier, while specialized industrial edge providers and mid-market SaaS challengers occupy differentiated positions below. The vendor base organizes around three strategic archetypes: data-to-everything platform generalists, ERP-embedded operational intelligence specialists, and industrial edge convergence leaders. Dominant competitive moves include strategic partnerships for OT-IT integration capability and portfolio diversification into AI-driven anomaly detection.
Within the platform generalist tier, Splunk Inc. and SAP SE exemplify divergent architectural approaches—Splunk anchoring enterprise security and observability workloads, SAP sustaining deep ERP integration advantages that embed operational intelligence directly into production planning workflows. Schneider Electric SE occupies a distinct position on the industrial edge, where its platform competes on OT-IT convergence in energy-intensive process environments. These three vendors represent the primary competitive vectors shaping procurement decisions across Fortune 500 accounts and mid-market manufacturing alike.
| Leading Market Players |
|---|
| Vitria Technology Inc. |
| Splunk Inc. |
| SAP SE |
| Software AG |
| Schneider Electric SE |
| OpenText Corporation |
| Hewlett Packard Enterprise Co. |
| International Business Machines Corp. |
| Starview Inc. |
| Others |
Supply & Pricing Matrix
Federal critical infrastructure operators under CISA zero-trust mandates anchor premium pricing power for compliant operational intelligence platforms, with subscription tiers scaling to audit-ready security certifications. This buyer concentration rewards vendors who embed continuous monitoring capabilities into standardized SaaS offerings while compressing margins for non-compliant alternatives.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to hybrid deployments requiring rapid OT-IT integration, while spot inventory discounts emerge for standardized cloud configurations. The dominant structure is three-tier pricing across premium, standard, and economy levels, with differentiation driven by ISO 27001 certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because mid-market manufacturers conserve working capital. Federal contractors show least price sensitivity; tier-two automotive suppliers in Indiana and Ohio exhibit highest sensitivity.
Supply Chain Analysis
Domestic-content provisions in the Infrastructure Investment and Jobs Act are reshaping sourcing for edge hardware and industrial sensors, compelling vendors to qualify North American component suppliers. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; industrial sensor assembly draws from China, Mexico, and Germany. Single-source vulnerability in advanced GPU supply for machine learning inference creates deployment timeline risk. Distribution runs through systems integrators serving the Great Lakes manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
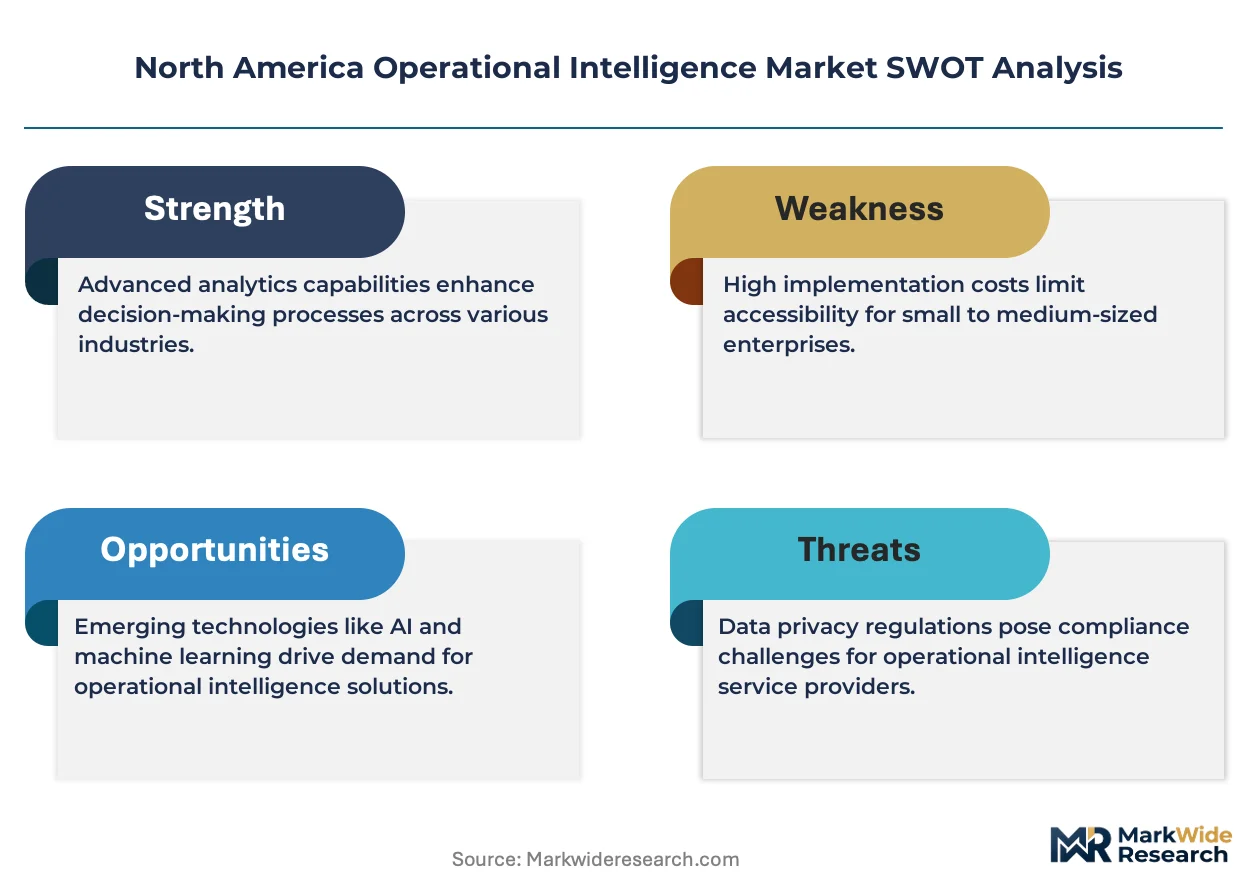
CISA zero-trust architecture mandates have erected a cost-of-compliance barrier that rewards incumbent platform vendors with pre-certified security stacks while filtering out undercapitalized challengers unable to sustain continuous audit cycles.
For Market Incumbents: Extend platform stickiness through deeper ERP integration partnerships that embed operational intelligence into production planning workflows, countering the threat of specialized industrial edge providers. Prioritize certification investment in Health Canada and FDA-aligned data governance modules to capture healthcare budget expansion. For New Entrants and Emerging Players: Begin with outcome-based contracting for mid-market automotive suppliers across Ontario and Indiana, where underpenetration relative to Fortune 500 adoption rates creates accessible white space. Target consumption-aligned pricing tied to measurable downtime reduction as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors vertical SaaS specialists with pre-built OT protocol adapters and existing SCADA integration capabilities. Acquisition targets should demonstrate proven deployment velocity in energy utilities under FERC reliability mandates. Watch for inflection when tier-one automotive OEMs mandate real-time supplier visibility as a procurement condition.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP embedding captures manufacturing planning workflows across Michigan and Ohio assembly plants. |
| Strategic Partnership | OT-IT systems integrator alliances accelerate deployment velocity in legacy SCADA environments. |
| Acquisition of Specialist Firm | Time-series database expertise addresses sub-second latency requirements in energy grid management. |
| Geographic Expansion | Ontario and Quebec healthcare penetration leverages Health Canada compliance pressure for patient flow analytics. |
| Product Launch | AI-driven anomaly detection modules target fraud detection expansion in financial services carriers. |
Research Methodology
Document review covered SEC 10-K filings from operational intelligence vendors, FERC reliability mandate documentation, and CISA zero-trust architecture directives, complemented by interviews with plant engineers at Great Lakes manufacturing facilities, IT procurement officers at energy utilities, and channel partners specializing in OT-IT integration. Secondary validation drew from hyperscaler capex disclosures, Health Canada procurement databases, and customs records for industrial sensor imports. Bottom-up deployment estimates and top-down market sizing were triangulated to anchor volume projections.
Historical adoption curves for manufacturing analytics platforms were cross-referenced against panel input from platform engineers and integration specialists to calibrate deployment velocity assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, application workload, and integration complexity tier. CAGRs were derived from elasticity-adjusted penetration rates applied to addressable manufacturing and utility capital expenditure baselines, with specific inputs for cloud migration acceleration and federal infrastructure incentive timing.
Geopolitical disruption to semiconductor supply, divergence in cross-border data governance between US states and Canadian provinces, and talent scarcity in stream processing expertise are the dominant revision risks that could compress or extend deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Process Analytics Market
Analytics
Sweden ICT Market
Analytics
Workforce Analytics Market
Analytics
Contact Center Analytics Market
Analytics
South Korea Contact Center Analytics Market
Analytics
Brazil Big Data Analytics Market
Analytics
Network Analytics Services Market
Analytics
Global E-Commerce Analytics Software Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Global Recommendation Engine Market
Analytics
Japan Geospatial Analytics Market
Analytics
Event Stream Processing Market
Analytics
Complex Event Processing Market
Analytics
Global Digital Intelligence Platform Market
Analytics
Embedded Analytics Software Market
Analytics
Business Intelligence (BI) Market