
 Construction Ceramics Market | 2026-2036
Construction Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Ceramics Market Outlook
Italian tile producers is consolidating capacity around digital printing and large-format slab technology. Mohawk Industries leverages vertical integration across North American distribution to sustain margin control. RAK Ceramics anchors Middle Eastern supply through integrated clay-to-showroom operations. Kajaria Ceramics dominates India's branded tile segment with extensive retail networks.
Construction ceramics encompass fired clay-based materials including tiles, bricks, and sanitary ware, typically produced through kiln sintering at temperatures exceeding 1,000 degrees Celsius to achieve compressive strength and moisture resistance for building envelopes. Tiles leads product type demand due to replacement cycles in residential flooring, while sanitary ware captures premium margin pools from commercial hospitality projects. The wall cladding application segment competes with alternative finishes through thin-profile porcelain solutions that reduce structural load.
EPA emissions standards in the United States and REACH chemical registration in Europe constrain traditional glaze formulations, redirecting R&D toward low-VOC and recycled-content certifications. India's BIS mandatory quality standards for ceramic tiles reshape import access and domestic manufacturing compliance requirements. Stakeholders must monitor evolving carbon border adjustments and embodied-carbon disclosure rules that will redefine competitive positioning in cross-border procurement decisions.
Market Dynamics
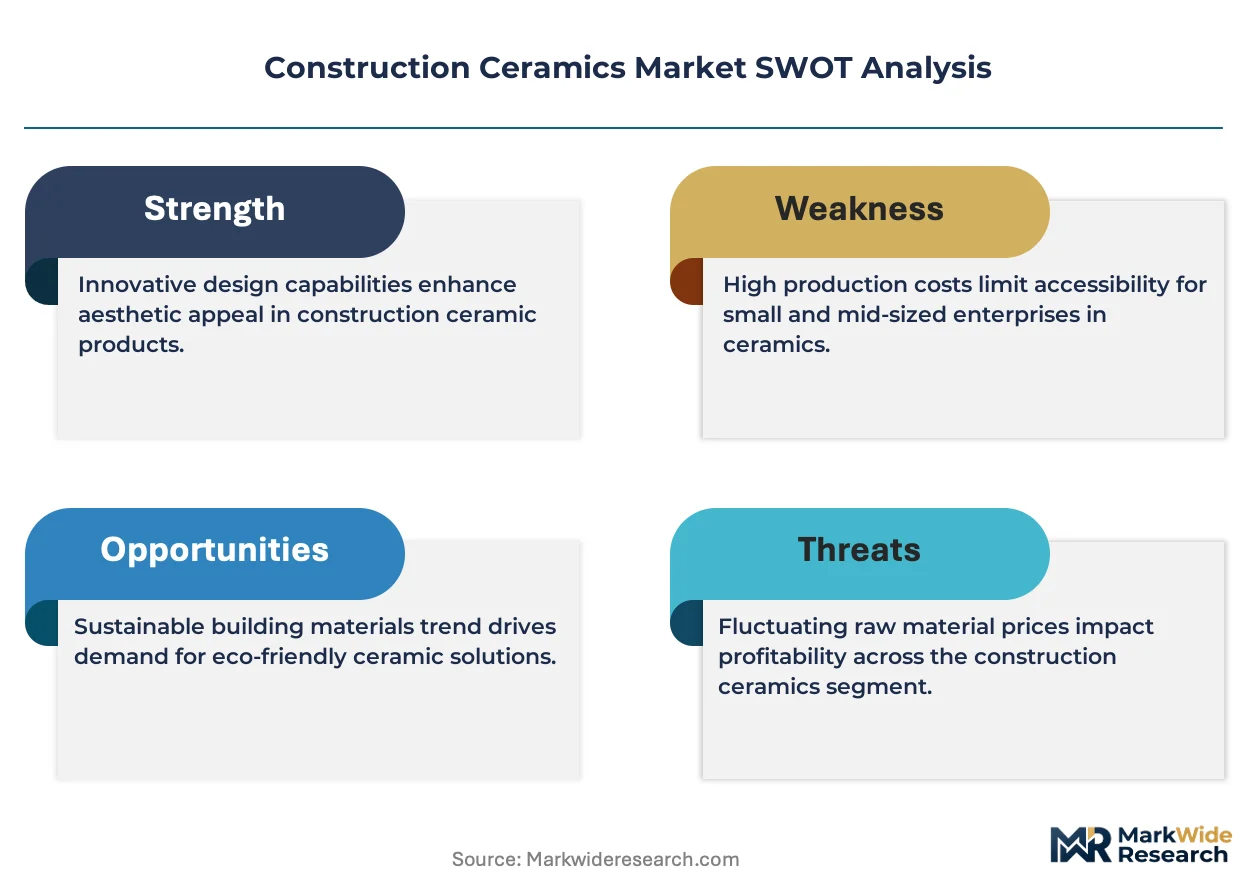
Kiln electrification and natural gas price volatility are forcing capital reallocation across ceramic manufacturing clusters, while REACH compliance deadlines compress formulation timelines for glaze chemists.
Growth Catalysts
- Urban housing densification:India's Pradhan Mantri Awas Yojana accelerates tile procurement for multi-story residential towers in Maharashtra and Gujarat.
- Thin-profile porcelain technology:Large-format slab production reduces structural load per square meter, expanding wall cladding applications in high-rise commercial envelopes.
- REACH chemical registration:European emissions standards redirect R&D investment toward low-VOC formulations, creating certification premiums for compliant producers.
Market Restraints
- Natural gas input volatility:Kiln energy costs represent 25-35% of tile production expenses, exposing margins to European pipeline supply disruptions.
- Kaolin supply concentration:High-grade ceramic clay deposits cluster in Brazil and Ukraine, creating geographic single-source vulnerability for sanitary ware producers.
- Frit import dependency:Specialized glaze materials concentrate in Italian and Spanish chemical suppliers, limiting formulation flexibility for Asian manufacturers.
Strategic Opportunities
- Vietnam manufacturing expansion:Underdeveloped domestic tile capacity meets ASEAN infrastructure investment flows, attracting kiln technology transfers from established producers.
- Recycled-content certification:EU Green Deal embodied-carbon disclosure rules create demand for post-industrial ceramic waste incorporation in new production.
- Direct-to-contractor digital platforms:B2B procurement channels bypass traditional distributor markups for mid-scale commercial renovation projects.
Industry Challenges
- Kiln operator skill scarcity:Electrified tunnel kiln management requires electrical engineering competencies distinct from legacy gas-fired combustion expertise.
- BIS certification timelines:India's mandatory quality standard testing creates 4-6 month product approval delays for imported tile lines.
- Digital printing integration complexity:Legacy roller kiln configurations require substantial modification to accommodate inkjet decoration lines without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Ceramics Market |
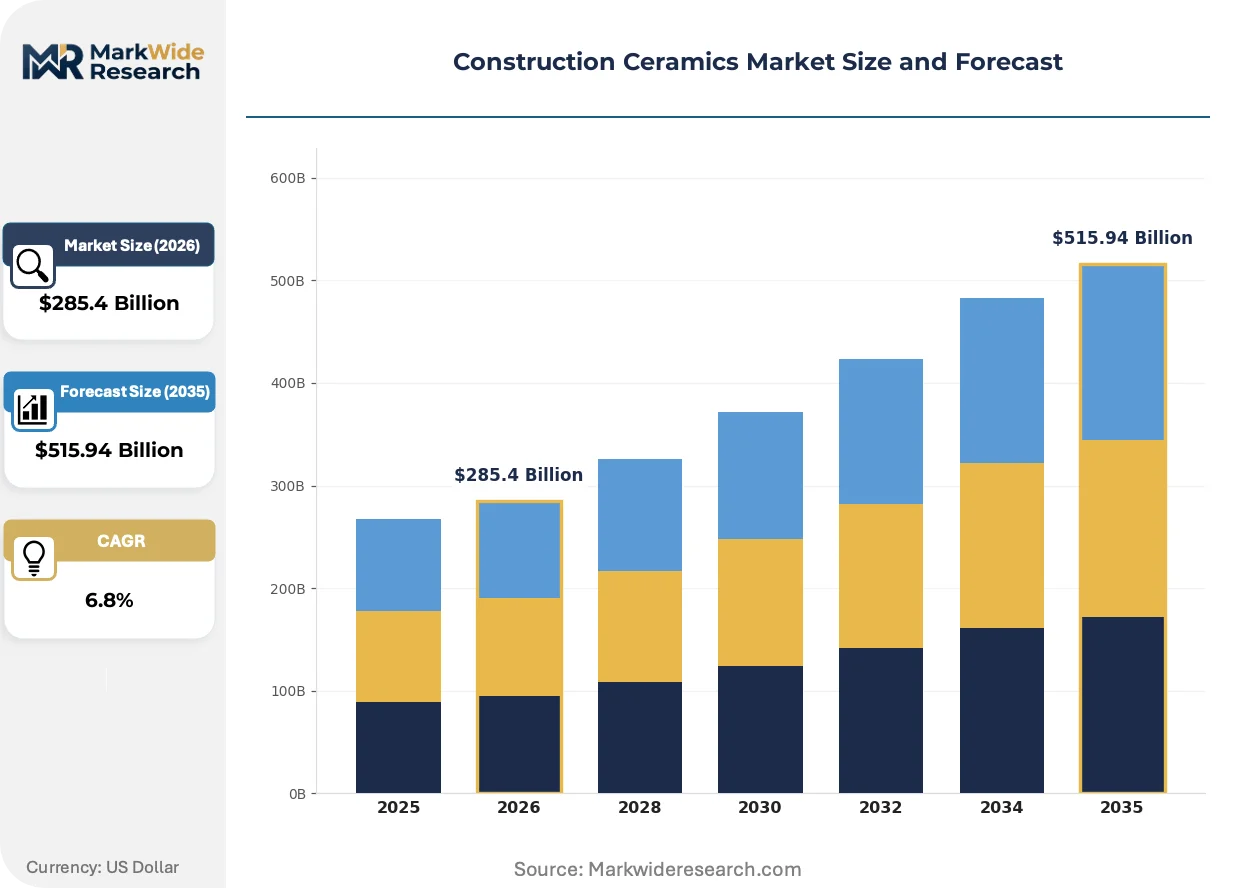
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $515.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tiles, Bricks, Sanitary Ware, Tableware End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Online, Offline, Wholesale, Retail Application: Flooring, Wall Cladding, Facades, Decorative Elements |
| Companies Covered | Mohawk Industries, RAK Ceramics, Kajaria Ceramics, Grupo Lamosa, SCG Ceramics, PORCELANOSA Grupo, Atlas Concorde, Saint-Gobain, Dong Peng Porcelain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Ceramics Market Strategic Shifts
Digital decoration systems and low-carbon kiln architectures are compressing traditional manufacturing timelines while expanding aesthetic possibilities for architectural specification.
Industrial inkjet printing is integrating high-resolution surface replication technology into standard tile production workflows. Hospitality and luxury residential specifiers now specify marble- and wood-look porcelain at volumes exceeding natural material procurement. This capability is integrating premium aesthetics into mid-market price tiers, compressing differentiation windows for traditional quarried stone suppliers.
EPA emissions standards in the United States constrain traditional glaze formulations containing heavy metal pigments. Tile manufacturers reformulate frit compositions to eliminate chromium and cobalt compounds ahead of compliance deadlines. Commercial flooring segments in California and New York metro areas show strongest response, with specification databases flagging low-VOC certified products for public project eligibility.
Architects and developers now bundle tile specification with embodied-carbon accounting for whole-building LCA submissions. Large commercial contractors in Germany and the Netherlands require EPD documentation for all interior finish materials, displacing traditional aesthetic-only selection criteria. This pattern concentrates most visibly in BREEAM and LEED pursuit projects across Northern European commercial construction.
Construction Ceramics Market Segmentation
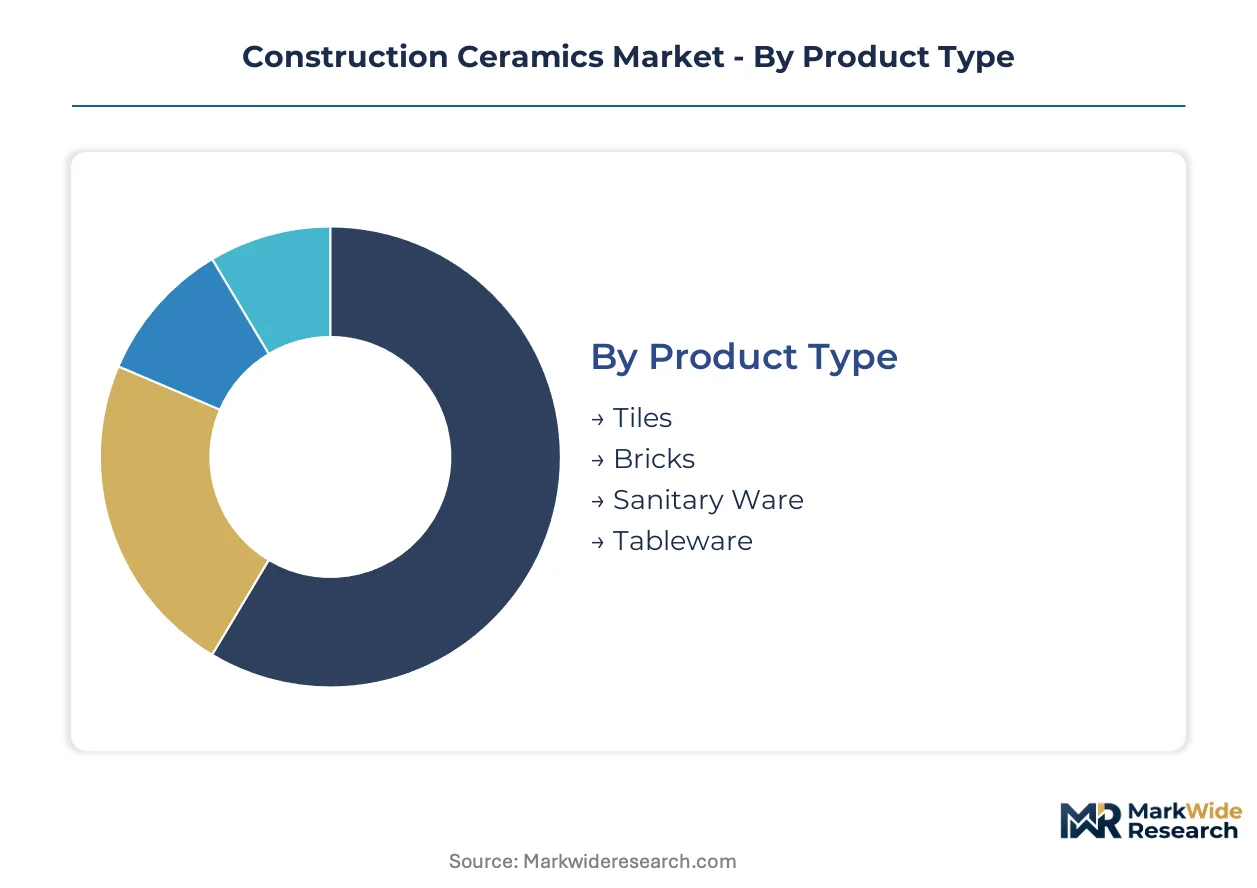
Construction ceramics demand fragments across distinct technical specifications and procurement channels. Each segment carries unique margin profiles and regulatory exposure that reshape competitive positioning. Understanding these fault lines reveals where capital allocation and compliance investment concentrate.
Product Type:
Supply concentration clusters around kiln-scale operations and clay deposit proximity, with technology leaders consolidating around digital decoration and large-format capabilities.
- Tiles:Fired clay slabs with glazed or unglazed surfaces, typically 6-12mm thickness for flooring and wall applications. Demand concentrates in India's urban housing programs across Maharashtra and Gujarat, where multi-story residential towers specify porcelain and ceramic variants for moisture resistance and replacement-cycle durability.
- Sanitary Ware:Vitreous china fixtures including toilets, basins, and cisterns fired above 1,200°C for non-porous surfaces. Premium margin pools concentrate in commercial hospitality projects across Dubai and Riyadh, where integrated clay-to-showroom operations capture specification influence through architect relationships.
- Bricks:Structural clay units for load-bearing walls and facades, produced through tunnel kiln firing at 900-1,100°C. Traditional masonry applications persist in Southeast Asian residential foundations.
- Tableware:Ceramic dining and kitchen articles including plates, bowls, and serving pieces. Hospitality procurement in European commercial developments drives specification for durability and aesthetic coordination.
Today's leader: Tiles. Tomorrow's challenger: Sanitary Ware.
End User:
Cost tier differentiation separates specification-driven commercial projects from price-sensitive residential procurement, with infrastructure emerging as a volume anchor for standardized products.
- Residential:Single-family homes, apartments, and multi-unit dwellings requiring flooring, bathroom fixtures, and kitchen surfaces. India's Pradhan Mantri Awas Yojana accelerates tile procurement for affordable housing towers, while replacement cycles in European renovation sustain aftermarket demand.
- Commercial:Office buildings, retail spaces, hotels, and restaurants specifying premium finishes for brand expression. Thin-profile porcelain technology reduces structural load per square meter in high-rise commercial envelopes across German and Dutch BREEAM pursuit projects.
- Industrial:Manufacturing facilities, warehouses, and processing plants requiring chemical-resistant flooring and drainage systems. Heavy-duty quarry tiles serve food processing and pharmaceutical cleanroom specifications.
- Infrastructure:Transportation terminals, public utilities, and civic buildings procuring through government tender processes. Standardized specifications prioritize durability over aesthetic differentiation in airport and railway station applications.
Commercial procurement commands premium positioning. Infrastructure volume is climbing the fastest as public investment flows accelerate.
Distribution Channel:
Geography of demand shapes channel configuration, with urban density favoring direct contractor platforms and rural markets sustaining traditional wholesale networks.
- Online:E-commerce platforms and digital procurement portals enabling specification comparison and direct ordering. B2B channels bypass traditional distributor markups for mid-scale commercial renovation projects in digitally mature markets.
- Offline:Physical showrooms, dealer networks, and architect specification centers supporting tactile material evaluation. Kajaria Ceramics anchors India's branded tile segment through extensive retail networks enabling consumer trust.
- Wholesale:Bulk procurement channels serving contractors, developers, and project aggregators with volume pricing and logistics coordination. RAK Ceramics leverages integrated operations to supply Middle Eastern wholesale tiers.
- Retail:Home improvement centers and specialty tile shops targeting homeowner renovation and DIY replacement cycles. Mohawk Industries sustains margin control through vertical integration across North American retail distribution.
Offline wholesale retains volume dominance. Online B2B platforms show steepest expansion trajectory in commercial specification workflows.
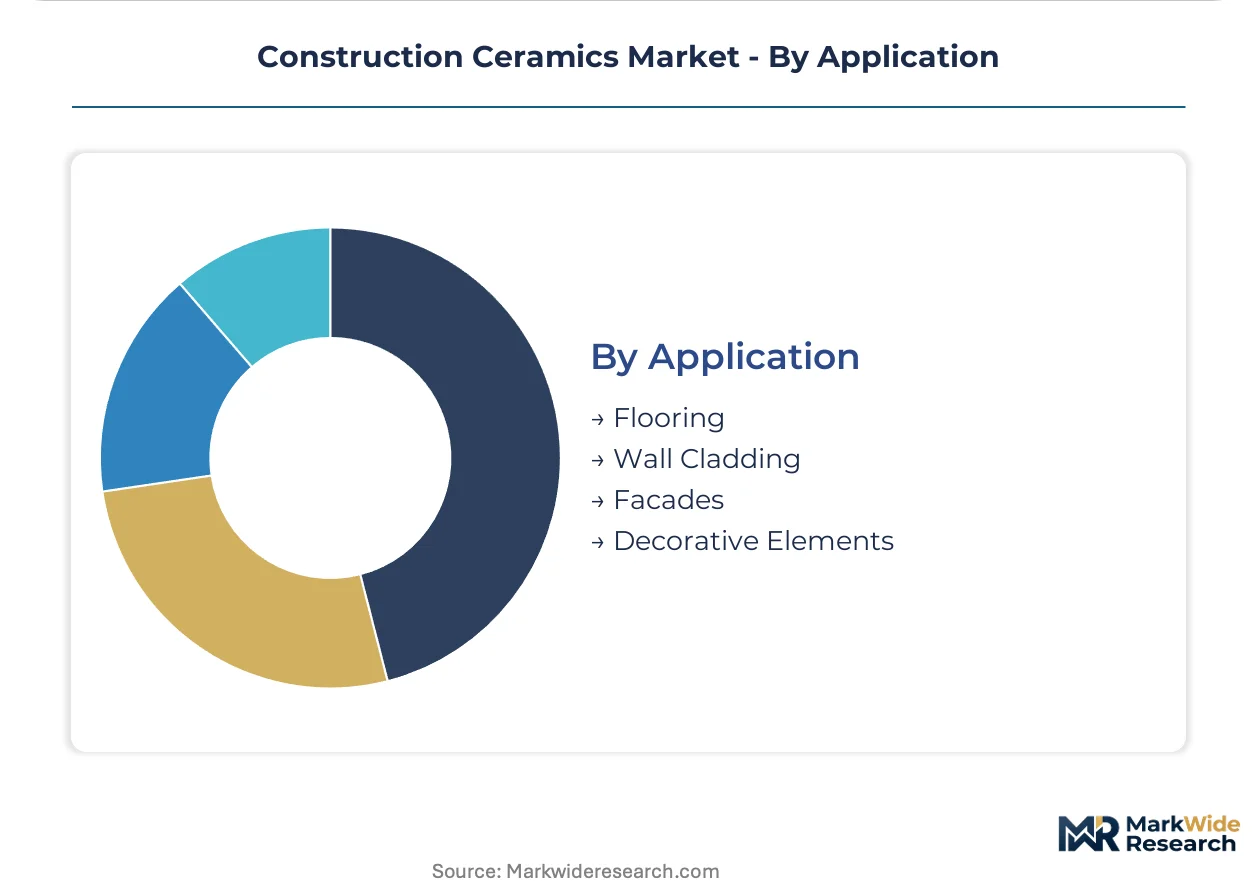
Application:
Margin structure varies by installation complexity and performance certification requirements, with facade applications commanding technical premium over interior finishes.
- Flooring:Horizontal surface installations requiring abrasion resistance, slip coefficient ratings, and load-bearing capacity. Replacement cycles in residential flooring sustain tile demand against competing resilient materials.
- Wall Cladding:Vertical surface applications competing with alternative finishes through thin-profile porcelain solutions. Large-format slab production expands high-rise commercial envelope specifications by reducing structural load.
- Facades:Exterior building envelopes requiring freeze-thaw resistance, thermal performance, and structural anchoring systems. Ventilated rainscreen configurations integrate ceramic panels with insulation and drainage cavities.
- Decorative Elements:Accent features, mosaic installations, and architectural ornamentation specifying custom colors and surface textures. Digital printing enables marble- and wood-look replication at volumes exceeding natural material procurement.
Wall cladding captures specification influence. Facade systems are gaining share fastest as energy code compliance tightens envelope performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where energy costs and emissions compliance create arbitrage opportunities for kiln operators. European REACH deadlines compress formulation timelines while Asian urban housing programs absorb capacity expansion.
India
Maharashtra and Gujarat anchor tile demand through Pradhan Mantri Awas Yojana procurement for multi-story residential towers. BIS mandatory quality standards reshape import access and domestic manufacturing compliance requirements. Morbi in Gujarat concentrates ceramic production clusters where kiln electrification trials intersect with natural gas price volatility.
China
Yangtze River Delta and Pearl River Delta manufacturing bases supply thin-profile porcelain technology for high-rise commercial envelopes. GB standards and dual carbon goals redirect R&D toward low-carbon kiln architectures. Foshan in Guangdong Province hosts digital printing integration clusters competing on marble-look replication capabilities.
Italy
Emilia-Romagna tile producers consolidate capacity around digital decoration and large-format slab technology for hospitality specification. REACH chemical registration constrains traditional glaze formulations containing heavy metal pigments. Sassuolo industrial district maintains frit chemistry expertise despite formulation compliance compression.
United States
California and New York metro commercial flooring segments flag low-VOC certified products for public project eligibility. EPA emissions standards constrain chromium and cobalt compounds in glaze compositions. Tennessee and Alabama manufacturing clusters leverage regional natural gas infrastructure against European pipeline disruption exposure.
Vietnam
Underdeveloped domestic tile capacity meets ASEAN infrastructure investment flows through kiln technology transfers. Urban densification in Ho Chi Minh City and Hanoi drives procurement for residential and commercial envelopes. Northern industrial zones attract equipment relocation from established producers seeking labor cost differentials.
Construction Ceramics Market Competitive Environment
Italian and Spanish producers anchor premium-tier specification influence through digital decoration expertise; Chinese and Indian fabricators hold volume positions through scale-driven cost structures. The vendor base stratifies across three tiers: integrated clay-to-showroom operators, regional wholesale suppliers, and specialized technology licensors. Strategic moves concentrate on kiln electrification partnerships and recycled-content certification acquisition ahead of EU Green Deal disclosure deadlines.
Among integrated operators, Mohawk Industries, RAK Ceramics, and Kajaria Ceramics occupy positions spanning North American distribution control, Middle Eastern supply anchoring, and Indian retail network density respectively. These entities exemplify archetypes of backward integration into raw material sourcing, captive logistics coordination, and showroom-based specification capture. Each represents a distinct geographic clustering strategy—North American vertical control, Gulf-based regional hub positioning, and subcontinental branded retail penetration—without convergence on uniform operating models.
| Leading Market Players |
|---|
| Mohawk Industries |
| RAK Ceramics |
| Kajaria Ceramics |
| Grupo Lamosa |
| SCG Ceramics |
| PORCELANOSA Grupo |
| Atlas Concorde |
| Saint-Gobain |
| Dong Peng Porcelain |
| Others |
Value Chain & Pricing Dynamics
India's Pradhan Mantri Awas Yojana procurement specifications for moisture-resistant porcelain in multi-story residential towers force supply reallocation toward Gujarat and Maharashtra production clusters, compressing delivered-cost differentials between domestic and imported tile lines.
Pricing Analysis
Distributor markups of 15-25% separate factory gate from retail shelf across Indian and Southeast Asian markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with BIS-compliant products commanding 8-12% premiums over uncertified imports. Pricing pressure stems from natural gas input volatility in European kiln operations, eroding margin buffers for Italian and Spanish exporters. Infrastructure contractors exhibit highest price sensitivity, while hospitality specifiers absorb premium tiers for marble-look digital replication.
Supply Chain Analysis
Kiln operator skill scarcity in Vietnam's northern industrial zones constrains throughput ramp-up despite equipment transfers from established Chinese producers. High-grade kaolin deposits concentrate in Brazil and Ukraine, while specialized frit chemistry clusters in Italy's Sassuolo district. Single-source vulnerability in Ukrainian clay feedstock threatens sanitary ware producers' formulation consistency. Distribution runs through integrated clay-to-showroom operators in the Middle East and wholesale contractor networks in India's Morbi cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-profile porcelain technology adoption compresses structural load costs for high-rise developers, expanding addressable margin pools for producers mastering large-format slab production at mid-market price points.
For Market Incumbents: Deepen backward integration into captive kaolin sourcing to offset Brazilian and Ukrainian supply concentration risks. Prioritize kiln electrification partnerships in Gujarat and Tennessee manufacturing clusters ahead of EPA emissions compliance deadlines. Cement architect specification relationships through EPD documentation for BREEAM and LEED pursuit projects in Northern Europe. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable channel wedge for mid-scale commercial renovation workflows in digitally mature North American and Western European markets. Target Vietnam's underdeveloped domestic tile capacity where ASEAN infrastructure investment flows exceed local supply response. Lead with recycled-content certification to capture EU Green Deal embodied-carbon disclosure premiums. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated clay-to-showroom operators possessing captive logistics and showroom-based specification capture. Long-term viability hinges on electrified kiln architecture deployment and low-VOC formulation portfolios. Watch for carbon border adjustment implementation signals as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Electrification Partnership | EPA and REACH compliance deadlines force capital reallocation away from gas-fired combustion infrastructure. |
| Recycled-Content Certification Acquisition | EU Green Deal embodied-carbon disclosure rules create demand for post-industrial ceramic waste incorporation. |
| Digital Printing Integration | Foshan and Sassuolo clusters compete on marble-look replication capabilities for hospitality specification. |
| Direct-to-Contractor Platform Launch | B2B procurement channels bypass traditional distributor markups in mid-scale commercial renovation segments. |
| Backward Integration into Kaolin Sourcing | Brazilian and Ukrainian deposit concentration creates geographic single-source vulnerability for sanitary ware producers. |
Study Parameters
Bottom-up residential and commercial construction modeling reconciled against top-down kiln capacity and clay deposit tracking forms the analytical core. Primary interviews with plant managers, procurement leads at tile distributors, architect specification directors, and ceramic R&D chemists combined with secondary validation from customs trade data, BIS certification registries, SEC 10-K filings, and ECHA REACH submission databases. Triangulation across supply-side capacity announcements and demand-side project pipelines ensures coherence.
Historical trendline analysis of tile production volumes, kiln energy input costs, and specification database flags for low-VOC certified products informs projection modeling across product type, end user, distribution channel, and application dimensions. CAGRs derive from segment-level growth rate reconciliation against macro construction spending patterns. Forecast inputs incorporate natural gas price volatility scenarios and BIS certification timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation and electrified kiln technology cost curves. Forecasts reflect documented assumptions about urban housing densification rates and REACH compliance deadline adherence. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
United States Ceramics Tableware Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Titanates Market
Ceramics
Industrial Ceramics Market
Ceramics
Thermal Spray Powder Market
Ceramics
Calcined Bauxite Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Asia-Pacific Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Refractories Market
Ceramics
Alumina Slurry Market
Ceramics
Titanium Carbide Market