
 Global Wired Interface Market | 2026-2036
Global Wired Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wired Interface Market Foresight
USB4 and Thunderbolt 4 certification is reorganizing supplier eligibility across the Global Wired Interface Market. TE Connectivity leverages its vertical integration in connector manufacturing to sustain leadership in high-speed copper assemblies. NXP Semiconductors anchors its position through automotive-grade interface controllers that meet AEC-Q100 qualification. Cypress Semiconductor Corporation specializes in programmable USB controllers that differentiate its portfolio against commodity PHY vendors.
Wired interface comprises physical layer connectivity solutions that transmit electrical or optical signals between electronic systems, typically operating at data rates from USB 2.0's 480 Mbps to Thunderbolt 4's 40 Gbps over shielded twisted pair or active optical cable constructions. These assemblies enable synchronous data exchange, power delivery, and protocol translation across dissimilar computing platforms. USB and Ethernet interface types occupy the largest installed base in enterprise and consumer applications, while Thunderbolt and active optical cable segments command premium pricing in broadcast equipment and data center deployments where bandwidth density and reach requirements exceed copper limitations. HDMI and DisplayPort interfaces compete for video-centric applications in industrial automation and aerospace systems, with DisplayPort gaining ground in multi-monitor enterprise configurations.
FCC equipment authorization rules in the United States govern electromagnetic emissions from wired interface assemblies, while EU REACH and RoHS directives restrict hazardous substances in connector plating and cable jacketing across European supply chains. Japan's METI enforces JIS standards for industrial communication interfaces that shape procurement specifications for automation OEMs. Stakeholders must monitor evolving USB-IF and IEEE protocol standards alongside national spectrum management policies that could redefine shielding and grounding requirements for next-generation copper and optical interconnects.
Market Dynamics
Protocol certification requirements under USB-IF and IEEE standards are restructuring supplier eligibility across copper and optical interconnect categories, forcing component vendors to absorb recurring compliance costs while tier-1 OEMs consolidate qualified vendor lists.
Growth Catalysts
- EU AI Act mandates:Auditable data transmission standards in Germany and France are accelerating server interconnect deployments in hyperscale data centers.
- Automotive Ethernet adoption:AEC-Q100 qualification requirements are expanding addressable market for interface controllers in electric vehicle architectures.
- Broadcast bandwidth density:Japanese equipment manufacturers are sourcing fiber optic DisplayPort and Thunderbolt assemblies for 8K production workflows.
Market Restraints
- Copper raw material volatility:LME price swings for high-purity copper directly compress margin on USB and Ethernet cable assemblies.
- Optical component supply concentration:Active optical cable transceivers depend on concentrated laser diode sourcing from East Asian foundries.
- REACH substance restrictions:ECHA limitations on cadmium and lead in connector plating force reformulation of legacy contact metallurgy.
Strategic Opportunities
- Indian data center buildout:BIS certification pathways for structured cabling create first-mover advantage in emerging cloud infrastructure.
- USB4-PCIe convergence:Protocol unification enables single-cable docking stations that consolidate power, data, and video transport.
- Industrial automation retrofit:METI JIS standards compliance opens procurement channels for deterministic Ethernet in factory modernization.
Industry Challenges
- Signal integrity engineering scarcity:Specialized talent for 40 Gbps+ channel modeling commands premium compensation and extends R&D timelines.
- USB-IF certification backlog:Thunderbolt 4 logo licensing queues create inventory risk for product launch windows.
- Legacy protocol coexistence:USB 2.0 fallback requirements in automotive and medical devices complicate silicon validation matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wired Interface Market |
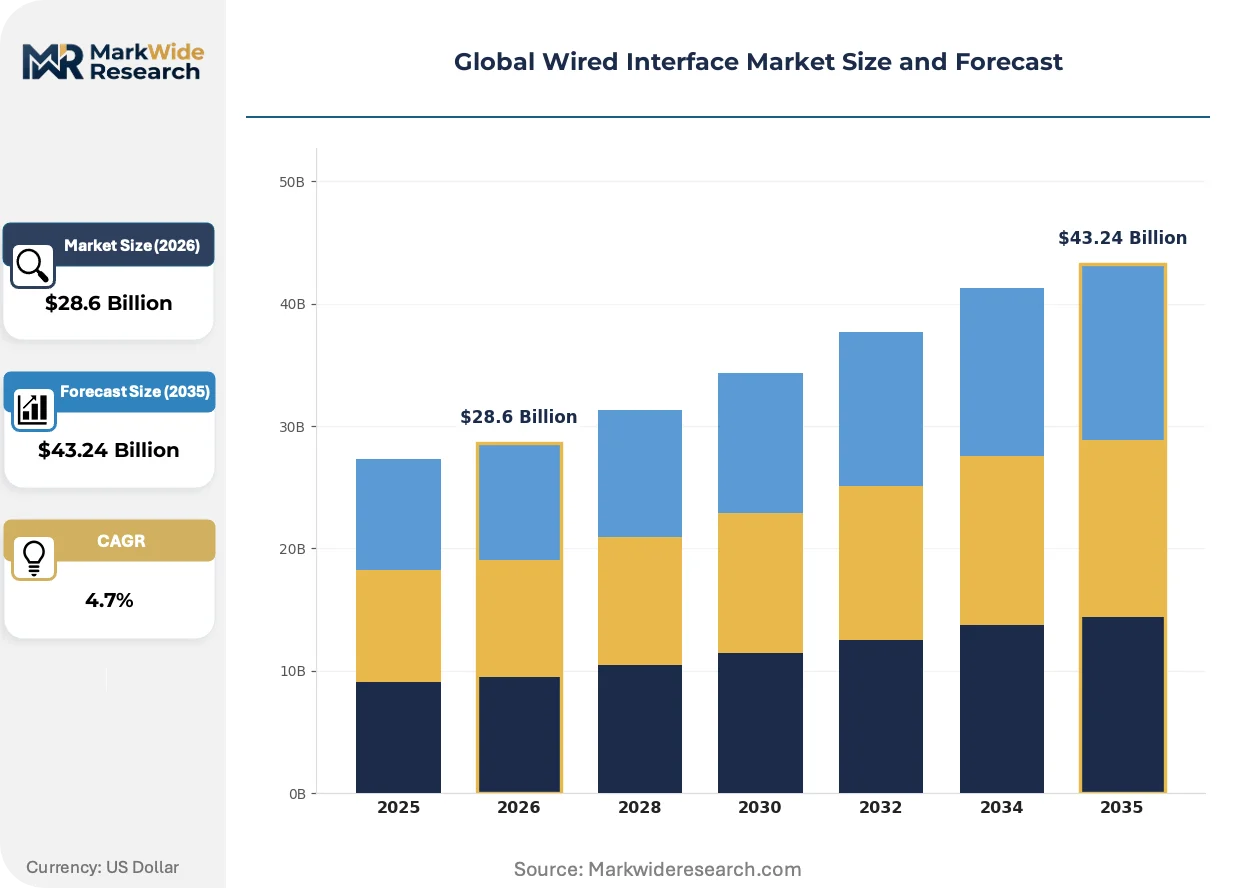
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Interface Type: USB, HDMI, Ethernet, DisplayPort, Serial ATA, Thunderbolt Technology: Copper Cable, Fiber Optic, Coaxial Cable, Twinaxial, Active Optical Cable, Shielded Twisted Pair Application: Data Centers, Consumer Electronics, Industrial Automation, Military Communications, Aerospace Systems, Broadcast Equipment End User: Telecommunications Providers, Government Agencies, System Integrators, Network Equipment Manufacturers, Enterprise Users, Research Institutions |
| Companies Covered | Amphenol Corporation, TE Connectivity, Molex Incorporated, STMicroelectronics, Texas Instruments Incorporated, NXP Semiconductors, Analog Devices, Inc., Cypress Semiconductor Corporation, ROHM Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wired Interface Market Shifts & Advancements
Active optical cable architectures are compressing the cost premium versus copper at 10 meters and beyond, while protocol convergence and regulatory substance bans are rewriting material specifications and procurement criteria.
Active optical cable assemblies based on silicon photonics transceivers are supplanting passive copper twinax in data center spine-leaf interconnects. Hyperscale operators in the United States and Germany are specifying AOC for 100G/400G links under 30 meters. This transition is compressing the traditional copper-dominant zone and fragmenting incumbent cable assembly revenue pools.
EU REACH Annex XVII restrictions on halogenated flame retardants in cable jacketing are forcing compound reformulation across European supply chains. Manufacturers serving automotive and industrial verticals must validate new thermoplastic elastomer grades without compromising flex life or fire safety ratings. German automation OEMs are pushing qualification timelines to mid-decade to accommodate dual-source material validation.
Enterprise IT procurement teams are consolidating interface specifications around USB4/Thunderbolt 4 single-cable solutions, displacing discrete HDMI, USB-A, and power brick configurations. Japanese and South Korean electronics manufacturers are responding with modular docking ecosystems that reduce SKUs and simplify field service logistics. This consolidation is visible most acutely in financial services and legal sector workstation refresh cycles.
Global Wired Interface Market Segmentation
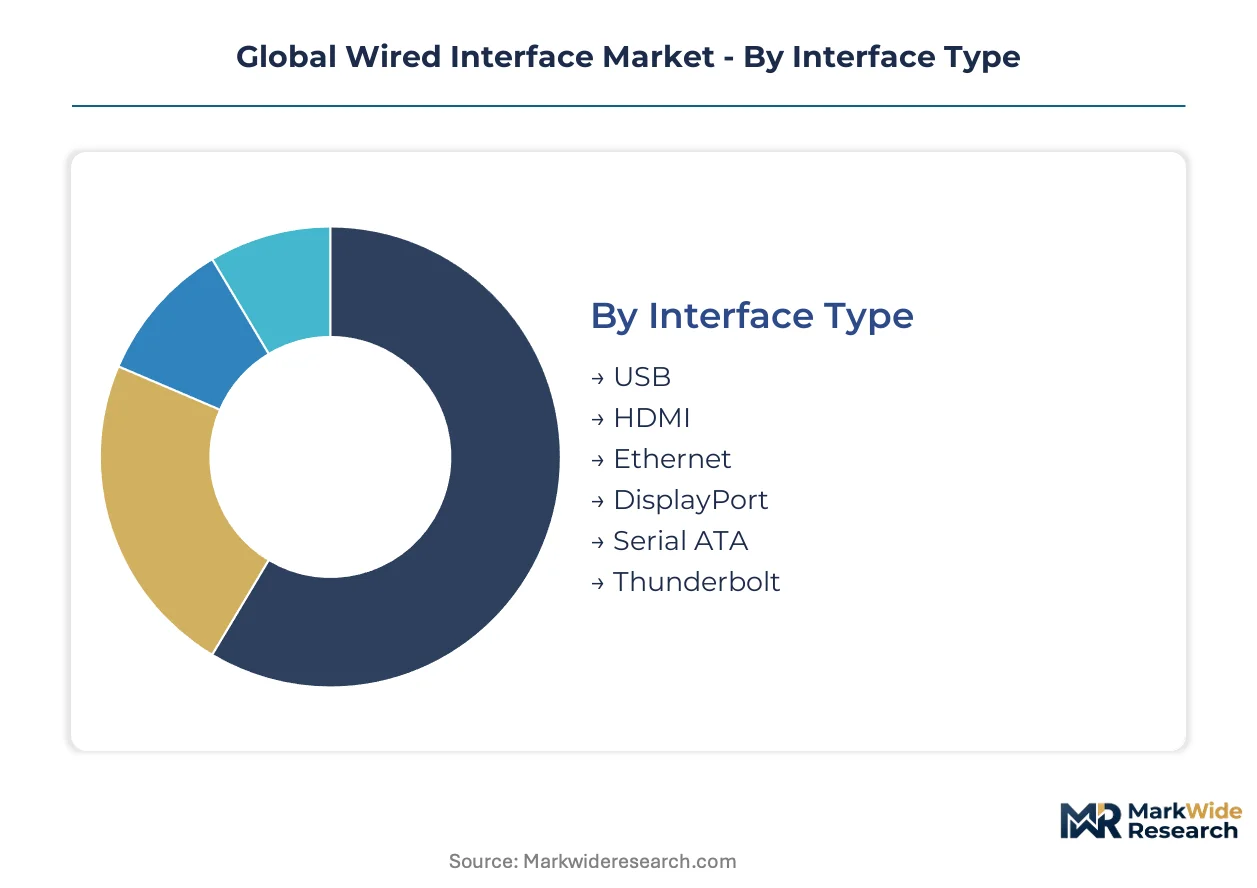
Wired interface procurement patterns diverge sharply across interface types, transmission media, and end-use environments. Channel strategy must account for these structural differences in specification authority, volume concentration, and margin profile.
Interface Type:
USB and Ethernet assemblies flow through distribution and direct OEM channels in highest volume, while Thunderbolt and DisplayPort concentrate through specialized AV integrators and broadcast equipment suppliers.
- USB:Dominates consumer electronics and enterprise peripheral shipments with backward-compatible PHY architectures spanning USB 2.0 through USB4. Enterprise procurement in the United States favors copper-based USB4 docking stations that consolidate power delivery and data transport.
- Ethernet:Industrial automation and data center spine-leaf interconnects drive demand for Cat 6A through Cat 8 shielded twisted pair assemblies. German automotive OEMs specify automotive-grade Ethernet controllers meeting AEC-Q100 qualification for electric vehicle architectures.
- HDMI:Consumer display and commercial signage applications sustain volume through retail and pro AV channels.
- DisplayPort:Multi-monitor enterprise configurations and broadcast monitor feeds in Japan favor fiber optic variants for 8K production workflows.
- Serial ATA:Legacy storage interconnect with concentrated demand from enterprise server refresh cycles.
- Thunderbolt:Premium single-cable docking ecosystems from South Korean and Japanese manufacturers target financial services workstation deployments.
USB dominates installed base. Thunderbolt is where expansion concentrates.
Technology:
Transmission media selection tracks reach requirements and electromagnetic environment constraints, with cost tiers separating short-reach copper from extended-reach optical solutions.
- Copper Cable:USB and Ethernet assemblies in lengths under 10 meters leverage high-purity copper conductors with shielded twisted pair construction. LME price volatility directly compresses margin on these high-volume cable categories.
- Fiber Optic:Japanese broadcast equipment manufacturers source fiber optic DisplayPort and Thunderbolt assemblies where bandwidth density exceeds copper limitations.
- Active Optical Cable:Hyperscale data center operators in Germany and the United States specify AOC for 100G/400G spine-leaf links under 30 meters.
- Shielded Twisted Pair:Enterprise structured cabling and industrial Ethernet deployments.
- Coaxial Cable:Legacy RF and video applications with declining share.
- Twinaxial:High-frequency test equipment and specialty computing interconnects.
Copper cable commands highest shipment volume. Active optical cable is climbing the fastest on a value basis.
Application:
Application-driven segmentation reveals divergent certification requirements and procurement authority structures across vertical markets.
- Data Centers:Server interconnect deployments in Germany and France accelerate under EU AI Act auditable data transmission mandates. Structured cabling and active optical cable procurement concentrates with hyperscale operators and colocation providers.
- Consumer Electronics:USB4 and Thunderbolt 4 certification requirements are reorganizing supplier eligibility for docking station and peripheral manufacturers.
- Industrial Automation:Japan's METI enforces JIS standards for deterministic Ethernet that shape procurement specifications for factory modernization.
- Broadcast Equipment:8K production workflows drive fiber optic interface sourcing.
- Aerospace Systems:DisplayPort and Ethernet assemblies with stringent qualification requirements.
- Military Communications:Ruggedized connectors with specialized shielding and grounding.
Data centers absorb premium optical interconnect volume. Industrial automation is gaining share fastest as factory Ethernet retrofit accelerates.
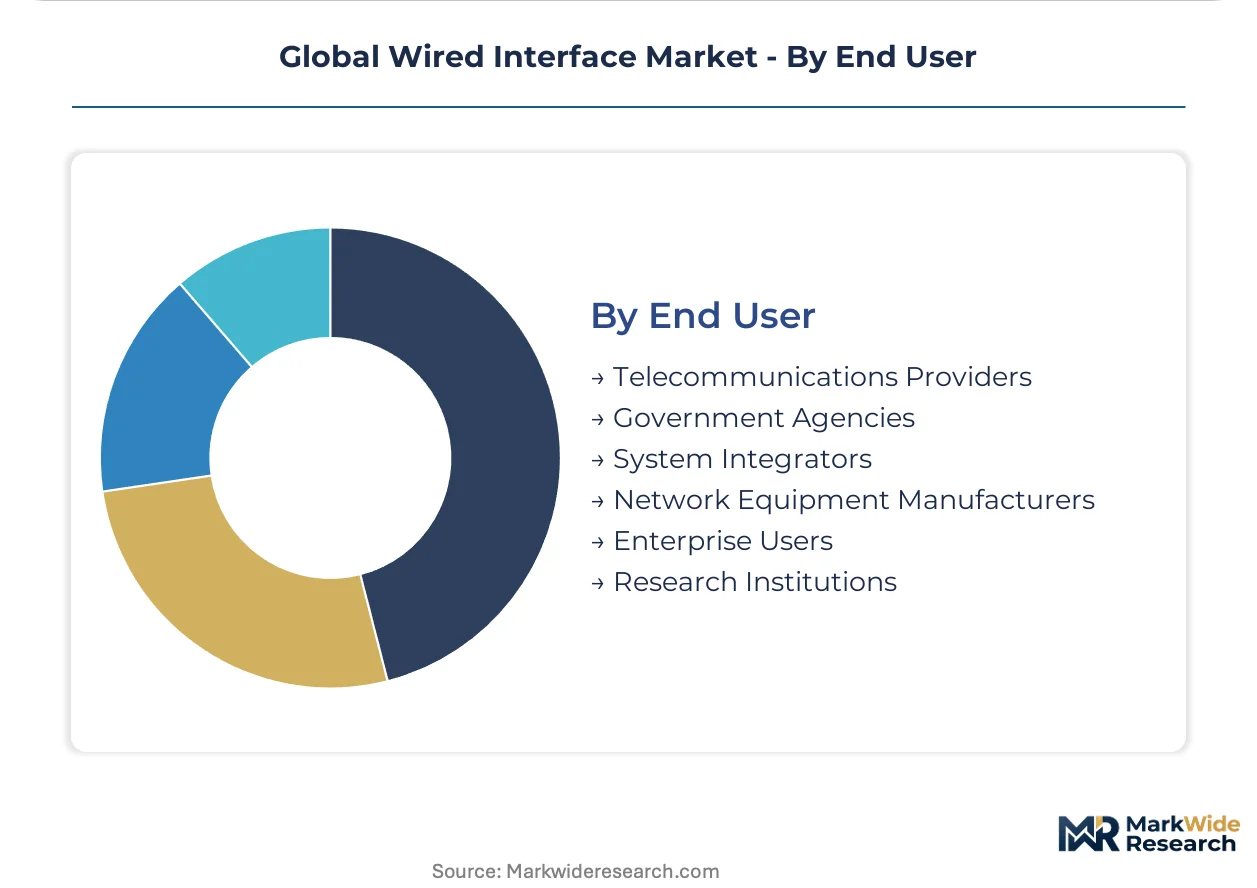
End User:
End-user category determines specification authority, with network equipment manufacturers and telecommunications providers holding greatest influence over interface standard adoption.
- Network Equipment Manufacturers:Drive PHY controller and connector specifications for enterprise switching and routing platforms.
- Telecommunications Providers:Structured cabling procurement for central office and edge infrastructure.
- Enterprise Users:Financial services and legal sector workstation refresh cycles favor USB4/Thunderbolt 4 single-cable consolidation.
- System Integrators:Industrial and commercial project-based procurement.
- Government Agencies:Defense and civilian infrastructure with domestic sourcing requirements.
- Research Institutions:High-performance computing and test equipment applications.
Network equipment manufacturers anchor specification development. Enterprise users are where interface consolidation trends manifest most acutely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine cable landing stations at Marseille anchor France's role in trans-Mediterranean data traffic. Germany's Frankfurt Rhine-Main corridor hosts the densest internet exchange peering capacity in Europe. Japan's Pacific submarine cable systems position the Kanto region as a critical node for Asia-Pacific bandwidth exchange.
United States
Hyperscale data center construction in Ashburn, Virginia and Hillsboro, Oregon drives demand for active optical cable assemblies. FCC equipment authorization rules govern electromagnetic emissions from copper interconnects deployed in enterprise settings. Dallas-Fort Worth and Phoenix data center clusters absorb premium fiber optic spine-leaf interconnect volume for cloud infrastructure expansion.
Germany
EU AI Act mandates for auditable data transmission standards accelerate server interconnect deployments in Frankfurt and Berlin colocation facilities. ECHA REACH restrictions on halogenated flame retardants force cable jacketing reformulation across automotive and industrial supply chains. Bavarian automation OEMs extend qualification timelines to mid-decade for dual-source thermoplastic elastomer validation.
Japan
8K broadcast production workflows in Tokyo and Osaka drive fiber optic DisplayPort and Thunderbolt sourcing from equipment manufacturers. METI enforces JIS standards for industrial communication interfaces that shape procurement specifications for factory modernization. The Chubu region around Nagoya concentrates deterministic Ethernet deployment for automotive manufacturing line retrofits.
India
Bureau of Indian Standards certification pathways for structured cabling create first-mover positioning in emerging cloud infrastructure buildouts. Mumbai and Hyderabad data center operators specify copper and optical interconnects for hyperscale server deployments. The country's national electronics regulator mandates electromagnetic compatibility testing for imported interface assemblies.
South Korea
Electronics manufacturers in Seoul and Suwon develop modular USB4/Thunderbolt 4 docking ecosystems for financial services workstation consolidation. The national spectrum management authority shapes shielding requirements for high-speed copper interconnects. Busan port infrastructure supports optical component import flows for active cable assembly production.
Global Wired Interface Market Competitive Landscape
Listed leaders compete with private specialists across connector manufacturing and semiconductor controller segments. The vendor base organizes into three tiers: integrated connector-cable assemblers with captive manufacturing, fabless interface controller designers, and specialized PHY silicon vendors. Dominant competitive moves include backward integration into contact metallurgy and strategic licensing of USB-IF certification protocols. Tier-1 OEMs consolidate qualified vendor lists to reduce supplier management overhead.
Within the integrated assembly tier, TE Connectivity and Amphenol Corporation exemplify vertical control over high-speed copper interconnect production. Molex Incorporated anchors the mid-tier specialist position for modular connector systems. STMicroelectronics and Texas Instruments Incorporated occupy the semiconductor controller segment with broad protocol coverage. NXP Semiconductors represents the automotive-qualified interface controller archetype through AEC-Q100 compliance positioning.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Molex Incorporated |
| STMicroelectronics |
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Analog Devices, Inc. |
| Cypress Semiconductor Corporation |
| ROHM Co., Ltd. |
| Others |
Supply & Pricing Matrix
Capacity utilization at East Asian laser diode foundries shapes cost floors for active optical cable assemblies while concentrating pricing power among integrated connector-cable manufacturers with captive photonics sourcing. German automotive OEMs and US hyperscale operators absorb divergent cost structures as copper raw material volatility compresses margins on high-volume USB and Ethernet categories.
Pricing Analysis
Certification level under USB-IF and Thunderbolt logo licensing creates the primary spread between premium and commodity tiers. Three-tier pricing structure across certified premium, qualified standard, and unbranded economy levels tracks protocol compliance investment and volume scale. Cost compression in copper cable assemblies is intensifying because LME price swings for high-purity conductors directly erode assembler margins. Enterprise procurement teams in financial services show lowest price sensitivity for Thunderbolt docking ecosystems, while consumer peripheral distributors face acute margin pressure.
Supply Chain Analysis
Inventory lead times for active optical cable transceivers have extended as concentrated laser diode sourcing from Taiwan and South Korea encounters capacity constraints. Connector metallurgy draws from Japanese and German precision stamping operations, while cable jacketing compounds hinge on Belgian and US specialty chemical suppliers. Single-source vulnerability in silicon photonics transceivers poses structural risk to spine-leaf interconnect procurement. Distribution runs through direct OEM channels for tier-1 data center operators and specialized AV integrators for broadcast equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-sale certification maintenance and field service logistics represent faster-expanding revenue layers than hardware shipment value as enterprise IT teams outsource USB-IF compliance tracking and docking station lifecycle management.
For Market Incumbents: Fortify backward integration into contact metallurgy and connector stamping to defend against commodity PHY vendor price erosion. Expand captive AOC transceiver capacity in Taiwan or South Korea to secure photonics supply against foundry allocation constraints. Deepen USB-IF certification queue relationships to reduce inventory risk from logo licensing delays. For New Entrants and Emerging Players: BIS certification fast-track pathways for Indian data center structured cabling create first-mover positioning in emerging cloud infrastructure buildouts. Target industrial automation retrofit channels in Japan's Chubu region where METI JIS standards compliance opens procurement access for deterministic Ethernet specialists. Pursue modular docking ecosystem partnerships with South Korean electronics manufacturers seeking SKU consolidation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-qualified interface controller specialists with AEC-Q100 compliance and electric vehicle platform design wins. Long-term viability rests on protocol convergence exposure and silicon photonics integration capability. Monitor USB4-PCIe convergence adoption rates in financial services workstation refresh cycles as inflection indicator for single-cable consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Fast-Track Investment | Accelerates logo licensing timelines for Thunderbolt 4 docking station launches. |
| Backward Integration into Contact Metallurgy | Secures supply of REACH-compliant plating alloys for European automotive connectors. |
| Active Optical Cable Capacity Expansion | Captures hyperscale spine-leaf interconnect demand in Ashburn and Frankfurt clusters. |
| Automotive Ethernet Controller Qualification | Unlocks AEC-Q100 positioning for electric vehicle architecture design wins. |
| Industrial JIS Standards Compliance Program | Opens METI-enforced procurement channels for Japanese factory modernization. |
Research Methodology
Operator-level perspectives from data center infrastructure managers, automotive platform engineers, broadcast equipment procurement leads, and industrial automation system integrators anchored the qualitative base. Primary interview findings triangulated against USB-IF certification databases, FCC equipment authorization filings, EU REACH substance restriction updates, and hyperscaler capex disclosures. Secondary validation drew from customs trade data for copper and optical component flows, SEC 10-K segment disclosures from connector manufacturers, and METI JIS standards publication records. Bottom-up assembly cost modeling and top-down end-use demand estimation converged on segment sizing.
Sensitivity analysis across copper price volatility scenarios, laser diode foundry utilization assumptions, and certification queue duration estimates framed forecast variance. The analytical framework modeled interface type, transmission media, application vertical, and end-user category dimensions across the projection horizon. CAGRs derived from shipment volume trajectories and value-per-unit trends incorporating protocol transition timing and regional buildout schedules. Forecast inputs included EU AI Act implementation pacing for auditable data transmission mandates and Indian BIS certification throughput for structured cabling.
Decision-makers should treat outputs as directional under base assumptions of sustained hyperscale data center expansion and protocol convergence toward USB4/Thunderbolt 4; material deviation in semiconductor cycle timing or regulatory enforcement pacing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Latin America Connector Market
Connectors
Liquid Cooling Connector Market
Connectors
Global Automotive Connector Market
Connectors
Heavy-Duty Connector Market
Connectors
Pin Retainer Market
Connectors
Press Fit Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Australia Connector Market
Connectors
Smart Crimper Market
Connectors
Circular Waterproof Connector Market
Connectors
Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
AS-Interface Market
Connectors
Wire-To-Board Connector Market
Connectors
India Connector Market