
 Europe Coil Coatings Market | 2026-2036
Europe Coil Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coil Coatings Market Foresight
Capital-intensity divergence between integrated resin producers and regional toll coaters is redrawing competitive boundaries in the Europe coil coatings sector. BASF leverages its backward integration into polyester and polyvinylidene fluoride resin chemistry to sustain margin structures that toll-dependent competitors cannot match. Akzo Nobel N.V. anchors its position through dedicated coil coating R&D facilities in the Netherlands and Sweden, while Beckers Group specializes in high-performance architectural finishes that dominate Nordic and Alpine premium segments.
Europe coil coatings are factory-applied liquid or powder systems—typically 15–25 micrometers thick—cured onto continuous metal strips of steel or aluminum to deliver corrosion resistance, color stability, and UV durability for downstream forming and fabrication. The coatings protect substrates that architects and appliance engineers subsequently bend, punch, and seam without damaging the finish layer. Polyester formulations occupy the volume core across metal roofing and siding panels, while polyvinylidene fluoride commands premium positioning in coastal and industrial atmospheres where chalking resistance extends service life. Plastisol persists in gutter and deep-drawn appliance niches where film thickness and post-form flexibility outweigh weathering demands.
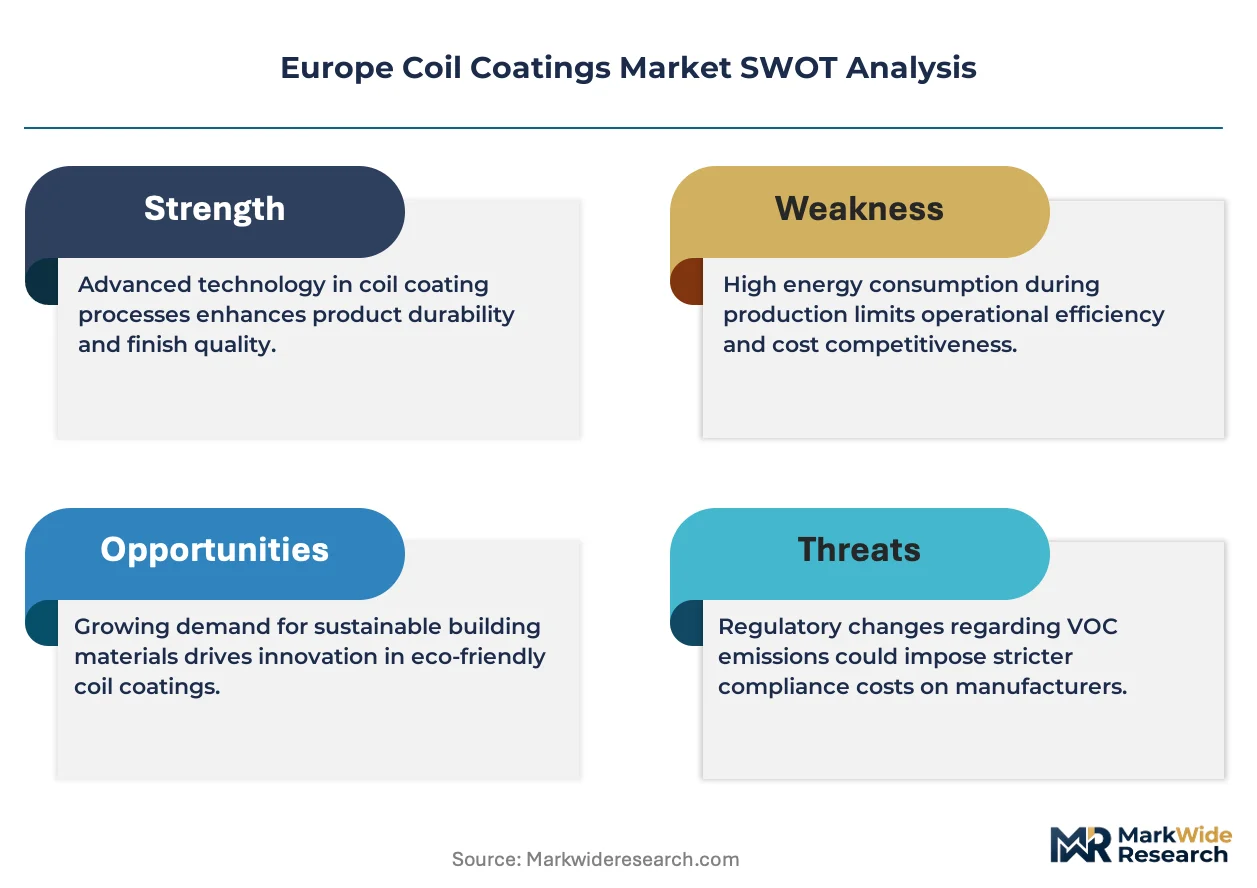
REACH registration requirements and the EU Green Deal's evolving embodied carbon benchmarks are forcing reformulation investments across the supply base, with ECHA substance restrictions progressively eliminating legacy crosslinkers and heavy-metal pigments. The Construction Products Regulation's harmonized EN standards for coated steel in structural applications further gate market access for non-compliant imports. Stakeholders must monitor how the F-Gas Regulation's phase-down trajectory affects HVAC end-use specifications and whether national building renovation waves in France, Germany, and Italy sustain metal roofing pull through the forecast horizon.
Market Dynamics
REACH substance restrictions and the EU Green Deal's embodied carbon mandates are forcing coil coating formulators to eliminate legacy crosslinkers and heavy-metal pigments while requalifying entire product lines for EN-standard compliance.
Growth Catalysts
- Building renovation waves:National stimulus programs in France, Germany, and Italy are accelerating metal roofing replacements on aging commercial and residential stock.
- F-Gas Regulation phase-down:HVAC manufacturers are redesigning heat exchanger coatings to accommodate lower-global-warming-potential refrigerants, creating specification refresh cycles.
- Polyester resin advances:Improved hydrolytic stability in super-durable grades is extending warranty terms for Alpine and coastal architectural applications.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin predictability for mid-volume coil coaters without long-term supply agreements.
- PVDF resin supply concentration:Three Asian suppliers control over 70 percent of global polyvinylidene fluoride polymer output, exposing European formulators to shipping disruptions and tariff exposure.
- Plastisol substitution ceiling:Thick-film PVC-based systems face regulatory pressure under REACH candidate list scrutiny for plasticizer content.
Strategic Opportunities
- Polish manufacturing expansion:Central European coil coating capacity is scaling to serve German automotive and appliance OEMs seeking near-shored metal finishing.
- Powder coating convergence:Hybrid liquid-powder lines are capturing architectural specification wins where zero-VOC claims support LEED and BREEAM certification.
- CSRD disclosure mandates:Large construction product manufacturers must report Scope 3 embodied carbon, creating pull for coatings with verified environmental product declarations.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in fluoropolymer dispersion and UV-curable acrylic design is retiring faster than universities replenish talent pipelines.
- EN 10169 requalification timelines:Coated steel producers face 12-18 month testing cycles to maintain Construction Products Regulation compliance across climate categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coil Coatings Market |
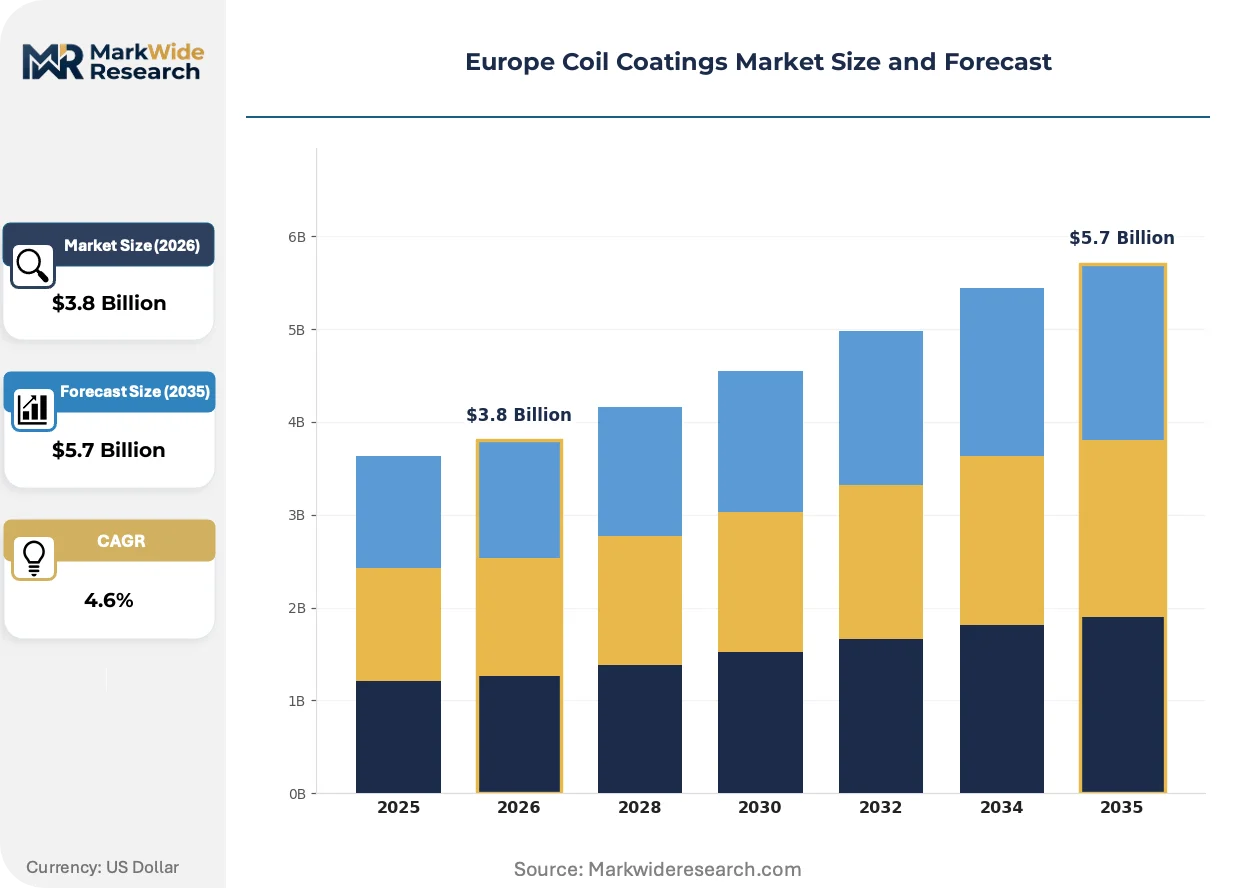
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyvinylidene Fluoride, Plastisol, Epoxy End User: Construction, Appliances, Automotive, HVAC Application: Metal Roofing, Siding Panels, Gutters, Roll Forming Technology: Coating, Baking, Electrostatic Spray, Liquid |
| Companies Covered | Sherwin-Williams, BASF, Akzo Nobel N.V., Madar Coil Coating, Arkema, Beckers Group, Axalta Coating Systems, Nippon Paint, PPG Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coil Coatings Market Shifts & Advancements
Formulation chemistry, regulatory disclosure requirements, and procurement digitization are simultaneously reshaping how coil coatings are specified, validated, and contracted across European metal finishing value chains.
Waterborne fluoropolymer dispersions are decomposing the historical trade-off between application efficiency and extreme weathering performance. Automotive trim and high-end architectural specifiers in Germany and Switzerland are adopting these systems at accelerating rates. The technology is decomposing PVDF's monopoly on 30-year warranty segments by matching chalk resistance with lower bake energy requirements.
ECHA's expanding candidate list of substances of very high concern is forcing systematic elimination of bisphenol-based crosslinkers and certain isocyanate hardeners from polyester formulations. Coil coating plants in Belgium and the Netherlands are investing in closed-loop application systems to capture volatile organic compounds ahead of anticipated threshold reductions. Appliance and HVAC segments face the steepest reformulation costs given their reliance on thin-film, high-cure-speed chemistries.
Building product manufacturers are consolidating supplier panels and demanding lifecycle carbon data before contract renewal. Tier-one metal roofing distributors in France and Italy are replacing spot-buying with multi-year framework agreements that bundle coating supply with substrate sourcing. This concentration is most visible in Nordic markets where large construction groups have vertically integrated cladding procurement functions and now specify coating systems by certified environmental product declaration rather than brand name alone.
Europe Coil Coatings Market Segmentation
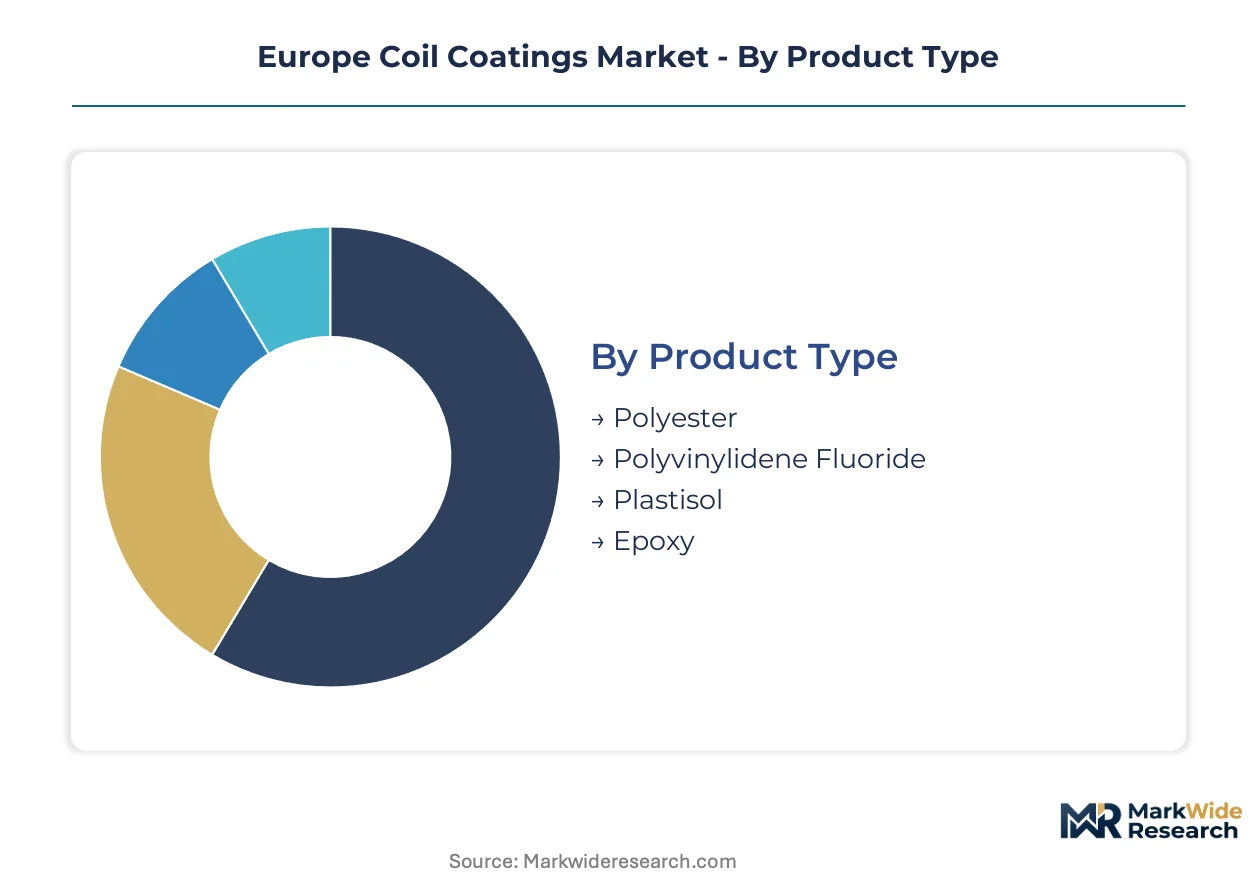
Coil coating specifications diverge sharply across end-use durability requirements and application economics, creating distinct margin architectures that reward chemistry specialization over commodity volume. Formulators who align resin systems with precise climate exposure and forming demands capture pricing power that generic suppliers cannot replicate.
Product Type:
Margin pools concentrate in fluoropolymer formulations where warranty extension commands substantial premiums over standard architectural grades.
- Polyester:Thermosetting resin systems formulated with super-durable or high-durable backbone chemistries dominate metal roofing and siding specifications across Germany, France, and Poland. Construction sector procurement in Western Europe favors these grades for 15-20 year color retention warranties on commercial and residential envelopes.
- Polyvinylidene Fluoride:Semi-crystalline fluoropolymer dispersions deliver unmatched chalking resistance and UV stability for coastal, industrial, and Alpine exposures where 30-year service life is specified. Premium architectural projects in Switzerland and Nordic markets absorb disproportionate volume despite resin supply concentration risks from Asian polymer producers.
- Plastisol:PVC-based thick-film systems retain niche dominance in deep-drawn gutter and appliance applications where 200-micrometer-plus film builds accommodate severe forming without cracking.
- Epoxy:Crosslinked epoxy-amine systems serve interior appliance linings and HVAC heat exchanger primers where corrosion resistance and chemical tolerance outweigh exterior weathering demands.
The dominant share belongs to Polyester, while Polyvinylidene Fluoride is closing the gap fastest.
End User:
Application volume scales with building stock renovation cycles and appliance manufacturing relocation patterns across Central and Western Europe.
- Construction:Metal roofing, cladding, and facade systems absorb the majority of coil coating volume as national renovation programs in France, Germany, and Italy accelerate replacement of aging building envelopes. EPD certification requirements under CSRD disclosure mandates are reshaping procurement toward verified low-carbon coating systems.
- Appliances:Refrigerator, washing machine, and oven panels require thin-film, high-gloss finishes that survive stamping and bending operations without surface defects. Manufacturing concentration in Poland and Turkey is pulling coating supply eastward from traditional Benelux production bases.
- Automotive:Exterior trim, roof rails, and bumper fascias specify coil-coated aluminum and steel for weight reduction and corrosion protection, with German OEMs driving qualification standards.
- HVAC:Heat exchanger fins and condenser housings demand hydrophilic and corrosion-resistant coatings compatible with next-generation refrigerants under F-Gas Regulation phase-down schedules.
Construction commands the volume base, though Appliances is expanding most quickly through Central European manufacturing investment.
Application:
Forming severity and exposure climate determine coating thickness, resin selection, and pretreatment chemistry across downstream fabrication steps.
- Metal Roofing:Standing seam and trapezoidal profiles specify 20-25 micrometer polyester or PVDF systems that withstand thermal cycling and foot traffic during installation. Nordic and Alpine markets prioritize snow load resistance and condensation durability.
- Siding Panels:Vertical and horizontal cladding applications favor textured or low-gloss finishes that mask substrate imperfections and reduce solar heat gain, with German and Benelux architects driving aesthetic specification trends.
- Gutters:Deep-drawn aluminum and steel profiles retain Plastisol preference for film thickness that accommodates severe forming radii without cracking.
- Roll Forming:Continuous profile production from coated coil demands lubricant-compatible topcoats that prevent galling during high-speed bending operations.
Metal Roofing holds the installed base leadership, while Siding Panels is climbing the fastest on green building certification alignment.
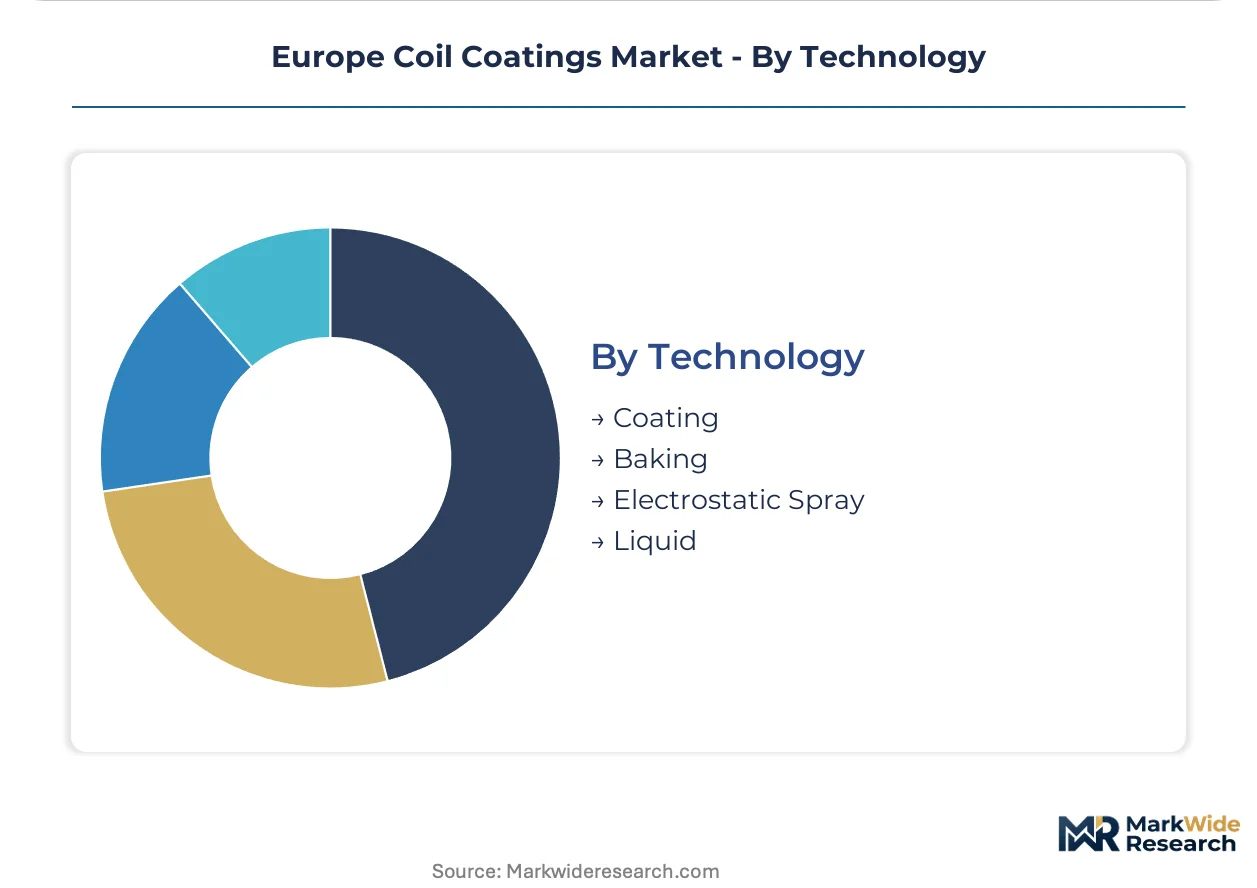
Technology:
Capital equipment intensity and VOC compliance thresholds separate competitive positions across application methods.
- Coating:Reverse roll coaters and precision metering systems apply 5-25 micrometer wet films at line speeds exceeding 150 meters per minute, representing the volume core of European coil coating capacity.
- Baking:Convection and infrared cure ovens polymerize thermosetting resins through controlled temperature profiles that determine final film properties and color stability.
- Electrostatic Spray:Powder coating lines capture zero-VOC specification wins in architectural segments where LEED and BREEAM certification drives material selection.
- Liquid:Conventional solventborne and waterborne spray systems serve specialty coil coating operations and touch-up applications outside continuous line economics.
Coating retains the dominant process share, though Electrostatic Spray is gaining share fastest on regulatory VOC restrictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Turkey exhibit acute price sensitivity as appliance manufacturing relocates eastward, while Swiss and Nordic specifiers absorb substantial premiums for 30-year warranty fluoropolymer systems. German and Italian demand sits mid-range, balancing total-cost-of-ownership against upfront material expense. Construction procurement across France and Benelux increasingly weights embodied carbon metrics alongside price.
Germany
Metal roofing replacements on aging commercial stock and automotive exterior trim specifications drive coil coating consumption. The F-Gas Regulation phase-down forces HVAC manufacturers to redesign heat exchanger coatings for lower-global-warming-potential refrigerants. The Rhine-Ruhr industrial corridor hosts concentrated coil coating capacity serving both domestic appliance OEMs and export-oriented metal fabricators.
Italy
National building renovation programs accelerate metal cladding and facade system installations across commercial and residential sectors. CSRD disclosure mandates require large construction product manufacturers to report Scope 3 embodied carbon, pulling procurement toward EPD-certified coating systems. Northern industrial clusters around Milan and Turin concentrate metal finishing operations for premium architectural export markets.
Poland
Central European manufacturing expansion pulls coil coating supply eastward as German automotive and appliance OEMs near-shore metal finishing operations. REACH compliance costs disadvantage smaller regional coaters against integrated resin producers with captive chemistry. The Silesian and Greater Poland voivodeships absorb disproportionate capacity investment for serving pan-European distribution networks.
Switzerland
Alpine exposure conditions and premium architectural specifications sustain demand for super-durable fluoropolymer formulations with extended chalking resistance. The country's national pharmaceutical regulator maintains strict chemical substance oversight that prequalifies coating systems for healthcare facility construction. Zurich and Geneva architectural practices specify coil-coated metal systems by environmental product declaration rather than brand recognition alone.
France
Building renovation waves and national stimulus programs accelerate metal roofing replacements on aging commercial envelopes. The EU Green Deal's embodied carbon benchmarks redirect public procurement toward lower-VOC coating chemistries with verified lifecycle data. The Lyon-Grenoble corridor and Paris Basin concentrate metal fabrication clusters serving high-performance architectural specifications.
Europe Coil Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into resin chemistry separating margin-sustainable positions from toll-dependent operations. The market structure rewards captive supply of polyester and fluoropolymer raw materials while penalizing formulators exposed to pigment and resin price volatility. Two strategic archetypes dominate: integrated chemical conglomerates with in-house resin production, and regional specialists commanding premium segments through formulation expertise. Capacity expansion and portfolio diversification toward waterborne and powder systems represent the prevailing competitive moves as REACH thresholds tighten.
Among integrated chemical producers, BASF and Arkema occupy positions that exemplify backward control over resin chemistry, insulating margin structures from feedstock volatility that pressures toll coaters. Akzo Nobel N.V. and Beckers Group sit within the specialist tier, with the latter representing concentrated expertise in high-performance architectural finishes for severe climate exposure. Sherwin-Williams and PPG Industries anchor multinational coating portfolios with European coil coating operations integrated into broader industrial and architectural divisions.
| Leading Market Players |
|---|
| Sherwin-Williams |
| BASF |
| Akzo Nobel N.V. |
| Madar Coil Coating |
| Arkema |
| Beckers Group |
| Axalta Coating Systems |
| Nippon Paint |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Continuous coil line throughput exceeding 150 meters per minute generates scale economies that concentrate supply among integrated resin producers while compressing price floors for toll-dependent coaters. BASF and Arkema leverage captive polyester and fluoropolymer production to absorb titanium dioxide volatility that erodes margins at smaller European operators.
Pricing Analysis
After-sales warranty extensions and technical service contracts drive lifetime value for coil coating suppliers more than upfront resin pricing. Three-tier pricing structure across premium fluoropolymer, standard polyester, and economy plastisol levels separates 30-year warranty systems from 10-year commercial grades. Cost compression in mid-volume polyester tiers is intensifying because Polish and Turkish appliance manufacturers negotiate consolidated procurement agreements. Brand-sensitive Swiss and Nordic architectural specifiers exhibit lowest price sensitivity, while Central European automotive OEMs prioritize total landed cost over certification premiums.
Supply Chain Analysis
Inbound logistics costs from Asian PVDF resin suppliers through Rotterdam and Hamburg ports expose European formulators to container availability swings and tariff uncertainty. Manufacturing concentrates in Germany, Poland, and Italy, with raw material dependencies spanning Chinese titanium dioxide, Belgian epoxy intermediates, and Korean fluoropolymer feedstock. Single-source vulnerability from three Asian PVDF polymer suppliers controlling over 70 percent of global output threatens formulation continuity. Distribution runs through pan-European metal service centers that bundle coated coil with slitting and blanking services for downstream fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe coil coatings are entering a cyclical recovery phase as national building renovation programs in France, Germany, and Italy restock metal roofing and cladding inventories. Construction sector capital expenditure cycles and F-Gas Regulation-driven HVAC specification refreshes provide the demand floor.
For Market Incumbents: Shield margin structures by accelerating backward integration into waterborne fluoropolymer dispersion technology before REACH candidate list expansions eliminate legacy crosslinkers. Lock in multi-year titanium dioxide offtake agreements to neutralize pigment cost volatility that compresses mid-volume coaters. Prioritize EN 10169 requalification investment ahead of Construction Products Regulation enforcement windows. For New Entrants and Emerging Players: Differentiate on zero-VOC powder coating systems that capture LEED and BREEAM specification wins in Nordic green building markets. Target Polish manufacturing expansion corridors where German automotive and appliance OEMs near-shore metal finishing operations. Lead with certified environmental product declarations that satisfy CSRD disclosure mandates for large construction product manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with demonstrated fluoropolymer dispersion expertise and established EPD certification libraries. Long-term viability hinges on waterborne and powder system portfolios that align with tightening REACH thresholds. Watch ECHA substance restriction announcements as inflection indicators for accelerated consolidation among toll-dependent regional coaters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | BASF's captive polyester production insulates margins from feedstock volatility that pressures toll coaters. |
| Waterborne Fluoropolymer Capacity Expansion | Beckers Group and Akzo Nobel are scaling dispersions that match PVDF durability with lower bake energy. |
| EPD Certification Investment | CSRD disclosure mandates pull procurement toward verified lifecycle carbon data in France and Italy. |
| Polish Manufacturing Footprint Expansion | Central European capacity captures German automotive and appliance OEM near-shoring trends. |
| Powder Coating Line Convergence | Hybrid liquid-powder systems capture zero-VOC architectural specifications under tightening REACH thresholds. |
Research Methodology
A spread of perspectives from coil coating plant managers, downstream OEM procurement leads at German appliance manufacturers, distribution channel partners in Benelux metal service centers, and technical R&D directors at integrated resin producers converged on the working assumptions. Secondary validation drew from ECHA substance restriction databases, EU customs trade data for titanium dioxide and fluoropolymer imports, SEC filings of multinational coating suppliers, and Cefic chemical industry reports. Bottom-up volume modeling triangulated against top-down construction sector expenditure analysis.
Segmentation dimensions modeled span resin chemistry tier, end-use industry application, coating technology format, and regional production hub clustering across the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories against construction sector investment cycles and appliance manufacturing relocation patterns. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down schedules and national building renovation program disbursement timelines.
Material uncertainties — ECHA candidate list expansions, Asian PVDF supply disruptions, and titanium dioxide price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about REACH compliance cost pass-through and CSRD disclosure adoption rates among large construction product manufacturers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Global Battery Coating Market
Coatings
Sustained Release Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Global Laser Cladding Service Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Canada Industrial Wood Coatings Market