
 CT Guided Intervention Market | 2026-2036
CT Guided Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
CT Guided Intervention Market Insights
Artificial intelligence algorithms are repositioning traditional CT-guided procedures toward autonomous navigation and real-time trajectory planning. Siemens Healthineers leverages embedded AI in its angiography-CT suites to reduce needle placement time in complex biopsies. Canon Medical Systems anchors its interventional portfolio on advanced flat-panel detector architectures with sub-millimeter spatial resolution. Koninklijke Philips competes through hybrid operating room ecosystems that merge CT guidance with intraoperative imaging.
CT guided intervention encompasses percutaneous procedures performed under cross-sectional imaging guidance, utilizing X-ray tube-detector gantries capable of sub-millimeter slice acquisition with reconstructed three-dimensional volumetric datasets for instrument tracking. The technology serves primarily to enable tissue sampling, fluid drainage, tumor ablation, and vascular access with reduced complication rates compared to unguided approaches. Biopsy and ablation procedures command the largest current revenue share within procedure type segmentation, reflecting sustained procedure volume in lung and liver oncology. Flat-panel detector CT and cone beam CT technologies are gaining fastest adoption within technology segmentation, driven by their compatibility with interventional suites and lower footprint than conventional multidetector systems. Ambulatory surgical centers represent the fastest-growing end user category as payors push site-of-care shifts for low-acuity interventions.
FDA 510(k) pathways govern software-as-medical-device navigation tools, while the EU MDR imposes stricter clinical evidence requirements on CT-guided intervention systems marketed in Europe. The FDA's evolving guidance on AI-enabled radiological devices is creating compliance complexity for manufacturers integrating machine learning into real-time guidance platforms. Stakeholders must monitor reimbursement parity between hospital-based and ambulatory CT-guided procedures, as site-neutral payment policies will determine capital deployment timing across health system footprints.
Market Dynamics
The CT guided intervention market is reconfiguring around site-of-care migration pressures and AI-enabled procedural automation, with integrated delivery networks consolidating purchasing power and compressing vendor margins across multi-site deployments.
Growth Catalysts
- EU MDR compliance acceleration:Stricter clinical evidence requirements for CT-guided systems are filtering out marginal competitors and concentrating procurement among vendors with robust regulatory dossiers, benefiting established platform manufacturers.
- Ambulatory surgical center expansion:Payor-mandated site-neutral payment policies are redirecting low-acuity biopsies and drainages from hospital outpatient departments to freestanding ASCs, expanding addressable hardware volume.
- Flat-panel detector miniaturization:Sub-millimeter spatial resolution in compact form factors is enabling CT-guided intervention suites in space-constrained facilities previously excluded from conventional multidetector installations.
Market Restraints
- Xenon shortfall in detector manufacturing:Supply concentration for high-purity noble gases in Eastern European refining corridors is injecting volatility into flat-panel production costs and extending lead times for detector assemblies.
- FDA 510(k) backlog for AI-enabled navigation:Evolving guidance on machine learning-based radiological devices is creating submission uncertainty and delaying clearance timelines for real-time trajectory planning software.
- Ultrasound-guided substitution in abdominal access:Portable ultrasound systems with GPS-registered needle tracking are capturing share in peritoneal fluid drainage and superficial mass biopsies where CT was previously standard.
Strategic Opportunities
- India tertiary hospital buildout:Government medical college expansion under the Pradhan Mantri Swasthya Suraksha Yojana is creating first-time demand for interventional radiology infrastructure in tier-2 cities.
- Cone beam CT-robotics convergence:Integration of intraoperative volumetric imaging with robotic needle drivers is opening precision ablation applications in spinal and cranial targets previously deemed inaccessible.
- US Medicare ASC coverage expansion:2024 site-of-care payment parity rulings for image-guided tumor ablation are accelerating capital deployment to ambulatory settings ahead of hospital system consolidation.
Industry Challenges
- Interventional radiologist workforce density:Fellowship-trained proceduralists remain concentrated in academic medical centers, constraining service expansion in community hospitals and ASCs acquiring CT-guided platforms.
- PACS-EMR- navigation software interoperability:Vendor-proprietary data formats are forcing costly middleware development for health systems seeking unified workflow integration across imaging and electronic record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CT Guided Intervention Market |
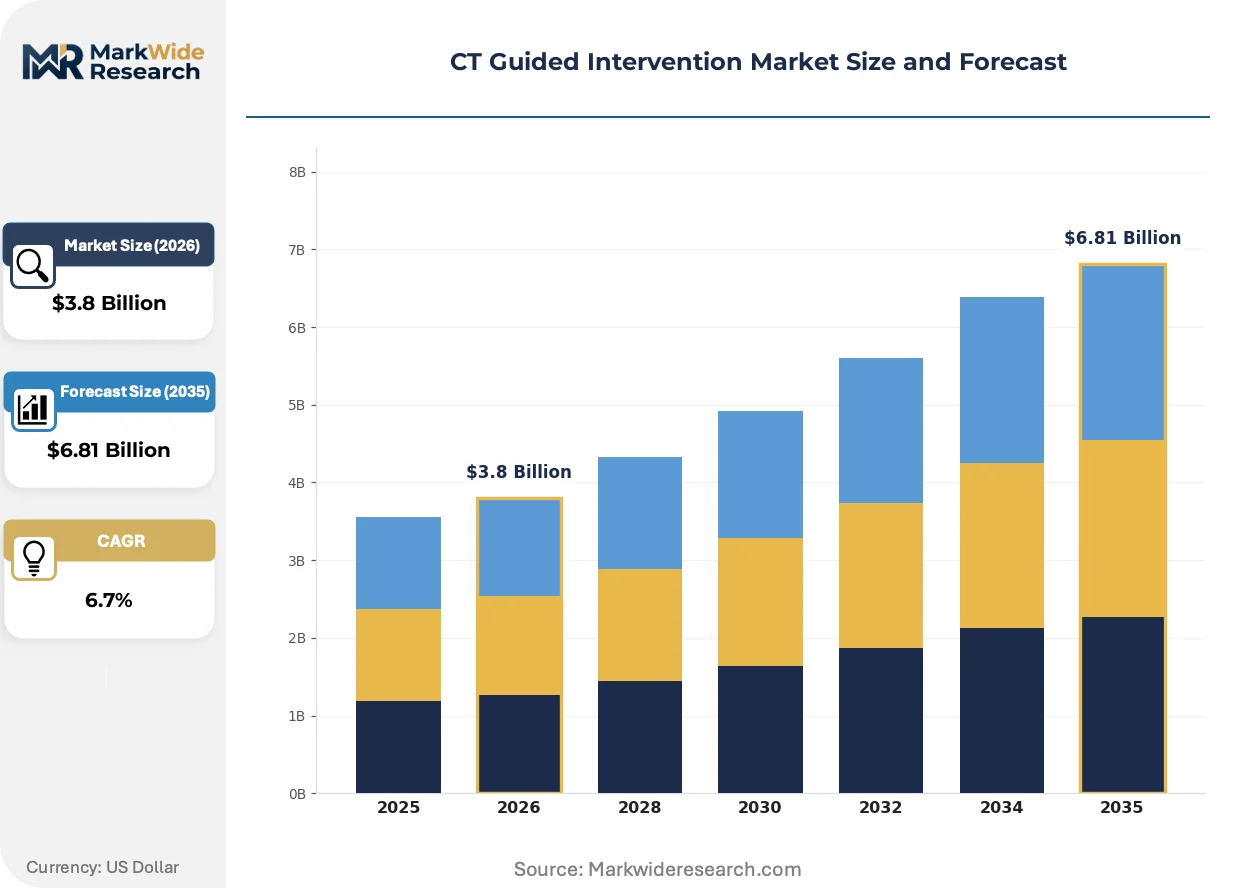
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Biopsy, Drainage, Ablation, Nerve Block, Catheter Placement, Vascular Intervention Technology: Flat-Panel Detector CT, Multidetector CT, Cone Beam CT, Time-Resolved CT, Helical CT, Volume CT End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Imaging Centers, Academic Research Institutions, Specialty Clinics, Private Practice Centers Guidance Software Type: 3D Navigation, Real-Time Imaging, Fusion Imaging, Dose Optimization, Automated Planning, Workflow Integration |
| Companies Covered | Siemens Healthineers, Canon Medical Systems, Koninklijke Philips, GE Healthcare, Fujifilm Corporation, Brainlab, Hologic, Becton, Dickinson and Company, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CT Guided Intervention Market Trends and Innovations
Procedural automation and real-time computational guidance are displacing conventional manual needle navigation, compressing training curves and expanding the addressable operator pool for complex interventions.
Photon-counting detector CT is expanding into interventional suites through Siemens Healthineers' NAEOTOM Alpha platform, which spectral imaging vendors are positioning for material-specific tumor targeting. Academic medical centers in Germany and the United States are piloting these systems for dual-energy ablation monitoring, with early adopters reporting reduced procedural radiation exposure and improved soft-tissue contrast for lesion boundary delineation.
The FDA's evolving guidance on predetermined change control plans for AI-enabled radiological devices is forcing navigation software developers to lock algorithm architectures at submission rather than enabling continuous learning post-clearance. This regulatory friction is most acute for startups building cloud-connected guidance platforms, which must now segment training pipelines between locked-base and modular-upgrade components to preserve 510(k) pathways.
Integrated delivery networks are consolidating CT-guided intervention procurement through centralized capital committees, displacing individual hospital radiology department autonomy. Multi-site health systems in Texas and Florida are negotiating enterprise-wide service contracts with single-vendor imaging ecosystems, bundling hardware, software, and consumables to extract volume discounts and standardize operator training across geographically dispersed facilities.
CT Guided Intervention Market Segmentation
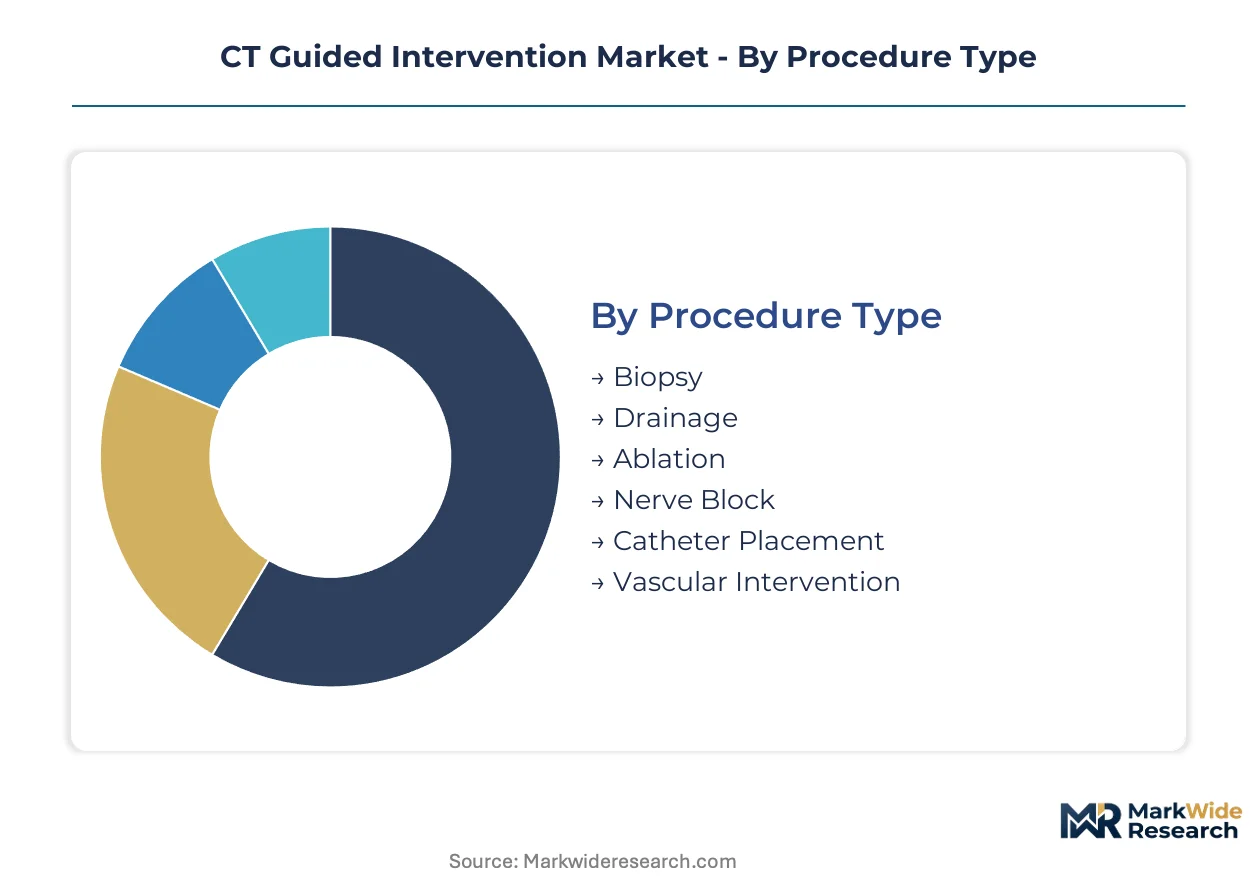
Segmentation in CT guided intervention reveals how regulatory pathways, site-of-care economics, and software architecture determine procurement patterns across health systems. Each dimension carries distinct compliance burdens and capital deployment timelines that shape vendor go-to-market strategy.
Procedure Type:
FDA 510(k) clearance governs device-tissue interaction claims for invasive procedures, while EU MDR clinical evidence requirements scale with procedural risk classification.
- Biopsy:Percutaneous tissue sampling under cross-sectional guidance demands sub-millimeter needle tracking accuracy. Demand concentrates in United States integrated delivery networks expanding lung and liver oncology services, constrained by interventional radiologist workforce shortages in community settings.
- Ablation:Thermal and cryogenic tumor destruction requires real-time temperature monitoring and margin assessment. Academic medical centers in Germany and the United States drive adoption of energy delivery systems with embedded thermocouple feedback.
- Drainage:Fluid evacuation procedures command lower regulatory classification than tissue-modifying interventions.
- Nerve Block:Pain management applications require precise anatomical targeting near neural structures.
- Catheter Placement:Vascular and non-vascular access procedures leverage CT guidance for complex anatomical variants.
- Vascular Intervention:Endovascular procedures under CT guidance remain limited to specialized hybrid suites.
Biopsy sits at the top of the volume ranking, with ablation climbing the fastest.
Technology:
Capital cost tiers separate premium spectral platforms from conventional multidetector systems, with footprint constraints driving miniaturization in ambulatory settings.
- Flat-Panel Detector CT:Compact detector architectures enable interventional suite integration with sub-millimeter spatial resolution. Ambulatory surgical centers in Texas and Florida prioritize these systems for space-constrained installations.
- Cone Beam CT:Intraoperative volumetric imaging with robotic needle convergence opens spinal and cranial targets. Academic medical centers in Germany pilot these configurations for precision ablation in previously inaccessible anatomy.
- Multidetector CT:Conventional gantry systems retain installed base dominance in hospital radiology departments.
- Time-Resolved CT:Dynamic perfusion imaging supports vascular intervention planning.
- Helical CT:Continuous acquisition modes serve high-throughput biopsy workflows.
- Volume CT:Extended z-axis coverage enables whole-organ ablation monitoring.
Multidetector CT holds the largest installed base, though flat-panel configurations are gaining share fastest in new deployments.
End User:
Reimbursement parity between hospital outpatient departments and freestanding sites determines capital allocation timing across health system footprints.
- Hospitals:Tertiary centers anchor complex ablation and vascular intervention volumes with fellowship-trained proceduralist density. United States academic medical centers concentrate photon-counting detector pilots and AI-enabled navigation research.
- Ambulatory Surgical Centers:Site-neutral payment policies redirect low-acuity biopsies and drainages from hospital settings. Medicare coverage expansion for image-guided tumor ablation accelerates hardware deployment to these facilities.
- Diagnostic Imaging Centers:Standalone facilities focus on biopsy services without therapeutic intervention capabilities.
- Academic Research Institutions:Clinical trial infrastructure supports regulatory evidence generation for novel guidance platforms.
- Specialty Clinics:Pain management and oncology-focused practices concentrate nerve block and ablation volumes.
- Private Practice Centers:Physician-owned entities face capital constraints for premium platform acquisition.
Hospitals maintain the highest procedure volume, with ambulatory surgical centers expanding most quickly under payor site-of-care mandates.
Guidance Software Type:
FDA predetermined change control plans for AI-enabled devices force architecture locking at submission, segmenting development pipelines between locked-base and modular-upgrade components.
- 3D Navigation:Volumetric trajectory planning with needle path simulation reduces procedural radiation exposure. Siemens Healthineers embeds these capabilities in angiography-CT suites for complex biopsy applications.
- Real-Time Imaging:Continuous cross-sectional feedback during instrument manipulation enables dynamic course correction. Cloud-connected platforms face regulatory friction under evolving FDA guidance on machine learning-based radiological devices.
- Fusion Imaging:Multi-modality registration combines CT anatomical detail with functional imaging data.
- Dose Optimization:Iterative reconstruction and tube current modulation reduce patient and operator exposure.
- Automated Planning:Algorithmic trajectory selection compresses training curves for less experienced operators.
- Workflow Integration:PACS-EMR interoperability remains constrained by vendor-proprietary data formats requiring costly middleware development.
3D navigation commands the broadest deployment, with real-time imaging platforms facing steepest regulatory clearance delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate the highest CT-guided intervention procurement volumes, while tertiary hospital buildouts in India and Germany's academic medical centers drive adoption of next-generation guidance platforms.
United States
Medicare site-neutral payment rulings redirect low-acuity biopsies toward ambulatory surgical centers in Texas and Florida. The FDA's evolving 510(k) guidance on AI-enabled radiological devices compresses clearance timelines for navigation software developers. Houston's Texas Medical Center anchors complex ablation volumes with fellowship-trained interventional radiologist density.
Germany
Photon-counting detector pilots at Heidelberg and Munich academic hospitals validate dual-energy ablation monitoring applications. The EU MDR imposes stricter clinical evidence requirements on CT-guided systems than predecessor directives, filtering marginal competitors. Bavaria's medical technology cluster concentrates navigation software development and regulatory consulting expertise.
India
Government medical college expansion under the Pradhan Mantri Swasthya Suraksha Yojana creates first-time demand for interventional radiology infrastructure in tier-2 cities. CDSCO medical device regulations govern import and local manufacturing compliance for guidance platforms. Maharashtra's tertiary hospitals in Mumbai and Pune lead private-sector adoption of flat-panel detector configurations.
Japan
PMDA approval pathways for software-as-medical-device navigation tools require substantial equivalence demonstrations to predicate devices. METI funding supports domestic development of compact cone beam CT systems for space-constrained facilities. Tokyo's university hospitals pilot robotic needle convergence technologies for spinal ablation applications.
China
NMPA innovation pathways accelerate review for CT-guided intervention systems with domestic intellectual property. Provincial hospital tiering policies concentrate advanced interventional capabilities at Class IIIA facilities in Beijing and Shanghai. The Yangtze River Delta medical device manufacturing base supplies detector assemblies and navigation software components.
CT Guided Intervention Market Competitive Landscape
Global majors compete with regional champions across regulatory dossier depth and site-of-care integration capabilities. The vendor base separates into three tiers: diversified imaging conglomerates with full modality portfolios, interventional navigation specialists with software-centric business models, and regional equipment fabricators serving price-sensitive hospital procurement. Dominant competitive moves include enterprise-wide service contract bundling across multi-site health systems and strategic partnerships between hardware manufacturers and AI guidance developers.
Within the diversified imaging tier, Siemens Healthineers, Canon Medical Systems, and Koninklijke Philips exemplify platform manufacturers competing through integrated ecosystem strategies. Siemens Healthineers occupies a position at the convergence of angiography-CT suites and embedded AI navigation. Canon Medical Systems anchors its presence on advanced detector architectures. Koninklijke Philips sits within hybrid operating room configurations that merge intraoperative imaging with CT guidance. These three conglomerates represent distinct geographic origins—German, Japanese, and Dutch respectively—each leveraging regional regulatory expertise to compress market access timelines.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Canon Medical Systems |
| Koninklijke Philips |
| GE Healthcare |
| Fujifilm Corporation |
| Brainlab |
| Hologic |
| Becton, Dickinson and Company |
| Cook Medical |
| Others |
Pricing and Supply Chain Analysis
Xenon gas supply from Eastern European refining corridors feeds directly into flat-panel detector manufacturing costs, cascading through three pricing tiers that separate photon-counting spectral platforms from compact cone beam systems and refurbished multidetector installations. Detector assembly lead times stretch procurement cycles for ASC buyers while integrated delivery networks exploit volume concentration to compress service contract margins across multi-site deployments.
Pricing Analysis
Input-cost pass-through from noble gas and semiconductor inputs drives pricing stratification across premium, standard, and economy tiers. Price differentiation rests on detector resolution grade and FDA 510(k) clearance tier for embedded navigation software. Pricing pressure stems from ultrasound-guided substitution in abdominal access procedures, eroding CT biopsy premiums. Ambulatory surgical centers exhibit highest price sensitivity, constrained by capital deployment limits, while academic medical centers prioritize spectral imaging capabilities regardless of cost.
Supply Chain Analysis
Photoresist and scintillator crystal supply rests on Japanese specialty chemical producers and Chinese rare earth processors, with detector module assembly concentrating in Germany, Japan, and the Yangtze River Delta. Raw material dependencies include high-purity xenon, cesium iodide crystals, and amorphous silicon photodiode arrays. Supply chain risk centers on single-source vulnerability for noble gas refining following Eastern European supply disruptions. Distribution runs through authorized dealer networks serving hospital systems, with direct OEM relationships dominating enterprise-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CT guided intervention market represents a late-cycle quality story where reimbursement parity and AI-enabled precision specifications are consolidating procurement around vendors with robust regulatory dossiers and embedded software ecosystems.
For Market Incumbents: Extend service contract bundling across integrated delivery networks to lock out navigation software competitors, while accelerating photon-counting detector pilots at academic medical centers to establish clinical evidence moats. Defend against ultrasound-guided substitution by embedding real-time thermocouple feedback in ablation platforms. Prioritize backward integration into detector assembly to mitigate xenon supply volatility. For New Entrants and Emerging Players: Tier-2 city hospitals in India under the Pradhan Mantri Swasthya Suraksha Yojana expansion represent an underserved buyer archetype with first-time interventional radiology infrastructure demand. Target cone beam CT-robotics convergence for spinal ablation applications where precision requirements exceed incumbent platform capabilities. Pursue CDSCO regulatory pathways with local manufacturing partnerships to compress import compliance timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 510(k) backlogs for AI-enabled navigation are filtering out undercapitalized software developers. Long-term viability favors platform manufacturers with locked-base algorithm architectures and enterprise service contract density. Acquisition targets include navigation software specialists with predetermined change control plan expertise. Watch Medicare ASC coverage expansion rulings as inflection indicators for ambulatory hardware deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses clearance timelines for AI-enabled trajectory planning platforms against evolving guidance. |
| Hospital System Partnership | Locks multi-site procurement through enterprise service contracts bundling hardware, software, and consumables. |
| Software Companion Development | Enables PACS-EMR interoperability addressing vendor-proprietary data format fragmentation. |
| Reimbursement Strategy | Secures site-neutral payment parity for ASC-based tumor ablation ahead of hospital consolidation. |
| CE Marking Pathway | Navigates EU MDR clinical evidence requirements that filter marginal competitors from European procurement. |
Research Methodology
Multiple input streams — primary interviews with interventional radiologists and hospital procurement committees, secondary validation against FDA 510(k) filings and CMS Medicare reimbursement databases, and trade data on detector component imports — were reconciled through bottom-up procedure volume modeling and top-down equipment shipment triangulation. Stakeholder consultations included GPO contracts managers, biomedical engineers at academic medical centers, and regulatory affairs leads at navigation software developers. Secondary sources encompassed hospital procurement databases, CDSCO import records, and EU MDR notified body documentation.
Historical installation data cross-referenced against panel input from equipment vendors and service providers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include procedure type, detector technology tier, end-user site category, and guidance software architecture. CAGRs were derived from procedure volume trajectories and capital replacement cycles. Industry-specific forecast inputs incorporated interventional radiologist fellowship training pipeline data and payor site-of-care policy evolution.
Underlying measurement precision varies by segment; biopsy and ablation procedure estimates carry tighter precision than vascular intervention volumes given reporting standardization. Forecasts reflect assumptions regarding reimbursement parity enforcement and AI regulatory pathway stability. Regulatory guidance shifts, noble gas supply disruptions, and ultrasound substitution rates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Preclinical Ultrasound Systems Market