
 Fluorescence Microscopy Market | 2026-2036
Fluorescence Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescence Microscopy Market Analysis
Multi-source procurement of optical components is realigning vendor relationships across the fluorescence microscopy supply chain. Nikon Corporation leverages in-house lens grinding capabilities to control image quality from glass formulation through final assembly. Bruker Corporation sustains its position in advanced research systems through super-resolution and light-sheet technology leadership. Thermo Fisher Scientific anchors its installed base with integrated workflows linking fluorescence platforms to reagent portfolios and cloud analytics.
Fluorescence microscopy employs excitation light to induce fluorophore emission, enabling visualization of cellular structures with resolution limits governed by numerical aperture and wavelength parameters. The technique serves biological research, clinical diagnostics, and materials science by mapping protein localization, tracking molecular dynamics, and quantifying cellular responses. Confocal microscopes command premium positioning due to optical sectioning depth and deconvolution fidelity, while super-resolution microscopes represent the fastest-expanding product category as structured illumination and stimulated emission depletion techniques penetrate core research facilities. Pharmaceutical companies as an end-user segment concentrate purchasing power around high-throughput screening configurations and automated imaging platforms.
FDA 21 CFR Part 11 compliance requirements shape data integrity specifications for fluorescence systems deployed in GLP drug discovery environments, while ISO 10993 biocompatibility standards influence fluorophore reagent formulations for live-cell applications. EMA and PMDA quality system regulations further constrain instrument validation protocols for clinical research use. Stakeholders must monitor convergence between artificial intelligence-enabled image analysis and evolving regulatory frameworks for algorithm-assisted diagnostic interpretation.
Market Dynamics
Super-resolution microscopy is compressing replacement cycles as core research facilities upgrade from confocal systems to structured illumination and stimulated emission depletion platforms. This technology displacement is redrawing competitive boundaries between instrument tiers.
Growth Catalysts
- ISO 10993 biocompatibility standards:Live-cell imaging protocols are mandating fluorophore reformulation, expanding reagent attach rates to instrument sales in pharmaceutical workflows.
- High-content screening automation:Drug discovery pipelines at contract research organizations are standardizing on integrated fluorescence platforms with robotic sample handling.
- Academic medical center capital cycles:Sustained NIH and institutional funding in the United States, Germany, and Japan is refreshing installed bases with advanced research systems.
Market Restraints
- Objective lens supply concentration:Precision grinding capabilities cluster with Japanese and German optical specialists, creating single-source vulnerability for high-numerical-aperture components.
- FDA 21 CFR Part 11 compliance costs:GLP drug discovery environments require validated software and audit trails that inflate system pricing and extend sales cycles.
- Electron microscopy substitution:Correlative workflows in materials science are diverting some structural biology budgets toward cryo-EM for near-atomic resolution.
Strategic Opportunities
- India biopharma manufacturing expansion:CDSCO-regulated contract manufacturing organizations are adopting fluorescence-based quality control for biosimilar production.
- AI-enabled image analysis convergence:Cloud-based segmentation algorithms are creating attach-rate expansion for software subscriptions bundled with hardware.
- Light-sheet microscopy penetration:Cleared-tissue imaging applications in developmental biology are opening new specimen preparation service revenue streams.
Industry Challenges
- Super-resolution specialist shortage:Structured illumination and STED operation require optical physics expertise that outpaces university training pipeline output.
- Multi-vendor integration complexity:Linking fluorescence platforms to laboratory information management systems demands custom scripting that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescence Microscopy Market |
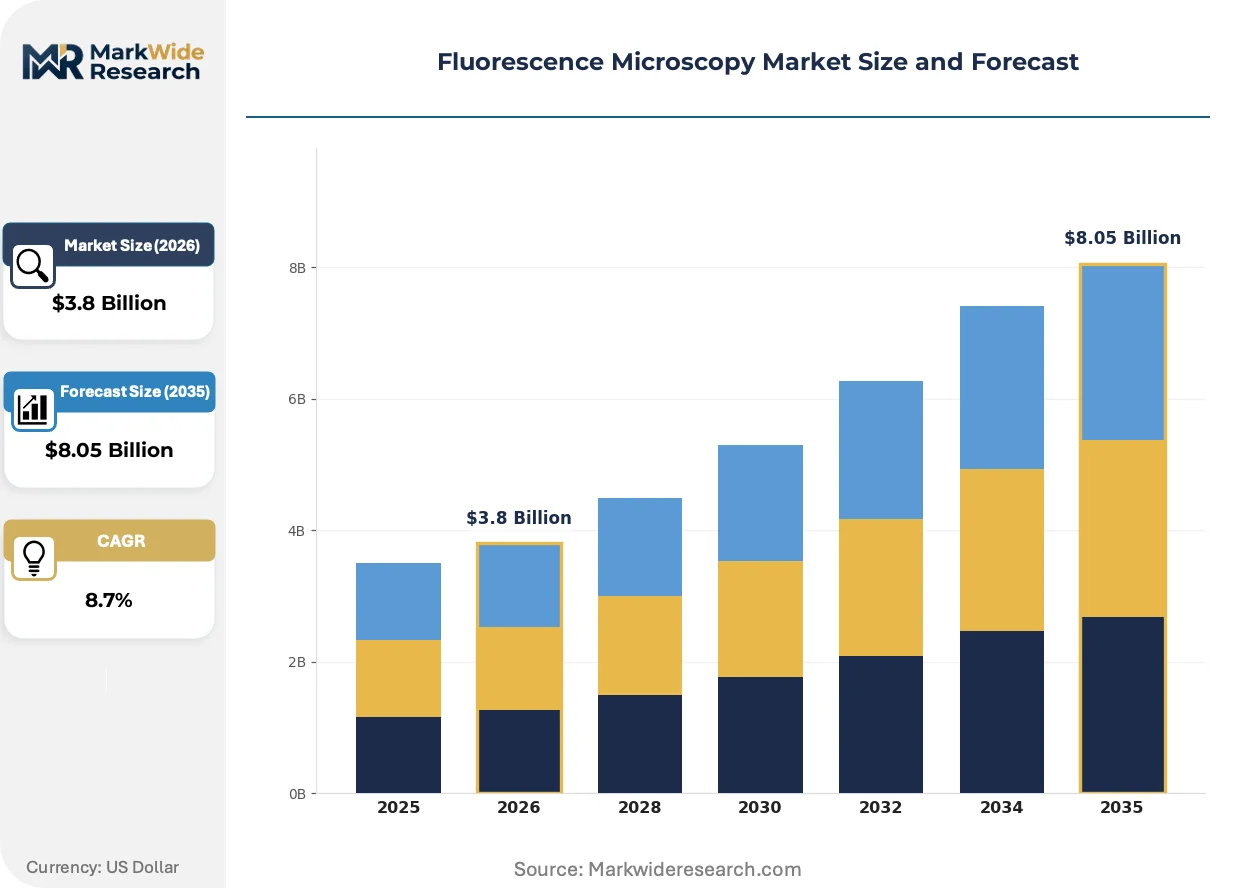
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Widefield Microscopes, Confocal Microscopes, Multiphoton Microscopes, Super-Resolution Microscopes Application: Cell Biology, Molecular Biology, Neuroscience, Drug Discovery End User: Research Laboratories, Pharmaceutical Companies, Biotechnology Firms, Academic Institutions Technology: Optical Coherence Tomography, High-Throughput Screening, Imaging Automation, 4D Imaging |
| Companies Covered | Nikon Corporation, Bruker Corporation, Thermo Fisher Scientific, Keyence Corporation, Agilent Technologies Inc., Carl Zeiss AG, Leica Microsystems GmbH, Hitachi High-Tech Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescence Microscopy Market Emerging Trajectories
Artificial intelligence is restructuring how fluorescence data generates value, shifting competitive advantage from hardware specifications to algorithmic interpretation capabilities. This transformation is compressing the traditional instrument-reagent-service revenue model.
Light-sheet fluorescence microscopy is expanding into developmental biology and neuroscience as cleared-tissue imaging protocols mature. Core facilities at Stanford University, Max Planck Institute, and RIKEN are adopting these systems for whole-organ imaging at cellular resolution. The technology is expanding into specimen preparation workflows, displacing serial sectioning methods and creating new reagent consumption patterns for refractive index matching media.
EMA's In Vitro Diagnostic Regulation is tightening performance documentation requirements for fluorescence systems used in clinical research across European member states. Manufacturers must now submit clinical evidence packages for algorithm-assisted image analysis modules. The regulation is compressing product development timelines for research-use-only systems seeking clinical workflow expansion.
Pharmaceutical procurement teams are consolidating vendor relationships around integrated reagent-instrument-analytics bundles. Thermo Fisher Scientific and Danaher Corporation are capturing multi-year service contracts that displace point-of-sale hardware transactions. This consolidation is most visible in United States and Swiss biopharma clusters where procurement centralization has advanced furthest.
Fluorescence Microscopy Market Segmentation
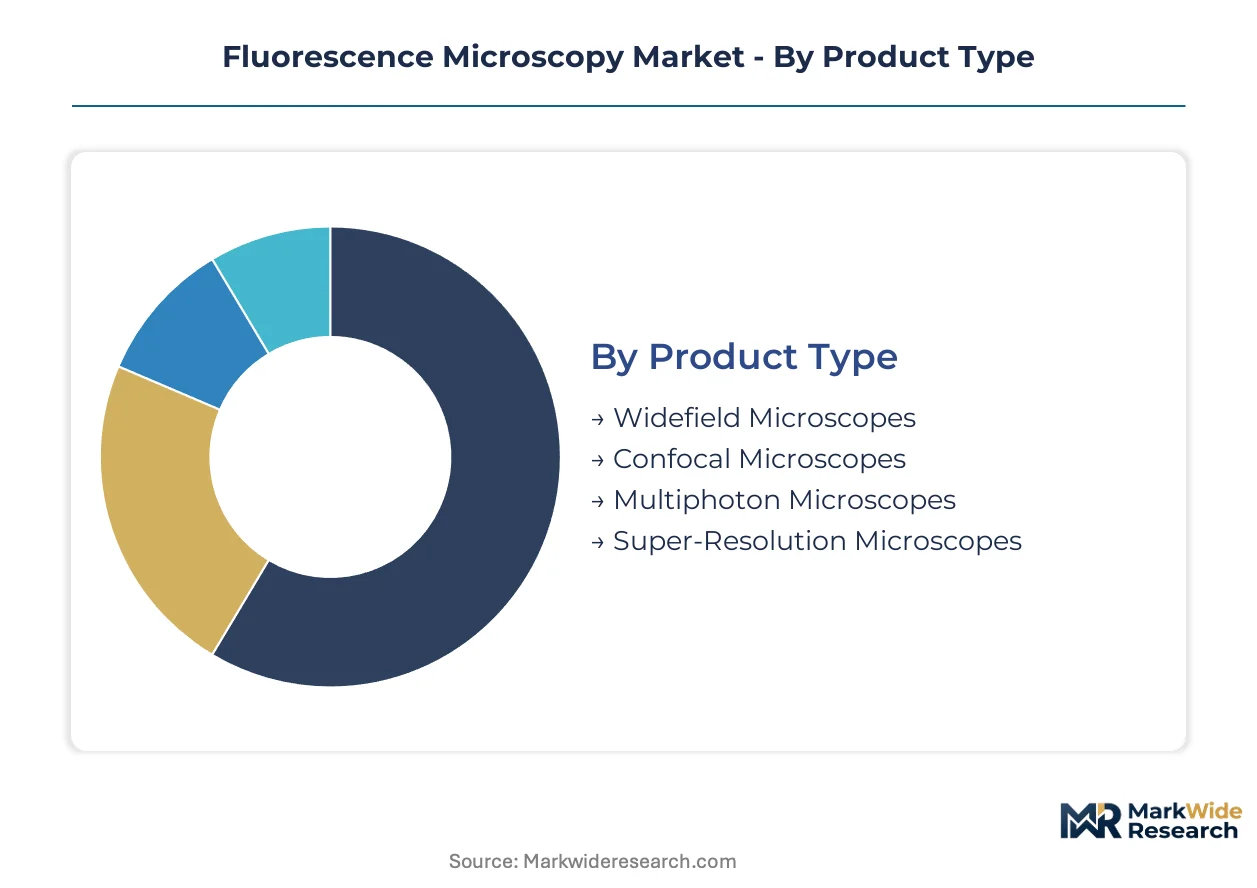
Fluorescence microscopy segmentation reveals how instrument architecture, workflow integration, and end-user sophistication create distinct purchasing patterns across the value chain. Each dimension shapes vendor R&D priorities and service attach rates differently.
Product Type:
Customization intensity spans from standardized widefield systems to bespoke super-resolution platforms requiring optical physics expertise for deployment.
- Widefield Microscopes:Epifluorescence systems with mercury or LED excitation sources serve routine screening and educational applications. Demand clusters at academic institutions in Germany and Japan where entry-level instrumentation refreshes undergraduate laboratory infrastructure.
- Confocal Microscopes:Laser-scanning platforms with pinhole-based optical sectioning dominate core research facilities requiring sub-cellular resolution with minimal phototoxicity. Pharmaceutical companies in the United States concentrate procurement around spinning-disk variants for live-cell kinetic assays.
- Multiphoton Microscopes:Pulsed infrared excitation enables deep-tissue imaging in intact organisms.
- Super-Resolution Microscopes:Structured illumination and STED platforms break the diffraction limit for single-molecule localization.
Leading the category by volume: Widefield Microscopes. Expanding most quickly: Super-Resolution Microscopes.
Application:
Workflow complexity escalates from descriptive cell biology toward quantitative drug discovery pipelines requiring regulatory-compliant data integrity.
- Cell Biology:Organelle dynamics and protein trafficking studies drive continuous instrument utilization at RIKEN and Max Planck Institute core facilities.
- Molecular Biology:Fluorescence in situ hybridization and protein-protein interaction mapping depend on spectral unmixing capabilities.
- Neuroscience:Calcium imaging and synaptic vesicle tracking in behaving animals demand high-speed cameras and specialized objective lenses.
- Drug Discovery:High-content screening of compound libraries requires automated plate handling and cloud-connected analytics at contract research organizations in the United States and Switzerland.
Drug Discovery commands the highest average selling prices. Cell Biology maintains the largest installed base.
End User:
Capital availability and procurement sophistication separate centralized pharmaceutical purchasing from distributed academic decision-making.
- Research Laboratories:Government-funded institutes in Japan and Germany sustain replacement cycles through institutional grant mechanisms.
- Pharmaceutical Companies:GLP-compliant validation requirements and multi-year service contracts dominate procurement at Pfizer, Roche, and Novartis campuses.
- Biotechnology Firms:Venture-backed startups in Cambridge and South San Francisco favor flexible leasing arrangements and shared core facility access.
- Academic Institutions:Undergraduate teaching laboratories and principal investigator grants drive fragmented purchasing with extended sales cycles.
Pharmaceutical Companies generate the highest revenue per customer. Biotechnology Firms show the steepest expansion trajectory in instrument placements.
Technology:
Integration depth separates standalone imaging hardware from automated workflow platforms with embedded analytical software.
- Optical Coherence Tomography:Interferometric depth-resolved imaging extends fluorescence microscopy into ophthalmology and dermatology clinical applications.
- High-Throughput Screening:Robotic sample handling and automated image acquisition enable 384-well plate processing at contract research organizations.
- Imaging Automation:Stage positioning, focus maintenance, and exposure optimization reduce operator intervention for longitudinal time-lapse experiments.
- 4D Imaging:Three-dimensional volume capture over time requires terabyte-scale data management and GPU-accelerated deconvolution.
High-Throughput Screening anchors the largest service contract values. 4D Imaging drives the fastest software subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical glass manufacturing clusters in Germany and Japan anchor fluorescence microscopy supply chains, while pharmaceutical R&D spending in the United States and Switzerland drives instrument demand at premium price tiers.
United States
NIH funding cycles and GLP drug discovery pipelines sustain capital investment at academic medical centers and contract research organizations. FDA 21 CFR Part 11 compliance requirements shape validation protocols for systems deployed in pharmaceutical workflows. The Boston-Cambridge biotech corridor and South San Francisco peninsula concentrate procurement from venture-backed startups and established pharma campuses.
Germany
Max Planck Institute core facilities and university medical centers maintain replacement cycles through institutional grant mechanisms. EMA In Vitro Diagnostic Regulation tightens performance documentation for clinical research applications across member states. The Baden-Württemberg optics cluster around Stuttgart supplies precision objective lenses to instrument manufacturers worldwide.
Japan
RIKEN national research institutes and university core facilities drive demand for super-resolution and live-cell imaging platforms. PMDA quality system regulations constrain instrument validation for clinical research use. The Tokyo-Yokohama corridor houses captive lens grinding operations that control image quality from glass formulation through final assembly.
Switzerland
Roche and Novartis procurement centralization favors multi-year service contracts with integrated reagent-instrument-analytics bundles. Swissmedic regulations govern clinical evidence requirements for algorithm-assisted diagnostic modules. The Basel biopharma cluster standardizes on automated high-content screening configurations for compound library evaluation.
India
CDSCO-regulated contract manufacturing organizations are adopting fluorescence-based quality control for biosimilar production lines. The country's national pharmaceutical regulator is aligning inspection protocols with international standards for analytical instrumentation. The Hyderabad-Bengaluru corridor is expanding CDMO capacity with integrated imaging platforms for batch release testing.
Fluorescence Microscopy Market Vendor Landscape
Technology licensing agreements dominate the current landscape as super-resolution patents reshape competitive boundaries between instrument tiers. The vendor base clusters around three structural positions: diversified life science conglomerates with reagent-instrument bundling capabilities, specialized optics houses with captive lens manufacturing, and analytical instrumentation firms with advanced research system portfolios. Consolidation pressures concentrate in the mid-market tier where scale advantages in software development are accelerating. M&A activity and strategic partnerships represent the dominant competitive vectors as firms seek to close gaps in workflow integration.
Within the diversified life science tier, Thermo Fisher Scientific anchors integrated workflow offerings linking hardware platforms to reagent portfolios and cloud analytics. Nikon Corporation exemplifies the specialized optics archetype through in-house lens grinding capabilities that control image quality from glass formulation through final assembly. Bruker Corporation occupies a position in advanced research systems through super-resolution and light-sheet technology leadership. These three firms represent distinct strategic postures that competitors must navigate.
| Leading Market Players |
|---|
| Nikon Corporation |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Keyence Corporation |
| Agilent Technologies Inc. |
| Carl Zeiss AG |
| Leica Microsystems GmbH |
| Hitachi High-Tech Corporation |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Objective lens grinding capability bifurcation separates premium super-resolution platforms from commodity widefield systems, with Japanese and German optical specialists commanding pricing power through captive manufacturing while downstream vendors absorb margin compression from multi-source component procurement.
Pricing Analysis
Extended warranty and field service bundling distinguish premium confocal and super-resolution configurations from unbundled widefield transactions. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 certification status and FDA 21 CFR Part 11 validation depth. Cost compression in entry-level widefield tiers is intensifying because academic institutions stretch replacement cycles. Pharmaceutical companies show lowest price sensitivity given GLP compliance requirements, while undergraduate teaching laboratories resist capital outlays without grant subsidy.
Supply Chain Analysis
Refurbished objective lens flows and remanufactured laser modules create secondary supply channels for budget-constrained academic buyers. Precision grinding capacity concentrates in Japan, Germany, and Switzerland. Optical glass formulations and high-numerical-aperture lens assemblies draw from specialty chemical and precision machining inputs. Single-source vulnerability for super-resolution objective components threatens instrument availability. Distribution runs through authorized dealer networks for research systems and direct OEM relationships for pharmaceutical procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Objective lens grinding capacity constraints in Japan and Germany prop pricing power for integrated manufacturers, sustaining margin structures despite downstream pressure on commoditized widefield configurations.
For Market Incumbents: To counter electron microscopy substitution in structural biology budgets, deepen captive lens manufacturing capacity in Stuttgart and Tokyo corridors while accelerating STED patent licensing to mid-tier competitors seeking technology access.
For New Entrants and Emerging Players: Enter via CDSCO-regulated contract manufacturing quality control workflows in India, where biosimilar production expansion outpaces established vendor service infrastructure. Target light-sheet microscopy specimen preparation services as attach-rate expansion beyond hardware margins.
For Investors and Strategic Acquirers: Re-rating potential sits with AI-enabled image analysis software specialists given EMA In Vitro Diagnostic Regulation tightening clinical evidence requirements for algorithm-assisted modules. Long-term viability favors platforms with recurring revenue density over transactional hardware exposure. Monitor NIH funding appropriations as inflection indicator for academic capital cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Super-Resolution Patent Licensing | Technology transfer agreements expand addressable market for structured illumination platforms at mid-tier research institutes. |
| Cloud Analytics Integration | Thermo Fisher Scientific bundles GPU-accelerated deconvolution subscriptions with confocal hardware placements. |
| CDSCO Validation Investment | Instrument manufacturers secure regulatory pathway for clinical research expansion in Indian biosimilar production. |
| Light-Sheet Service Expansion | Cleared-tissue imaging protocols at Stanford and Max Planck Institute create specimen preparation revenue streams. |
| AI Module Clinical Evidence Packaging | EMA compliance requirements compress development timelines for research-use-only systems seeking diagnostic workflow entry. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across core facility directors, pharmaceutical procurement managers, biomedical engineers, and optical component specialists. FDA 510(k) databases, EMA submission repositories, NIH RePORTER grant records, and ISO certification registries supplied validation benchmarks. Bottom-up instrument shipment tracking and top-down R&D spending allocation triangulated market sizing.
Granularity-level modeling disaggregated revenue across product type, application workflow, end-user capital availability, and technology integration depth. CAGRs derived from logistic diffusion curves fitted to super-resolution adoption patterns and replacement cycle compression rates. Analysis window projections incorporated PMDA quality system evolution and AI-enabled image analysis regulatory convergence.
Revisions become necessary when objective lens supply disruptions, electron microscopy technology jumps, or pharmaceutical R&D budget reallocations materialize. Forecasts reflect assumptions about sustained NIH and institutional funding trajectories. Practitioners should monitor CDSCO inspection protocol alignment and cryo-EM correlation workflow adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
North America Digital X-Ray Market