
 Compound Acetaminophen Market | 2026-2036
Compound Acetaminophen Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Acetaminophen Market Insights
Continuous manufacturing technology is rewriting how compound acetaminophen formulations achieve batch consistency and cost efficiency. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across multiple dosage formats. GlaxoSmithKline anchors its position through R&D intensity in fixed-dose combination science. Granules India dominates API-to-formulation integration, controlling cost structures for export markets.
Compound acetaminophen refers to pharmaceutical preparations combining acetaminophen (paracetamol) with adjunct agents such as caffeine, codeine, or diphenhydramine in specified ratios, manufactured through wet granulation or direct compression to achieve uniform content distribution and specified dissolution profiles for analgesic and antipyretic therapy. Tablets occupy the largest volume share due to stability advantages and patient familiarity, though liquid formats attract pediatric and geriatric segments where swallowing difficulties limit solid uptake. The therapy area of pain relief generates the deepest margin pools, while flu treatment combinations experience faster volume growth as seasonal demand patterns intensify.
The US FDA and EMA enforce stringent bioequivalence and stability requirements for combination analgesics, compelling manufacturers to invest in accelerated aging studies and dissolution testing protocols that extend development timelines. India's CDSCO mandates local clinical bridging data for imported compound formulations, creating regulatory friction for multinational portfolio expansion. Stakeholders must monitor evolving pharmacovigilance obligations for hepatotoxicity risk labeling, as regulatory bodies tighten post-market surveillance frameworks without harmonizing cross-border standards.
Market Dynamics
Continuous manufacturing technology is collapsing traditional batch boundaries in compound acetaminophen production, compressing development timelines while FDA bioequivalence requirements simultaneously extend validation protocols. This structural tension between process acceleration and regulatory rigor defines current competitive positioning.
Growth Catalysts
- India's API manufacturing expansion:Domestic production of paracetamol active pharmaceutical ingredients reduces import dependency and enables cost-competitive export formulations for African and Southeast Asian markets.
- EMA stability testing harmonization:Standardized accelerated aging protocols reduce redundant testing burdens for combination analgesics seeking multi-country approval.
- Pain relief hospital protocols:Surgical volume recovery and multimodal analgesia guidelines drive fixed-dose combination utilization in perioperative settings.
Market Restraints
- Paracetamol raw material concentration:Four Indian and Chinese suppliers control over 60% of global API capacity, creating vulnerability to environmental shutdowns or export restrictions.
- CDSCO bridging study requirements:India's mandate for local clinical data adds 18-24 months to multinational product registration timelines.
- Hepatotoxicity labeling expansion:FDA and EMA liver injury warnings limit maximum daily dose marketing and constrain combination product positioning.
Strategic Opportunities
- Pediatric liquid formulations:Swallowing difficulties in aging populations and children create underserved demand for palatable, stable suspension technologies.
- PLI scheme incentives:India's production-linked incentive program for pharmaceutical manufacturing offers 5-20% cashback on incremental API and formulation exports.
- Direct-to-pharmacy distribution:Bypassing traditional wholesale layers through e-pharmacy integration captures margin and improves cold-chain control for temperature-sensitive liquids.
Industry Challenges
- Continuous manufacturing talent scarcity:Process analytical technology and real-time release testing expertise remains concentrated among equipment vendors and pioneer facilities.
- Dissolution method transfer complexity:Biorelevant testing protocols for combination products vary across FDA, EMA, and CDSCO guidelines, complicating unified development strategies.
- Post-market surveillance integration:Hepatotoxicity signal detection requires harmonizing disparate national adverse event databases with incompatible coding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Acetaminophen Market |
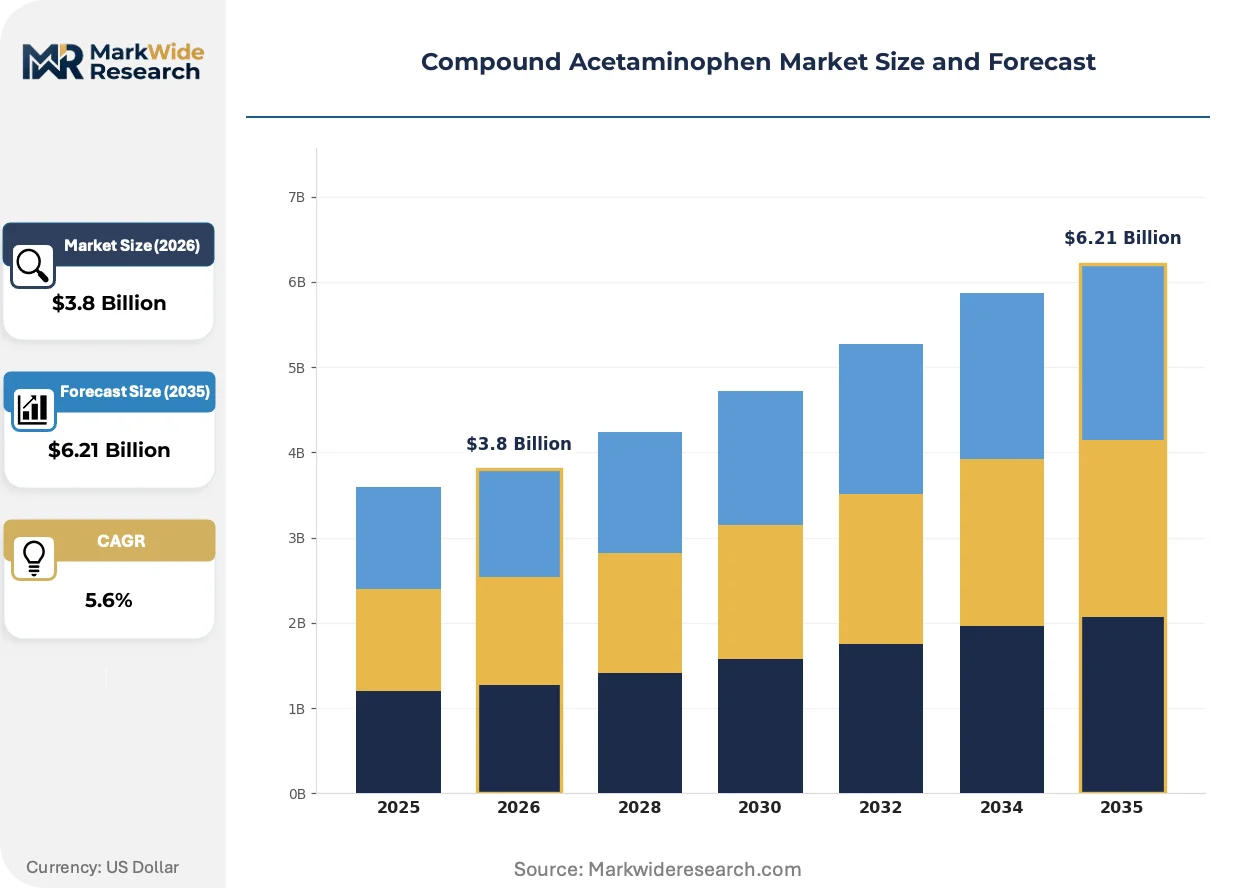
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid, Powder End User: Hospitals, Pharmacies, Retail Clinics, Homecare Distribution Channel: Online Stores, Drugstores, Supermarkets, Wholesalers Therapy Area: Pain Relief, Antipyretic, Flu Treatment, Headache Management |
| Companies Covered | Johnson & Johnson, GlaxoSmithKline, Mallinckrodt Pharmaceuticals, Teva Pharmaceutical Industries, Sanofi, Bayer AG, Perrigo Company, Sun Pharmaceutical Industries, Granules India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Acetaminophen Market Trends and Innovations
Wet granulation equipment and real-time process analytical tools are converging to enable on-demand production of combination analgesics. These shifts compress batch release timelines while raising the technical bar for market entry.
Continuous direct compression is collapsing the distinction between API synthesis and finished dosage manufacturing. Hospital procurement groups in Germany and Japan are piloting point-of-use production contracts that eliminate finished goods inventory. This technology is collapsing traditional supply chain layers and compressing working capital requirements for large-volume buyers.
REACH chemical safety dossier requirements now mandate extended environmental fate studies for paracetamol metabolites in aquatic systems. European formulation manufacturers face reformulation pressures to reduce ecotoxicological burden. Pediatric liquid specialists are responding with biodegradable packaging and reduced-volume dosing technologies to preempt regulatory restriction.
Hospital formularies are consolidating vendor lists around suppliers offering integrated pain management protocols rather than standalone products. Group purchasing organizations in the United States now prioritize vendors with real-time inventory visibility and automated replenishment systems. This concentration is most visible in integrated delivery networks across Texas and Florida, where three-supplier policies now dominate acute care procurement.
Compound Acetaminophen Market Segmentation
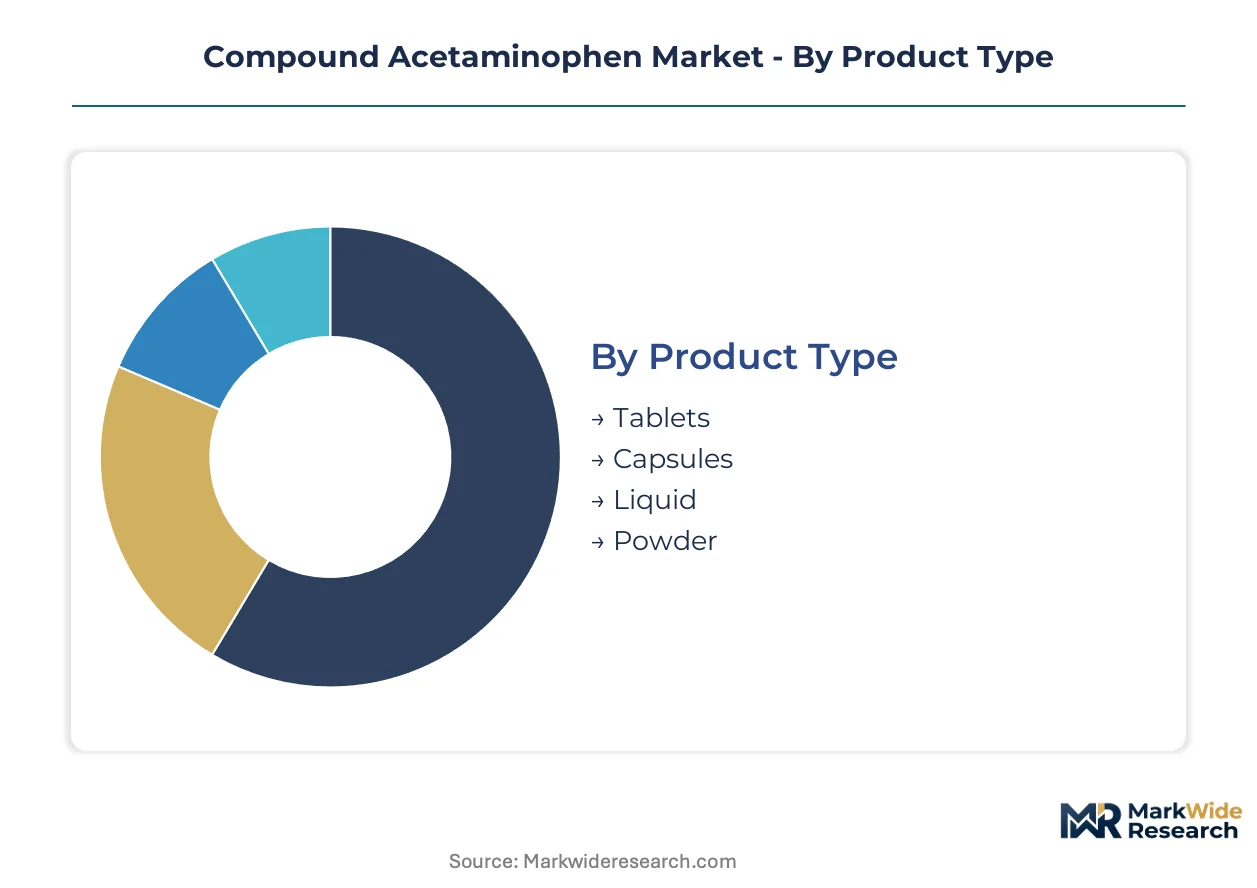
Compound acetaminophen formulations fragment across four critical dimensions that determine manufacturing investment, regulatory pathway, and margin capture. Product format dictates stability requirements and bioequivalence testing scope. End-user concentration shapes distribution economics and formulary access.
Product Type:
Tablets anchor volume through manufacturing scale and patient familiarity, while liquids command premium positioning in swallowing-limited populations.
- Tablets:Direct compression and wet granulation methods deliver uniform content distribution with dissolution profiles meeting FDA and EMA specifications. Hospital procurement in the United States and Germany concentrates tablet volumes through multimodal analgesia protocols, though swallowing difficulties in aging populations constrain expansion.
- Liquid:Suspension technologies with palatability masking serve pediatric and geriatric segments where solid dosage forms face adherence barriers. India's domestic formulation capacity targets African and Southeast Asian export markets with cost-competitive liquid packaging.
- Capsules:Gelatin and HPMC shells enable taste masking and rapid disintegration for codeine-combination products.
- Powder:Sachet formats for effervescent or dispersible applications attract travel and emergency use cases.
The dominant share belongs to Tablets, while Liquid is closing the gap fastest.
End User:
Cost tier differentiation separates institutional procurement from retail pharmacy economics.
- Hospitals:Surgical volume recovery and perioperative pain protocols drive fixed-dose combination utilization through formulary consolidation. Group purchasing organizations in Texas and Florida enforce three-supplier policies that favor vendors with real-time inventory visibility.
- Pharmacies:Community dispensing captures recurring analgesic demand through pharmacist counseling on hepatotoxicity risk management.
- Retail Clinics:Urgent care settings favor single-dose convenience packaging for acute symptom relief.
- Homecare:Self-administration trends concentrate demand in blister-packed combination products with clear dosing instructions.
Hospitals command the deepest margin pools, though Pharmacies retain volume leadership through accessibility density.
Distribution Channel:
Supply concentration among four Indian and Chinese API producers cascades through channel margin structures.
- Wholesalers:Traditional three-tier distribution maintains dominance in institutional contracting through cold-chain custody for temperature-sensitive liquids.
- Drugstores:Front-of-counter placement drives impulse purchase for headache and flu combination products.
- Online Stores:E-pharmacy integration enables direct-to-pharmacy bypass that captures margin and improves traceability.
- Supermarkets:Mass merchandising of standard-strength tablets competes on price with private label offerings.
Wholesalers retain institutional lock-in, while Online Stores are expanding most quickly through regulatory adaptation in India and Southeast Asia.
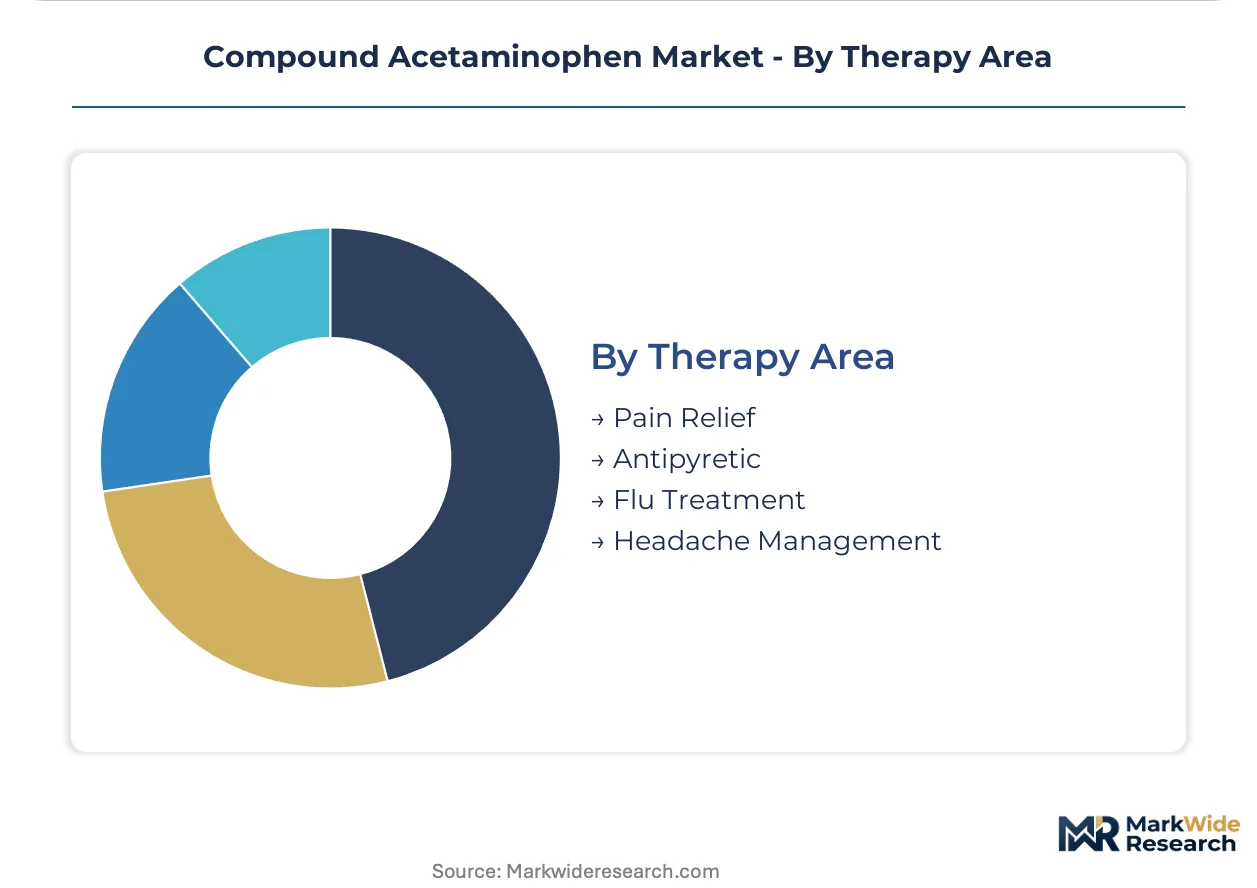
Therapy Area:
Maturity gradients separate established pain management from emerging flu combination positioning.
- Pain Relief:Perioperative multimodal protocols and chronic condition management generate the deepest revenue concentration. CDSCO bridging study requirements in India add 18-24 months to multinational product registration for opioid-containing combinations.
- Flu Treatment:Seasonal demand intensification drives faster volume expansion for antihistamine-caffeine-acetaminophen combinations. EMA stability testing harmonization reduces redundant protocol burdens for multi-country approval.
- Antipyretic:Fever management in pediatric populations favors liquid formats with dosing precision.
- Headache Management:Caffeine-adjunct positioning targets tension-type and migraine prophylaxis segments.
Pain Relief holds the revenue base, while Flu Treatment gains share fastest through seasonal stocking patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement groups in the United States concentrate volume through multimodal analgesia protocols, while India's API manufacturing expansion reshapes cost structures for export-oriented formulations.
United States
FDA bioequivalence requirements for combination analgesics extend validation timelines for fixed-dose products entering hospital formularies. Group purchasing organizations in Texas and Florida enforce three-supplier policies that favor vendors with real-time inventory visibility. New Jersey-based consumer health operations leverage established shelf presence across multiple dosage formats.
Germany
EMA stability testing harmonization reduces redundant protocol burdens for manufacturers seeking multi-country approval for flu treatment combinations. Hospital procurement in Bavaria and North Rhine-Westphalia pilots point-of-use production contracts that eliminate finished goods inventory. REACH chemical safety dossier requirements mandate extended environmental fate studies for paracetamol metabolites in aquatic systems.
India
CDSCO bridging study requirements add 18-24 months to multinational product registration timelines for opioid-containing combinations. The PLI scheme offers 5-20% cashback on incremental API and formulation exports to African and Southeast Asian markets. Hyderabad and Visakhapatnam clusters dominate API-to-formulation integration, controlling cost structures for export markets.
China
NMPA manufacturing standards for combination analgesics reshape product development cycles for domestic and export-bound formulations. Environmental shutdowns at concentrated paracetamol API facilities create supply vulnerability for global formulation manufacturers. Zhejiang and Jiangsu provinces house wet granulation and direct compression capacity serving regional hospital networks.
Japan
METI procurement guidelines favor suppliers offering integrated pain management protocols rather than standalone products. PMDA post-market surveillance frameworks tighten hepatotoxicity risk labeling for combination analgesics. The Kansai region around Osaka maintains formulation expertise for geriatric liquid formats addressing swallowing difficulties.
Compound Acetaminophen Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital, pharmacy, and direct-to-consumer vectors. The market structure fragments between multinational consumer health conglomerates with shelf-space dominance and API-integrated specialists commanding export cost advantages. Two strategic archetypes predominate: vertically integrated pharmaceutical conglomerates leveraging R&D intensity in fixed-dose combination science, and formulation specialists capturing margin through backward integration into active pharmaceutical ingredient production. Competitive moves concentrate on M&A for technology access and capacity expansion in continuous manufacturing infrastructure.
Within the multinational conglomerate tier, Johnson & Johnson and GlaxoSmithKline occupy positions defined by consumer health infrastructure and R&D depth respectively. Among API-integrated specialists, Granules India exemplifies the archetype of domestic Indian manufacturers leveraging production-linked incentives for export competitiveness. Teva Pharmaceutical Industries represents the generic-specialist position, navigating regulatory friction across FDA, EMA, and CDSCO jurisdictions.
| Leading Market Players |
|---|
| Johnson & Johnson |
| GlaxoSmithKline |
| Mallinckrodt Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Sanofi |
| Bayer AG |
| Perrigo Company |
| Sun Pharmaceutical Industries |
| Granules India |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Zhejiang and Jiangsu paracetamol API facilities compresses spot pricing for export-bound formulations while Indian PLI-subsidized capacity tightens contract terms for African and Southeast Asian buyers. This utilization divergence splits procurement behavior between cost-plus hospital tenders in the United States and formula-indexed supply agreements for emerging market distributors.
Pricing Analysis
Cost-plus contracts with paracetamol API indexation dominate hospital procurement in the United States and Germany, locking margins to raw material volatility while spot markets in India and Southeast Asia trade on weekly API quotations. Three-tier pricing structure across premium, standard, and economy levels separates patented fixed-dose combinations from branded generics and unbranded hospital tenders. Cost compression in economy-tier tablets is intensifying because Indian API-to-formulation integration under PLI subsidies erodes Chinese export competitiveness. Hospital group purchasing organizations exhibit lowest price sensitivity due to formulary consolidation power, while independent retail pharmacies in emerging markets face highest sensitivity to weekly API price swings.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical manufacturing equipment under dual-use technology frameworks constrains capacity expansion in certain jurisdictions, though paracetamol API itself remains uncontrolled. Supply concentrates in India and China, with Hyderabad, Visakhapatnam, Zhejiang, and Jiangsu housing over sixty percent of global active pharmaceutical ingredient capacity. Raw material dependencies rest on p-aminophenol intermediates, acetic anhydride, and specialized wet granulation equipment. Single-source vulnerability from environmental shutdowns at concentrated Chinese API facilities poses structural risk. Distribution runs through three-tier wholesale networks for institutional cold-chain custody, with direct-to-pharmacy e-commerce bypass emerging fastest in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound acetaminophen markets reward service-layer attachment, where real-time inventory visibility and automated formulary replenishment contracts expand faster than standalone product margins in hospital procurement.
For Market Incumbents: Entrench formulary position through backward integration into continuous manufacturing infrastructure and real-time release testing capability. Johnson & Johnson and GlaxoSmithKline face substitution threat from Indian API-integrated specialists capturing African and Southeast Asian tenders. Capacity addition in Hyderabad and Visakhapatnam clusters, not legacy Western facilities, anchors cost defense. For New Entrants and Emerging Players: Build out pediatric liquid formulation capacity with biodegradable packaging to preempt REACH-driven environmental restrictions in Europe. White-space concentrates in geriatric swallowing-difficulty segments across Japan and aging Western populations. Go-to-market angle: direct-to-pharmacy e-commerce integration bypassing wholesale layers in India and Southeast Asia. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous manufacturing equipment as process analytical technology commoditizes, compressing returns for late equipment buyers. Long-term viability favors API-to-formulation integrated specialists with captive paracetamol supply and PLI subsidy access. Signal to watch: CDSCO bridging study requirement relaxation for opioid-containing combinations, which would accelerate multinational product registration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Real-time release testing compresses FDA validation timelines for fixed-dose combinations. |
| API Backward Integration | Hyderabad and Visakhapatnam clusters capture PLI cashback on export formulation volumes. |
| Direct-to-Pharmacy Distribution | E-pharmacy bypass improves cold-chain control for temperature-sensitive liquid suspensions. |
| Pediatric Liquid Formulation Development | Palatability masking technologies address geriatric swallowing barriers in Japan and Europe. |
| Hospital System Partnership | Texas and Florida GPO three-supplier policies favor vendors with automated replenishment systems. |
Research Methodology
Desk research of FDA bioequivalence filings, EMA stability protocols, CDSCO registration databases, and Indian PLI scheme disclosures preceded structured interviews with pharmaceutical manufacturing executives, regulatory affairs directors, hospital procurement managers, and API supply chain specialists. Primary fieldwork combined with secondary validation across customs trade records, pharmaceutical export data, and hospital formulary databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include current FDA bioequivalence timelines, EMA stability testing harmonization scope, and CDSCO bridging study requirements; variables tested included PLI subsidy renewal rates and REACH environmental restriction severity. The analytical framework segments by product type, end user, distribution channel, and therapy area across the analysis window. CAGRs derive from regression against surgical volume recovery patterns and multimodal analgesia protocol adoption curves, with dissolution method transfer complexity and hepatotoxicity labeling expansion as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized API producers or sudden environmental shutdown enforcement would shift outcomes. Material shifts in CDSCO registration requirements, PLI scheme eligibility, or FDA continuous manufacturing guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Stomach Cancer Drugs Market