
 Hardbanding Services Market | 2026-2036
Hardbanding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hardbanding Services Market Foresight
Buyer concentration among integrated drilling contractors and national oil companies is expanding as procurement teams consolidate vendor lists and demand volume-based service agreements. Hardfacing Technologies, LLC leverages proprietary wire-feed processes to anchor premium positioning in Gulf Coast workshop networks. National Oilwell Varco sustains global channel control through captive hardbanding cells co-located with drill pipe manufacturing. Arnco Technology specializes in tungsten carbide matrix formulations that differentiate its field service crews in shale plays.
Hardbanding services apply wear-resistant weld overlays to drill pipe tool joints and centralizer bands, typically depositing chromium carbide or tungsten carbide composites at 58-65 HRC to mitigate casing wear and extend string life in extended-reach drilling. The industrial purpose centers on reducing friction-generated heat and galling between rotating steel surfaces and wellbore casing walls. Overlay services dominate current revenue as operators prioritize preventive application during pipe recertification cycles. Chromium carbide formulations lead material type selection due to lower cost per deposit and established API qualification protocols, while tungsten carbide segments capture margin pools in high-temperature, high-pressure wells where wear rates intensify.
API standards govern deposit hardness and chemistry qualification, while NACE MR0175/ISO 15156 restricts sulfide stress cracking susceptibility in sour gas environments, effectively filtering market access for uncertified applicators. EPA emissions oversight on welding fume capture and OSHA hexavalent chromium exposure limits raise compliance costs for workshop-based hardbanding operations. Stakeholders must monitor evolving downhole automation trends and robotic welding adoption that could displace manual field crews and reshape service delivery economics.
Market Dynamics
Directional drilling contractors in the Permian Basin and other unconventional oil provinces are extending lateral lengths beyond 15,000 feet, forcing hardbanding applicators to engineer deposits that survive higher torque loads and more aggressive rotation cycles.
Growth Catalysts
- API Specification 7G:The updated standard mandates stricter deposit hardness testing, filtering uncertified workshops and concentrating demand among qualified applicators with automated weld controls.
- Extended-reach drilling:Operators in the Delaware and Midland sub-basins now rotate strings for 200+ hours per lateral, accelerating tool joint wear and shortening recertification intervals.
- Tungsten carbide matrix advances:New powder metallurgy processes enable 62-67 HRC deposits that reduce casing wear by 40% compared to legacy chromium carbide formulations in high-pressure formations.
Market Restraints
- Ferro-tungsten price volatility:Tungsten ore supply concentrates in China and Vietnam, exposing applicators to 30-50% input cost swings that compress margins on fixed-price service contracts.
- Workshop emissions compliance:EPA welding fume capture mandates and OSHA hexavalent chromium exposure limits require capital outlays of $150,000-$400,000 per facility, raising barriers for independent operators.
- Robotic welding substitution:Automated deposition cells now achieve 0.3mm tolerance consistency that manual field crews cannot match, threatening the economics of portable hardbanding services.
Strategic Opportunities
- Sour service expansion:NACE MR0175/ISO 15156 qualification for sulfide stress cracking resistance opens premium pricing in the Sichuan Basin and other high-H2S provinces where uncertified deposits fail.
- Drill pipe OEM integration:Co-locating hardbanding cells with pipe manufacturing facilities in Houston and Navasota eliminates transport costs and captures preventive application volume during new pipe production.
- Geothermal drilling crossover:Hardbanding deposits engineered for 300°C+ bottom-hole temperatures transfer directly to geothermal projects in Nevada and Utah where casing wear rates rival shale plays.
Industry Challenges
- Certified welder scarcity:AWS D1.1 and API 1104 qualified technicians command 35% wage premiums in the Permian Basin, constraining expansion for field service crews.
- Deposit qualification timelines:Full API 7G and NACE protocol testing requires 8-12 weeks, delaying commercialization of reformulated carbide matrices and freezing R&D pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardbanding Services Market |
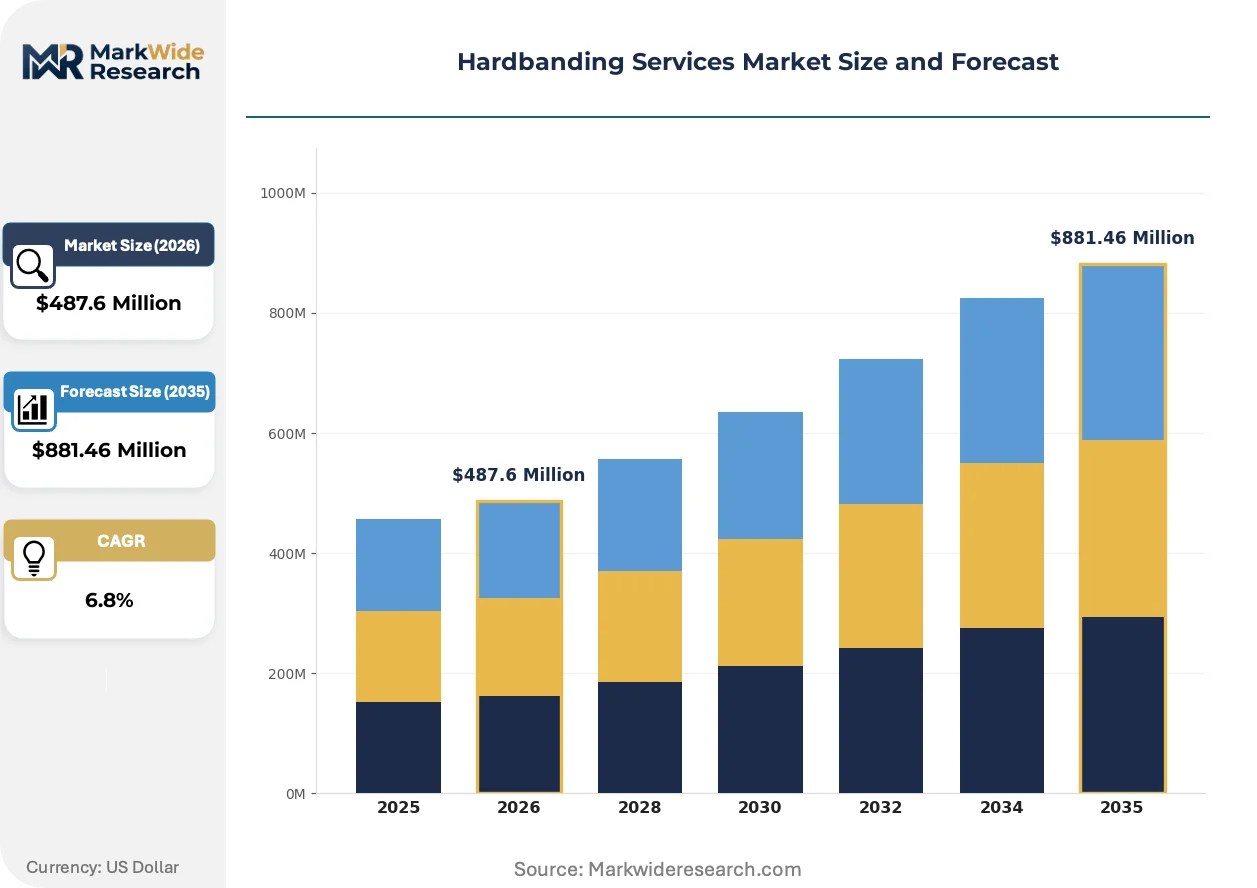
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overlay, Hardfacing, Wear-resistant Coating, Repair Material Type: Chromium Carbide, Tungsten Carbide, Nickel-based Alloy, Others Industry Vertical: Oil & Gas, Mining, Construction, Marine Deployment Method: Field Service, Workshop Service, On-site Application, Remote Monitoring |
| Companies Covered | Hardfacing Technologies, LLC, Welding Alloys & Services, Inc., Midwest Hardfacing, Inc., Allied Grinding & Machine, Inc., Therm-A-Line Industries, Inc., ITR International, Hard Steel Lines, LLC, Arnco Technology, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardbanding Services Market Shifts & Advancements
Laser cladding and robotic wire-feed deposition are compressing the traditional workshop-field service boundary, enabling precision hardbanding at rig site rather than during pipe recertification cycles.
Pulsed laser cladding systems now deposit tungsten carbide-cobalt matrices with 0.1mm dilution control, eliminating post-weld machining. Directional drilling contractors in the Eagle Ford Shale are piloting mobile units that apply overlays between bit trips, cutting pipe rotation downtime by 60%. This precision is rewriting the economics of preventive maintenance by shifting hardbanding from scheduled workshop events to just-in-time field interventions.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants on chromium electroplating operations is pressuring hardbanding workshops to convert to tungsten carbide wire-feed processes. The regulatory friction elevates compliance costs for legacy chromium carbide applicators while creating certification premiums for NESHAP-compliant facilities. Gulf Coast service providers are consolidating into shared fume-capture facilities to amortize scrubber investments across multiple deposition lines.
Integrated drilling contractors now bundle hardbanding into multi-year pipe management agreements rather than purchasing spot overlay services. This contractual unbundling of preventive wear mitigation from pipe rental compresses margins for independent applicators while rewarding vertically integrated service networks. The shift is most visible in the Permian Basin, where Patterson-UTI and Helmerich & Payne have internalized hardbanding capacity to capture lifecycle cost savings.
Hardbanding Services Market Segmentation
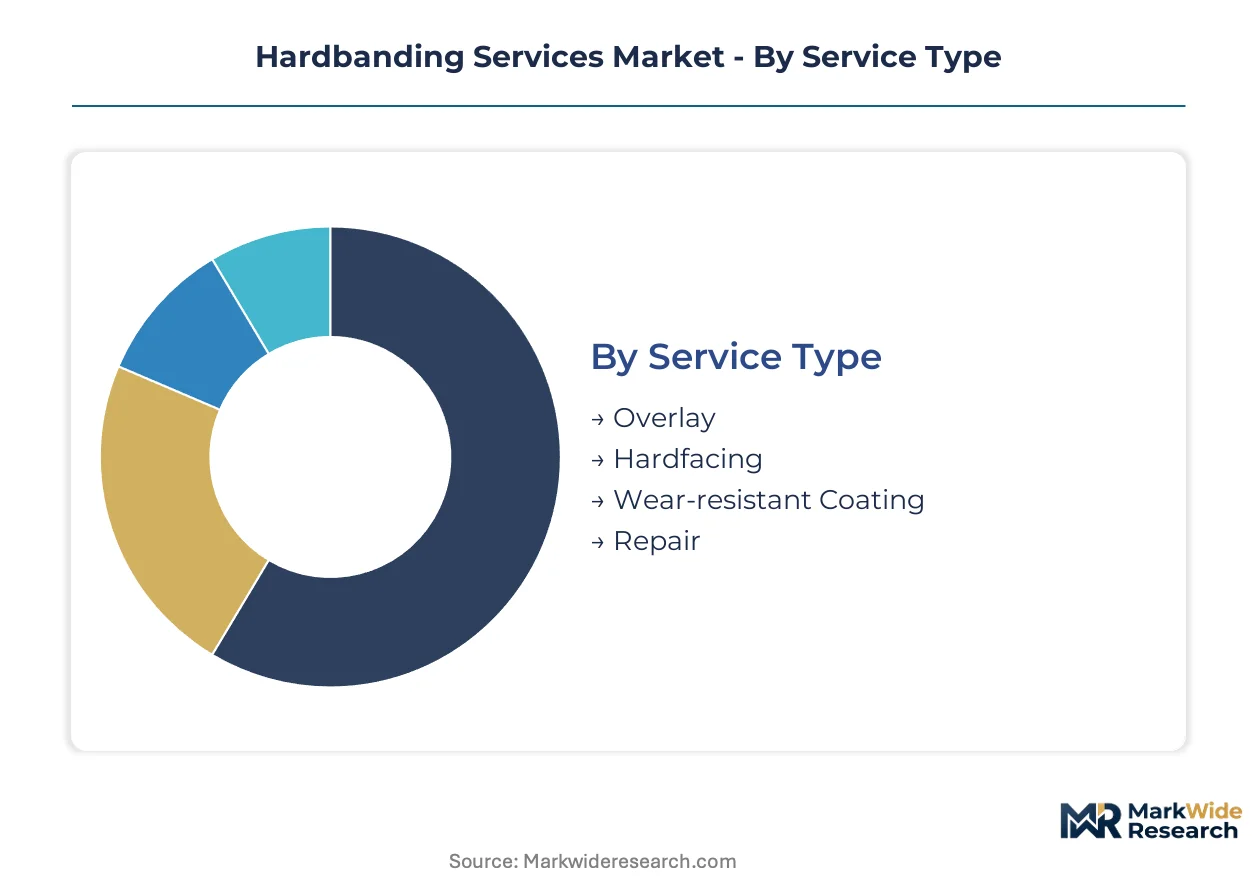
Hardbanding services fragment across four dimensions that determine pricing power, certification requirements, and customer lock-in. Service type and material chemistry drive technical differentiation, while deployment method shapes margin structure and geographic reach.
Service Type:
Standalone overlay work dominates preventive maintenance budgets, while integrated hardfacing commands premium pricing in OEM supply chains.
- Overlay:Weld deposits of 58-65 HRC carbide matrices applied to tool joints during scheduled recertification cycles. Permian Basin operators rotate drill strings 200+ hours per lateral, compressing intervals between overlay applications and sustaining workshop throughput.
- Hardfacing:Dense tungsten carbide deposition for extreme wear environments requiring 62-67 HRC hardness. Sour gas developments in the Sichuan Basin and Middle East drive NACE MR0175 qualification premiums for hardfacing crews.
- Wear-resistant Coating:Thin-film ceramic and metal-matrix alternatives for non-critical centralizer bands.
- Repair:Remedial rework of damaged tool joints, typically priced at 60-70% of new overlay rates.
Overlay leads volumes today; hardfacing is gaining share fastest.
Material Type:
Cost tiers separate commodity carbide formulations from engineered matrix composites.
- Chromium Carbide:Lower-cost deposits qualified under legacy API protocols. EPA NESHAP compliance costs on hexavalent chromium exposure are forcing Gulf Coast workshops toward closed-loop fume capture or material substitution.
- Tungsten Carbide:Powder metallurgy advances enable 40% casing wear reduction versus chromium carbide. Ferro-tungsten price volatility tied to Chinese ore supply creates margin pressure on fixed-price contracts.
- Nickel-based Alloy:Corrosion-resistant matrices for geothermal and sour service crossover applications.
- Others:Experimental cobalt-chrome and boride formulations in qualification pipelines.
Chromium carbide holds the installed base; tungsten carbide climbs the fastest on performance premiums.
Industry Vertical:
Application intensity varies sharply by sector wear rates and regulatory exposure.
- Oil & Gas:Dominant vertical with directional drilling driving tool joint consumption. Extended-reach laterals beyond 15,000 feet multiply contact cycles against casing walls.
- Mining:Dragline bucket teeth and crusher rolls require thick deposits in abrasive ore environments. Australian iron ore operations sustain mobile hardbanding fleet utilization.
- Construction:Piling equipment and tunnel boring machine cutters represent intermittent demand with lower specification thresholds.
- Marine:Offshore platform mooring connectors and subsea riser joints in corrosive seawater environments.
Oil and gas anchors revenue; mining shows the steepest expansion trajectory on equipment fleet growth.
Deployment Method:
Customer type stratifies between integrated contractors preferring captive capacity and independents buying spot field service.
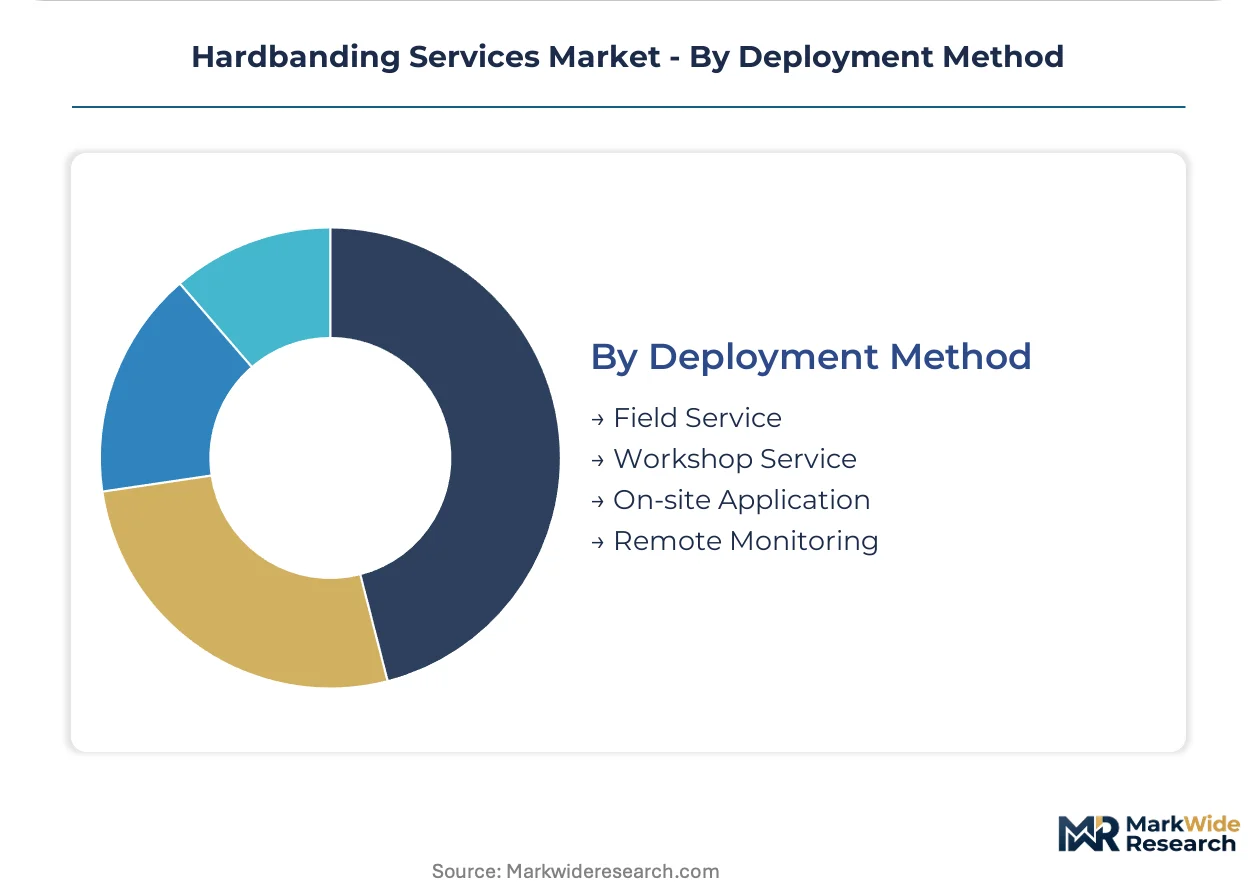
- Field Service:Portable wire-feed units at rig sites reduce pipe transport costs. Robotic welding cells achieving 0.3mm tolerance threaten manual crew economics.
- Workshop Service:Fixed facilities with automated deposition controls and fume capture infrastructure. OSHA hexavalent chromium limits and EPA mandates require $150,000-$400,000 capital per facility.
- On-site Application:Co-located cells at pipe manufacturing plants in Houston and Navasota eliminating logistics friction.
- Remote Monitoring:Emerging sensor-based wear tracking to predict optimal reapplication timing.
Workshop service captures the volume base; on-site application expands most quickly through OEM integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands a disproportionate share of hardbanding service revenue compared to Saudi Arabia, where state-directed drilling programs generate concentrated but less fragmented demand. This divergence shapes how applicators configure their workshop networks and field service footprints.
United States
Directional drilling contractors in the Permian Basin of West Texas and southeastern New Mexico rotate drill strings 200+ hours per extended-reach lateral, accelerating tool joint wear and compressing recertification intervals. EPA National Emission Standards for Hazardous Air Pollutants enforcement on chromium electroplating operations pressures Gulf Coast workshops to convert to closed-loop fume capture systems. Houston and Navasota host the densest concentration of hardbanding cells co-located with drill pipe manufacturing facilities.
Canada
Steam-assisted gravity drainage operations in northern Alberta impose thermal cycling stresses on drill strings that exceed conventional wear rates. Health Canada and provincial regulators enforce welding fume exposure limits that match or exceed OSHA thresholds, raising compliance costs for Calgary-based service providers. Edmonton maintains specialized hardbanding capacity serving oil sands operators with sour service qualification requirements.
Saudi Arabia
Aramco's drilling programs in the Ghawar and Safaniya fields generate predictable volume demand for high-specification hardbanding deposits. The national oil company's procurement consolidation favors vendors with API 7G and NACE MR0175 pre-qualification, filtering market access for independent applicators. Dhahran anchors the Eastern Province's service cluster, with workshops serving both onshore and offshore rig fleets.
China
Sichuan Basin shale gas development with high-H2S content requires sulfide stress cracking resistant deposits that command qualification premiums. MIIT and GB standards on welding equipment certification create regulatory friction for imported deposition technologies. Chongqing and Chengdu host the principal hardbanding service concentrations for domestic unconventional gas drilling.
United Arab Emirates
Offshore drilling contractors in the Zakum and Umm Shaif fields demand hardbanding formulations that withstand corrosive seawater and high-temperature formation contact. ADNOC's technical specifications increasingly mirror API 7G with additional sour service protocols. Abu Dhabi and Dubai service bases support rig fleets operating across the Arabian Gulf.
Hardbanding Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple service tiers, creating a bifurcated structure where scale advantages and technical depth operate as distinct competitive currencies. The vendor base organizes around three archetypes: integrated drilling contractors with captive hardbanding capacity, independent workshop operators with regional density, and technology licensors with proprietary deposition processes. Market consolidation proceeds through acquisition of qualified welding technicians rather than facility assets, while strategic partnerships between applicators and drill pipe distributors reshape customer access patterns.
Within the independent specialist tier, Hardfacing Technologies LLC and Arnco Technology exemplify contrasting positioning strategies. National Oilwell Varco anchors the integrated contractor segment through captive capacity co-located with manufacturing. These three entities represent the dominant competitive anchors without exhausting the competitive set.
| Leading Market Players |
|---|
| Hardfacing Technologies, LLC |
| Welding Alloys & Services, Inc. |
| Midwest Hardfacing, Inc. |
| Allied Grinding & Machine, Inc. |
| Therm-A-Line Industries, Inc. |
| ITR International |
| Hard Steel Lines, LLC |
| Arnco Technology |
| National Oilwell Varco |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up workshop operators across the Gulf Coast anchor supply discipline through centralized fume-capture investments, translating compliance scale into pricing power over independent single-facility competitors. Their consolidated procurement of ferro-tungsten and chromium carbide wire feedstock creates volume leverage that squeezes margins for non-integrated field service crews bidding fixed-price contracts.
Pricing Analysis
Capacity additions in Houston and Navasota are reshaping price floors for API-qualified overlay services. Contract-based long-term pipe management agreements dominate, with price differentiation driven by NACE MR0175 certification tier and volume scale. Cost compression in standard chromium carbide deposits is intensifying because EPA NESHAP compliance outlays favor consolidated operators. Integrated drilling contractors exhibit lowest price sensitivity due to lifecycle cost framing, while independent directional drilling operators remain most responsive to spot-rate competition.
Supply Chain Analysis
Domestic-content mandates in Saudi Arabia and China's MIIT equipment certification rules are reshaping sourcing patterns for deposition technologies. Raw material supply concentrates in China, Vietnam, and Kazakhstan for tungsten ore, with secondary dependence on South African chromium. Ferro-tungsten price volatility tied to Chinese export quotas creates single-source vulnerability for Western applicators. Distribution runs through co-located OEM cells at drill pipe manufacturing facilities and regional workshop networks serving rig-site field service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA welding fume compliance costs in the United States run three to four times above equivalent regulatory thresholds in the Middle East, compressing Western operator margins while elevating returns for Gulf-based service clusters.
For Market Incumbents: To counter robotic welding substitution threatening manual field crew economics, incumbents should deepen backward integration into automated deposition cell manufacturing and anchor channel control through exclusive pipe management agreements with Permian Basin drilling contractors. Certification investment in NACE MR0175 qualification for sour service deposits creates defensive moats against uncertified competitors in high-H2S provinces. For New Entrants and Emerging Players: The price-point gap between premium tungsten carbide hardfacing and economy-grade chromium carbide overlay creates entry space for mid-tier applicators targeting geothermal drilling crossover demand in Nevada and Utah. White-space concentration sits with mobile laser cladding units serving Eagle Ford Shale operators between bit trips. A technology-licensing go-to-market angle with established drill pipe distributors accelerates customer access without captive workshop investment. For Investors and Strategic Acquirers: Integrated drilling contractors are the most active acquirer in this space, seeking qualified welding technician pools rather than facility assets. Long-term viability over the coming decade hinges on automation adoption curves and sour service qualification premiums. The signal to watch is ADNOC and Aramco procurement consolidation favoring pre-qualified vendor lists, which will accelerate independent operator exit opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Automated Deposition Cell Manufacturing | Captures equipment margin and locks in API 7G process consistency for workshop networks. |
| NACE MR0175 Qualification Investment | Opens premium pricing in Sichuan Basin and Middle East sour gas developments. |
| Mobile Laser Cladding Fleet Deployment | Enables just-in-time field application between bit trips, cutting pipe rotation downtime. |
| Co-location Partnership with Drill Pipe OEMs | Eliminates logistics friction and captures preventive application volume during new pipe production. |
| Geothermal Drilling Technology Transfer | Repurposes 300°C-qualified deposits for Nevada and Utah projects with comparable casing wear rates. |
Research Methodology
Direct dialogue with hardbanding workshop operators, API-qualified welding technicians, directional drilling procurement managers, and EPA compliance officers grounded qualitative findings, cross-referenced against customs data on ferro-tungsten import flows, API specification documentation, NACE MR0175 qualification registries, and OSHA enforcement records. Bottom-up facility capacity counts and top-down drilling activity models were triangulated to anchor volume estimates.
Segmentation outputs across service type, material chemistry, deployment method, and industry vertical were generated through the projection horizon. CAGRs were derived from rig-count trajectories, lateral length extension rates, and recertification interval compression factors specific to Permian Basin and Sichuan Basin drilling economics.
Caveats apply where ferro-tungsten price spikes, accelerated robotic welding adoption, or NACE standard revisions could materially shift the outlook. A small set of triggers—Chinese ore export policy, EPA NESHAP enforcement intensity, and integrated contractor internalization rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Industrial Maintenance Products Market
Construction Services
3D Concrete Printing Services Market
Construction Services
NDT and Inspection Market
Construction Services
Work Order Management Market
Construction Services
Dust Suppression Control Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Construction TIC Market
Construction Services
Condenser Cleaners Market
Construction Services
Die Casting Services Market
Construction Services
Construction Project Management Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
MENA Architectural Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Excavating Contractor Market
Construction Services
Gutter Cleaning Services Market