
 Green UPS Market | 2026-2036
Green UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Green UPS Market Analysis
The capability gap between integrated power electronics manufacturers and component-assemblers is rotating competitive advantage toward firms with in-house semiconductor and battery management competencies. Schneider Electric leverages its vertically integrated energy management portfolio to control project economics across large-scale deployments. Eaton Corporation anchors its position through specialized medium-voltage integration for industrial microgrids. Huawei Technologies competes on manufacturing scale in modular architectures, though its geographic reach faces regulatory constraints in several Western markets.
A green uninterruptible power supply converts incoming AC power to DC for battery charging, then inverts stored DC back to conditioned AC output with efficiency thresholds typically exceeding 96 percent in double-conversion online topologies, designed to eliminate downtime while minimizing standby losses and refrigerant-based cooling dependency. Modular UPS configurations now lead capital deployment in hyperscale data centers because they match incremental load growth without stranding capacity. Lithium-ion battery technology captures the fastest expansion across product categories, displacing valve-regulated lead-acid systems where cycle life and footprint constraints dominate total cost of ownership calculations.
EPA Energy Star specifications and EU Ecodesign Directive standby power limits now shape product development roadmaps, forcing redesign of rectifier and inverter stages to meet loss thresholds. China's GB standards on UPS energy efficiency, administered by MIIT, create a parallel compliance track for suppliers serving state-backed data center construction programs. Stakeholders must monitor divergence between regional efficiency test protocols and carbon accounting methodologies, as misalignment threatens to fragment certification requirements and complicate multinational procurement standardization.
Market Dynamics
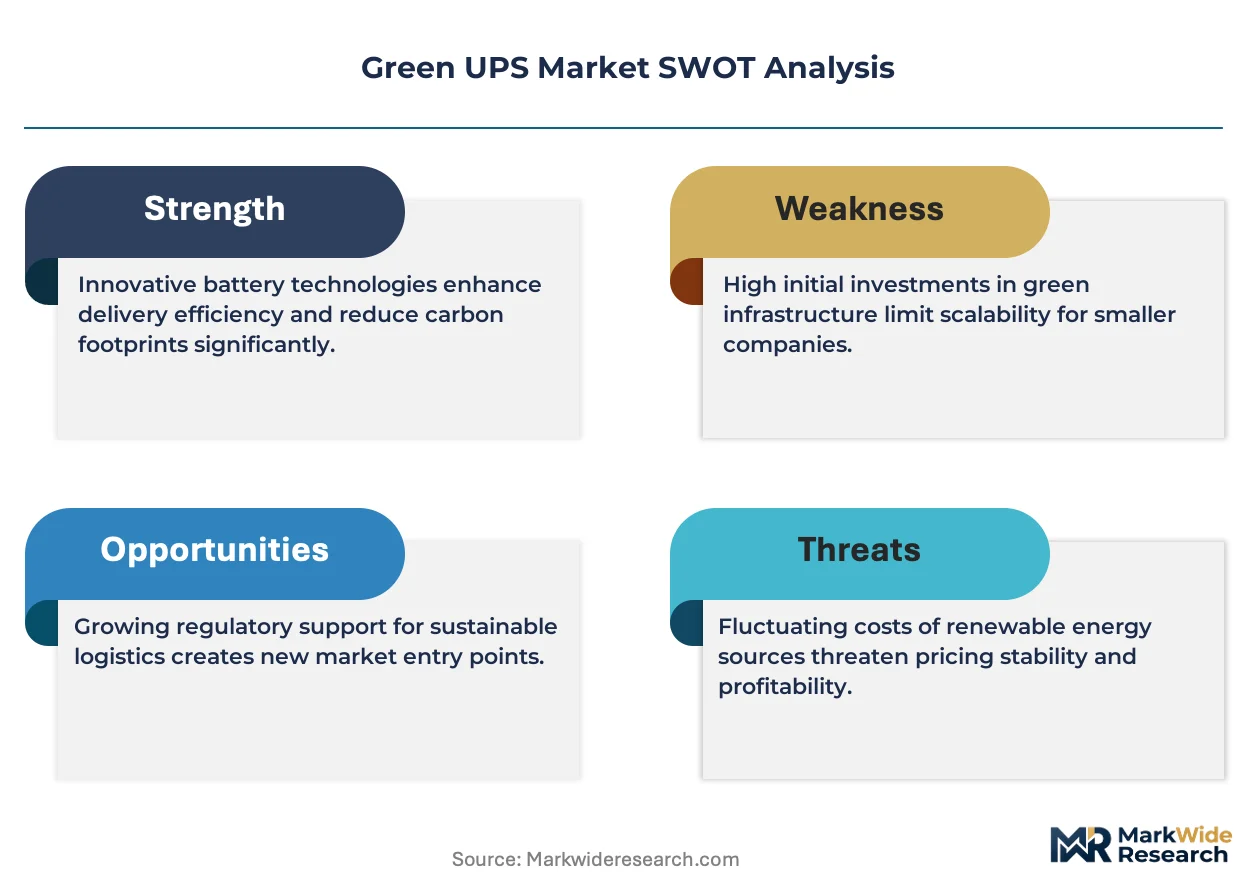
Lithium-ion battery chemistry is compressing total cost of ownership curves while EPA Energy Star and EU Ecodesign mandates force rectifier redesigns, creating a capability sieve that favors integrated power electronics manufacturers over component-assemblers.
Growth Catalysts
- EPA Energy Star 2.0 standby loss thresholds:Data center operators in the United States face procurement mandates requiring sub-2% standby power consumption, accelerating replacement cycles for legacy valve-regulated lead-acid installations.
- Hyperscale facility buildouts:Cloud infrastructure expansion in Germany, the United States, and China is concentrating demand for modular architectures that match incremental load growth without stranding capacity.
- Lithium iron phosphate cell chemistry:Cycle life exceeding 5,000 cycles and footprint reductions of 40-60% versus lead-acid systems are unlocking rooftop and constrained-facility deployments previously uneconomical for UPS installation.
Market Restraints
- Lithium carbonate price volatility:Battery pack cost structures remain exposed to upstream mining concentration in South American salars and Australian hard-rock deposits, compressing margins during commodity spikes.
- Semiconductor fabrication bottlenecks:Insulated-gate bipolar transistor and silicon carbide wafer supply concentrates in East Asian foundries, extending lead times for high-efficiency rectifier and inverter stage production.
- Fire safety code fragmentation:Divergent NFPA 855, UL 9540A, and local jurisdiction interpretations for lithium-ion energy storage systems create compliance friction and insurance underwriting uncertainty.
Strategic Opportunities
- India data center construction pipeline:PLI scheme incentives for electronics manufacturing and state-level data center policies in Maharashtra and Karnataka create first-mover positioning for localized assembly operations.
- Second-life battery integration:Decommissioned electric vehicle cells are converging with stationary power applications, enabling circular economy service models and differentiated ESG positioning for fleet operators.
- Edge computing micro-facilities:5G base station and autonomous vehicle infrastructure deployments represent underpenetrated demand for sub-10kVA modular systems with extreme temperature tolerance.
Industry Challenges
- Power electronics engineering talent scarcity:Design of wide-bandgap semiconductor gate drivers and magnetics optimization requires specialized expertise concentrated in automotive and aerospace sectors, creating recruitment friction.
- Legacy facility electrical infrastructure incompatibility:Retrofit installations face integration complexity with aging switchgear and grounding systems originally specified for lead-acid battery characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green UPS Market |
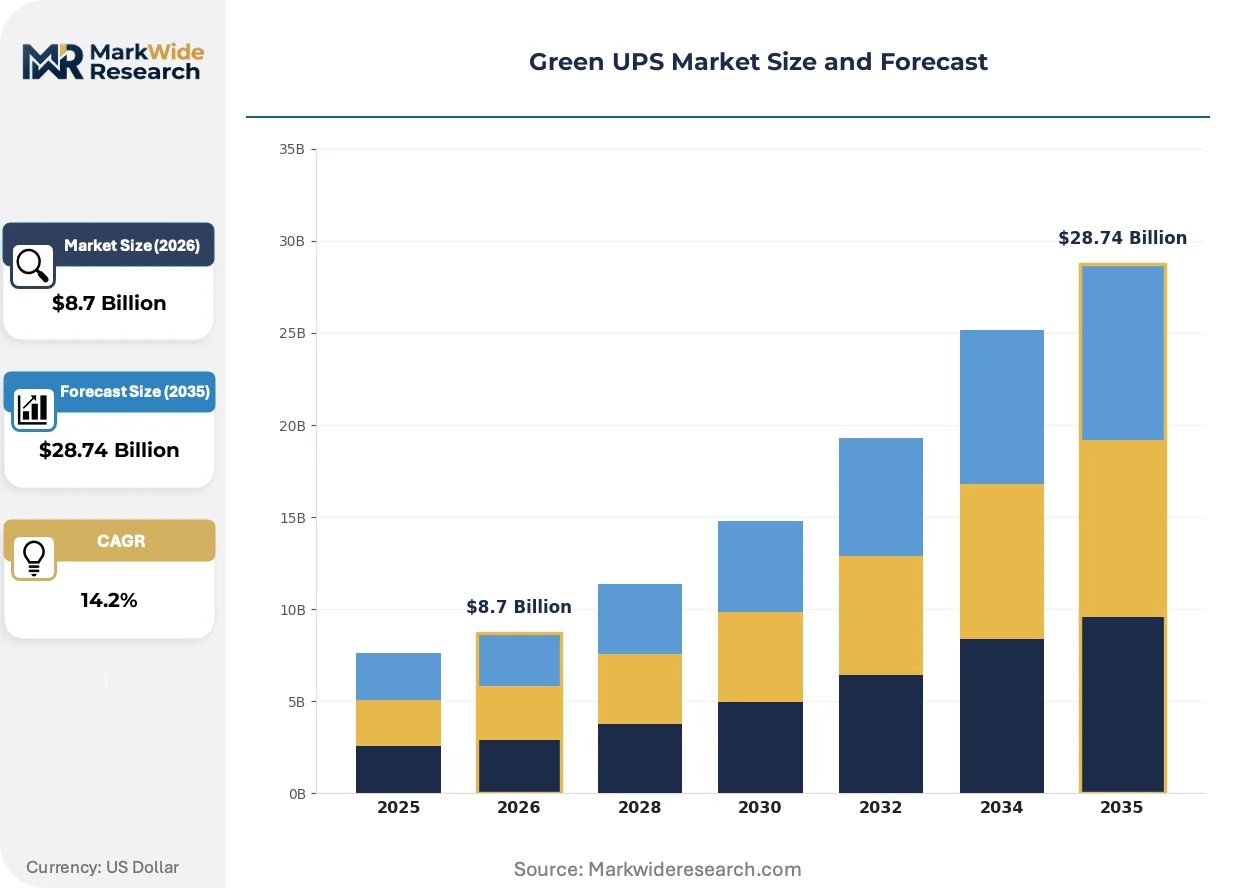
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone UPS, Modular UPS, Rack-mounted UPS, Hybrid UPS Energy Source: Solar Energy, Wind Energy, Biofuel, Grid Energy End User: Data Centers, Telecommunications, Healthcare, Retail Technology: Li-ion Batteries, Flywheel Technology, Fuel Cell Technology, Supercapacitors |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group Corp, Huawei Technologies, ABB Ltd, Delta Electronics, Inc., Emerson Electric Co., Siemens AG, Cyber Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green UPS Market Emerging Trajectories
Solid-state battery architectures and silicon carbide power semiconductors are converging to redefine efficiency frontiers, while procurement patterns compress toward lifecycle service contracts that internalize operational risk.
Silicon carbide MOSFETs in three-level neutral-point-clamped topologies are supplanting silicon IGBT-based rectifier designs in double-conversion online systems. Hyperscale operators in the United States and Germany are specifying 98% efficiency targets for new builds, compressing payback periods for premium hardware investments. The technology is supplanting legacy 96% efficiency platforms in facilities where cooling load reduction drives total facility economics.
EU Ecodesign Directive standby power limits are forcing inverter stage redesigns across the 10-400kVA product range. Manufacturers must now certify sub-1% standby losses or face market exclusion across the twenty-seven member states. Medium-voltage integration projects for industrial microgrids in Germany face the tightest compliance timelines, with Q3 2025 certification deadlines already locking engineering resources.
Power-as-a-service contracting is displacing capital purchase models in enterprise data center verticals. Schneider Electric and Eaton Corporation are restructuring offerings to bundle hardware, installation, and fifteen-year maintenance into single operational expenditure lines, transferring battery replacement risk to vendors. This pattern is most visible in the United States financial services sector, where CIOs face capital allocation constraints and prefer balance sheet efficiency over asset ownership.
Green UPS Market Segmentation
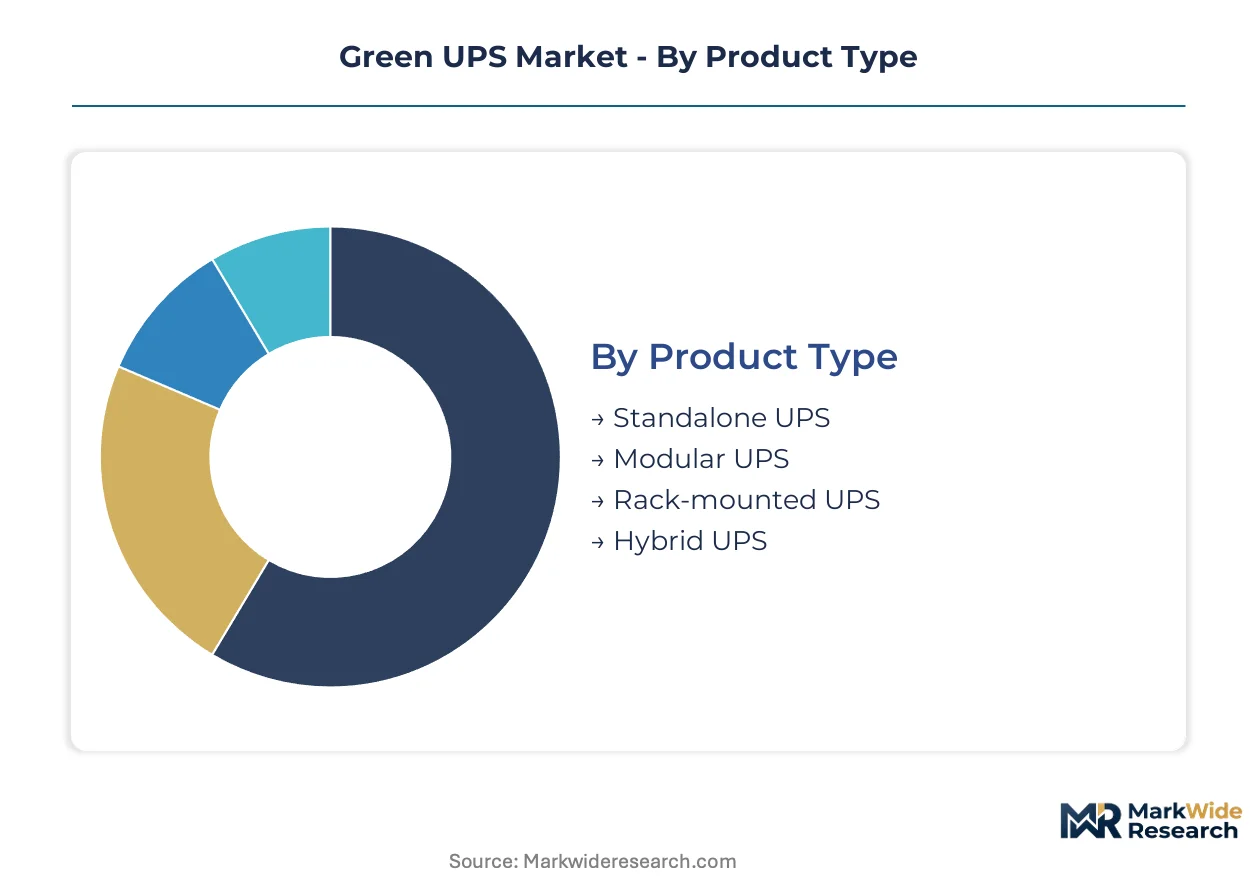
Segmentation in the Green UPS Market reveals how procurement channels, efficiency mandates, and facility-scale requirements reshape product mix across customer categories. Channel concentration varies sharply by segment, with hyperscale operators driving modular architectures through direct manufacturer relationships while smaller facilities rely on distributor networks for standardized units.
Product Type:
Channel mix diverges by scale: hyperscale data centers source modular systems through direct procurement, while standalone units flow through electrical distributors serving enterprise and healthcare verticals.
- Modular UPS:Scalable rack-based units allow capacity additions in 50-200kVA increments without system shutdown. Demand concentrates in Germany and the United States where hyperscale cloud operators face EPA Energy Star 2.0 mandates and cannot afford stranded capacity during phased facility buildouts.
- Standalone UPS:Monolithic double-conversion systems dominate retrofit installations in legacy healthcare and retail infrastructure. Procurement runs through regional electrical distributors in China and India, where state-backed hospital modernization programs and commercial retail expansion create volume.
- Rack-mounted UPS:Compact 1-10kVA units integrate into server cabinets for edge computing deployments. The format serves 5G base station rollouts and autonomous vehicle infrastructure where footprint constraints dominate.
- Hybrid UPS:Systems combining battery storage with renewable integration and grid-tie capability. Adoption tracks behind pure battery configurations due to control complexity and local interconnection standards.
By volume, standalone UPS leads in unit shipments across distributor channels. By growth pace, modular UPS is gaining share fastest as hyperscale construction accelerates.
Energy Source:
Cost tier structures segment procurement: premium solar-hybrid installations command engineering-intensive integration, while grid-tied systems compete on capital efficiency for budget-constrained facilities.
- Grid Energy:Conventional utility-sourced power with high-efficiency rectification remains the dominant input for double-conversion systems. Installations in the United States face tightening EPA standby loss thresholds that force premium component selection.
- Solar Energy:Photovoltaic-coupled UPS with DC bus integration eliminates conversion losses. Demand clusters in China where MIIT-administered GB standards incentivize renewable-hybrid data center construction.
- Wind Energy:Turbine-coupled systems for industrial microgrids and remote telecommunications. Variable input stability challenges limit penetration to sites with consistent wind resource profiles.
- Biofuel:Liquid fuel cell or generator backup for extended runtime requirements. Niche applications include healthcare facilities in regions with unreliable grid infrastructure.
By installed base, grid-tied systems dominate. By expansion trajectory, solar-hybrid configurations are climbing the fastest as carbon neutrality commitments harden procurement specifications.
End User:
Application requirements dictate technology selection: data centers prioritize efficiency and modularity, while healthcare mandates runtime reliability above capital cost.
- Data Centers:Hyperscale and colocation facilities drive lithium-ion adoption and silicon carbide rectifier specifications. Construction in Germany, the United States, and China concentrates demand for 98% efficiency targets.
- Healthcare:Hospitals and clinics require UL 9540A-certified battery systems with minimum 30-minute runtime for life safety loads. Procurement emphasizes NFPA 855 compliance over energy density optimization.
- Telecommunications:5G infrastructure and rural cell towers demand wide-temperature operation and minimal maintenance. Edge computing micro-facilities represent underpenetrated demand for sub-10kVA modular systems.
- Retail:Point-of-sale and inventory management backup prioritizes capital efficiency over premium efficiency metrics. Standardized 1-3kVA units dominate through distributor channels.
By revenue concentration, data centers lead. By regulatory pressure intensity, healthcare exhibits the steepest compliance cost escalation.
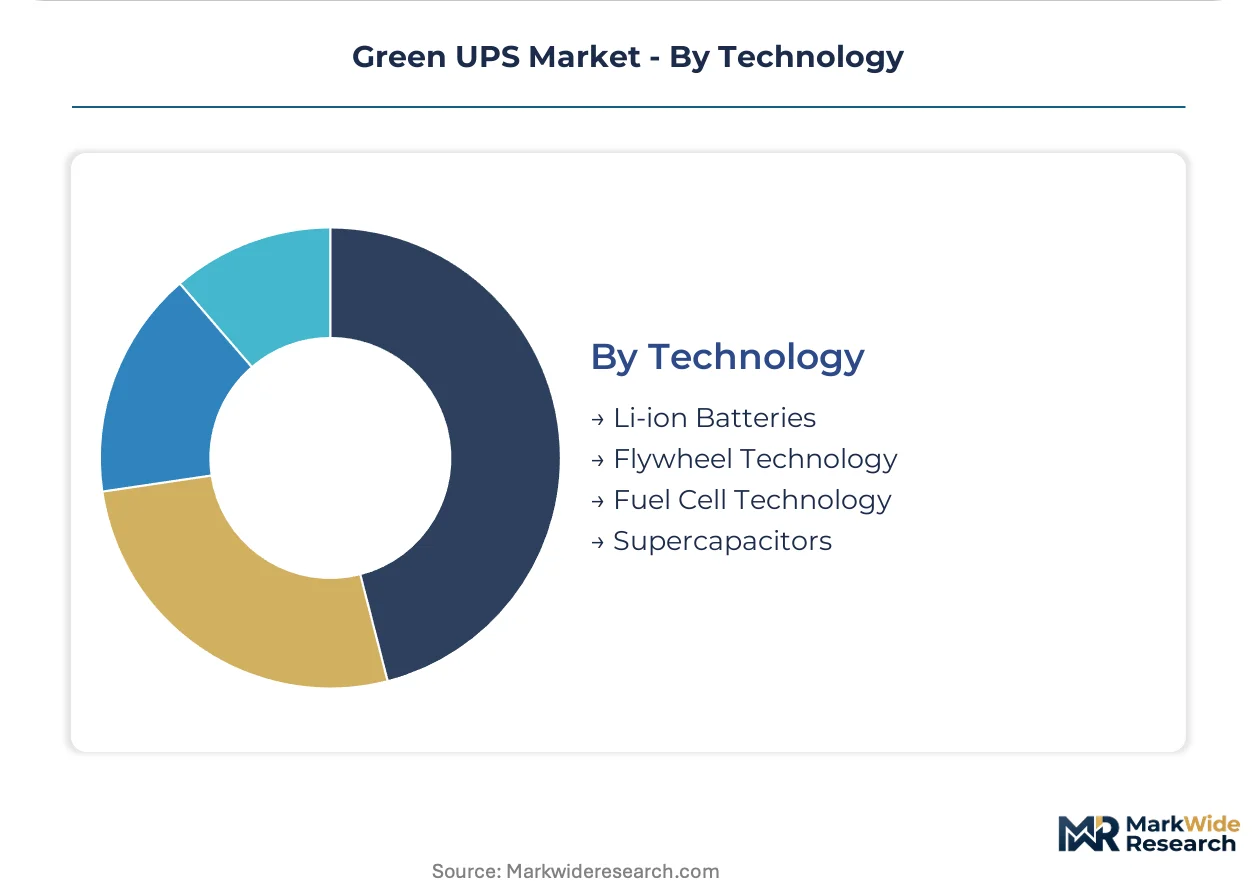
Technology:
Maturity curves separate segments: lithium-ion benefits from electric vehicle supply chain scale, while flywheel and fuel cell alternatives occupy specialized reliability or runtime niches.
- Li-ion Batteries:Lithium iron phosphate chemistry delivers 5,000+ cycle life and 40-60% footprint reduction versus lead-acid. Cycle life and energy density advantages unlock rooftop and constrained-facility deployments previously uneconomical for UPS installation.
- Flywheel Technology:Kinetic energy storage provides 15-30 second ride-through for voltage sag protection. Applications concentrate in semiconductor fabrication and broadcast transmission where battery maintenance is unacceptable.
- Fuel Cell Technology:Hydrogen or methanol-powered extended runtime for critical infrastructure. High capital cost and fuel logistics limit deployment to military, emergency services, and remote telecommunications.
- Supercapacitors:Ultra-high cycle life and instantaneous response for power quality conditioning. Energy density constraints restrict use to short-duration applications alongside battery systems.
By deployment volume, lithium-ion batteries dominate. By technology maturation pace, supercapacitor integration is advancing most rapidly in hybrid storage architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys green UPS systems primarily within industrial microgrid integrations, while the United States concentrates demand in hyperscale data center efficiency mandates and China channels procurement through state-backed carbon neutrality construction programs.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth drive modular UPS procurement with 98% efficiency specifications. EPA Energy Star 2.0 standby loss thresholds below 2% force replacement of legacy valve-regulated lead-acid installations. Silicon carbide rectifier deployments concentrate in Phoenix and Ashburn data center clusters where cooling load reduction dominates total facility economics.
Germany
Industrial microgrid projects in North Rhine-Westphalia and Bavaria anchor medium-voltage UPS integration for manufacturing resilience. EU Ecodesign Directive sub-1% standby loss mandates lock engineering resources toward Q3 2025 certification deadlines. Frankfurt and Berlin data center construction prioritizes lithium-ion systems with rooftop deployment feasibility.
China
State-backed data center construction in the Yangtze River Delta and Pearl River Delta channels procurement through MIIT-administered GB efficiency standards. Dual carbon goals accelerate solar-hybrid UPS adoption in Beijing-Tianjin-Hebei corridors. Shenzhen and Shanghai hyperscale facilities specify modular architectures matching phased buildout schedules.
India
PLI scheme incentives for electronics manufacturing attract localized assembly operations in Maharashtra and Karnataka. State-level data center policies in Mumbai and Bangalore create first-mover positioning for modular system suppliers. Grid modernization investments intersect with commercial retail expansion in Delhi-NCR for standardized distributor-channel units.
Japan
Semiconductor fabrication facilities in Kanto and Kyushu demand flywheel-based ride-through systems where battery maintenance is operationally unacceptable. METI efficiency guidelines shape procurement specifications for Tokyo and Osaka data center operators. Earthquake resilience requirements drive premium-tier UPS adoption in critical infrastructure clusters.
Green UPS Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capability concentration in power electronics and battery management determining competitive position. The market structure rewards firms with captive semiconductor sourcing and in-house energy management software stacks. Three archetypes dominate: vertically integrated energy management conglomerates, specialized power electronics manufacturers, and scale-driven modular system fabricators. Competitive moves center on fifteen-year power-as-a-service contracting structures and silicon carbide supply chain partnerships.
Within the integrated conglomerate tier, Schneider Electric and Eaton Corporation exemplify firms controlling project economics across large-scale deployments through bundled hardware-installation-maintenance offerings. Huawei Technologies occupies a position among scale-driven modular specialists, though its geographic reach faces regulatory constraints in several Western markets. These three anchors represent the capability spectrum from vertically integrated energy management to manufacturing-scale modular production.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group Corp |
| Huawei Technologies |
| ABB Ltd |
| Delta Electronics, Inc. |
| Emerson Electric Co. |
| Siemens AG |
| Cyber Power Systems Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MOSFET substitution for silicon IGBTs in rectifier stages simultaneously relocates procurement gravity toward East Asian foundries and compresses margin structures for systems lacking captive semiconductor access. This substitution dynamic concentrates pricing power with integrated manufacturers while forcing component-assemblers toward cost-plus contracting.
Pricing Analysis
Long-term power-as-a-service contracts now dominate enterprise data center procurement, bundling fifteen-year hardware-installation-maintenance into single operational expenditure lines. Price differentiation rests on silicon carbide component sourcing and EPA Energy Star 2.0 certification tier, with premium efficiency ratings commanding substantial uplifts. Pricing pressure stems from lithium carbonate volatility compressing battery pack margins. Hyperscale operators exhibit lowest price sensitivity due to total facility economics focus, while retail distributors face acute margin compression.
Supply Chain Analysis
Inbound logistics costs for silicon carbide wafers and lithium iron phosphate cells concentrate exposure on Shanghai-to-Long Beach and Busan-to-Rotterdam trade lanes, where container availability constraints extend procurement cycles. Manufacturing gravity centers on China, South Korea, and Taiwan for power semiconductors, with Australia and Chile anchoring lithium raw material flows. Supply chain risk manifests in single-source vulnerability for insulated-gate bipolar transistor fabrication. Distribution runs through direct manufacturer relationships for hyperscale deployments and regional electrical distributors for standardized units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent scarcity constrains competitive expansion, with wide-bandgap semiconductor design expertise concentrated in automotive and aerospace sectors creating recruitment friction for UPS manufacturers seeking efficiency leadership.
For Market Incumbents: Shield margin structures through backward integration into silicon carbide wafer sourcing and captive battery management system production. Lock engineering resources toward EU Ecodesign Q3 2025 certification deadlines before competitors capture medium-voltage integration slots in German industrial microgrids. Prioritize fifteen-year service contract structures that transfer operational risk and create switching costs. For New Entrants and Emerging Players: Differentiate on second-life battery integration and circular economy service models targeting fleet operators with decommissioned electric vehicle cells. Penetrate India's Maharashtra and Karnataka data center construction pipeline through PLI scheme-aligned localized assembly. Pursue edge computing micro-facilities for 5G infrastructure where sub-10kVA modular demand remains underpenetrated. For Investors and Strategic Acquirers: EPA Energy Star 2.0 and EU Ecodesign Directive implementation reshapes the acquisition landscape toward firms with certified silicon carbide topologies and in-house energy management software stacks. Five-to-ten year viability favors vertically integrated energy management conglomerates over component-assemblers. Target acquisition archetype: mid-cap specialists with captive semiconductor relationships and established service infrastructure. Monitor lithium carbonate price trajectories as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Secures wafer allocation from Taiwan and South Korea foundries for 98% efficiency rectifier production. |
| Power-as-a-Service Contracting Structure | Bundles hardware, installation, and fifteen-year maintenance into operational expenditure lines for financial services CIOs. |
| Second-Life Battery Integration Program | Converges decommissioned electric vehicle cells with stationary power applications for differentiated ESG positioning. |
| PLI-Aligned Localized Assembly | Captures Maharashtra and Karnataka data center incentives through India-based manufacturing footprint. |
| EU Ecodesign Certification Investment | Locks engineering resources toward sub-1% standby loss compliance for medium-voltage industrial microgrid access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA power infrastructure data, EPA Energy Star certification databases, EU Ecodesign Directive filings, and MIIT GB standard documentation. Interviews with data center procurement directors, power electronics engineering leads, lithium-ion battery supply managers, and electrical distributor channel heads inform demand-side validation. Top-down market sizing triangulates against bottom-up unit economics across modular, standalone, and rack-mounted product configurations.
Segmentation dimensions modeled include product architecture, energy source integration, end-user vertical, and battery chemistry technology across the projection horizon. CAGRs derive from unit shipment trajectories and average selling price evolution by efficiency tier. Forecast inputs incorporate hyperscale facility construction pipelines, grid modernization investment schedules, and regional carbon neutrality commitment timelines.
Forecasts assume regulatory continuity in EPA Energy Star 2.0, EU Ecodesign Directive, and MIIT GB efficiency regimes; material policy shifts would require re-modeling. Lithium carbonate price volatility, semiconductor fabrication capacity constraints, and fire safety code fragmentation represent specific risk factors that could revise trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Electric Power Sports Market
Power
Italy Power EPC Market
Power
Denmark Power Market
Power
Smart Power Market
Power
Power Purchase Agreement Market
Power
Residential Micro Inverter Market
Power
Europe Submarine Power Cables Market
Power
Europe Frequency Converter Market
Power
Distributed Buoyancy Modules Market
Power
Canada Thermal Power Market
Power
Rotating Phase Converter Market
Power
Europe Microturbine Market
Power
North America Micro CHP Market
Power
Italy Power Market
Power
North America Power Market
Power
United States Power Market