
 Vietnam Taxi Market | 2026-2036
Vietnam Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Taxi Market Analytics
Decree 10/2020 on automobile transport business is consolidating the cost-of-entry calculus for new fleet operators. Xanh SM leverages VinFast's captive electric vehicle supply to anchor its zero-emission positioning. Mai Linh Corporation sustains brand recognition through its nationwide radio-dispatch infrastructure. Grab competes on multimodal integration, bundling taxi rides with food delivery and financial services.
A taxi constitutes a licensed for-hire passenger vehicle operating on either street-hail or pre-booked dispatch, typically governed by metered or algorithmic fare calculation with seating capacity up to nine passengers. The Vietnam taxi market serves urban mobility, airport transfers, and inter-district commuting across a fleet transitioning from internal combustion to electric powertrains. Ride-hailing platforms dominate transaction volume by embedding payment, routing, and driver-rating systems within a single mobile interface. Electric Vehicle adoption within the Vehicle Type dimension is accelerating fastest where Xanh SM's charging network density supports daily fleet utilization. Traditional Taxi operations retain structural relevance in provincial cities where smartphone penetration lags and cash payment persists.
Vietnam's Ministry of Transport enforces Decree 10/2020 compliance for ride-hailing platforms, while the country's national standards body sets vehicle safety and emissions benchmarks that filter fleet procurement decisions. The central bank's e-payment directives are accelerating Mobile Payment penetration, reducing cash-handling friction for drivers and platforms. Stakeholders must monitor regulatory clarity on cross-provincial operating licenses and charging infrastructure standards as electrification timelines tighten.
Market Dynamics
Decree 10/2020's electrification mandates are compressing fleet replacement timelines while charging infrastructure gaps create operational chokepoints for operators transitioning from internal combustion engines.
Growth Catalysts
- Smartphone penetration:Ho Chi Minh City and Hanoi commuters now complete ride bookings through mobile interfaces, eliminating street-hail friction and expanding addressable demand for app-based dispatch services.
- Decree 10/2020 compliance:Vietnam's Ministry of Transport vehicle-type mandates are pulling forward electric fleet procurement, creating regulatory certainty that attracts infrastructure investment.
- Inter-district commuting patterns:Urban sprawl between Hanoi core districts and satellite industrial zones is lengthening average trip distances, improving per-ride economics for metered and algorithmic fare models.
Market Restraints
- Charging infrastructure concentration:Fast-charging stations cluster in central business districts, limiting electric vehicle utilization rates for airport and provincial route operators.
- Driver certification bottlenecks:Vietnam's Ministry of Transport commercial license requirements create 45-60 day onboarding delays, constraining fleet expansion velocity during demand spikes.
- Dual-fleet maintenance complexity:Operators managing parallel internal combustion and electric powertrains face doubled spare parts inventory and technician training costs through the transition window.
Strategic Opportunities
- Provincial city penetration:Da Nang, Can Tho, and Hai Phong exhibit smartphone adoption curves comparable to Hanoi five years prior, presenting first-mover positioning for platform operators.
- Airport transfer premiumization:Noi Bai and Tan Son Nhat international terminals generate predictable high-value trip volumes underserved by fixed-route bus alternatives.
- Mobile payment integration:State Bank of Vietnam e-wallet directives are collapsing cash-handling overhead, enabling real-time driver earnings distribution and reduced platform reconciliation costs.
Industry Challenges
- Electric vehicle technician scarcity:High-voltage battery diagnostics and motor controller repair skills remain concentrated at manufacturer-authorized centers, extending vehicle downtime for independent operators.
- Cross-provincial licensing fragmentation:Operating permits issued by provincial transport departments create administrative burden for fleets serving inter-city routes, requiring duplicate documentation and compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Taxi Market |
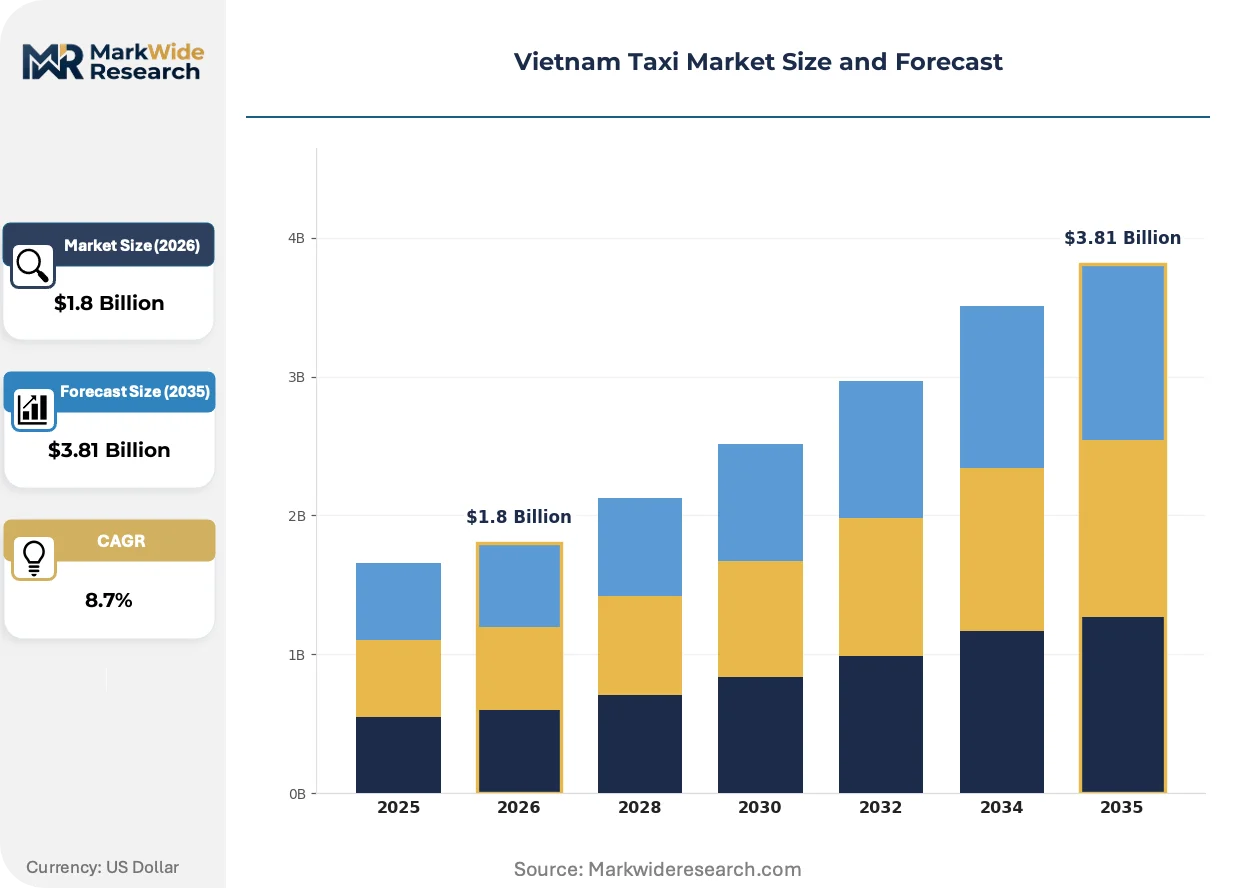
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Traditional Taxi, Luxury Taxi, Shared Ride Vehicle Type: Sedan, SUV, Van, Electric Vehicle Customer Segment: Business Travelers, Tourists, Locals, Commuters Payment Method: Cash, Credit Card, Mobile Payment, Prepaid |
| Companies Covered | Mai Linh Corporation, G7 Taxi, Xanh SM (Green & Smart Mobility), VinaTaxi, Taxi Group, Grab, Vinasun Corporation, inDrive, Be Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Taxi Market Evolving Landscape
Algorithmic dispatch systems are displacing traditional radio-dispatch infrastructure across Vietnamese metropolitan corridors, while payment digitization and fleet electrification converge to reshape operator economics and consumer experience expectations.
Vehicle-to-grid integration technology is expanding into taxi fleet operations, enabling bidirectional power flow between electric vehicle batteries and grid infrastructure during idle periods. Xanh SM and VinFast-affiliated operators are piloting this capability at depot charging clusters, converting parked fleet assets into distributed energy storage. The structural consequence is expanding into ancillary revenue streams that offset vehicle capital costs through grid stabilization service payments.
Decree 10/2020's progressive electrification quotas are mandating specific percentages of zero-emission vehicles in licensed commercial fleets by weight class. Vietnam's Ministry of Transport enforcement mechanisms include permit renewal conditions tied to documented vehicle procurement timelines. App-based platforms with captive charging infrastructure are responding fastest, while traditional radio-dispatch operators face compressed compliance windows that favor asset-light partnership models over owned-fleet strategies.
Commuters are consolidating transportation spending onto super-app platforms that bundle taxi dispatch with food delivery, digital payments, and micro-lending. This behavioral shift concentrates transaction data that improves demand prediction algorithms and dynamic pricing precision. The pattern is most visible among Hanoi and Ho Chi Minh City office workers under age 35, where single-interface convenience overrides loyalty to standalone taxi services.
Vietnam Taxi Market Segmentation
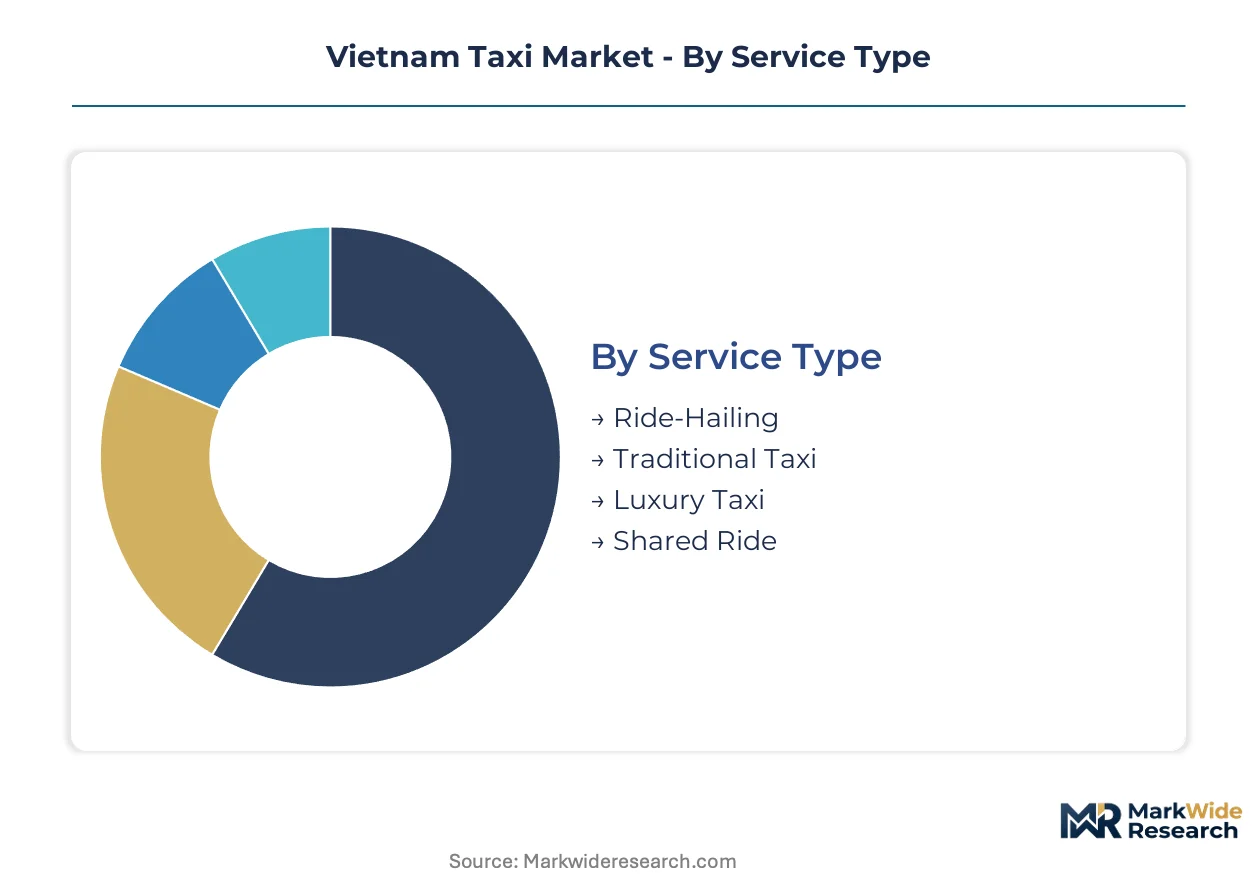
Segmentation reveals how Decree 10/2020 compliance costs and smartphone penetration diverge across service models and customer types. Fleet operators must align vehicle procurement and payment infrastructure with distinct mobility behaviors in Ho Chi Minh City and Hanoi corridors.
Service Type:
Cost tier separates occasional users from daily dependents, with subscription and per-ride economics driving platform design choices.
- Ride-Hailing:Algorithmic dispatch platforms coordinate driver supply with real-time demand through mobile interfaces. Smartphone penetration in Hanoi and Ho Chi Minh City concentrates transaction volume here, though driver certification bottlenecks constrain fleet expansion velocity during peak periods.
- Traditional Taxi:Radio-dispatch or street-hail operations maintain metered fare structures with licensed commercial drivers. Provincial cities and airport queues sustain this segment where cash payment persists and smartphone adoption lags metropolitan curves.
- Luxury Taxi:Premium vehicle classes with fixed-rate airport transfers and corporate account billing.
- Shared Ride:Route-optimized pooling algorithms matching multiple passengers toward common destinations.
Volume sits with Ride-Hailing; growth tilts toward Shared Ride.
Vehicle Type:
Application context determines powertrain suitability, with duty cycles and charging access dictating procurement priorities.
- Electric Vehicle:Battery-electric powertrains with zero tailpipe emissions and regenerative braking systems. Xanh SM's depot charging clusters in Ho Chi Minh City support daily utilization rates, though technician scarcity at independent garages extends repair downtime.
- Sedan:Four-door passenger vehicles with 1.5-2.0L displacement or equivalent electric range. Inter-district commuting between Hanoi core and satellite industrial zones concentrates demand here, with per-ride economics favoring fuel efficiency over capacity.
- SUV:Higher-clearance vehicles with expanded cargo and passenger capacity.
- Van:Multi-passenger configurations serving airport groups and corporate shuttles.
Procurement concentrates on Sedan; fleet transition accelerates fastest for Electric Vehicle.
Customer Segment:
Margin profile varies sharply by trip predictability and price sensitivity, from expense-account elasticity to commuter routine.
- Business Travelers:Corporate-account passengers prioritizing reliability and receipt documentation over fare minimization. Noi Bai and Tan Son Nhat international terminals generate predictable high-value trip volumes with fixed-route bus alternatives underserving this demand.
- Commuters:Daily work-trip passengers with routine origin-destination patterns and high platform loyalty potential. Ho Chi Minh City office workers under age 35 consolidate transportation spending onto super-app bundles, collapsing standalone taxi loyalty.
- Tourists:Short-stay visitors with infrequent, destination-uncertain mobility needs.
- Locals:Non-commuting residents with intermittent, price-elastic trip demand.
Revenue per trip peaks with Business Travelers; transaction frequency concentrates with Commuters.
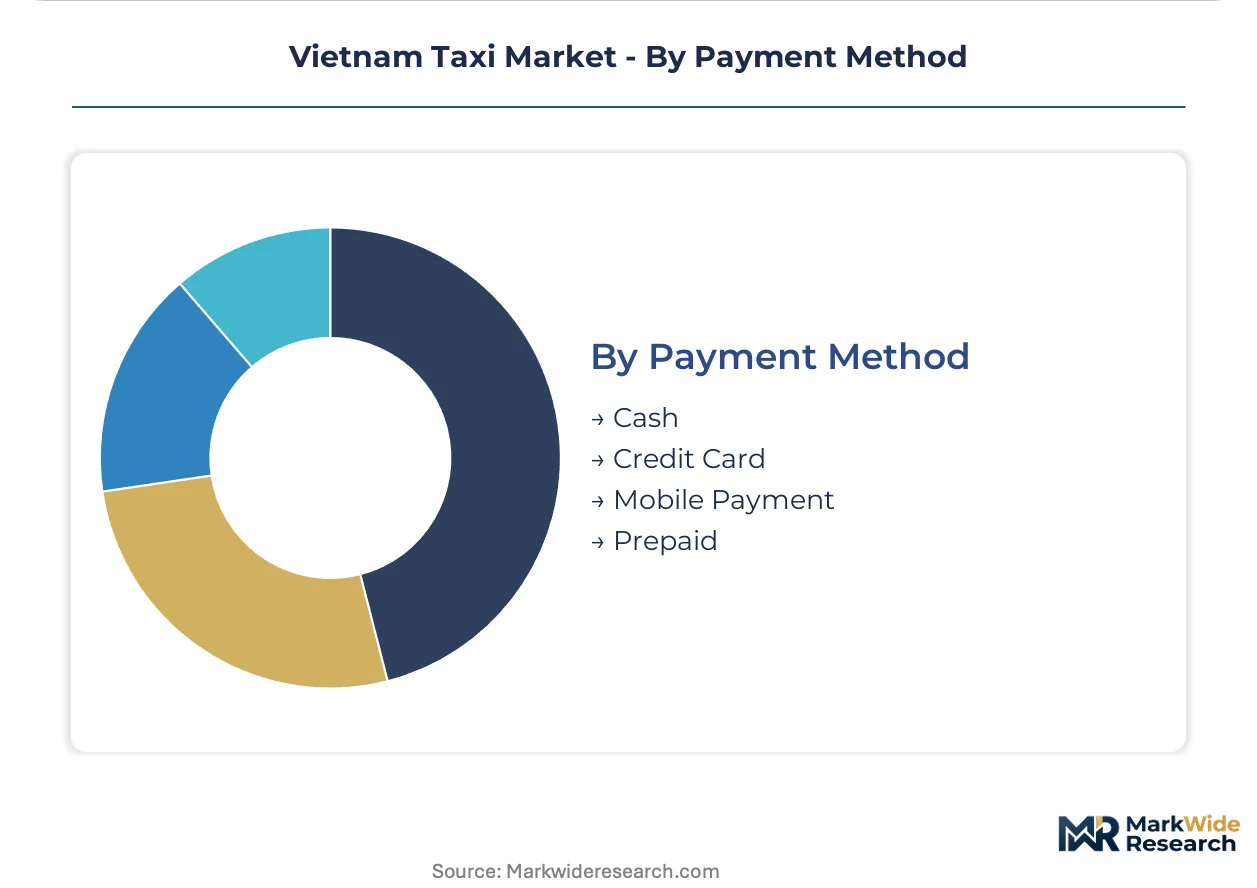
Payment Method:
Maturity of financial infrastructure determines driver onboarding friction and platform reconciliation overhead.
- Mobile Payment:E-wallet and in-app transactions with real-time settlement through State Bank of Vietnam-licensed providers. Regulatory directives collapsing cash-handling overhead enable instantaneous driver earnings distribution and reduced platform reconciliation costs.
- Cash:Physical currency exchange at trip conclusion with driver float requirements. Traditional radio-dispatch operators and provincial markets retain this method where smartphone penetration lags and unbanked populations persist.
- Credit Card:Card-present or tokenized transactions with interchange fee structures.
- Prepaid:Account-based stored value with corporate or individual top-up mechanisms.
Transaction volume concentrates in Mobile Payment; Cash retention is strongest in provincial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thu Duc City special economic zone in Ho Chi Minh City concentrates ride-hailing platform headquarters and charging infrastructure investment. Vietnam's Ministry of Transport coordinates provincial licensing frameworks that shape fleet deployment patterns across northern, central, and southern corridors.
Northern Vietnam
Hanoi commuters generate dense trip volumes between core districts and satellite industrial zones in Bac Ninh and Hung Yen. Decree 10/2020 electrification quotas apply uniformly across northern provinces, pulling forward electric vehicle procurement timelines. Noi Bai International Airport anchors premium airport transfer demand, with fixed-rate corporate contracts sustaining higher per-ride economics than street-hail operations.
Central Vietnam
Da Nang's tourism-driven mobility demand concentrates around airport transfers and coastal resort corridors during peak seasons. The city's Department of Transport issues commercial operating permits with vehicle-type restrictions that favor four-door sedans over multi-passenger vans. Hoi An heritage district proximity creates short-haul trip clustering where electric two-wheelers compete for tourist wallet share.
Southern Vietnam
Ho Chi Minh City accounts for the dominant share of national transaction volume, with District 1 and District 7 office corridors generating predictable commuter flows. Tan Son Nhat International Terminal's expansion is compressing pickup wait times for app-based platforms. Thu Duc City's integrated planning mandates are embedding charging stations within new commercial developments, supporting Xanh SM's depot-based fleet model.
Mekong Delta
Can Tho represents the most penetrated provincial market, with smartphone adoption curves comparable to Hanoi five years prior. The city's Transport Department enforces Decree 10/2020 compliance with simplified documentation for inter-district routes connecting to Ho Chi Minh City. Floating market tourism generates intermittent demand spikes that strain driver supply during harvest seasons.
Vietnam Taxi Market Competitive Landscape
Vietnamese operators anchor the domestic tier; regional platform specialists from Singapore and Indonesia hold cross-border technology integration. Market structure tilts toward platform consolidation where super-app bundling concentrates user data and transaction frequency. Three archetypes dominate: state-affiliated radio-dispatch incumbents, venture-backed algorithmic platforms, and captive electric fleet operators. Capacity expansion and strategic charging infrastructure partnerships constitute the dominant competitive moves.
Within the captive electric fleet tier, Xanh SM exemplifies vertical integration with manufacturer-affiliated charging networks. Among platform specialists, Grab and Be Group occupy positions where multimodal bundling collapses standalone taxi loyalty. Mai Linh Corporation represents the radio-dispatch archetype sustaining brand recognition through nationwide infrastructure.
| Leading Market Players |
|---|
| Mai Linh Corporation |
| G7 Taxi |
| Xanh SM (Green & Smart Mobility) |
| VinaTaxi |
| Taxi Group |
| Grab |
| Vinasun Corporation |
| inDrive |
| Be Group |
| Others |
Value Network & Pricing Analysis
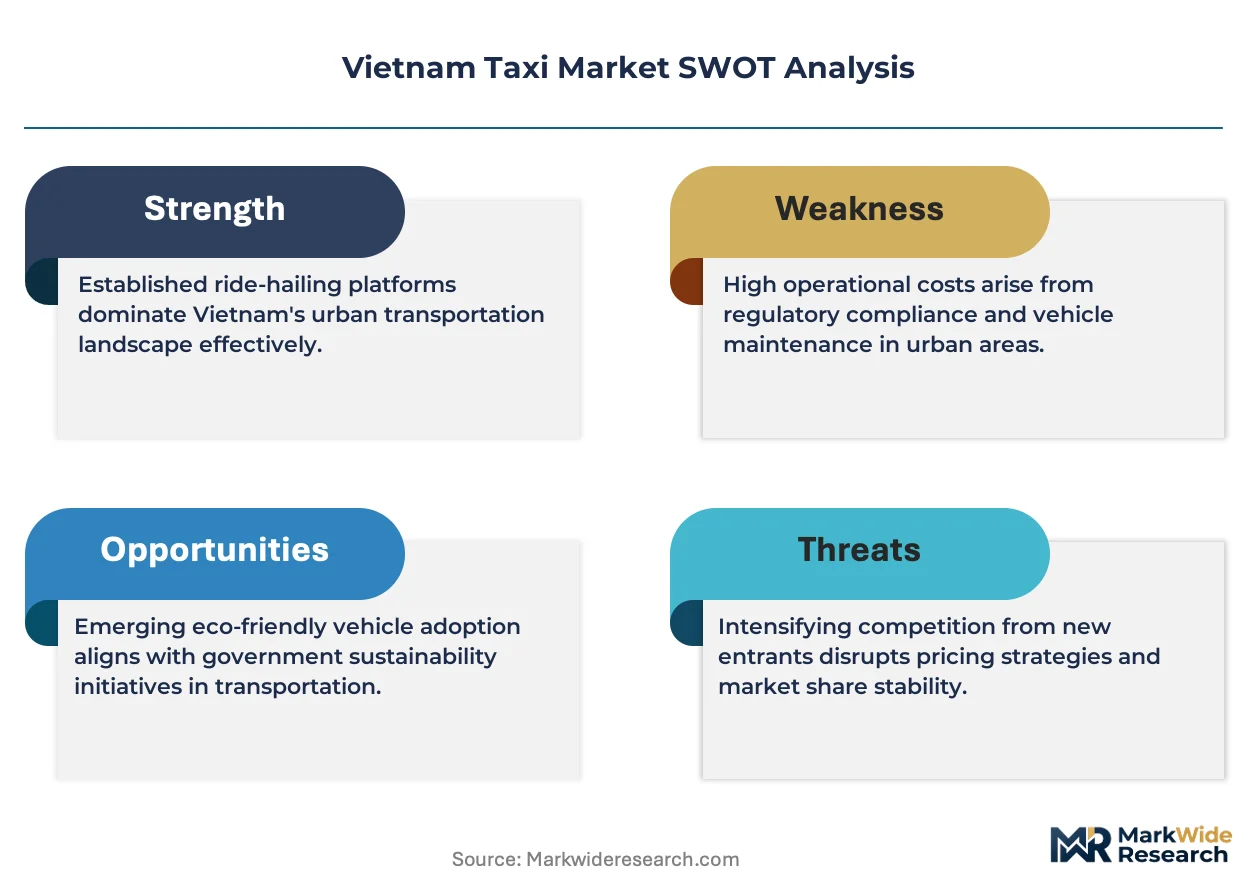
Captive charging infrastructure separates fleet operators into tiered cost positions that manifest in both fare structures and vehicle procurement pathways. Vietnam's Decree 10/2020 electrification mandates compress replacement timelines for operators lacking vertical integration with domestic EV manufacturers, while platform specialists with algorithmic pricing engines extract premium yields from business traveler segments.
Pricing Analysis
Short-lead-time dispatch commands fare premiums through dynamic surge algorithms during peak congestion windows, while spot-market street-hail operations trade at discounts to pre-booked rates. Ride-hailing platforms deploy three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by vehicle class and guaranteed arrival windows. Cost compression in traditional radio-dispatch tiers intensifies because app-based platforms capture commuter routine demand. Tourist and occasional-use segments exhibit highest price elasticity, while corporate account travelers show lowest sensitivity.
Supply Chain Analysis
Decree 10/2020 vehicle-type certification gates fleet procurement to manufacturers meeting Vietnam's national standards body safety and emissions benchmarks. Battery-electric powertrains draw from China, South Korea, and domestic VinFast production lines, with lithium-ion cell supply resting on nickel and cobalt feedstock concentration in Indonesia and the DRC. Single-source vulnerability sits with proprietary charging connector standards that lock operators into manufacturer-affiliated infrastructure networks. Distribution runs through manufacturer-direct fleet sales and platform-operated depot procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's taxi market functions as a cost-of-compliance arena where Decree 10/2020's electrification quotas erect regulatory moats favoring capitalized incumbents with captive charging infrastructure over asset-light entrants.
For Market Incumbents: Cement market position through exclusive charging infrastructure partnerships in Thu Duc City and Hanoi satellite industrial zones. Fleet operators should deepen backward integration into battery leasing arrangements to offset vehicle capital intensity. The threat of super-app bundling by Grab and Be Group demands defensive multimodal service expansion beyond standalone taxi dispatch.
For New Entrants and Emerging Players: Provincial transport departments in Can Tho and Hai Phong represent the most penetrable channel partner type for licensing facilitation and local market intelligence. White-space targets concentrate in airport transfer premiumization at expanding Tan Son Nhat terminals and inter-district commuter contracts linking Hanoi core to Bac Ninh manufacturing zones. A fleet-light driver aggregation model minimizes capital deployment while capturing algorithmic dispatch economics.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated EV fleet operators given State Bank of Vietnam e-payment directives collapsing cash-handling friction and improving platform unit economics. Long-term viability favors archetypes with charging infrastructure ownership and manufacturer supply agreements that compress per-kilometer operating costs. The signal to watch as inflection indicator is cross-provincial operating license harmonization that would unlock inter-city route scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Xanh SM's depot network in Ho Chi Minh City anchors utilization rates for electric fleet transition. |
| Super-App Platform Integration | Grab's bundling of taxi dispatch with food delivery collapses standalone service loyalty among commuters. |
| Provincial License Expansion | Da Nang and Can Tho transport department relationships enable first-mover positioning in emerging corridors. |
| Corporate Account Billing System | Mai Linh's nationwide radio-dispatch infrastructure sustains premium yield from business traveler segments. |
| Vehicle-to-Grid Pilot Program | VinFast-affiliated operators convert parked fleet assets into grid stabilization revenue streams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet operations directors, transport department licensing officers, platform algorithm engineers, and charging infrastructure planners combined with bottom-up and top-down triangulation. Secondary validation drew from Vietnam Ministry of Transport Decree 10/2020 implementation guidelines, State Bank of Vietnam e-payment directives, VinFast production disclosures, and Ho Chi Minh City Department of Transport permit databases.
Data-stream reconciliation across vehicle registration flows, app-based transaction volumes, and charging station deployment records shaped the analytical framework. Segmentation dimensions modeled include service type, vehicle powertrain architecture, customer segment, and payment method across the projection horizon. CAGRs derived from trend extrapolation of electrification compliance timelines and smartphone penetration curves, with fleet utilization rates and driver certification velocity as industry-specific forecast inputs.
Caveats apply where charging infrastructure buildout delays or cross-provincial licensing fragmentation could materially shift the outlook. Forecasts reflect assumptions on regulatory enforcement consistency and EV technician training pipeline expansion. A model refresh is warranted upon material change in Decree 10/2020 amendment schedules or national standards body charging protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Bulk Transportation Services Market
Transportation Services
ASEAN Car Rental Market
Transportation Services
Full-Service Carrier Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Poland Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Waste Collection Vehicle Market
Transportation Services
Cross Docking Services Market
Transportation Services
Australia Taxi Market
Transportation Services
Refuse Truck Market
Transportation Services
United Arab Emirates Car Rental Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Water Truck Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Indonesia Car Rental Market