
 Commercial Ice Equipment and Supplies Market | 2026-2036
Commercial Ice Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Ice Equipment and Supplies Market Outlook
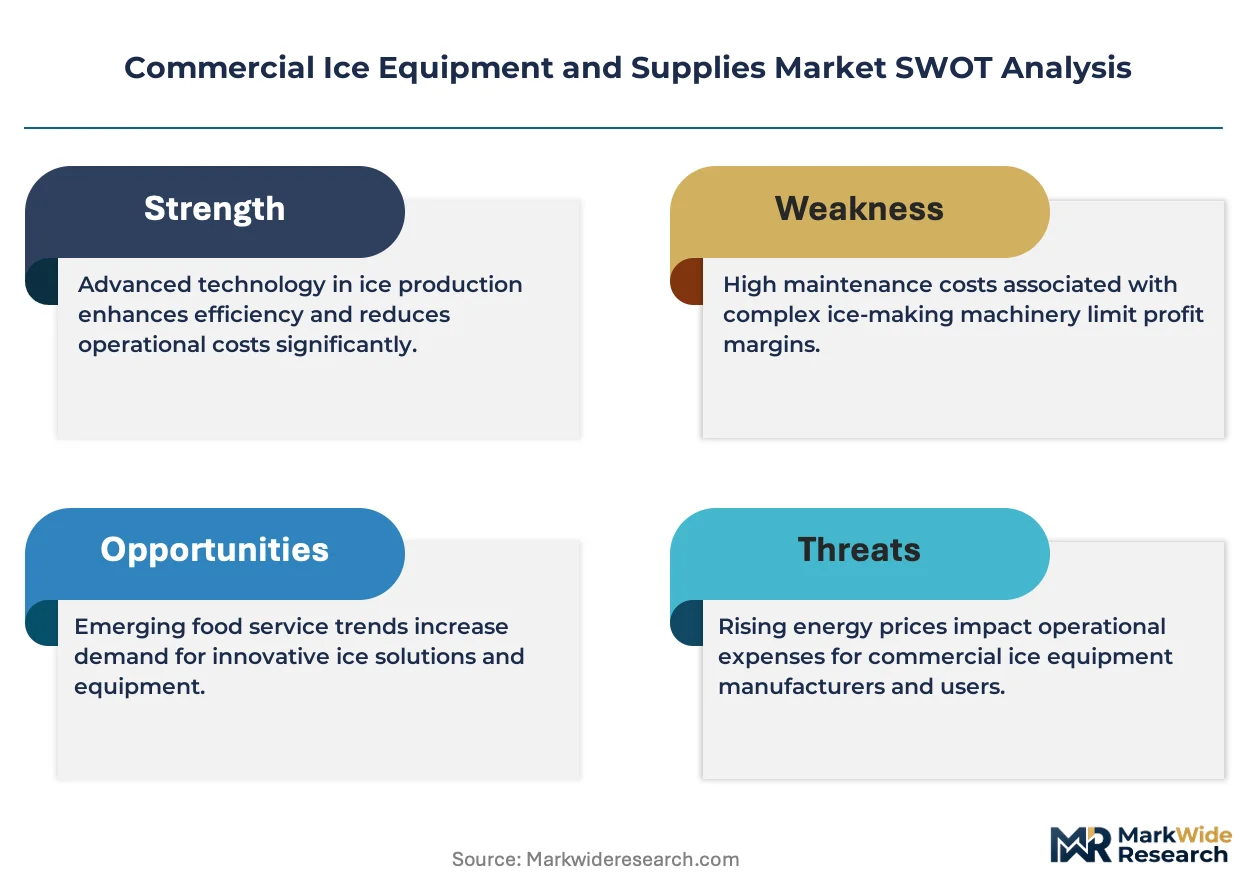
Energy Star certification tiers is bifurcating the competitive landscape as operators face rising utility costs and sustainability mandates. Hoshizaki Corporation leverages its scale in remote condensing systems to serve high-volume hotel chains. Manitowoc Ice anchors its position through extensive distributor networks across North American food service corridors. Scotsman Ice Systems differentiates via specialized nugget and flake ice architectures for healthcare and retail applications.
Commercial ice equipment encompasses electrically powered refrigeration systems that produce, store, and dispense ice for business use, typically operating with air-cooled or water-cooled condensers rated between 100 and 2,000 pounds of daily ice production. These systems employ hermetic or semi-hermetic compressors with R290 or R404A refrigerant circuits, delivering cube, flake, nugget, or gourmet ice forms for consumption, preservation, or process cooling. Ice makers command the dominant revenue position within product type segmentation due to replacement cycles and technological refresh rates. Food service application channels carry the deepest margin pools among end-use categories, while healthcare and industrial segments present faster growth trajectories driven by hygiene protocols and process cooling requirements.
The US Department of Energy and EPA Energy Star program shape equipment efficiency baselines and refrigerant transition timelines, directly influencing manufacturer R&D allocation and product qualification costs. NSF International standards govern sanitary design for food zone materials and cleanability, creating compliance barriers for imported equipment. Stakeholders must monitor refrigerant phase-down schedules and regional utility rebate structures to align procurement timing with total cost of ownership optimization.
Market Dynamics
The US Department of Energy's tightened commercial refrigeration efficiency standards are compressing replacement cycles and forcing compressor architecture redesigns across the installed base, creating a structural refresh imperative that favors R290 refrigerant adoption and variable-speed drive integration.
Growth Catalysts
- Sun Belt food service density:Metropolitan expansion across Phoenix, Houston, and Miami is elevating ice production capacity requirements per establishment. Climate stress on equipment accelerates replacement frequency in high-humidity zones.
- EPA Energy Star tier advancement:Utility rebate structures tied to certification tiers are pulling operators toward higher-efficiency models. Rebate qualification thresholds now exclude legacy fixed-speed compressor designs.
- Healthcare hygiene protocols:Joint Commission accreditation standards for ice as a food contact surface are mandating NSF-certified sanitary designs. Hospitals and long-term care facilities are retiring non-compliant legacy machines.
Market Restraints
- Copper and aluminum input volatility:Condenser coil materials face commodity price swings that compress manufacturer margin structures. Sheet metal fabrication costs transmit directly to end-user pricing.
- Refrigerant phase-down friction:The EPA's AIM Act hydrofluorocarbon restrictions are stranding R404A service infrastructure. Technicians require retraining for flammable refrigerant handling.
- Water-cooled system permitting:Municipal water use restrictions in drought-prone jurisdictions are blocking new installations. Air-cooled alternatives carry efficiency penalties in high-ambient conditions.
Strategic Opportunities
- Remote condensing architecture:Heat-rejection separation enables kitchen layout flexibility and noise mitigation. Hotel chains are specifying these configurations for guest-floor installations.
- Industrial process cooling:Concrete batching and chemical manufacturing require flake ice for temperature control. This segment escapes food service seasonality.
- Utility demand-response integration:Grid-interactive ice storage systems qualify for peak-shaving incentives. California and Texas utilities are piloting controlled load programs.
Industry Challenges
- Refrigerant technician certification gaps:Section 608 technician credentials do not cover R290 handling protocols. Training program scaling lags equipment rollout timelines.
- NSF/ANSI 12 cleanability validation:Food zone material approval cycles extend product development timelines. Third-party testing capacity constraints create queue bottlenecks.
- Legacy control system integration:Building management system protocols vary across hospitality property portfolios. Proprietary communication standards complicate centralized monitoring deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Ice Equipment and Supplies Market |
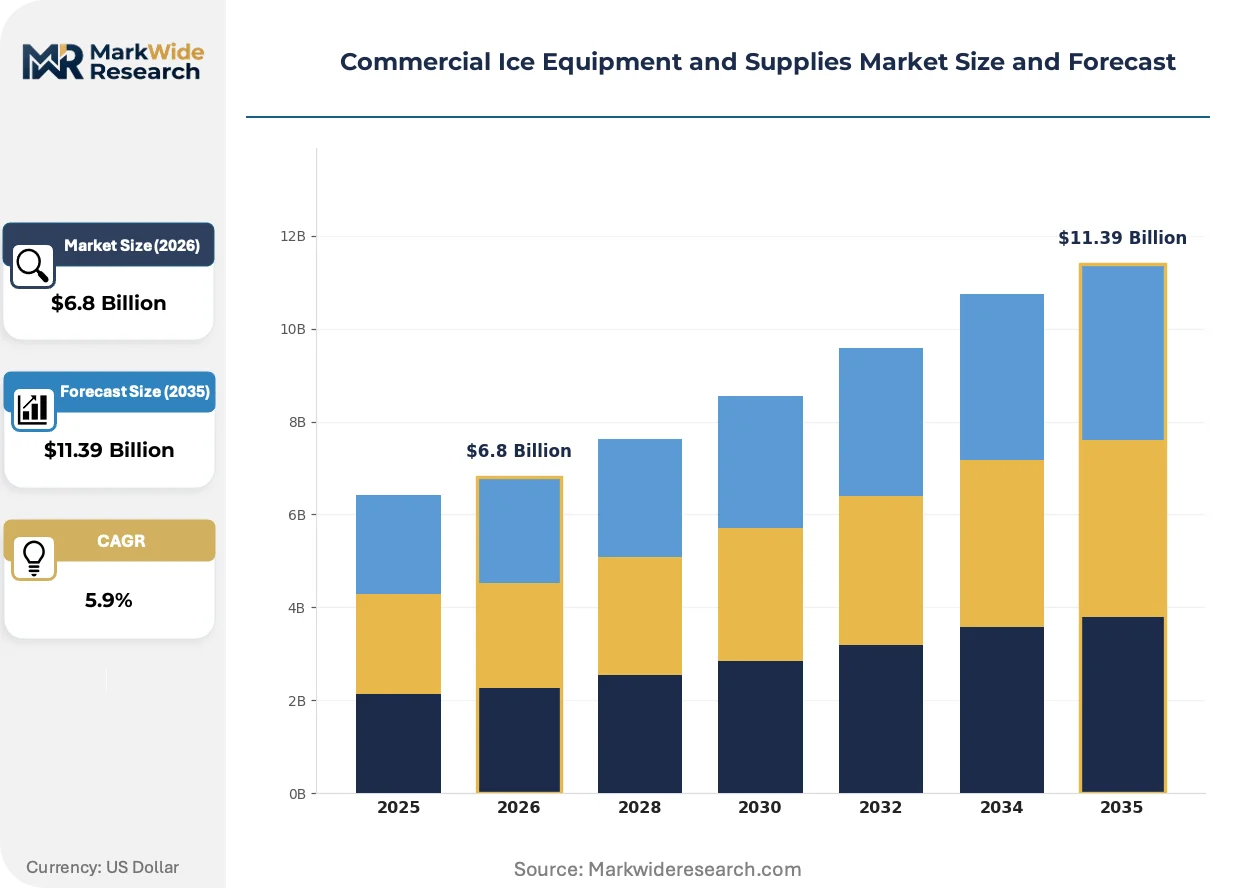
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Makers, Ice Storage Bins, Ice Dispensers, Ice Bags End User: Restaurants, Hotels, Cafes, Convenience Stores Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers Application: Food Service, Retail, Healthcare, Industrial |
| Companies Covered | Hoshizaki Corporation, Manitowoc Ice, Scotsman Ice Systems, Ice-O-Matic, Follett Corporation, Cornelius, Inc., Kold-Draft, Beverage-Air, Brema Ice Makers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Ice Equipment and Supplies Market Strategic Shifts
Equipment intelligence and refrigerant chemistry are converging to redefine performance baselines, with connected diagnostics and natural working fluids displacing legacy architectures across the replacement cycle.
R290 propane refrigerant circuits are supplanting hydrofluorocarbon systems in sub-500-pound daily production categories. Quick-service restaurant chains are specifying these units for new construction to preempt regulatory obsolescence. The transition is compressing R404A equipment residual values and accelerating write-downs in the secondary market.
The EPA's SNAP program restrictions on high-global-warming-potential refrigerants are mandating chemistry transitions by 2026. Equipment manufacturers are redesigning charge limits and safety controls to satisfy UL 60335-2-89 ignition risk standards. Food service operators in California face the earliest compliance deadlines under state-level HFC prohibitions.
Cloud-connected ice machine telemetry is transforming service models from reactive dispatch to predictive intervention. Multi-site operators are unbundling maintenance from equipment purchase, favoring subscription-based uptime guarantees. This pattern concentrates in national hotel and casino portfolios where downtime costs exceed service premiums.
Commercial Ice Equipment and Supplies Market Segmentation
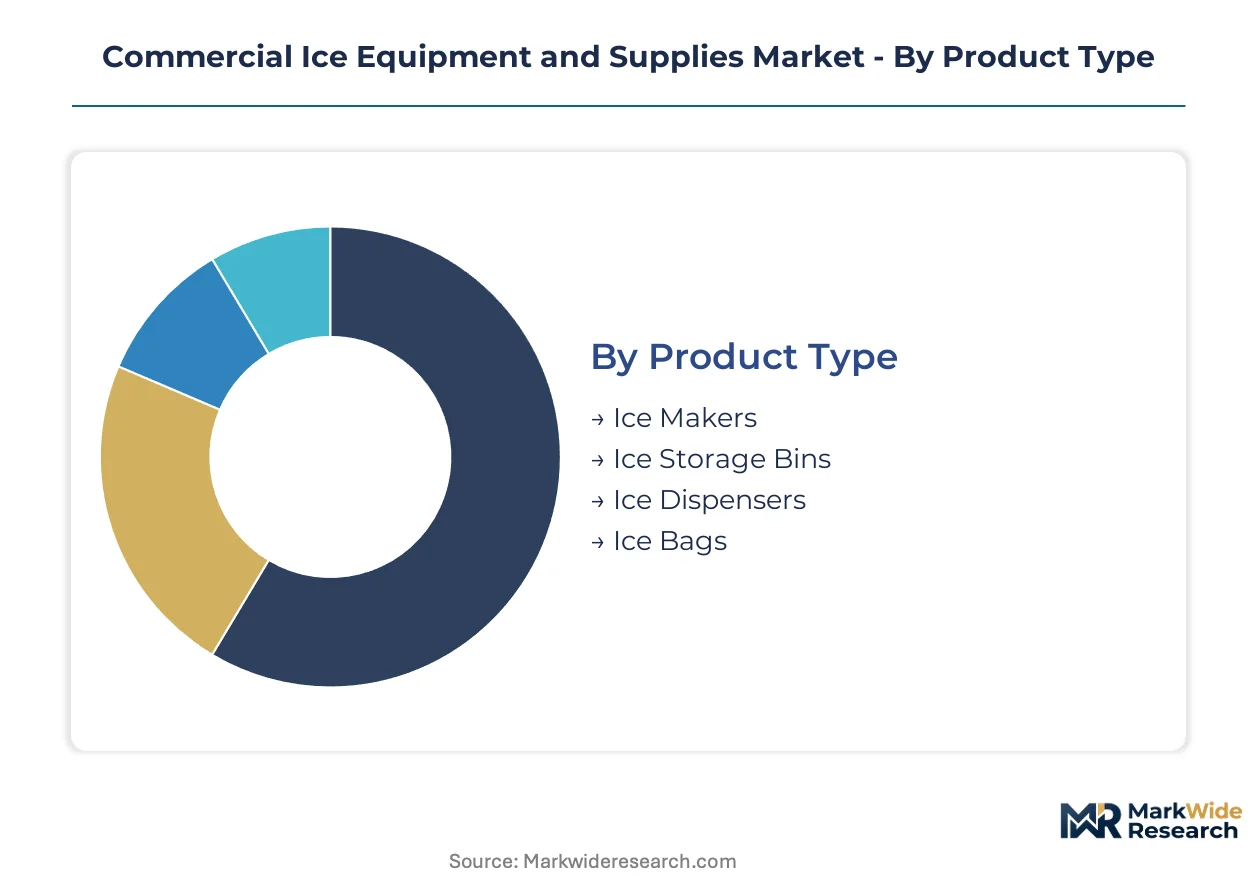
Segmentation in commercial ice equipment reveals distinct procurement patterns across equipment categories and operational contexts. Operators prioritize different performance attributes based on application intensity, regulatory exposure, and total cost of ownership calculations. Understanding these divides enables targeted product positioning and channel strategy calibration.
Product Type:
Domestic manufacturing concentrates on ice makers and storage bins, while dispensers and bags show heavier import dependence from Asian assembly operations.
- Ice Makers:Refrigeration systems with hermetic compressors producing 100-2,000 pounds daily, configured as modular heads or self-contained units. Full-service restaurants in Phoenix, Houston, and Miami drive replacement demand as climate stress accelerates equipment degradation in high-humidity zones.
- Ice Storage Bins:Insulated polyethylene or stainless steel containers maintaining sub-freezing temperatures for inventory buffering. Hotel chains specify remote condensing architectures with separated heat rejection for guest-floor installations where noise mitigation commands premium pricing.
- Ice Dispensers:Countertop or floor-standing units with automated dispensing mechanisms for self-service environments.
- Ice Bags:Pre-packaged ice for retail resale and emergency backup supply in convenience stores.
Ice makers hold the largest share; momentum sits with ice storage bins as remote condensing configurations gain specification in hospitality new construction.
End User:
Volume concentration varies sharply by operational scale, with multi-unit chains driving standardization while independent operators prioritize flexibility over efficiency tiers.
- Restaurants:Full-service establishments with elevated beverage programs requiring gourmet and nugget ice varieties. EPA Energy Star rebate thresholds now exclude fixed-speed compressor designs, forcing equipment refreshes across the installed base.
- Hotels:Properties with centralized ice service for guest floors and banquet operations. National portfolios are unbundling maintenance from equipment purchase, favoring subscription-based uptime guarantees where downtime costs exceed service premiums.
- Cafes:Limited-service beverage-focused operations with compact footprint constraints.
- Convenience Stores:Retail fuel and grocery hybrids requiring bagged ice merchandising and fountain drink support.
Restaurants dominate volume; hotels are expanding most quickly as guest-experience investments elevate ice quality specifications.
Distribution Channel:
Channel selection correlates directly with customer technical sophistication and service integration requirements.
- Direct Sales:Manufacturer-led specification for national accounts with customized configurations. Chains leverage volume aggregation to secure extended warranty terms and preventive maintenance bundling.
- Distributors:Regional networks providing local inventory, installation coordination, and emergency service response. Food service corridors across the Sun Belt depend on these relationships for same-day replacement availability.
- Online Retail:E-commerce platforms serving small independent operators with standard configurations and transparent pricing.
- Wholesalers:Bulk procurement intermediaries supplying contractors and facility maintenance departments.
Distributors retain the deepest penetration; direct sales are climbing the fastest as national hospitality portfolios consolidate procurement authority.
Application:
Margin structures diverge dramatically between regulated food contact applications and industrial process cooling with less stringent material certification.
- Food Service:Restaurants, bars, and catering operations requiring NSF-certified sanitary designs for ice as a consumable product. Joint Commission accreditation standards are mandating equipment upgrades across healthcare-adjacent food operations.
- Healthcare:Hospitals and long-term care facilities with strict hygiene protocols for immunocompromised patient populations. R290 refrigerant adoption is accelerating in this segment to preempt regulatory obsolescence under EPA SNAP restrictions.
- Retail:Grocery and convenience operations with dual requirements for customer-facing dispensing and back-of-house production.
- Industrial:Concrete batching, chemical manufacturing, and process cooling applications utilizing flake ice for temperature control. This segment escapes food service seasonality with year-round demand tied to construction and manufacturing cycles.
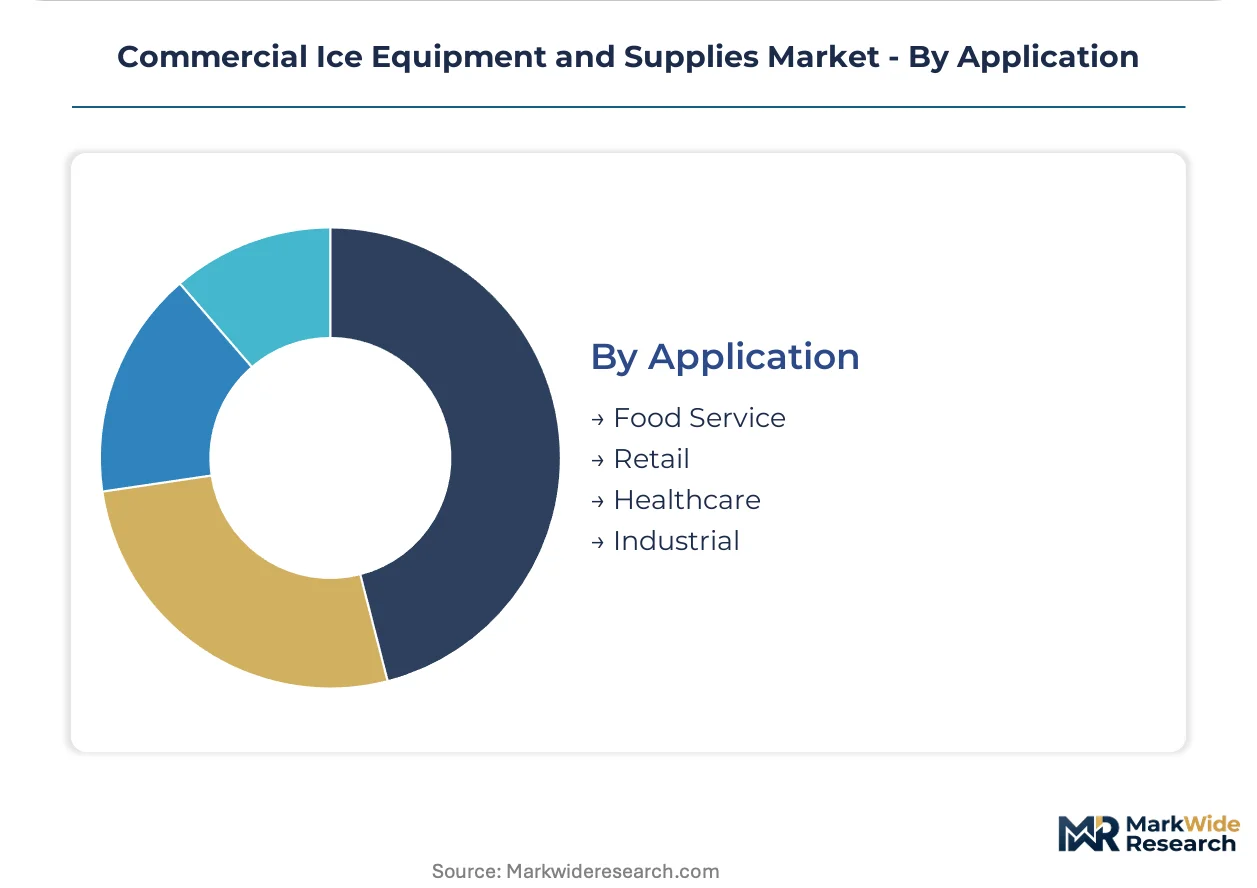
Food service commands the greatest revenue concentration; healthcare shows the steepest expansion trajectory as hygiene protocol enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for ice storage bins and dispensers runs counter to domestic manufacturing strength in modular ice makers, creating trade flow asymmetries that shape procurement timelines and warranty support structures across major consuming economies.
United States
Sun Belt metropolitan expansion in Phoenix, Houston, and Miami elevates replacement frequency as climate stress degrades condenser performance in high-humidity zones. The EPA's Energy Star tier advancement excludes fixed-speed compressor designs from utility rebate qualification, accelerating equipment refresh cycles. Food service corridors across Texas and Florida depend on regional distributor networks for same-day replacement availability.
Germany
Industrial process cooling applications in concrete batching and chemical manufacturing sustain year-round demand outside food service seasonality. The EU F-Gas Regulation mandates hydrofluorocarbon phase-down schedules that compress R404A equipment residual values. Manufacturing clusters in North Rhine-Westphalia and Bavaria anchor specification authority for remote condensing architectures in hospitality new construction.
Japan
Compact footprint constraints in dense urban food service operations favor self-contained units over modular configurations. METI efficiency standards and JIS certification requirements create compliance barriers for imported equipment. The Kanto and Kansai metropolitan areas concentrate demand from hotel chains and convenience store networks with standardized procurement protocols.
United Kingdom
Healthcare hygiene protocol enforcement through NHS England procurement frameworks mandates NSF-certified sanitary designs for hospital and long-term care facilities. The country's national pharmaceutical regulator aligns equipment specifications with Joint Commission accreditation standards. London and Southeast England concentrate food service density with elevated beverage program investments driving gourmet ice specifications.
Australia
Municipal water use restrictions in drought-prone jurisdictions block new water-cooled installations, forcing efficiency penalties from air-cooled alternatives in high-ambient conditions. The country's national food safety regulator enforces strict material certification for food zone components. New South Wales and Victoria concentrate demand from hospitality portfolios unbundling maintenance from equipment purchase.
Commercial Ice Equipment and Supplies Market Competitive Environment
Concentration sits with diversified refrigeration conglomerates and specialized ice equipment fabricators, with mid-scale regional players occupying niche application segments. The competitive terrain stratifies across three tiers: multinational systems houses with captive distribution, dedicated ice equipment specialists with application-specific architectures, and contract manufacturers serving private-label channels. Consolidation pressure operates through distributor network acquisitions and refrigerant transition-driven technology licensing arrangements.
Within the multinational systems tier, Hoshizaki Corporation and Manitowoc Ice occupy positions defined by scale advantages in compressor sourcing and specification authority with national hospitality portfolios. Scotsman Ice Systems exemplifies the specialization archetype, anchoring its competitive position through differentiated ice form architectures. These three companies represent the dominant competitive anchors, with regional fabricators and import-dependent assemblers contesting price-sensitive segments below the premium tier.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| Manitowoc Ice |
| Scotsman Ice Systems |
| Ice-O-Matic |
| Follett Corporation |
| Cornelius, Inc. |
| Kold-Draft |
| Beverage-Air |
| Brema Ice Makers |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for hermetic compressors from Asian assembly operations concentrate pricing power with manufacturers holding captive component inventories, while spot-market aluminum volatility feeds directly into condenser coil quotations and distributor markup structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the premium tier, with NSF certification grade and volume scale driving price differentiation between modular ice maker configurations. Cost compression in standard-tier equipment intensifies because copper and aluminum input volatility transmits directly to end-user pricing. National hospitality portfolios exhibit lowest price sensitivity due to unbundled subscription service models, while independent restaurant operators show acute sensitivity to upfront capital outlays.
Supply Chain Analysis
China and Mexico anchor condenser coil fabrication and sheet metal stamping operations serving North American demand. Compressor sourcing draws from Japan and South Korea for hermetic and semi-hermetic units. Single-source vulnerability concentrates in R290 refrigerant charge limits and safety control assemblies under UL 60335-2-89 validation. Distribution runs through regional distributor networks providing same-day replacement availability across Sun Belt food service corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in remote condensing architectures as hotel chains unbundle maintenance from equipment purchase and elevate ice quality specifications for guest-experience investments.
For Market Incumbents: Fortify distributor network control across Phoenix, Houston, and Miami food service corridors to preempt same-day replacement competition. Secure captive compressor sourcing through backward integration into hermetic assembly operations. R290 refrigerant transition timelines from the EPA's SNAP program threaten stranded R404A service infrastructure investments. For New Entrants and Emerging Players: Anchor in industrial process cooling applications for concrete batching and chemical manufacturing, where flake ice demand escapes food service seasonality and NSF certification barriers are minimal. Pursue utility demand-response integration pilots with California and Texas grid operators as a specification wedge against established hospitality-focused incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory transition play because refrigerant phase-down schedules and Energy Star tier advancement create forced replacement cycles independent of economic cyclicality. Target mid-scale regional fabricators with R290-ready product platforms and established technician training programs. Monitor EPA Section 608 credential expansion for flammable refrigerant handling as an inflection signal for service model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | R290 propane circuits preempt EPA SNAP obsolescence deadlines and qualify for California HFC prohibition compliance. |
| Cloud-Connected Telemetry Deployment | Predictive maintenance subscriptions transform service economics for national hotel and casino portfolios. |
| Remote Condensing Architecture Expansion | Heat-rejection separation commands premium pricing in guest-floor installations where noise mitigation dominates specifications. |
| Utility Demand-Response Integration | Grid-interactive ice storage qualifies for peak-shaving incentives with California and Texas pilot programs. |
| NSF/ANSI 12 Certification Acceleration | Sanitary design validation opens healthcare procurement channels under Joint Commission accreditation standards. |
Study Parameters
Cross-validation between distributor inventory audits and EPA Energy Star qualification databases anchors the qualitative findings. Primary interviews with food service equipment procurement directors, regional distributor operations managers, commercial refrigeration service technicians, and hospitality facility engineering heads combined with secondary validation from DOE efficiency standard filings, NSF certification registries, and utility rebate program disclosures. Bottom-up equipment shipment tracking and top-down food service establishment census triangulation establish market sizing boundaries.
Sensitivity analysis across refrigerant transition timelines, commodity input price bands, and rebate qualification thresholds tests forecast robustness. Segmentation dimensions span product type, end-user operational scale, application hygiene requirements, and geographic climate stress zones. CAGRs derive from replacement cycle compression analysis and regulatory mandate acceleration effects. Compressor technology refresh rates and municipal water use restriction patterns constitute industry-specific forecast inputs across the projection horizon.
Material uncertainties — copper and aluminum commodity swings, EPA refrigerant phase-down enforcement variance, Section 608 technician certification scaling delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding Energy Star tier advancement adherence and Sun Belt metropolitan expansion continuity. Recalibration cycles align with material shifts in DOE efficiency standard revisions and regional utility rebate structure modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Retail Cooler Market