
 Commercial Cookers Market | 2026-2036
Commercial Cookers Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Cookers Market Outlook
The US Department of Energy's Appliance and Equipment Standards Program is pivoting commercial kitchen procurement toward higher-efficiency gas and electric cookers. Middleby Corporation leverages its vertical manufacturing footprint to sustain price competitiveness across convection and fryer lines. Ali Group anchors its position through deep specialization in modular cooktop systems for European hospitality chains.
Commercial cookers encompass heavy-duty food preparation equipment engineered for continuous operation in professional kitchens, typically constructed from stainless steel with burner outputs exceeding 30,000 BTU and temperature tolerances up to 500°F for sustained batch cooking. These units serve restaurants, institutional cafeterias, and catering operations requiring throughput volumes unattainable by residential appliances. Convection ovens and induction cooktops capture expanding margin pools as operators prioritize energy recovery and precise thermal control. Gas-fired equipment retains volume dominance in legacy kitchen installations where infrastructure retrofit costs constrain fuel switching.
The US Department of Energy and EPA ENERGY STAR program shape product certification pathways, while the EU Ecodesign Directive and F-Gas Regulation restrict refrigerant-dependent cooking technologies in European installations. India's Bureau of Energy Efficiency mandates labeling standards for commercial cooking appliances under its Standards and Labeling Program. Stakeholders must monitor evolving efficiency benchmarks across multiple jurisdictions to align R&D pipelines with compliance timelines.
Market Dynamics
Energy efficiency mandates from the US Department of Energy are compressing product lifecycles and forcing simultaneous R&D across gas and electric platforms. This dual-track compliance burden favors manufacturers with captive component production and modular architecture expertise.
Growth Catalysts
- Urban hospitality corridor expansion:India's metropolitan restaurant clusters are scaling centralized kitchen infrastructure to serve delivery-native brands. This concentrates demand for high-throughput batch cooking equipment.
- EPA ENERGY STAR certification pathways:The program's tightened commercial kitchen equipment standards create procurement preference hierarchies in US institutional foodservice contracts.
- Induction technology maturation:Precise thermal control capabilities are penetrating quick-service formats previously dominated by gas-fired equipment, opening retrofit cycles in Southeast Asian chains.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet price swings compress margin visibility for equipment fabricators operating on project-based contracts.
- Legacy gas infrastructure lock-in:Kitchen ventilation and utility hookup sunk costs in North American and European installed bases slow fuel-switching economics.
- F-Gas Regulation phase-down schedules:The EU's refrigerant-dependent cooking technology restrictions limit product line extensions for combination oven-steamer platforms in European markets.
Strategic Opportunities
- Cloud kitchen infrastructure buildouts:Delivery-optimized ghost kitchen operators in India's tier-2 cities require compact, high-density cooking suites with rapid deployment timelines.
- EU Ecodesign Directive compliance services:Technical documentation and testing support for modular cooktop systems represent adjacent revenue streams for specialized engineering consultancies.
- IoT-enabled predictive maintenance:Sensor-integrated convection ovens allow remote diagnostics and parts forecasting, shifting revenue from equipment sales to subscription service models.
Industry Challenges
- Certification timeline compression:Simultaneous DOE efficiency rulemakings and state-level building code updates force parallel testing workflows that strain laboratory capacity.
- Integration complexity with building management systems:New equipment must communicate with existing HVAC and fire suppression infrastructure without proprietary protocol fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Cookers Market |
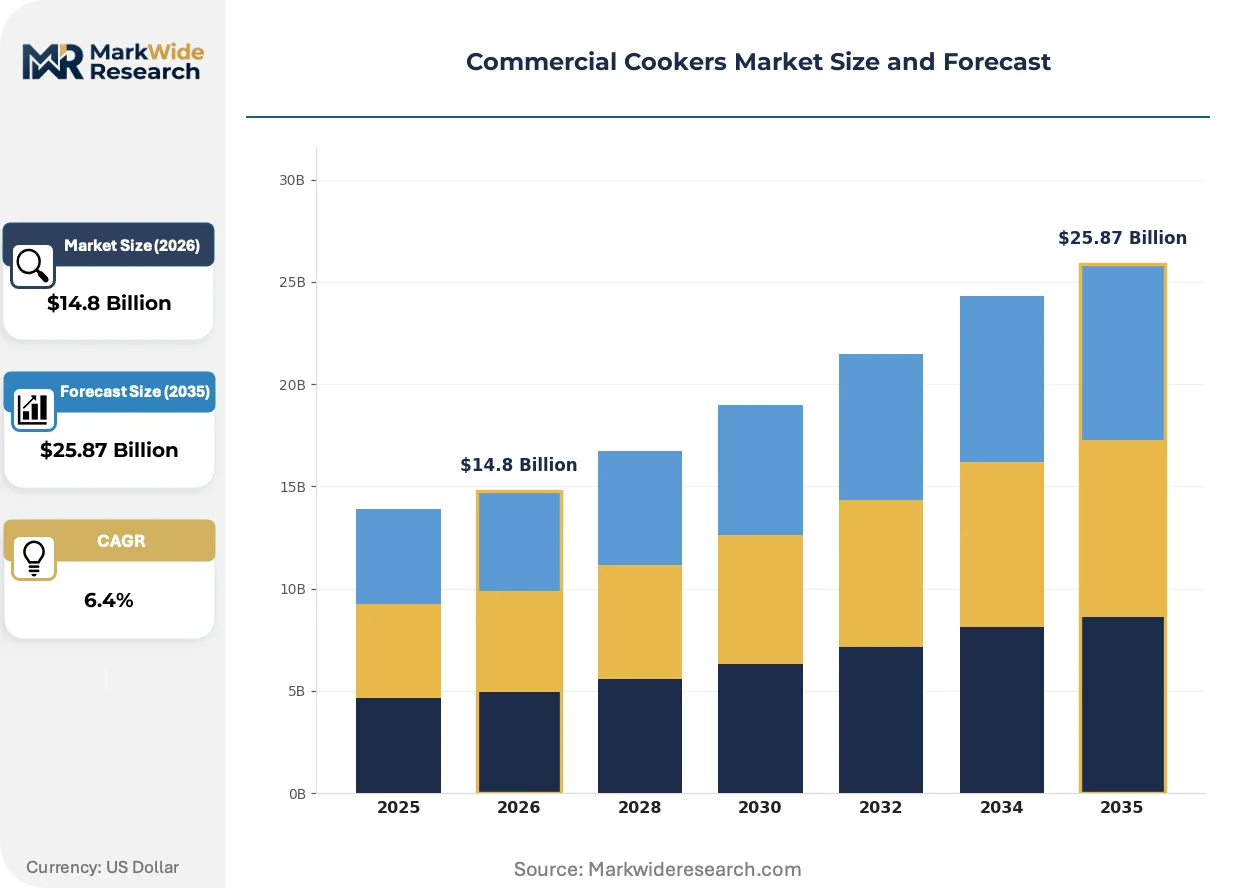
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Ovens, Fryers, Griddles, Cooktops End User: Restaurants, Cafeterias, Catering Services, Hotels Fuel Type: Gas, Electric, Induction, Wood Size: Small, Medium, Large, Extra Large |
| Companies Covered | Middleby Corporation, Ali Group, Electrolux, Duke Manufacturing, Alto-Shaam, Welbilt, Rational AG, Vulcan, Imperial Commercial Cooking Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Cookers Market Strategic Shifts
Equipment architecture is converging around platform-based modularity that allows field-upgradable burner configurations and control systems. This shift reduces total cost of ownership while complicating manufacturer service revenue models.
Combination oven technology is unifying convection, steam, and sous-vide functions within single footprint units. Hotel and institutional cafeteria operators are standardizing on these platforms to compress kitchen square footage requirements. The structural consequence is collapsing demand for standalone single-function equipment and compressing vendor count per kitchen.
The EU F-Gas Regulation's stepped refrigerant phase-down is forcing accelerated R&D on alternative thermal systems for combination cooking platforms. Equipment manufacturers serving European hospitality chains must redesign core product architectures ahead of 2030 restriction milestones. This regulatory pressure is most acute in Germany and France, where national building codes amplify compliance stringency.
Buying committees in US institutional foodservice are unbundling equipment procurement from installation and maintenance contracts. Third-party facility management firms are capturing specification influence previously held by equipment distributors. This disintermediation is most visible in K-12 and healthcare cafeteria segments, where centralized procurement offices now mandate multi-vendor service interoperability.
Commercial Cookers Market Segmentation
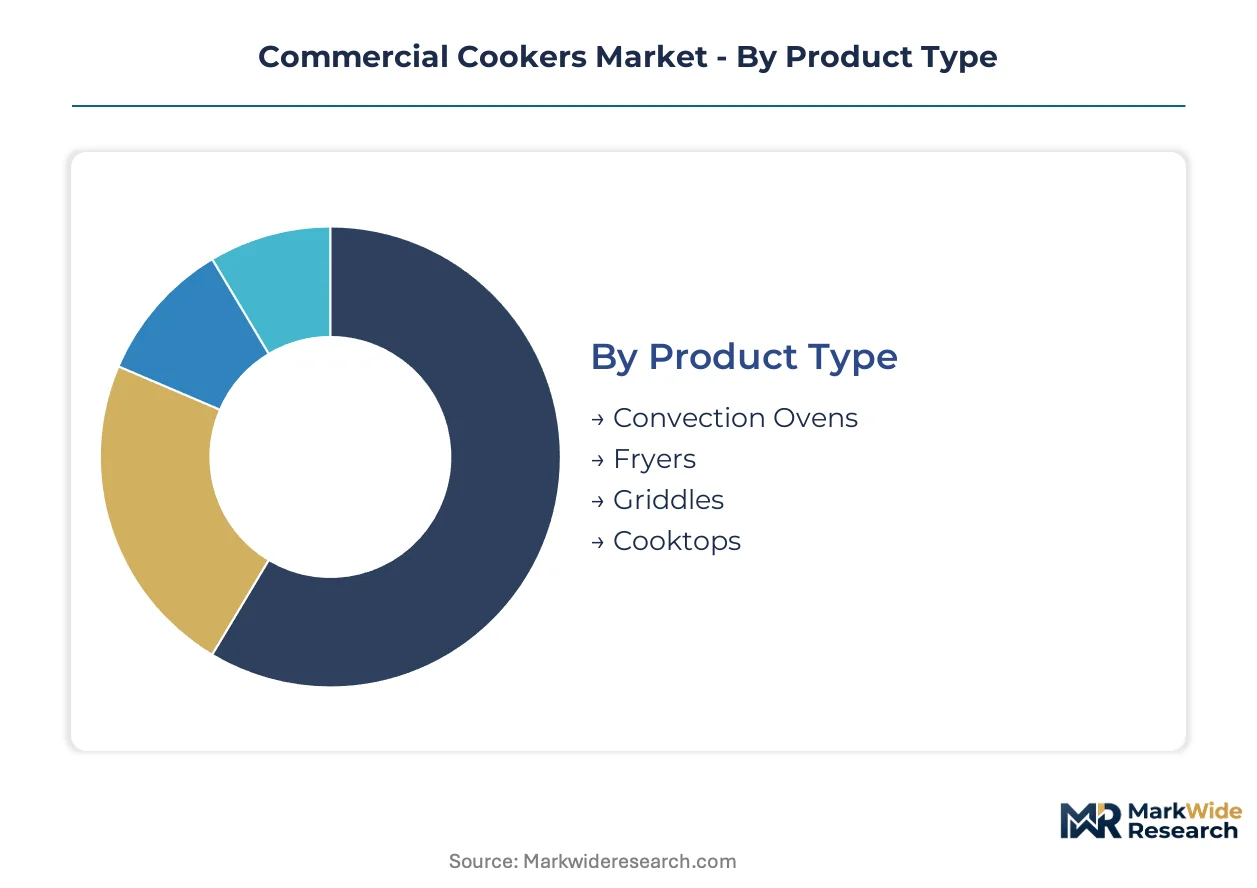
Commercial cooker procurement patterns diverge sharply between standalone replacement cycles and integrated kitchen buildouts. Equipment specification depends on whether operators prioritize fuel flexibility, throughput density, or compliance with tightening efficiency standards.
Product Type:
Standalone units dominate replacement demand in legacy kitchens, while modular platforms anchor new construction and ghost kitchen deployments.
- Convection Ovens:These units circulate heated air through fan systems to reduce cooking times and improve temperature uniformity across multiple racks. Demand concentrates in US institutional cafeterias where EPA ENERGY STAR certification now gates contract eligibility, forcing operators to retire aging thermal models.
- Fryers:Vat systems maintain oil temperatures between 300-375°F for continuous batch production of fried products. Quick-service chains across Southeast Asia are expanding fryer counts in centralized production kitchens to serve delivery-native brands with standardized output.
- Griddles:Flat-top thermal surfaces provide direct-contact cooking for breakfast proteins and sandwich assembly. Operators favor griddles for menu flexibility in compact footprints.
- Cooktops:Open-burner and sealed-element configurations offer modular burner arrangement for sauté and sauce preparation. European hospitality chains specify cooktops with field-upgradable control systems to extend equipment lifecycles.
Convection ovens lead volumes today; induction-ready cooktops are gaining share fastest.
End User:
Customer procurement sophistication varies from centralized national contracts to single-location owner-operator decisions.
- Restaurants:Full-service and limited-service operators balance equipment first cost against ventilation and utility infrastructure requirements. India's urban hospitality corridors are scaling centralized kitchen infrastructure for delivery-native brands, concentrating batch-cooking equipment demand in Mumbai, Delhi, and Bangalore clusters.
- Cafeterias:Institutional feeding operations in K-12, healthcare, and corporate settings prioritize multi-vendor service interoperability and remote diagnostics capability. US buying committees are unbundling equipment procurement from installation contracts, shifting specification influence to third-party facility managers.
- Catering Services:Mobile and event-based operators require equipment with rapid deployment and breakdown characteristics for temporary kitchen installations.
- Hotels:Full-service properties standardize on combination platforms to compress kitchen square footage, collapsing demand for standalone single-function units.
Restaurants anchor current installed base; cloud kitchen operators are expanding most quickly.
Fuel Type:
Energy infrastructure lock-in and regulatory pressure create divergent technology adoption curves across geographies.
- Gas:Burner systems exceeding 30,000 BTU retain dominance in North American legacy installations where ventilation and utility hookup sunk costs constrain fuel-switching economics. The US Department of Energy's tightening efficiency minimums are compressing product lifecycles for non-compliant models.
- Electric:Resistance-element systems serve markets with lower gas penetration and operators seeking simplified ventilation requirements. European installations face accelerating phase-down schedules under the EU F-Gas Regulation, redirecting R&D toward alternative thermal architectures.
- Induction:Electromagnetic coil systems deliver precise thermal control with energy recovery advantages previously unattainable in quick-service formats. Southeast Asian chains are retrofitting induction cooktops as electricity infrastructure reliability improves in metropolitan corridors.
- Wood:Solid-fuel systems persist in specialty barbecue and artisanal baking applications where flavor profile differentiation commands premium positioning.
Gas-fired equipment holds volume leadership; induction platforms show the steepest expansion trajectory.
Size:
Footprint constraints and throughput requirements segment demand across operator scale tiers.
- Small:Countertop and under-counter configurations serve food trucks, kiosks, and compact ghost kitchens with space premiums exceeding equipment cost considerations. India's tier-2 cloud kitchen buildouts favor small-format suites with rapid deployment timelines.
- Medium:Floor-standing units with moderate deck or vat capacity anchor independent restaurants and satellite production facilities balancing volume and flexibility.
- Large:High-throughput systems with multiple cavities or extended cooking surfaces serve centralized commissaries and high-volume institutional contracts.
- Extra Large:Custom-engineered battery configurations support airport catering hubs, stadium concessions, and national chain distribution centers with continuous batch requirements.
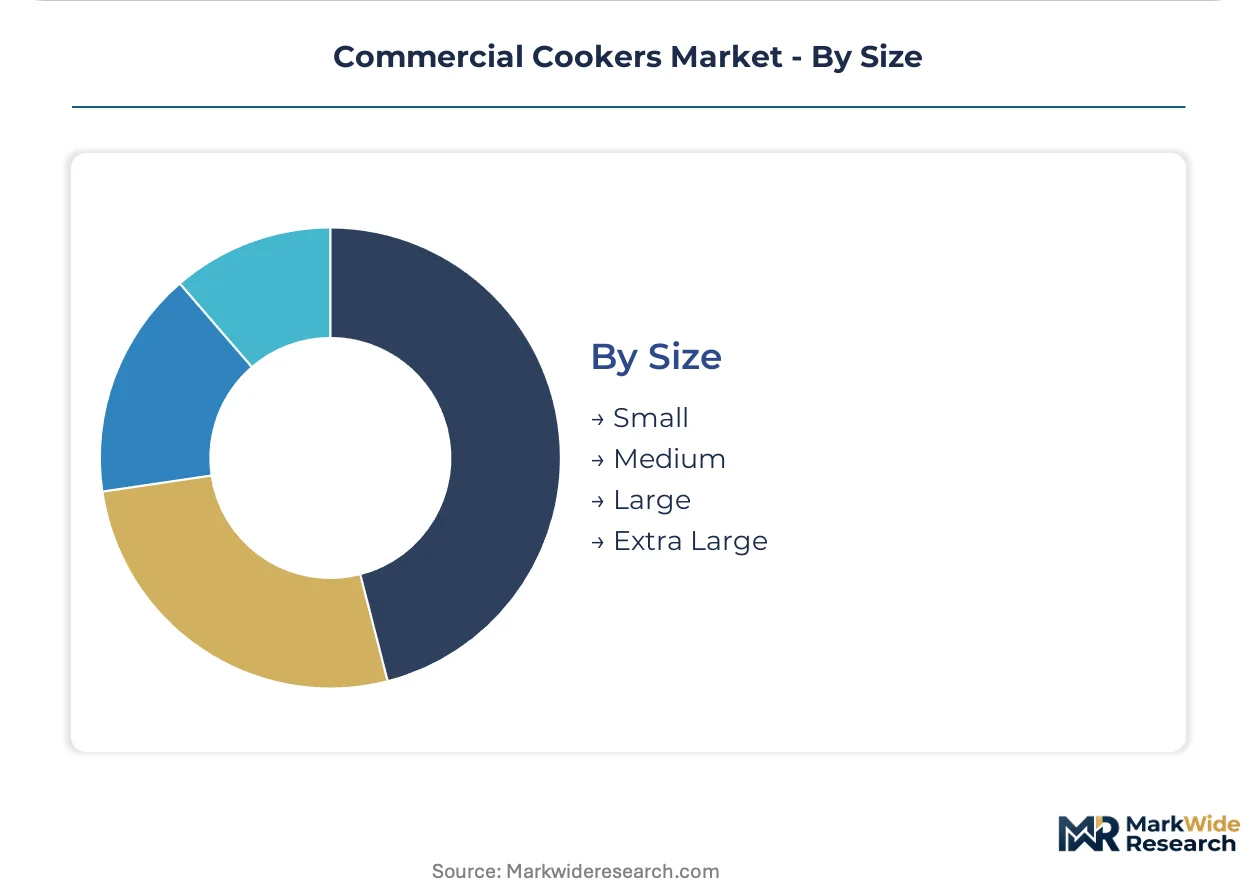
Medium-size units dominate replacement cycles; small-format equipment is climbing the fastest in absolute unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial cooker manufacturing originated in post-war industrial centers across the United States and Western Europe, where stainless steel fabrication expertise and institutional foodservice demand first converged at scale.
United States
EPA ENERGY STAR certification now gates federal institutional procurement contracts, accelerating replacement cycles in K-12 and healthcare cafeterias. The Department of Energy's Appliance and Equipment Standards Program tightens efficiency minimums annually. Equipment demand concentrates in the Southeast corridor from Atlanta to Miami, where quick-service chains expand centralized kitchen infrastructure.
Germany
The EU F-Gas Regulation's stepped refrigerant phase-down forces accelerated R&D on alternative thermal systems for combination cooking platforms. Ecodesign Directive compliance documentation requirements create adjacent revenue streams for engineering consultancies. Industrial clusters in Bavaria and Baden-Württemberg anchor modular cooktop system production for European hospitality chains.
India
Bureau of Energy Efficiency labeling standards under the Standards and Labeling Program mandate efficiency disclosure for commercial cooking appliances. Urban hospitality corridors in Mumbai, Delhi, and Bangalore scale centralized kitchen infrastructure to serve delivery-native brands. Cloud kitchen operators in tier-2 cities drive small-format equipment demand with rapid deployment timelines.
China
MIIT industrial equipment efficiency guidelines shape domestic manufacturing standards for export-oriented fabricators. Yangtze River Delta manufacturing bases supply convection and induction platforms to Southeast Asian quick-service chains. Zhejiang and Jiangsu provinces concentrate stainless steel fabrication capacity for mid-market equipment segments.
Japan
METI energy conservation standards for commercial kitchen equipment drive precision thermal control innovation. Kanto region equipment manufacturers supply compact, high-efficiency systems to space-constrained urban restaurant operators. Tokyo and Osaka metropolitan clusters prioritize induction technology adoption where electricity infrastructure reliability supports fuel switching from legacy gas installations.
Commercial Cookers Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and modular architecture depth. The vendor base organizes into three tiers: diversified conglomerates with captive component production, specialized mid-caps with vertical manufacturing footprints, and regional fabricators competing on first cost. Consolidation pressure intensifies as dual-track gas and electric R&D compliance burdens favor scale. Dominant competitive moves include strategic partnerships for IoT-enabled predictive maintenance platforms and geographic expansion through cloud kitchen infrastructure buildouts.
Within the diversified conglomerate tier, Middleby Corporation and Electrolux occupy positions defined by breadth across convection, fryer, and induction lines. Ali Group anchors the specialized mid-cap segment through deep focus on modular cooktop architectures. Rational AG exemplifies the precision-engineering archetype with combination oven-steamer platforms serving European institutional contracts. These three entities represent distinct competitive vectors: scale-driven portfolio breadth, modular specialization depth, and thermal system integration expertise.
| Leading Market Players |
|---|
| Middleby Corporation |
| Ali Group |
| Electrolux |
| Duke Manufacturing |
| Alto-Shaam |
| Welbilt |
| Rational AG |
| Vulcan |
| Imperial Commercial Cooking Equipment |
| Others |
Value Chain & Pricing Dynamics
Captive stainless steel fabrication in Zhejiang and Jiangsu provinces anchors both supply security and pricing power for mid-market equipment tiers. This backward integration into Grade 304 and 316 sheet processing insulates dominant fabricators from commodity volatility while compressing margins for project-contract operators lacking upstream control.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA ENERGY STAR-certified convection ovens from non-compliant thermal models and basic gas-fired units. Price differentiation centers on certification grade and after-sales service bundling, with US institutional buyers least sensitive and India's tier-2 cloud kitchen operators most cost-constrained. Pricing pressure stems from stainless steel input volatility, forcing fabricators toward shorter contract terms.
Supply Chain Analysis
India's Bureau of Energy Efficiency labeling mandates and China's MIIT efficiency guidelines are reshaping sourcing patterns for export-oriented fabricators. Supply concentrates in China, India, and Germany, with raw material dependencies on Indonesian nickel, South African chromium, and Australian iron ore. Single-source vulnerability runs through Yangtze River Delta stainless processing. Distribution runs through third-party facility management firms capturing specification influence in US K-12 and healthcare segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA ENERGY STAR certification gates and EU F-Gas phase-down schedules continuously refresh replacement demand.
For Market Incumbents: To counter induction technology displacement in Southeast Asian quick-service chains, Middleby Corporation and Ali Group should deepen backward integration into electromagnetic coil production and accelerate modular platform R&D. Certification investment in multi-vendor service interoperability represents the critical defensive lever as US buying committees unbundle procurement from installation contracts. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer the most penetrable wedge for cloud kitchen operators in India's tier-2 cities seeking rapid deployment with subscription-based service models. Target compact, high-density cooking suites with sensor-integrated diagnostics as the primary go-to-market angle, bypassing legacy distributor networks through direct facility management firm relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized mid-caps with modular cooktop expertise because dual-track gas and electric R&D compliance burdens favor scale over fragmentation. Long-term viability centers on acquisition of engineering consultancies with Ecodesign Directive documentation capabilities. Watch EPA efficiency rulemaking acceleration as the signal for replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Field-upgradable burner configurations extend equipment lifecycles for European hospitality chains. |
| Backward Integration into Coil Production | Captive electromagnetic component supply secures margin pools in induction-ready cooktop segments. |
| IoT Predictive Maintenance Launch | Sensor-integrated convection ovens shift revenue from equipment sales to recurring service subscriptions. |
| Ecodesign Compliance Services | Technical documentation support captures adjacent revenue from EU F-Gas Regulation deadlines. |
| Cloud Kitchen Infrastructure Partnership | Rapid-deployment compact suites penetrate India's tier-2 delivery-native brand expansion. |
Study Parameters
Direct dialogue with commercial kitchen equipment procurement managers, facility management firm technical directors, stainless steel fabrication plant engineers, and regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from US Department of Energy Appliance and Equipment Standards Program filings, EPA ENERGY STAR certification databases, EU Ecodesign Directive technical documentation, and Bureau of Energy Efficiency labeling records. Bottom-up equipment shipment analysis and top-down hospitality sector capex triangulation anchored volume estimates.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, fuel technology, end-user sophistication, and regional regulatory stringency. The analytical framework incorporated convection oven replacement cycles, induction cooktop retrofit penetration, and combination platform adoption curves. CAGRs derived from regression against historical efficiency mandate impacts and infrastructure buildout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel commodity volatility, F-Gas Regulation phase-down acceleration, and cloud kitchen operator consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Low-Sugar Rice Cooker Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Countertop Griddle Market