
 Restaurant Equipment Market | 2026-2036
Restaurant Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Equipment Market Outlook
Market Context
Energy Star certification tiers is reorganizing procurement priorities across commercial kitchen portfolios. Electrolux Professional leverages its European manufacturing base to dominate premium refrigeration lines in regulated markets. Middleby Corporation anchors its position through captive supply of automated cooking systems for major fast-food chains. Hobart Corporation specializes in dishwashing and food preparation equipment with deep channel control across North American dealer networks.
Technical Definition and Segments
Restaurant equipment comprises electrically or gas-powered appliances, stainless steel fabrication, and control systems engineered for commercial food preparation, cooking, storage, and sanitation at volumes exceeding residential thresholds by tenfold or greater. Cooking equipment and refrigeration units represent the largest product type segments, with smart ovens and energy-efficient refrigerators capturing margin pools as operators face utility cost pressures. Full-service restaurants and fast-food chains lead end-user demand, though catering services represent the fastest-growing channel as ghost kitchen formats multiply.
Regulatory Frame
The US Department of Energy and EPA Energy Star program shape minimum efficiency standards for refrigeration and cooking equipment, while the EU Ecodesign Directive and F-Gas Regulation restrict refrigerant types and thermal performance thresholds in European markets. China's GB standards and MIIT energy labeling enforce parallel compliance requirements for imported equipment. Stakeholders must monitor evolving refrigerant phase-down schedules and electrification mandates that will determine product line viability across major sourcing regions.
Market Dynamics
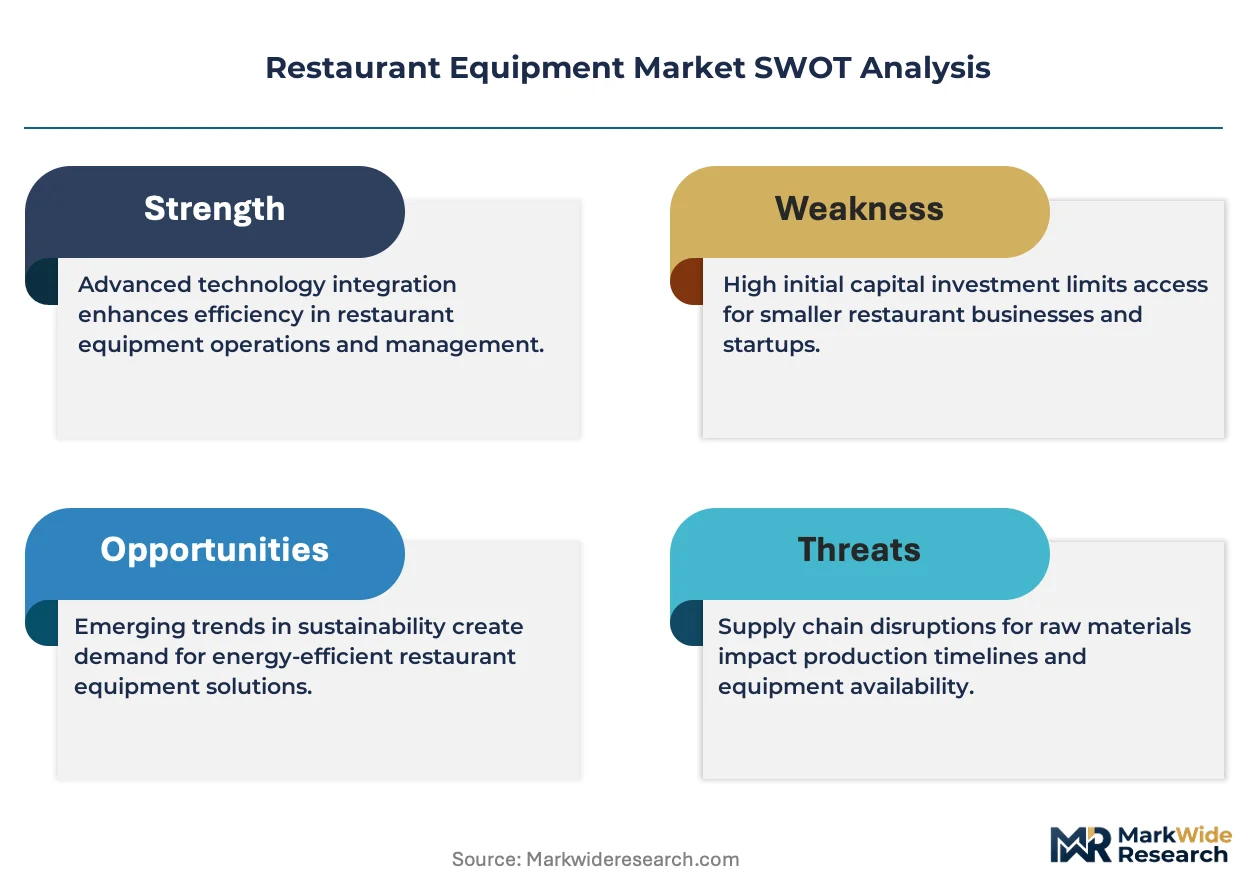
Energy efficiency mandates from the US Department of Energy are compressing equipment replacement cycles as operators face dual pressure from utility costs and refrigerant phase-down requirements. Full-service restaurants now treat kitchen modernization as a compliance-driven capital priority rather than discretionary upgrade.
Growth Catalysts
- Fast-food chain standardization:Domestic operators in China are deploying identical kitchen configurations across tier-one cities to ensure menu consistency and simplify maintenance protocols.
- Energy Star tier advancement:The EPA's certification thresholds are pulling forward replacement demand for commercial refrigeration units that fail to meet new efficiency benchmarks.
- Ghost kitchen proliferation:Catering services and delivery-only formats are driving compact, high-throughput equipment configurations optimized for limited footprints.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices compress margin predictability for fabrication-heavy product lines.
- European supply concentration:Premium refrigeration manufacturing clusters in Germany and Italy create geographic vulnerability to energy cost shocks and logistics disruption.
- F-Gas Regulation compliance friction:The EU's refrigerant restrictions force costly redesign cycles for equipment destined for European markets.
Strategic Opportunities
- India foodservice infrastructure buildout:Organized retail and quick-service penetration in tier-two Indian cities remains underpenetrated for standardized commercial kitchen equipment.
- Induction-electrification convergence:Gas-to-electric cooking transitions are creating white space for hybrid equipment platforms that bridge infrastructure gaps.
- IRA commercial incentives:US tax credits for energy-efficient appliance deployment are accelerating payback calculations for premium equipment upgrades.
Industry Challenges
- Refrigerant technician scarcity:The phase-down of hydrofluorocarbons has outpaced training pipeline capacity for alternative refrigerant handling certification.
- Legacy control system integration:Smart equipment retrofits face protocol incompatibility with existing building management systems in older restaurant properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Equipment Market |
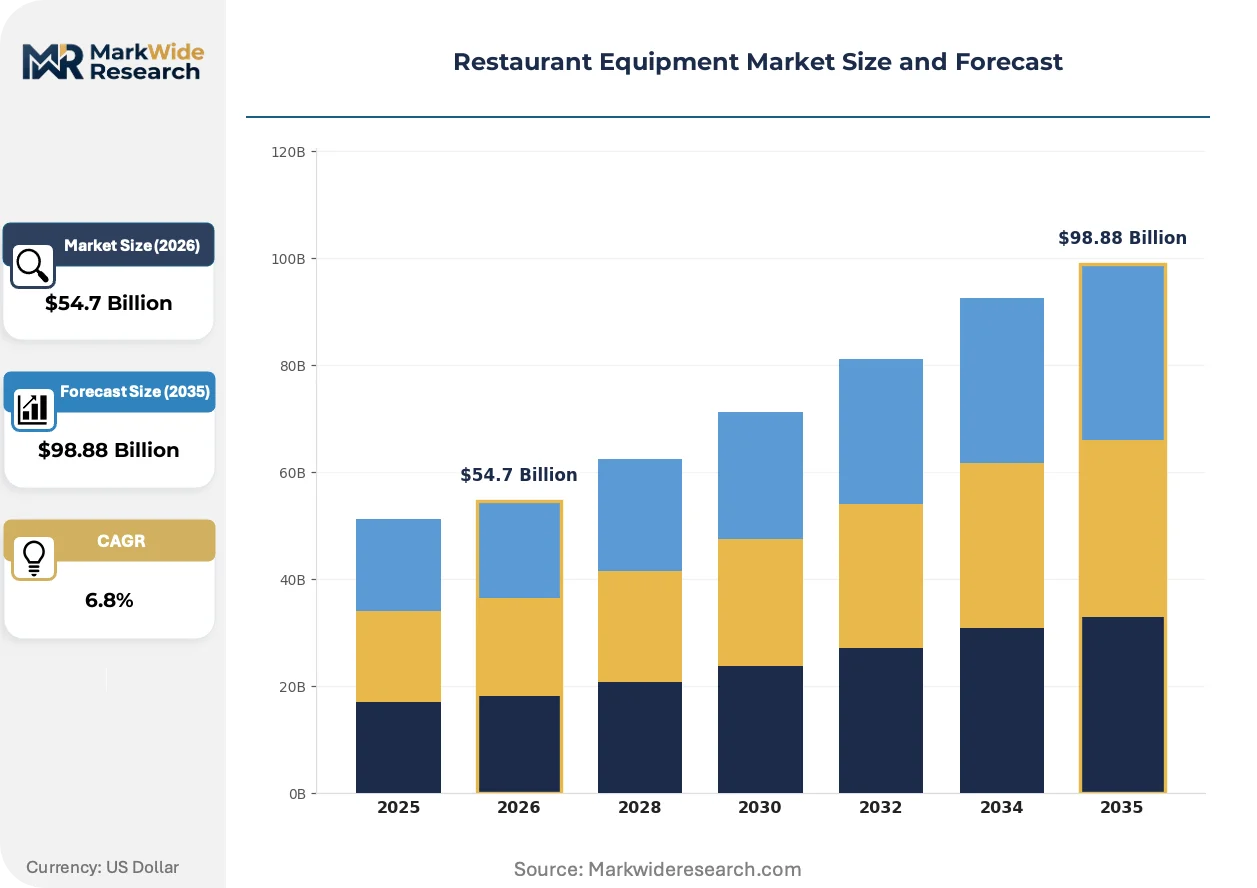
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Equipment, Refrigeration Units, Food Preparation Tools, Serving Equipment End User: Full-Service Restaurants, Fast-Food Chains, Cafes, Catering Services Material: Stainless Steel, Aluminum, Plastic, Wood Technology: Smart Ovens, Induction Cooktops, Energy-Efficient Refrigerators, Automated Dishwashers |
| Companies Covered | Electrolux Professional, Welbilt, Inc., Ali Group, Alto-Shaam, Fagor Commercial, Middleby Corporation, Rational AG, Cambro Manufacturing Co, Hobart Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Equipment Market Strategic Shifts
Connected equipment platforms and refrigerant chemistry shifts are redefining product architecture. Operators now prioritize total cost of ownership over upfront capital expenditure, compressing vendor differentiation around energy performance and predictive maintenance capabilities.
Connected ovens with embedded sensors and automated recipe management are supplanting manual temperature monitoring in high-volume operations. Fast-food chains are deploying these systems across flagship locations to reduce operator error and standardize output. The technology is compressing training requirements while enabling centralized menu updates across distributed fleets.
The EU F-Gas Regulation is tightening quotas for hydrofluorocarbon refrigerants used in commercial cooling equipment. Manufacturers are accelerating natural refrigerant transitions to carbon dioxide and hydrocarbon alternatives. European markets are experiencing the most acute compliance pressure, with importers facing port-of-entry certification verification.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale restaurant groups. Third-party financiers and OEM captive units are bundling maintenance, energy monitoring, and upgrade rights into per-meal fees. This arrangement is most visible in the United States, where private equity-backed restaurant portfolios seek balance sheet flexibility.
Restaurant Equipment Market Segmentation
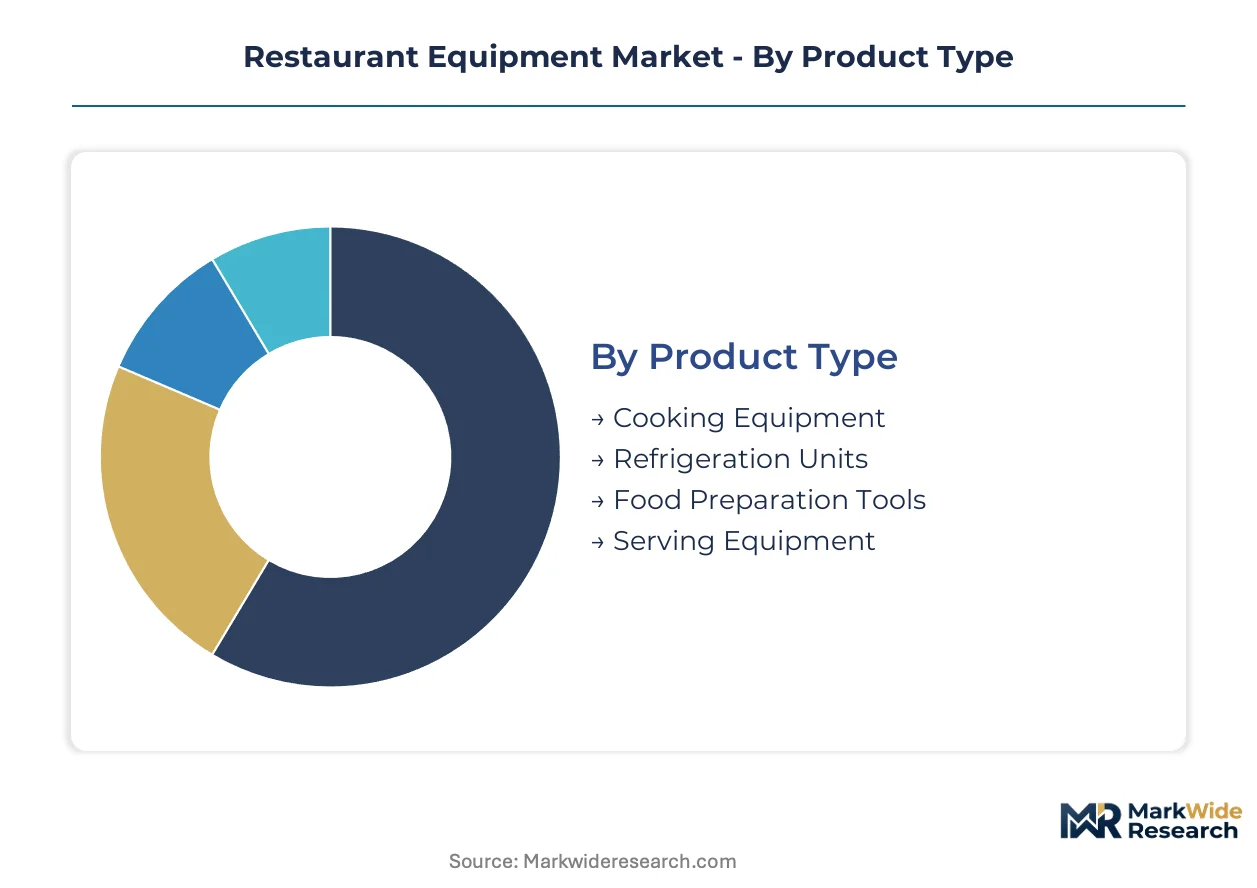
Equipment segmentation in foodservice channels determines procurement workflows, warranty structures, and aftermarket service economics. Channel partners stock inventory based on segment velocity, while operators configure kitchens around specific technology-material combinations that match menu throughput and utility infrastructure.
Product Type:
Channel mix varies sharply by product category, with cooking equipment flowing through dealer networks that bundle installation and training, while refrigeration units move through direct OEM relationships for large chain accounts.
- Cooking Equipment:Gas and electric ranges, fryers, griddles, and combi ovens engineered for continuous high-volume thermal processing. Fast-food chains in China are standardizing combi oven configurations across tier-one city deployments to compress training overhead and menu variance.
- Refrigeration Units:Reach-in coolers, walk-in freezers, and blast chillers with compressor systems regulated by DOE efficiency thresholds and F-Gas refrigerant quotas. Full-service restaurants treat these as compliance-driven replacement priorities as Energy Star tiers advance.
- Food Preparation Tools:Slicers, mixers, food processors, and cutting stations for upstream ingredient processing.
- Serving Equipment:Heated holding cabinets, steam tables, and buffet infrastructure for final-stage presentation.
By volume, cooking equipment leads. By growth pace, refrigeration is climbing the fastest amid regulatory replacement cycles.
End User:
Cost tier stratification separates capital-heavy full-service kitchens from equipment-light ghost kitchen formats, with procurement authority concentrating differently across each tier.
- Full-Service Restaurants:Complex kitchen architectures requiring coordinated cooking, refrigeration, and sanitation systems with extended equipment lifecycles. Operators face dual pressure from DOE efficiency mandates and refrigerant phase-down schedules that compress replacement timelines.
- Fast-Food Chains:Standardized, high-throughput configurations optimized for menu consistency and rapid crew training. Domestic Chinese operators are deploying identical kitchen layouts across tier-one cities to simplify maintenance protocols and supply chain logistics.
- Cafes:Compact footprints emphasizing beverage preparation and limited hot food service.
- Catering Services:Mobile and temporary installations for event-based food production.
Full-service restaurants anchor procurement volume. Catering services are expanding most quickly as ghost kitchen formats multiply.
Material:
Supply concentration for nickel and chromium inputs creates margin volatility that propagates through fabrication-heavy product lines.
- Stainless Steel:Austenitic grades 304 and 316 dominate commercial kitchen fabrication for corrosion resistance and cleanability. Nickel price fluctuations compress margin predictability for OEMs producing refrigeration cabinets and cooking suites.
- Aluminum:Lightweight extrusions and castings for portable equipment and heat exchange components. Catering services favor aluminum construction for mobility and thermal efficiency in temporary installations.
- Plastic:Polymer housings and food-contact surfaces for cost-sensitive preparation tools.
- Wood:Cutting boards, display fixtures, and aesthetic elements for front-of-house integration.
Stainless steel commands the highest unit economics. Aluminum is gaining share fastest in mobile and catering applications.
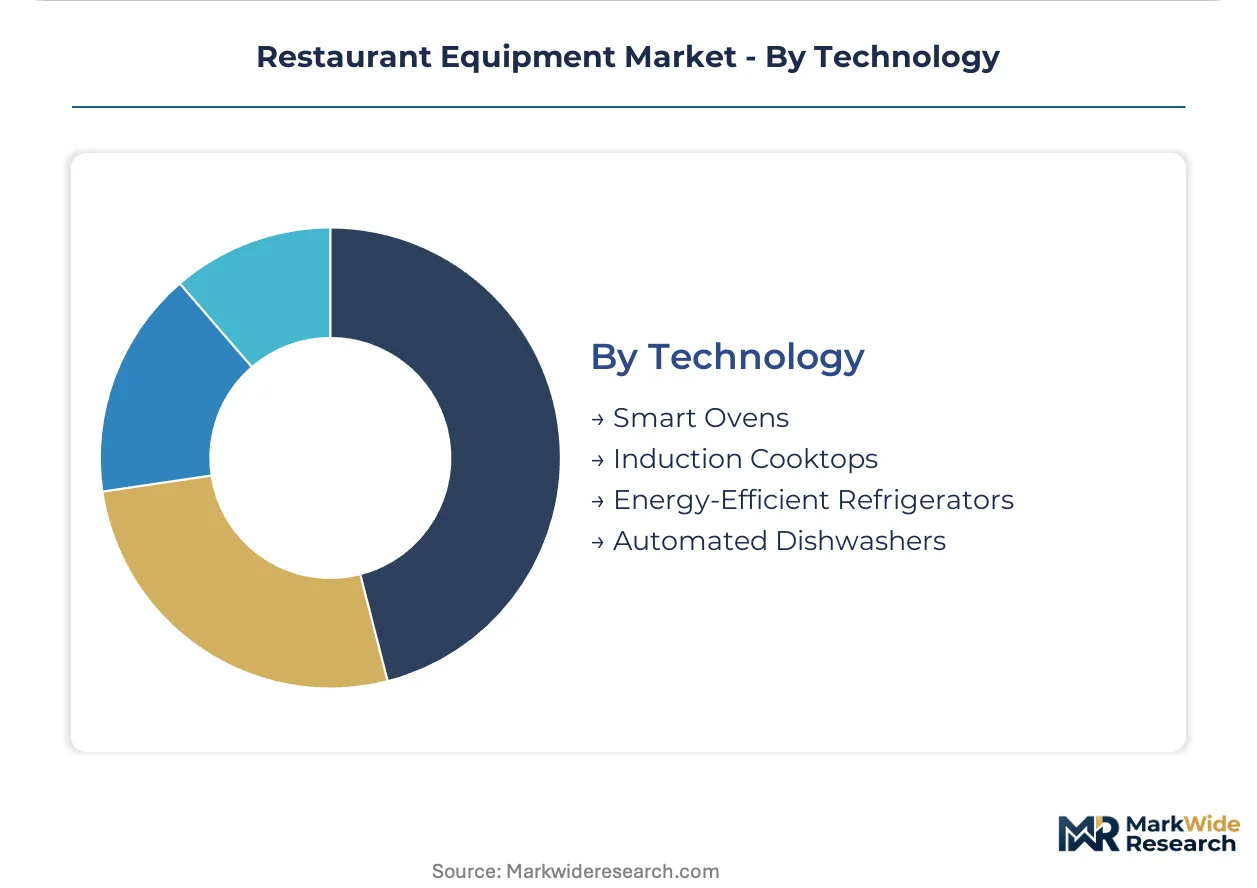
Technology:
Maturity gradients separate established induction platforms from emerging connected equipment architectures that require protocol integration with building management systems.
- Smart Ovens:Sensor-embedded thermal systems with automated recipe management and remote monitoring capabilities. Fast-food chains deploy these across flagship locations to reduce operator error and enable centralized menu updates.
- Induction Cooktops:Electromagnetic heating platforms enabling precise temperature control and reduced ambient heat load. Gas-to-electric transitions in US markets are creating white space for hybrid equipment that bridges infrastructure gaps.
- Energy-Efficient Refrigerators:Compressor and insulation systems designed to meet advancing DOE and Energy Star thresholds.
- Automated Dishwashers:Conveyor and door-type machines with water recovery and chemical dosing optimization.
Energy-efficient refrigerators dominate current procurement volume. Smart ovens are on the steepest expansion trajectory as connectivity platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in restaurant equipment tilt toward manufacturing surplus regions serving import-dependent foodservice markets. Germany and Italy anchor European refrigeration exports. China balances domestic absorption with selective equipment exports across Southeast Asia.
United States
Full-service restaurant chains are accelerating kitchen modernization to meet DOE efficiency thresholds. The EPA's Energy Star program is pulling forward replacement cycles for commercial refrigeration units. Equipment-as-a-service contracting is proliferating across private equity-backed restaurant portfolios in major metro markets.
Germany
Commercial refrigeration OEMs face acute pressure from the EU F-Gas Regulation's hydrofluorocarbon quotas. The Ecodesign Directive is tightening thermal performance thresholds for equipment sold across member states. Manufacturing clusters in Bavaria and Baden-Württemberg are accelerating natural refrigerant transitions to carbon dioxide platforms.
China
Domestic fast-food chains are deploying standardized kitchen configurations across tier-one cities including Beijing, Shanghai, and Shenzhen. MIIT energy labeling and GB standards enforce compliance requirements for imported equipment. Yangtze River Delta manufacturing bases are scaling production for both domestic absorption and selective Southeast Asian export.
India
Organized retail and quick-service penetration in tier-two cities is creating infrastructure demand for standardized commercial kitchens. BIS certification requirements and FSSAI food safety standards shape equipment import protocols. Maharashtra and Gujarat are emerging as concentration points for foodservice chain expansion and equipment distribution.
Italy
Premium refrigeration and cooking equipment manufacturing concentrates in northern industrial districts. The EU F-Gas Regulation is forcing costly redesign cycles for equipment lines destined for European markets. Emilia-Romagna and Lombardy host specialized fabricators supplying regulated markets with high-efficiency product lines.
Restaurant Equipment Market Competitive Environment
Listed leaders compete with private specialists across capital structure and investment horizon dimensions. The vendor base stratifies into three tiers: multinational diversified industrials with captive distribution, mid-scale specialists with regional manufacturing concentration, and private equity-backed roll-ups consolidating fragmented service networks. Two dominant competitive moves are reshaping positioning: backward integration into stainless steel fabrication to control input cost volatility, and strategic partnerships with third-party financiers to expand equipment-as-a-service penetration.
Among European-based diversified industrials, Electrolux Professional and Rational AG occupy positions anchoring premium-tier refrigeration and thermal processing lines. Middleby Corporation exemplifies the acquisition-driven consolidator archetype, with its corporate structure reflecting serial rollup activity across automated cooking systems. These three entities represent distinct strategic postures: European manufacturing-based premium positioning, German engineering-specialist focus, and North American scale-driven consolidation.
| Leading Market Players |
|---|
| Electrolux Professional |
| Welbilt, Inc. |
| Ali Group |
| Alto-Shaam |
| Fagor Commercial |
| Middleby Corporation |
| Rational AG |
| Cambro Manufacturing Co |
| Hobart Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Yangtze River Delta fabrication facilities shapes both supply concentration and price floors for stainless steel-intensive product lines. Full-service restaurant chains in the United States face compressed replacement timelines as DOE efficiency mandates pull forward demand, tightening procurement leverage against OEMs.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels for commercial refrigeration and cooking suites. Price differentiation rests on Energy Star certification tier and stainless steel grade specification, with nickel price volatility compressing margin predictability for fabrication-heavy lines. Cost compression in economy-tier equipment is intensifying because Chinese domestic brands are scaling standardized kitchen deployments. Fast-food chains exhibit lowest price sensitivity due to total cost of ownership calculations, while independent full-service operators remain most exposed to upfront capital constraints.
Supply Chain Analysis
Inventory lead times for compressor systems and control modules have extended as European manufacturers accelerate natural refrigerant transitions under F-Gas Regulation quotas. Manufacturing gravity centers on China, Germany, and Italy for premium refrigeration and thermal processing equipment. Raw material dependencies draw from nickel and chromium ore markets, copper winding stock, and semiconductor components for smart control systems. Single-source vulnerability concentrates in Bavarian and Baden-Württemberg compressor manufacturing clusters. Distribution runs through dealer networks bundling installation and training for cooking equipment, while large chain accounts procure refrigeration through direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting is creating platform-economics inflection as third-party financiers bundle maintenance and upgrade rights into per-meal fees. Interoperability standards between connected ovens and building management systems are determining vendor lock-in dynamics across distributed restaurant fleets.
For Market Incumbents: Compound defensive positioning through backward integration into stainless steel fabrication to control nickel price volatility exposure. Capture channel control across North American dealer networks before emerging connectivity platforms disintermediate traditional procurement relationships. Prioritize certification investment in natural refrigerant handling capabilities as F-Gas Regulation phase-down schedules compress product line viability. For New Entrants and Emerging Players: Differentiate on hybrid induction-gas cooking platforms that bridge infrastructure gaps in US markets undergoing electrification transitions. Target tier-two Indian cities where organized retail penetration remains underdeveloped for standardized commercial kitchen equipment. Pursue go-to-market partnerships with ghost kitchen operators seeking compact, high-throughput configurations optimized for limited footprints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OEMs with captive financing units and predictive maintenance software stacks. Long-term viability hinges on regulatory compliance adaptability across multiple jurisdictions rather than geographic concentration. Acquisition target archetype: mid-scale specialists with regional manufacturing concentration and established service networks. Monitor refrigerant technician certification pipeline capacity as inflection indicator for aftermarket service economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Mitigates nickel price volatility exposure for refrigeration cabinet OEMs. |
| Natural Refrigerant Platform Transition | Secures EU market access as F-Gas Regulation quotas tighten compliance thresholds. |
| Equipment-as-a-Service Financing Launch | Captures private equity-backed restaurant portfolios seeking balance sheet flexibility. |
| Smart Oven Connectivity Stack Development | Enables centralized menu updates across fast-food chain distributed fleets. |
| Tier-Two India Distribution Buildout | Positions for quick-service penetration in Maharashtra and Gujarat expansion zones. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with foodservice operators and equipment OEMs, and secondary validation across regulatory filings and trade databases. Interview participants included procurement directors at full-service restaurant chains, aftermarket service heads at dealer networks, plant engineers at Yangtze River Delta manufacturing facilities, and regulatory compliance leads at refrigeration OEMs. Secondary sources encompassed DOE appliance efficiency standards, EPA Energy Star certification databases, EU F-Gas Regulation quota schedules, MIIT energy labeling requirements, and customs records for stainless steel fabrication inputs. Bottom-up equipment shipment data triangulated against top-down foodservice construction permits and chain expansion announcements.
Across the analysis window, projections integrate product type segmentation by cooking equipment, refrigeration units, food preparation tools, and serving equipment; end-user segmentation spanning full-service restaurants, fast-food chains, cafes, and catering services; and technology segmentation across smart ovens, induction cooktops, energy-efficient refrigerators, and automated dishwashers. CAGRs were derived from regression analysis against historical replacement cycle compression and regulatory mandate timing. Forecast inputs include stainless steel price index trajectories, refrigerant phase-down schedules, and ghost kitchen format proliferation rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of efficiency standards or accelerated electrification infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding replacement cycle elasticity and supply chain disruption frequency. Specific risk factors include nickel price spike events, F-Gas Regulation quota acceleration, and technician certification pipeline bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
US and Canada Hot Food Vending Machine Market
Food Service Equipment
Used Restaurant Equipment Market