
 Commercial Electric Restaurant Ranges Market | 2026-2036
Commercial Electric Restaurant Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Electric Restaurant Ranges Market Outlook
Quick-service chains and ghost kitchen operators are consolidating their equipment procurement around electric ranges to lower utility exposure and simplify ventilation. Vulcan Equipment dominates the heavy-duty floor range segment through captive manufacturing of heating elements. Garland Group leverages its distribution network across North American dealer channels. Southbend differentiates through modular configurations that reduce installation downtime for renovation projects.
Commercial electric restaurant ranges are stationary cooking appliances powered by resistive or induction heating elements, typically operating at 208–480 volts with outputs from 12 to 50 kilowatts, designed for continuous batch cooking in licensed foodservice facilities. Floor ranges command the largest installed base due to their throughput capacity in high-volume kitchens, while induction ranges capture the fastest expansion as operators prioritize precision temperature control and reduced ambient heat. The hospitality sector drives replacement cycles through franchise standardization programs, whereas culinary schools represent a smaller but specification-influential end user segment that shapes future purchasing norms.
The US Department of Energy sets minimum efficiency thresholds for commercial cooking equipment, while NSF International certifies sanitation and construction standards that govern market access. California's Title 24 building codes and local gas connection moratoria in cities such as San Francisco and Berkeley are reshaping new construction specifications toward all-electric kitchens. Stakeholders must monitor municipal electrification ordinances and utility rebate programs to anticipate regional demand inflections before competitors lock in specification relationships.
Market Dynamics
Electrification mandates from US Department of Energy commercial cooking equipment standards are compressing gas-to-electric conversion timelines, forcing operators to accelerate capital replacement cycles ahead of regulatory deadlines.
Growth Catalysts
- California Title 24 Building Codes:All-electric kitchen requirements in new construction are mandating electric range specifications across full-service and quick-service restaurant chains, eliminating gas infrastructure from design-phase decisions.
- Induction Heating Technology:Precision temperature control and reduced ambient heat are displacing resistive elements in high-throughput kitchens, particularly where ventilation costs dominate operational budgets.
- Ghost Kitchen Consolidation:Centralized procurement by delivery-focused operators is aggregating demand for standardized electric equipment configurations, reducing supplier negotiation leverage.
Market Restraints
- Copper and Semiconductor Input Volatility:Heating element manufacturing depends on copper winding and power control semiconductors, exposing margins to commodity price swings and foundry allocation constraints.
- Electrical Infrastructure Retrofit Costs:Existing facilities require 208–480 volt three-phase upgrades, creating capital barriers for independent operators in older urban buildings with legacy 120-volt distribution.
- Gas Range Substitution Threat:Propane and natural gas alternatives retain installed base advantages in regions without electrification mandates, particularly where utility electricity rates exceed thermal fuel costs.
Strategic Opportunities
- Texas and Florida New Construction:Population-driven restaurant development in these states is outpacing electrification mandate adoption, creating specification windows before codes tighten.
- Culinary School Specification Influence:Training institutions are embedding induction proficiency into curricula, shaping future chef preferences that translate into franchise procurement standards.
- Utility Rebate Program Arbitrage:Demand-side management incentives from municipal utilities in California, New York, and Massachusetts are offsetting equipment premiums for early electrification adopters.
Industry Challenges
- NSF International Certification Timelines:Sanitation and construction standard validation creates 6–12 month product launch delays, compressing competitive response windows to regulatory changes.
- Legacy Ventilation System Integration:Existing hood and exhaust configurations designed for gas combustion loads require recalculation for reduced induction heat signatures, complicating renovation project scopes.
- Electrician Skill Shortages:Commercial kitchen equipment installation demands certified high-voltage technicians, with labor scarcity extending project timelines in dense urban markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Electric Restaurant Ranges Market |
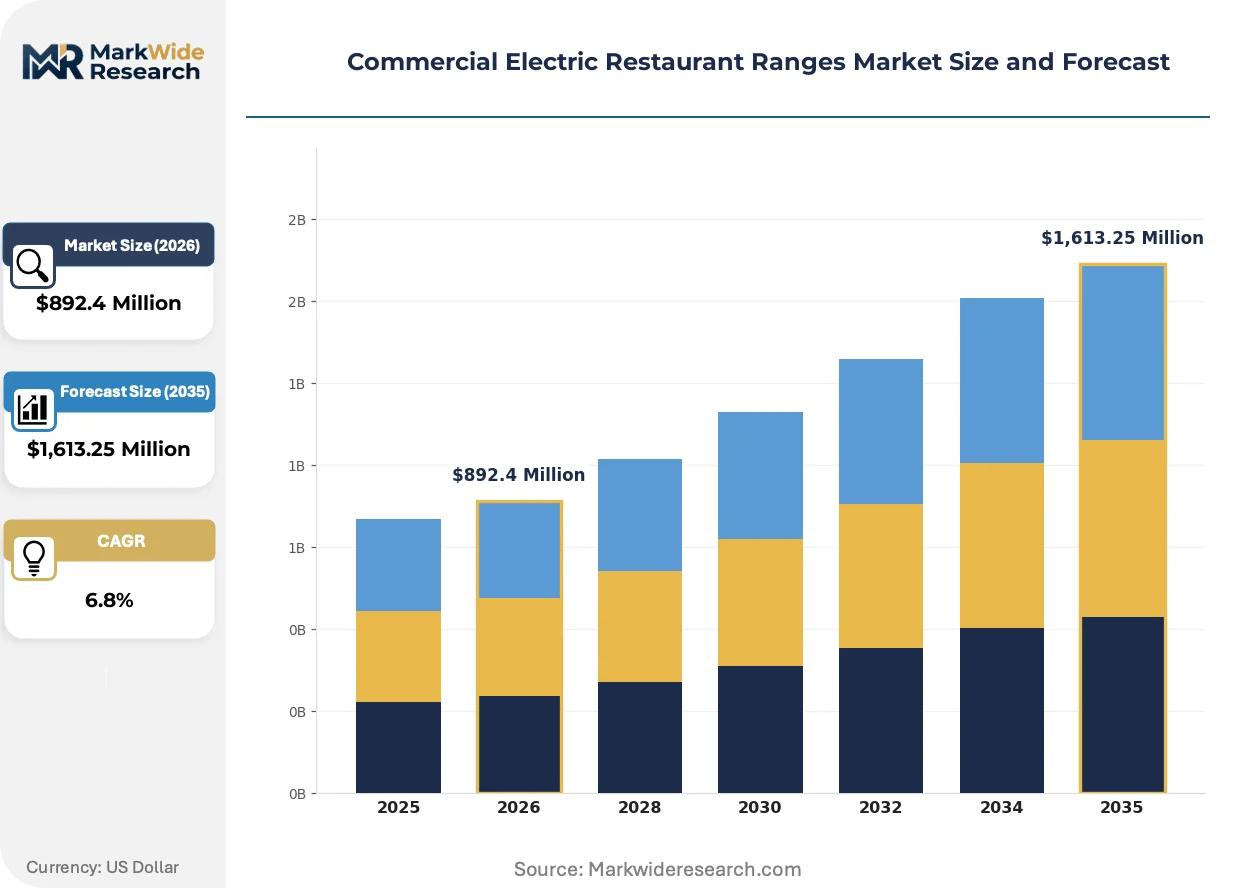
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ranges, Floor Ranges, Combination Ranges, Induction Ranges Application: Restaurants, Cafés, Caterers, Food Trucks End User: Commercial Kitchens, Hospitality Sector, Culinary Schools, Institutions Distribution Channel: Retail Stores, Online Portals, Direct Sales, Distributors |
| Companies Covered | Vulcan Equipment, Garland Group, Imperial Commercial Cooking Equipment, Southbend, American Range Corporation, Comstock-Castle Stove Co., Wolf Range, Alto-Shaam, Inc., Blodgett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Electric Restaurant Ranges Market Strategic Shifts
Equipment manufacturers are embedding connectivity and automation into electric ranges to differentiate beyond thermal performance, while regulatory pressure and operator consolidation reshape procurement criteria.
Smart induction ranges with IoT-enabled temperature logging and predictive maintenance alerts are integrating into enterprise kitchen management platforms. Multi-unit franchise operators are deploying these systems to standardize quality control across distributed locations. This convergence of cooking hardware and data infrastructure is compressing the competitive advantage window for equipment-only suppliers.
The US Department of Energy's amended commercial cooking equipment standards are tightening minimum efficiency thresholds for electric resistance and induction technologies. Manufacturers must redesign heating element geometries and power control algorithms to maintain market access. Heavy-duty floor range categories face the steepest compliance redesign costs due to their higher thermal output specifications.
Quick-service chains are consolidating procurement through national equipment leasing programs rather than capital purchase models. Dealer networks are losing specification influence as corporate procurement teams centralize vendor selection and negotiate enterprise service agreements. This channel compression is most visible in California and New York markets where electrification mandates have synchronized replacement cycles across franchise systems.
Commercial Electric Restaurant Ranges Market Segmentation
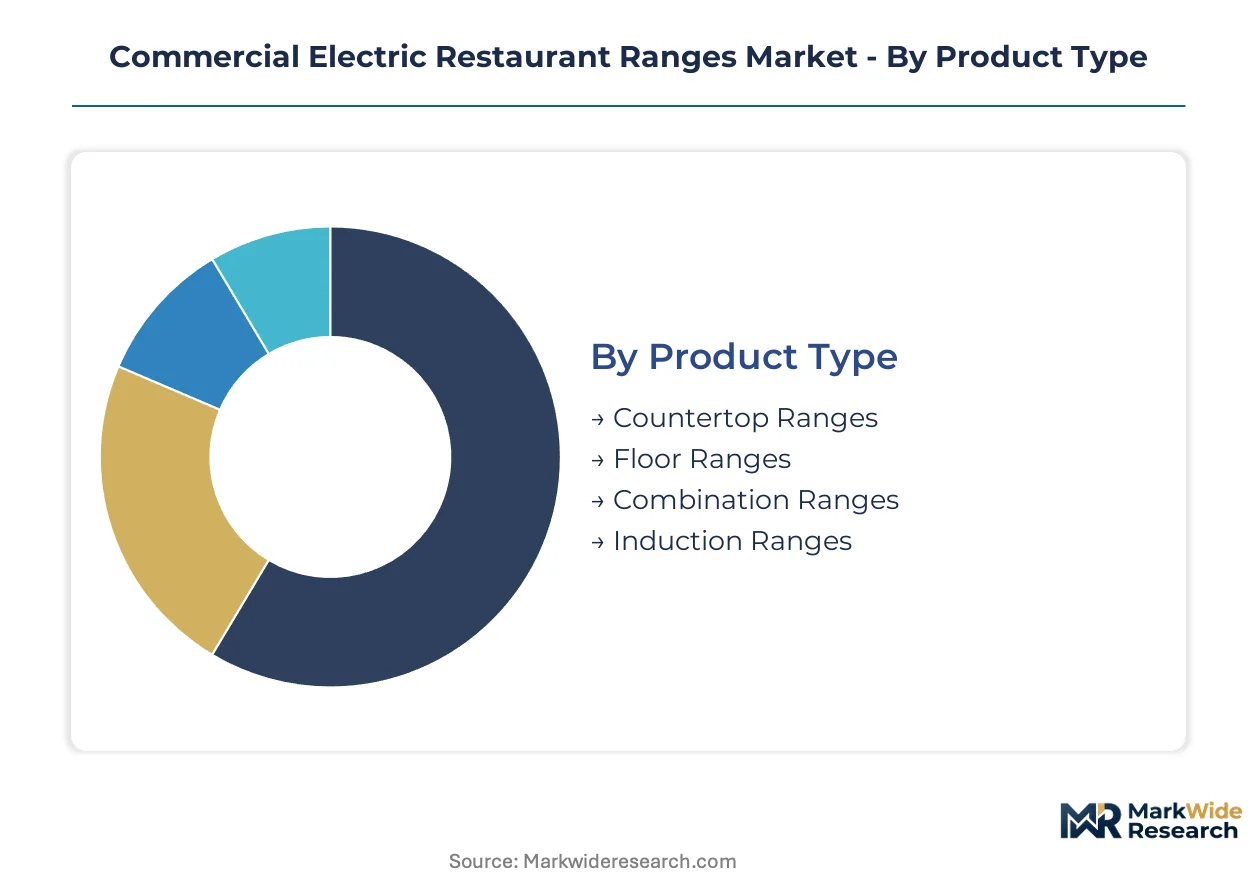
Commercial electric restaurant ranges fragment across equipment form factors, operational settings, and procurement pathways that each impose distinct technical and commercial requirements. Understanding these divisions clarifies where specification influence concentrates and which upgrade cycles offer the strongest revenue capture potential.
Product Type:
Replacement cycles vary dramatically by equipment footprint, with heavy-duty installations demanding longer capital planning horizons than modular alternatives.
- Floor Ranges:Stationary heavy-duty units operating at 208–480 volts with 12–50 kilowatt outputs anchor throughput capacity in high-volume licensed foodservice facilities. California Title 24 building codes are mandating these specifications in new full-service and quick-service restaurant construction, eliminating gas infrastructure from design-phase decisions.
- Induction Ranges:Precision temperature control and reduced ambient heat signatures displace resistive elements where ventilation costs dominate operational budgets. Ghost kitchen operators are consolidating procurement around these configurations to lower utility exposure and simplify exhaust requirements.
- Countertop Ranges:Compact units suited for space-constrained operations and renovation projects where three-phase electrical upgrades prove impractical.
- Combination Ranges:Multi-function designs integrating oven bases with cooktop surfaces, favored by caterers requiring equipment mobility across event venues.
Floor ranges sit at the top of the volume ranking, with induction ranges climbing the fastest.
Application:
Operational intensity and regulatory exposure shape demand concentration across foodservice formats.
- Restaurants:Full-service and quick-service chains are expanding electric kitchen footprints as US Department of Energy commercial cooking equipment standards compress gas-to-electric conversion timelines. Franchise standardization programs drive replacement cycles through specification lock-in.
- Caterers:Mobile and event-based operations prioritize equipment portability and rapid power connection, with demand clustering in Texas and Florida where population-driven restaurant development outpaces electrification mandate adoption.
- Cafés:Limited-service formats with lower throughput requirements favor countertop and modular configurations.
- Food Trucks:Severe space and electrical constraints restrict viable equipment options to compact induction and resistive units.
Restaurants command the largest installed base, while caterers are expanding most quickly as event-service demand rebounds.
End User:
Procurement authority and specification influence diverge sharply between centralized hospitality groups and dispersed institutional buyers.
- Commercial Kitchens:Centralized facilities in ghost kitchen networks and delivery-focused operations aggregate demand for standardized electric equipment configurations, reducing supplier negotiation leverage through volume concentration.
- Hospitality Sector:Hotel and resort foodservice operations drive replacement cycles through enterprise procurement programs, with California properties facing accelerated electrification deadlines under local gas connection moratoria.
- Culinary Schools:Training institutions embed induction proficiency into curricula, shaping future chef preferences that translate into franchise procurement standards despite representing smaller absolute volume.
- Institutions:Government and corporate cafeterias face extended capital approval timelines but offer multi-year equipment lease structures.
Commercial kitchens dominate current revenue concentration, with culinary schools gaining specification influence fastest.
Distribution Channel:
Channel compression is reshaping how operators access equipment and service support.
- Distributors:North American dealer channels retain specification influence in renovation projects where installation expertise and local service relationships prove decisive, though corporate procurement centralization is eroding this position in California and New York markets.
- Direct Sales:National equipment leasing programs are consolidating procurement for quick-service chains, bypassing traditional dealer networks in favor of enterprise service agreements.
- Retail Stores:Limited to small independent operators and emergency replacement purchases.
- Online Portals:Growing share for standardized countertop units and replacement parts, constrained by high-voltage installation requirements for heavy-duty equipment.
Distributors maintain the deepest existing relationships, with direct sales capturing the steepest expansion trajectory as franchise procurement centralizes.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting equipment procurement toward jurisdictions where electrification mandates create specification windows before compliance costs rise. Manufacturers are positioning production capacity to serve these demand clusters while codes remain permissive.
United States
California's Title 24 building codes and municipal gas connection moratoria in San Francisco and Berkeley are mandating all-electric kitchen specifications in new construction. The US Department of Energy's commercial cooking equipment standards compress conversion timelines nationwide. Texas and Florida markets concentrate demand where population-driven restaurant development outpaces electrification mandate adoption, creating specification capture opportunities.
Canada
Provincial energy efficiency regulations in British Columbia and Ontario are tightening commercial kitchen equipment standards ahead of federal harmonization. Natural Resources Canada administers equipment certification programs that parallel NSF International sanitation requirements. The Greater Toronto Area anchors procurement volume for chain restaurant electrification projects.
Germany
The EU Green Deal and national building energy efficiency regulations are accelerating commercial kitchen electrification in new hospitality construction. Ecodesign requirements under EU framework directives set minimum efficiency thresholds for cooking equipment. Bavaria's foodservice manufacturing cluster around Munich supplies induction technology to central European markets.
United Kingdom
Building regulations Part L conservation of fuel and power amendments are tightening commercial kitchen energy performance standards. The Climate Change Committee's net-zero pathway pressures hospitality operators toward electric alternatives. London's dense urban restaurant concentration drives renovation-project demand for compact induction configurations.
Japan
METI's Top Runner program sets escalating efficiency standards for commercial cooking equipment categories. Tokyo's metropolitan building energy codes restrict gas infrastructure in new large-scale developments. The Kansai region's precision manufacturing base supplies induction heating components to domestic and export markets.
Commercial Electric Restaurant Ranges Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with heavy-duty floor range categories concentrating around established fabrication names while modular and countertop configurations attract diversified equipment producers. The vendor base organizes into three archetypes: captive heating-element manufacturers, distribution-network aggregators, and modular-configuration specialists. Consolidation pressures favor scale players with in-house component production and enterprise service agreement capabilities. Geographic expansion and technology licensing represent the dominant competitive vectors as regional codes synchronize.
Among North American fabrication specialists, Vulcan Equipment, Garland Group, and Southbend occupy positions across distinct strategic tiers. Vulcan Equipment exemplifies the captive-manufacturing archetype through vertical control of heating element production. Garland Group represents distribution-network leverage across dealer channels. Southbend anchors the modular-configuration specialist tier. These three names illustrate how competitive positioning fragments across technical specialization, channel control, and installation-flexibility value propositions rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Vulcan Equipment |
| Garland Group |
| Imperial Commercial Cooking Equipment |
| Southbend |
| American Range Corporation |
| Comstock-Castle Stove Co. |
| Wolf Range |
| Alto-Shaam, Inc. |
| Blodgett |
| Others |
Value Chain & Pricing Dynamics
Copper futures volatility on the London Metal Exchange cascades through heating element fabrication into three distinct pricing tiers across the commercial electric restaurant ranges market. Resistive coil manufacturers pass material swings directly to mid-market buyers, while induction specialists absorb short-term spikes through captive semiconductor inventories.
Pricing Analysis
Distributor margins spanning 18-25 percent separate factory gate from installed pricing across North American dealer channels. Three-tier pricing structure across premium, standard, and economy levels reflects NSF certification grade, heating element technology type, and bundled installation service. Cost compression in economy-tier resistive ranges is intensifying because ghost kitchen operators are consolidating procurement volume for standardized configurations. Independent restaurant operators exhibit highest price sensitivity due to capital constraints, whereas hospitality groups with enterprise leasing programs prioritize total cost of ownership over upfront equipment cost.
Supply Chain Analysis
Refurbishment flows for induction power modules and control boards are extending equipment lifecycle value through authorized service depots in Ohio, Tennessee, and Mexico. Component manufacturing draws from China for power semiconductors, Germany for precision heating coils, and domestic US facilities for stainless steel fabrication enclosures. Single-source vulnerability concentrates in IGBT transistor supply from East Asian foundries. Distribution runs through authorized dealer networks for heavy-duty floor ranges, while countertop units increasingly flow through direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on induction technology premiumization and copper input hedging programs that stabilize manufacturing cost bases. Equipment suppliers capturing specification relationships ahead of municipal electrification ordinance waves will command pricing power through the forecast window.
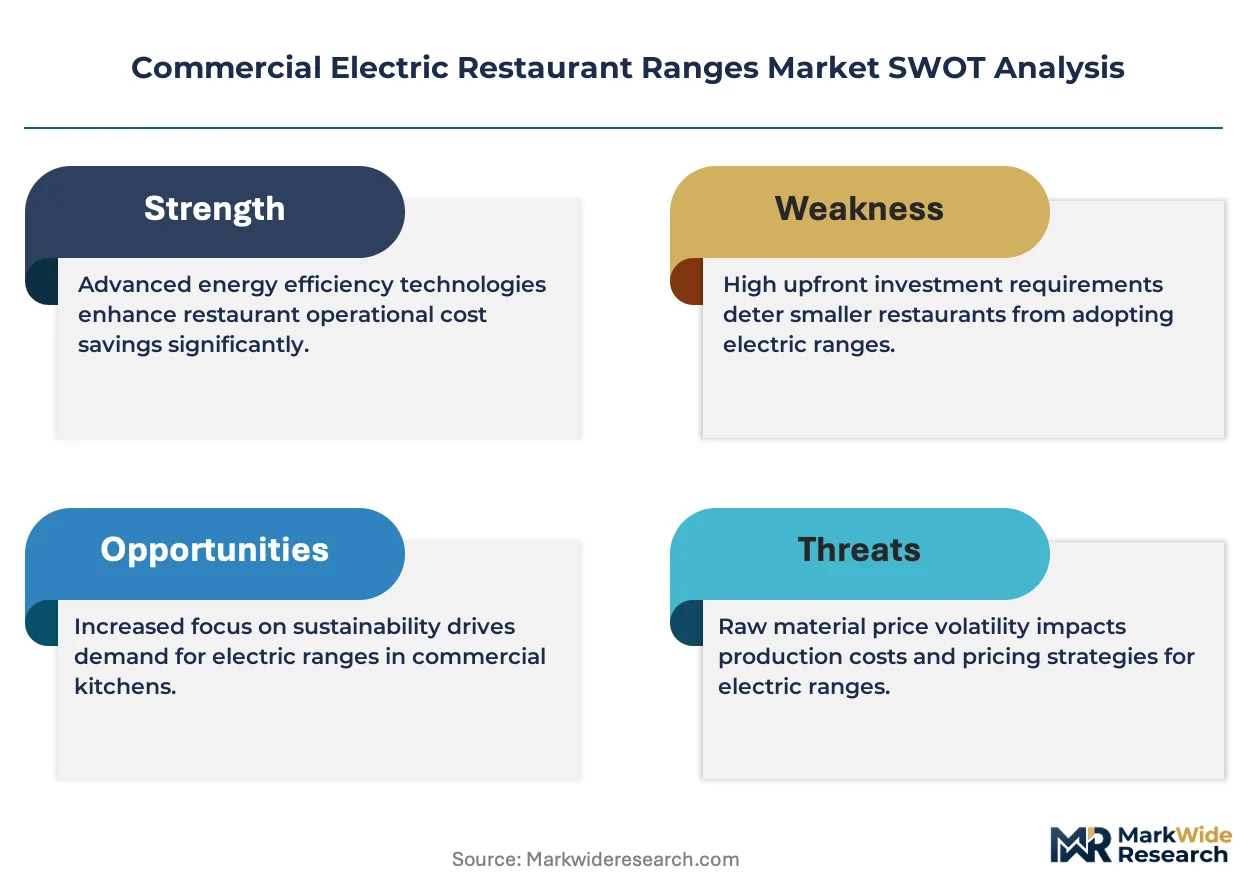
For Market Incumbents: Lock in specification relationships with California and New York franchise operators before Title 24 and local gas moratoria synchronize replacement cycles. Deepen backward integration into heating element production to offset copper price volatility. Prioritize NSF certification pipeline investment to compress 6-12 month validation timelines that delay competitive response to regulatory shifts. For New Entrants and Emerging Players: Begin with countertop induction configurations targeting Texas and Florida independent operators where electrification mandates lag population-driven construction. The most penetrable white space sits in compact modular ranges for food truck and ghost kitchen retrofit applications. A service-leasing hybrid go-to-market model bypasses capital-constrained buyer resistance. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fabrication specialists possessing in-house heating element capability and established California specification track records. Long-term viability favors suppliers with enterprise service agreement infrastructure and IoT-enabled predictive maintenance platforms. Monitor municipal utility rebate program expansion velocity as early demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heating Element Manufacturing | Vertical control over copper coil and induction core production insulates margins from commodity volatility. |
| IoT-Enabled Predictive Maintenance Platform | Smart induction ranges with temperature logging integrate into enterprise kitchen management systems. |
| California Specification Capture Program | Title 24 compliance relationships lock in new construction procurement before competitors establish presence. |
| Ghost Kitchen Equipment Leasing Partnership | Centralized procurement by delivery-focused operators aggregates demand and reduces sales cycle friction. |
| Culinary School Curriculum Integration | Training institution partnerships shape future chef preferences that translate into franchise procurement standards. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for commercial electric restaurant ranges. Primary fieldwork engaged equipment procurement directors at hospitality groups, NSF certification specialists, dealer network managers, and utility demand-side management program administrators. Secondary validation drew from US Department of Energy appliance standards filings, California Energy Commission Title 24 documentation, NSF International certification databases, and North American foodservice construction permit records. Bottom-up equipment shipment analysis and top-down foodservice facility investment flows were triangulated to anchor volume estimates.
Segment-weighting across product type, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. Floor range, induction range, countertop, and combination configurations were modeled separately with distinct replacement cycle assumptions. Restaurant, caterer, café, and food truck applications carried differential electrification mandate exposure. CAGRs were derived from regression against regulatory deadline schedules and construction permit velocity. Forecast inputs included municipal gas connection moratoria adoption curves and utility rebate program funding trajectories.
Several conditions sit outside the modeled scope, including potential federal preemption of state electrification codes, breakthrough solid-state cooking technology disruption, and sustained copper price spikes exceeding historical volatility bands. Forecasts reflect documented assumptions about regulatory timeline adherence and construction labor availability. Practitioners should monitor municipal ordinance adoption velocity and semiconductor foundry capacity allocation for early signals of demand or supply inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Food Trays and Bowls Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Commercial Microwaves Market