
 Countertop Pressure Fryer Market | 2026-2036
Countertop Pressure Fryer Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Pressure Fryer Market Outlook
Food trucks and compact commercial kitchens is realigning demand toward smaller-capacity units with faster recovery times. Winston leverages its engineering heritage in pressure frying to sustain premium positioning among chain accounts. Henny Penny Corporation anchors the high-volume segment through institutional channel control. Pitco Frialator, Inc. competes on modularity, allowing operators to swap heating elements without technician calls.
A countertop pressure fryer seals food in a pressurized cooking chamber typically operating at 12 psi, using moist heat to accelerate cook times while reducing oil absorption versus conventional open frying. Electric fryers dominate urban installations where venting constraints block gas equipment, while gas fryers retain cost advantages in regions with lower natural gas tariffs. Digital fryers with programmable menus command margin pools in chain deployments, whereas multi-function units integrating air-frying modes attract independent operators seeking equipment versatility.
NSF International standards govern commercial kitchen equipment sanitation in the United States, while UL 197 certification addresses electrical safety for countertop appliances. The EU's Ecodesign Directive and REACH chemical compliance shape material selections for units sold across Europe. Stakeholders must monitor evolving energy efficiency thresholds and oil filtration automation requirements as labor scarcity pushes operators toward self-managing fryer systems.
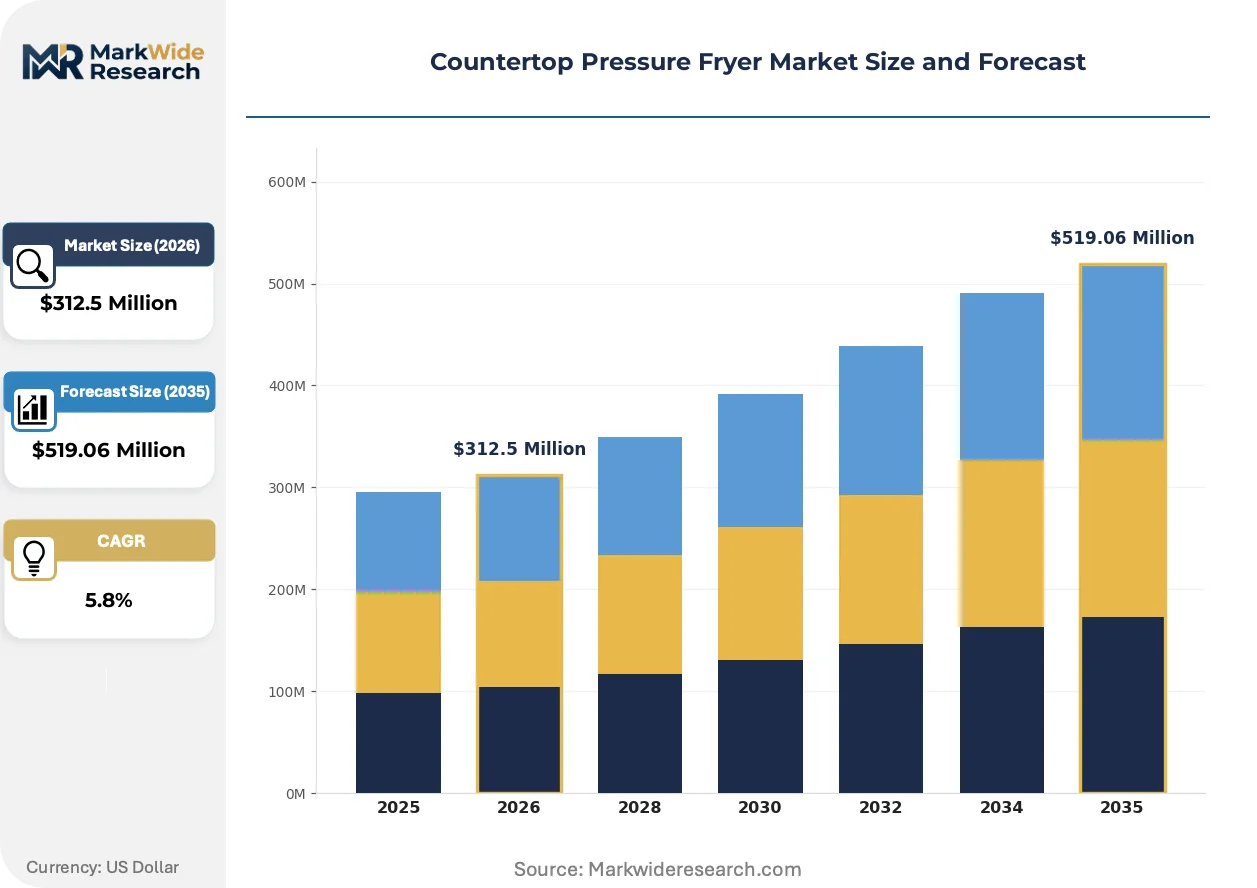
Market Dynamics
Quick-service restaurant chains are compressing kitchen footprints to accommodate drive-thru expansion and ghost kitchen formats, forcing equipment manufacturers to prioritize thermal density and ventless operation in countertop pressure fryer design.
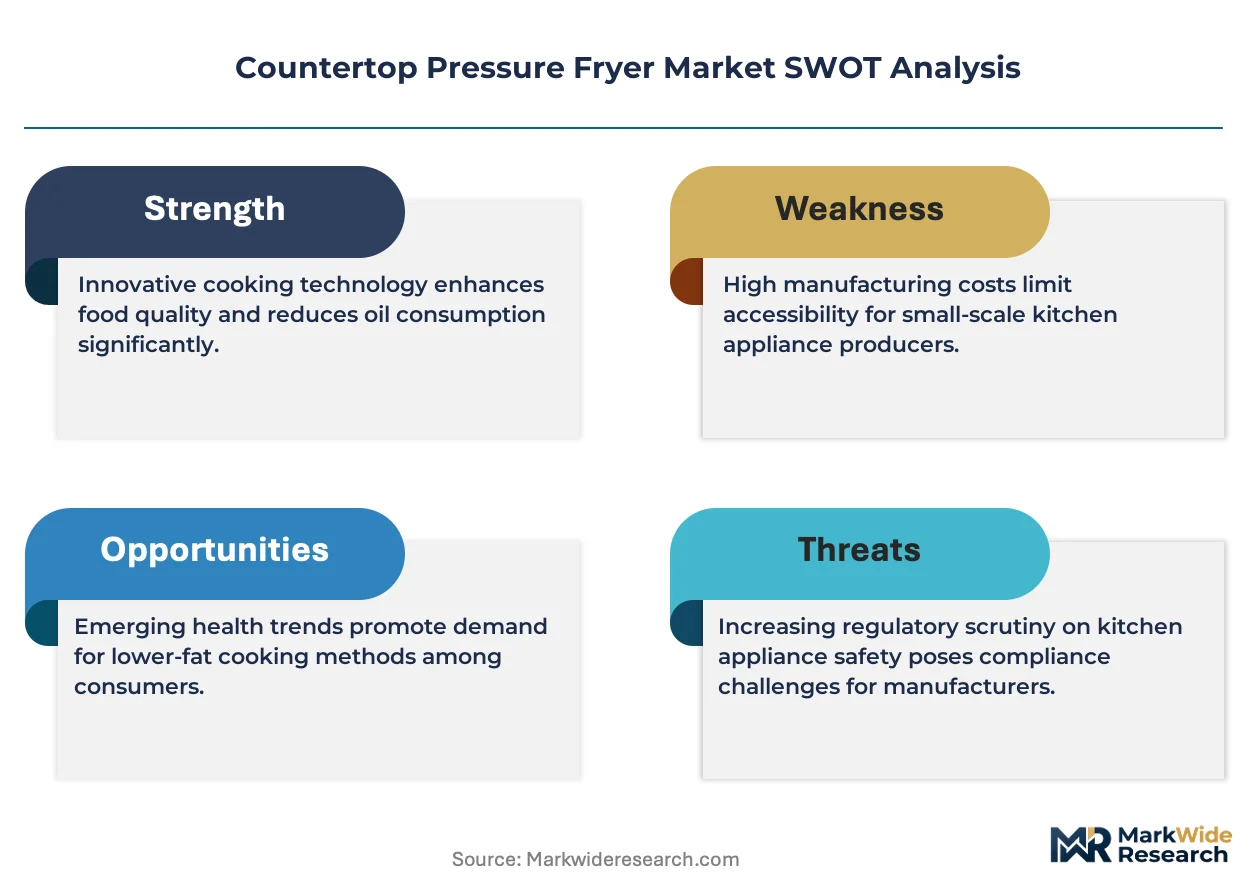
Growth Catalysts
- UL 197 electrical safety certification:Streamlined approval pathways for ventless electric models accelerate deployment in urban US food halls where traditional hood systems are cost-prohibitive.
- Cloud kitchen proliferation:Delivery-optimized ghost kitchens in Tier-2 Chinese cities demand compact, high-throughput frying equipment with minimal installation overhead.
- Air-frying mode integration:Multi-function units combining pressure frying with convection air circulation attract independent operators seeking menu versatility without second equipment purchases.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet metal price swings compress OEM margins and complicate long-term contract pricing with chain accounts.
- Gas connection infrastructure gaps:Urban core buildings lacking natural gas risers lock operators into electric models despite higher operating costs in low-electricity-tariff regions.
- REACH chemical compliance:EU Ecodesign Directive material restrictions on certain non-stick coatings force reformulation cycles that extend product development timelines.
Strategic Opportunities
- Food truck electrification:Battery-powered mobile kitchens in Germany and the United States create demand for low-amperage electric pressure fryers with rapid recovery profiles.
- ISO 22000 food safety certification:Premium positioning through third-party hygiene auditing appeals to hospital and university cafeteria procurement committees.
- Oil filtration automation:Self-managing fryer systems with integrated filtration and top-off capabilities address labor scarcity in high-turnover quick-service environments.
Industry Challenges
- NSF field certification delays:Third-party sanitation validation bottlenecks extend time-to-market for new product launches by 8-14 weeks.
- Legacy POS integration:Digital fryer menu programming requires API development work with fragmented restaurant management software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Pressure Fryer Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Fryers, Gas Fryers, Multi-Function Fryers, Digital Fryers End User: Restaurants, Catering Services, Food Trucks, Households Capacity: Small, Medium, Large, Extra Large Feature: Adjustable Temperature, Safety Lock, Timer, Non-Stick Interior |
| Companies Covered | Winston, Pitco Frialator, Inc., Emeril, Frymaster, BKI Worldwide, Ninja, Henny Penny Corporation, Electrolux, NuWave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Pressure Fryer Market Strategic Shifts
Equipment intelligence and energy accountability are redefining competitive differentiation in countertop pressure frying, with operators now prioritizing connected diagnostics and utility transparency alongside raw throughput metrics.
Automated oil management systems are expanding into chain deployments as standard configuration rather than premium add-on. These systems monitor degradation chemistry, trigger filtration cycles, and automate replenishment to maintain consistent product quality. Quick-service operators in the United States are adopting these capabilities fastest, recognizing that labor reduction in fryer tending justifies 15-20% equipment cost premiums.
REACH chemical restrictions and the EU Ecodesign Directive are forcing material transitions in heating element coatings and chamber seals. Manufacturers serving European markets must now validate alternative formulations that eliminate perfluorinated compounds while maintaining release properties and thermal durability. German commercial kitchen distributors report 6-month qualification cycles for redesigned components, compressing effective product lifecycles.
Lease-to-own financing through equipment finance companies is displacing traditional capital purchase models among independent restaurant operators. Third-party financiers assume residual value risk and bundle maintenance contracts, lowering entry barriers for digital fryer technology. This shift concentrates most visibly in US metropolitan markets where cloud kitchen startups prioritize operational flexibility over balance-sheet ownership.
Countertop Pressure Fryer Market Segmentation
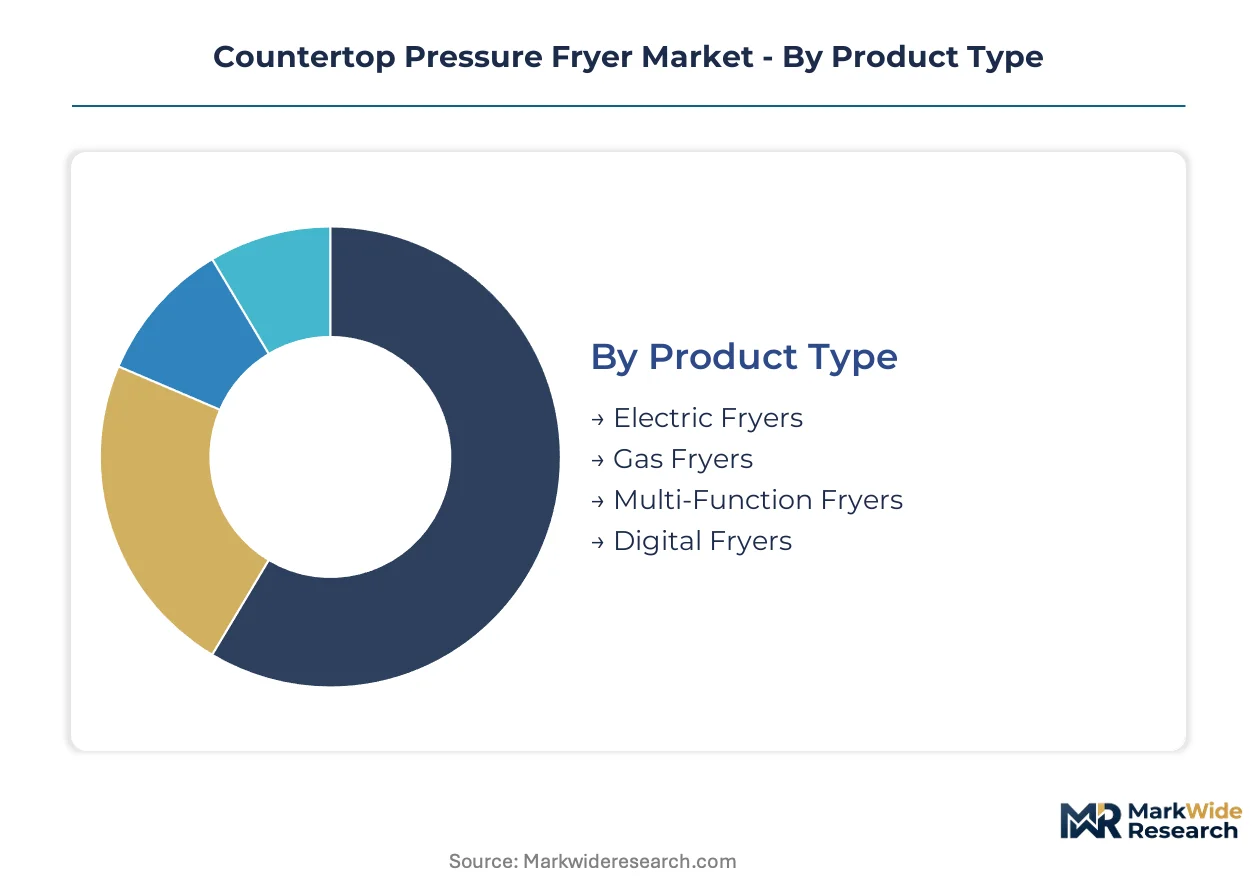
Countertop pressure fryer procurement patterns diverge sharply across installation constraints, menu complexity, and labor availability. Equipment specification directly shapes oil turnover rates, energy recovery profiles, and compliance pathways in commercial kitchens.
Product Type:
Supply concentration tilts toward electric configurations as urban venting restrictions proliferate across dense metropolitan cores.
- Electric Fryers:Heating elements rated 208-240V achieve pressure seal in 90-120 seconds. Demand clusters in US food halls and German ghost kitchens where hood infrastructure is unavailable or cost-prohibitive; UL 197 certification streamlines deployment timelines.
- Gas Fryers:Natural gas burners deliver faster recovery between batches through direct flame impingement. Operators in Texas and Louisiana with sub-$0.08/kWh equivalent gas tariffs favor these units despite installation complexity; regional utility pricing determines adoption thresholds.
- Multi-Function Fryers:Pressure-convection hybrid chambers toggle between moist-heat sealing and dry-air circulation. Independent pizzerias and sandwich shops in Chicago and Manchester deploy these for menu breadth without footprint expansion.
- Digital Fryers:Programmable controllers store 50+ menu profiles with HACCP logging. Quick-service chains in California and New York mandate these for franchise consistency; API integration with POS systems remains a procurement checkpoint.
Electric fryers absorb the bulk of installed capacity; multi-function fryers are expanding most quickly.
End User:
Application scale dictates automation depth and filtration specification across customer tiers.
- Restaurants:Full-service and fast-casual operators prioritize throughput per square foot. Chains in Atlanta and Phoenix specify automated oil management to reduce labor touchpoints; filtration frequency correlates with table-turn targets.
- Catering Services:Mobile banquet operations demand rapid cooldown and transport safety locks. Off-premise specialists in Florida and Spain select compact 12-psi units with 30-minute pressure release cycles; event volume volatility shapes rental-versus-purchase decisions.
- Food Trucks:Battery-constrained mobile kitchens require sub-30A draw with inverter compatibility. Electrified fleets in Berlin and Austin drive demand for low-amperage recovery systems; generator noise ordinances accelerate electric transition.
- Households:Consumer-grade 6-8 psi chambers target home enthusiasts and small-batch producers. Direct-to-consumer channels in Japan and South Korea emphasize compact storage dimensions; safety certification exceeds commercial scrutiny in liability-sensitive markets.
Restaurant chains command the dominant share of unit volume; food truck electrification is climbing the fastest.
Capacity:
Batch size selection tracks kitchen throughput requirements and peak demand curve sharpness.
- Small:8-12 lb oil capacity suits single-item specialty operations. Boutique fried chicken shops in Seoul and Nashville optimize for 4-6 minute cycle times; limited menu depth reduces equipment redundancy.
- Medium:15-20 lb chambers balance recovery speed with footprint efficiency. Mid-scale caterers in Ontario and Victoria standardize on this tier for 50-150 cover events; thermal mass sustains quality across staggered service waves.
- Large:25-35 lb systems serve high-volume lunch rushes. University cafeterias in Ohio and hospital foodservice in Massachusetts specify these for 300+ daily transactions; automated filtration becomes standard above this threshold.
- Extra Large:40+ lb configurations target central commissaries and stadium concessions. Regional quick-service hubs in Dallas and Manchester deploy these with conveyor integration; capital intensity restricts adoption to multi-unit operators.
Medium capacity carries the highest shipment volumes; extra large units are gaining share fastest in commissary consolidation.
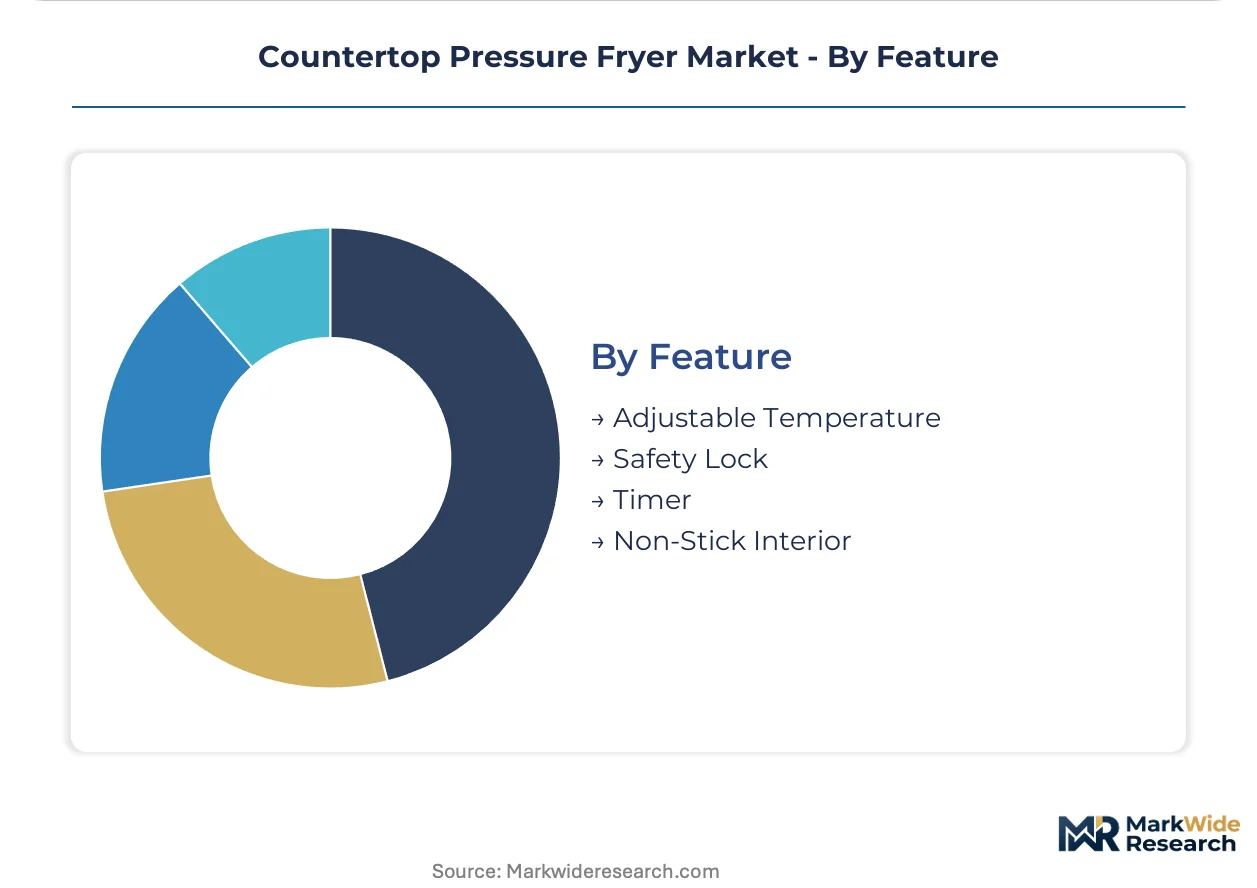
Feature:
Specification bundling reflects labor cost pressure and regulatory compliance layering.
- Adjustable Temperature:250°F-375°F range control enables protein-specific profiles. Fish-and-chip operators in Boston and Sydney require precise low-temperature starting points; thermal flexibility reduces cross-flavor contamination.
- Safety Lock:Pressure-sealed chamber interlocks prevent mid-cycle opening. EU Ecodesign Directive mandates these for commercial certification; German and French distributors report zero inventory of non-compliant stock.
- Timer:Digital countdown with auto-pressure release eliminates operator attention dependency. Cloud kitchen startups in Shenzhen and Miami prioritize these for unattended operation; labor scarcity justifies 10-15% feature premiums.
- Non-Stick Interior:Ceramic and diamond-like carbon coatings reduce oil adhesion and cleaning labor. REACH chemical restrictions are forcing ceramic substitution in European-bound units; qualification cycles extend supplier lead times.
Safety lock mechanisms are universal in commercial-spec equipment; timer automation is penetrating fastest in labor-constrained markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Dubai are accelerating equipment import flows for cloud kitchen infrastructure. These zones concentrate demand for ventless electric pressure fryers among delivery-optimized operators.
United States
Drive-thru expansion and ghost kitchen proliferation in Atlanta and Phoenix are compressing kitchen footprints. UL 197 certification streamlines deployment in urban food halls where traditional hood systems face cost barriers. Texas and Louisiana operators favor gas models where utility tariffs fall below $0.08/kWh equivalent.
Germany
Battery-powered food truck electrification in Berlin drives demand for low-amperage electric units with rapid recovery profiles. REACH chemical compliance and EU Ecodesign Directive requirements force 6-month qualification cycles for redesigned heating element coatings. Commercial kitchen distributors in Munich report zero inventory of non-safety-lock-compliant stock.
China
Cloud kitchen startups in Tier-2 cities like Chengdu and Hangzhou prioritize compact, high-throughput frying equipment with minimal installation overhead. GB standards govern electrical safety for commercial kitchen appliances. The Yangtze River Delta cluster concentrates manufacturing capacity for export-oriented OEMs.
Japan
Consumer-grade 6-8 psi chambers target home enthusiasts through direct-to-consumer channels in Tokyo and Osaka. METI energy efficiency guidelines shape product development priorities for domestic-market units. JIS standards certification exceeds commercial scrutiny in liability-sensitive residential segments.
South Korea
Boutique fried chicken shops in Seoul optimize for 4-6 minute cycle times using small-capacity 8-12 lb oil systems. MFDS food safety regulations govern commercial kitchen equipment sanitation. The Seoul Capital Area concentrates independent operator demand for multi-function pressure-convection hybrid units.
Countertop Pressure Fryer Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium chain accounts favoring engineered solutions while independent operators prioritize cost accessibility. The vendor base organizes into three tiers: heritage engineering houses, diversified foodservice conglomerates, and agile Asian fabricators. Consolidation pressure is mounting as scale advantages in automated oil management systems widen performance gaps. Strategic moves center on API integration capabilities and lease-to-own financing partnerships that lower entry barriers for digital fryer technology.
Within the heritage engineering tier, Winston and Henny Penny Corporation exemplify premium positioning through pressure frying specialization and institutional channel control respectively. Pitco Frialator, Inc. sits within the modularity-focused archetype, occupying a position where serviceability design reduces operator downtime. These three anchors represent distinct competitive vectors: engineering pedigree, high-volume reliability, and field-service efficiency.
| Leading Market Players |
|---|
| Winston |
| Pitco Frialator, Inc. |
| Emeril |
| Frymaster |
| BKI Worldwide |
| Ninja |
| Henny Penny Corporation |
| Electrolux |
| NuWave |
| Others |
Value Chain & Pricing Dynamics
REACH chemical compliance mandates in Europe are forcing stainless steel component reformulation cycles that compress OEM margins and extend supplier qualification timelines. Equipment manufacturers must absorb these certification-driven cost escalations while maintaining chain account pricing discipline.
Pricing Analysis
Short-lead-time premiums dominate transaction economics, with US food hall operators paying 12-18% markups for UL 197-certified ventless electric units against 14-week standard delivery windows. Three-tier pricing structure across premium, standard, and economy levels segments by automation depth and certification bundling. Pricing pressure stems from Grade 304 stainless input volatility and compressed development cycles. Independent restaurant operators exhibit highest price sensitivity, while quick-service chains prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Stainless steel sheet metal supply rests on mills in China, Germany, and South Korea, with heating element coatings concentrated among Japanese and German specialty chemical producers. Control systems draw from Taiwanese semiconductor fabricators and Shenzhen PCB assemblers. Single-source vulnerability in non-stick ceramic coating formulations creates procurement risk given REACH transition timelines. Distribution runs through commercial kitchen equipment distributors in Dallas, Munich, and Shanghai, with lease-to-own financiers assuming residual value risk in US metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NSF International certification requirements create a structural moat that elevates compliant incumbents above price-competitive imports, transforming this market into a cost-of-compliance story where validation investment separates sustainable players from margin-erosion casualties.
For Market Incumbents: Anchor premium positioning through automated oil management system integration that justifies 15-20% equipment cost premiums against emerging Asian fabricators. Deepen backward integration into heating element coating production to insulate margins from REACH-driven supplier delays. Defend chain account relationships through API development work with fragmented POS platforms. For New Entrants and Emerging Players: Capture battery-powered food truck electrification demand in Berlin and Austin with low-amperage electric units optimized for inverter compatibility. Target independent pizzerias and sandwich shops in secondary US and UK cities with pressure-convection hybrid chambers enabling menu breadth without footprint expansion. Deploy lease-to-own financing partnerships to lower entry barriers for digital fryer technology adoption. For Investors and Strategic Acquirers: Re-rating potential sits with heritage engineering houses possessing UL 197 and NSF certification portfolios given consolidation pressure from scale advantages in automated oil management systems. Long-term viability favors vendors with API integration capabilities and cloud kitchen channel penetration. Monitor food truck electrification policy acceleration in Germany and the United States as inflection signal for low-amperage electric segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Oil Management Integration | Henny Penny and Winston capture labor-scarcity premiums through self-managing fryer system deployment. |
| API Development for POS Integration | Digital fryer manufacturers reduce franchisee friction through programmable menu profile synchronization. |
| Lease-to-Own Financing Partnerships | Equipment finance companies assume residual value risk, accelerating cloud kitchen startup equipment adoption. |
| REACH-Compliant Coating Qualification | German and French distributors eliminate non-compliant inventory, forcing 6-month supplier validation cycles. |
| Food Truck Electrification Product Line | Berlin and Austin fleet operators drive demand for sub-30A draw pressure fryers with rapid recovery profiles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving quick-service chain procurement directors, commercial kitchen equipment distributors, food truck fleet operators, NSF International certification specialists, and stainless steel component suppliers. Bottom-up shipment data from OEM bill-of-materials analysis combined with top-down foodservice equipment spending estimates across the United States, Germany, and China.
Data-stream reconciliation across electric and gas configuration splits, capacity tier distributions, and end-user segmentation dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, restaurant industry capital expenditure surveys, and cloud kitchen infrastructure deployment tracking. Energy tariff differentials and venting regulation enforcement intensity served as regional adoption modifiers.
The model holds under stable stainless steel pricing and certification timeline continuity; deviation in REACH chemical restriction acceleration or UL 197 approval pathway changes would shift equipment availability and pricing trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Egypt Food Service Market
Food Service
United States Food Truck Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Integrated Stove Market
Food Service
Vietnam Online Food Delivery Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Full-Service Restaurants Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Chained Consumer Foodservice Market
Food Service
Haute Cuisine Market
Food Service
Ship Catering Service Market
Food Service
Snack Subscription Box Service Market
Food Service
Quick-Service Restaurants Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Food Contract Manufacturing Market