
 South America Free from Food Market | 2026-2036
South America Free from Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Free from Food Market Analytics
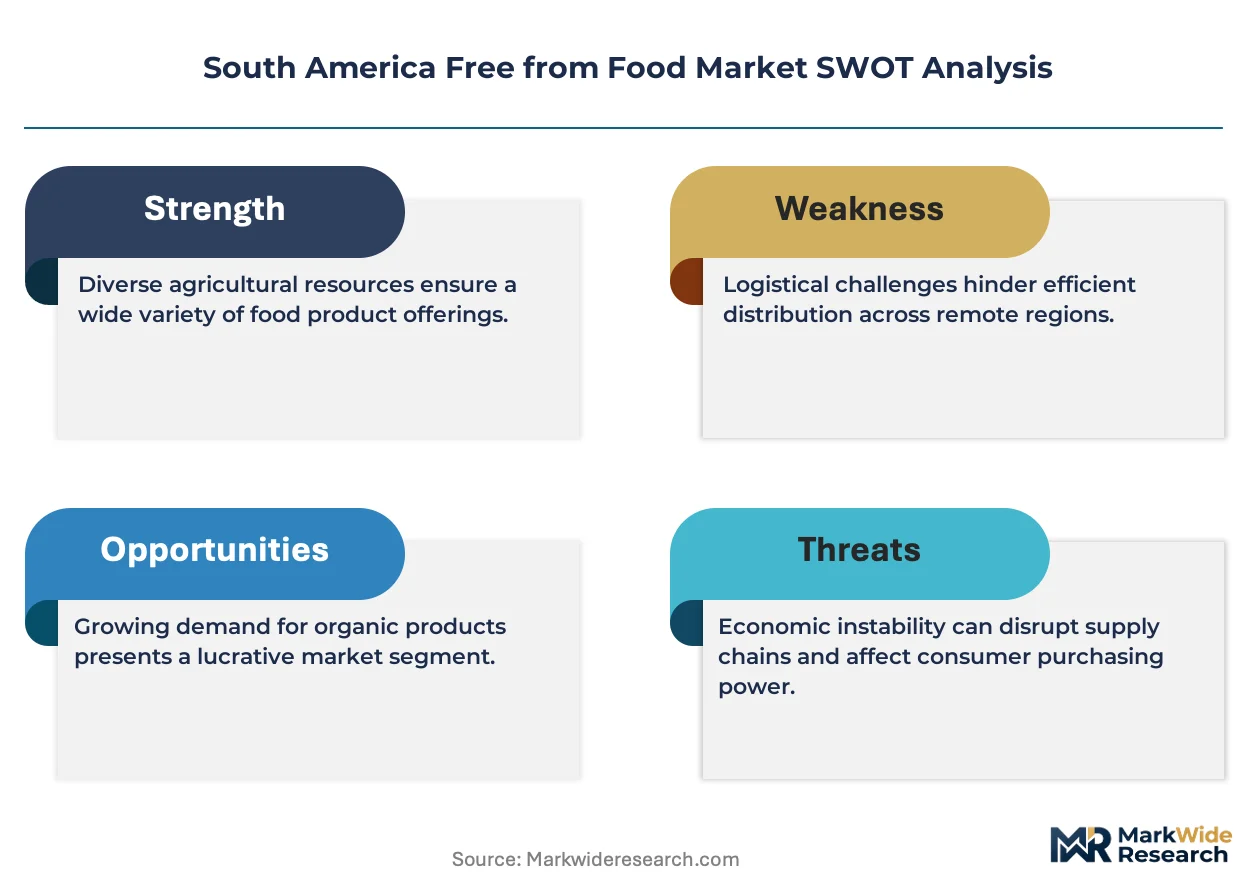
Supermarket private-label free-from aisles is reshaping how South American consumers discover allergen-free alternatives. Dr Schar AG / SPA leverages its dedicated gluten-free manufacturing infrastructure to sustain shelf presence across Brazilian and Argentine retail networks. Danone SA anchors the dairy-free segment through specialized plant-based fermentation platforms. Molinos Río de la Plata competes on localized ingredient sourcing and price positioning in mass-market channels.
Free from food denotes formulated products excluding specific allergens or ingredients through controlled substitution, achieving functional parity via modified starches, hydrocolloids, or protein isolates while maintaining sensory and nutritional benchmarks. Gluten-free products lead volume due to established celiac diagnosis rates and retail penetration, though dairy-free alternatives register the fastest structural expansion driven by flexitarian migration and oat-based formulation advances. Sugar-free SKUs occupy concentrated margin pools through pharmacy and diabetic-specialist channels where premium pricing endures.
ANVISA mandates precautionary allergen labeling that expands compliance burdens for importers and domestic manufacturers alike. Brazil's INMETRO certification and Argentina's food code provisions create divergent technical barriers that segment production runs by destination market. Stakeholders must monitor evolving Mercosur harmonization talks and decide whether to consolidate formulations or maintain country-specific recipes.
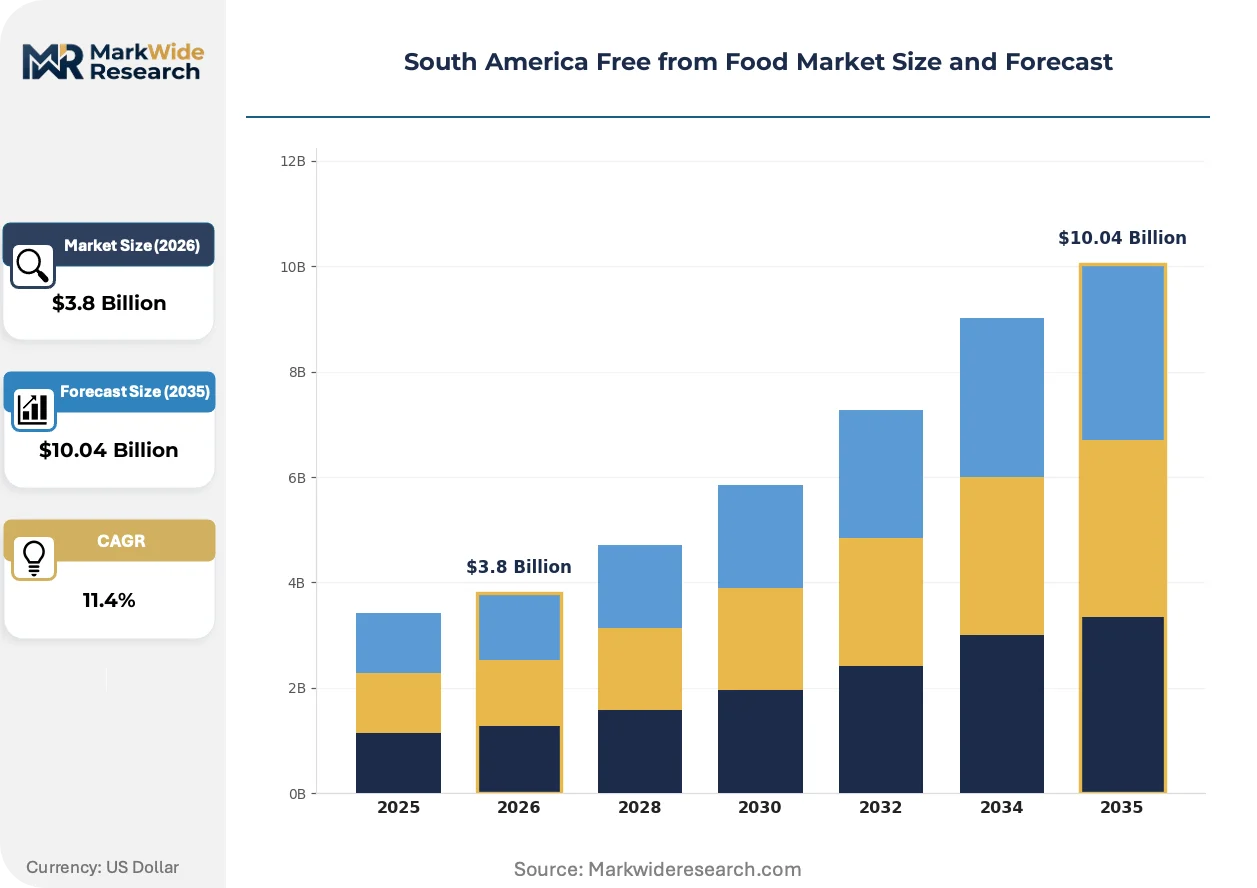
Market Dynamics
ANVISA's precautionary allergen labeling mandate is compressing formulation cycles across Brazilian and Argentine manufacturing facilities, forcing simultaneous reformulation of legacy SKUs and new product development pipelines.
Growth Catalysts
- ANVISA Labeling Mandate:Brazil's expanded precautionary allergen disclosure rules compel manufacturers to develop certified clean-label alternatives, creating compliant product lines that command shelf space in Carrefour and GPA networks.
- Oat Protein Isolation:Advances in enzymatic oat processing yield functional dairy substitutes with improved mouthfeel, accelerating flexitarian adoption in São Paulo's metropolitan corridor.
- Celiac Diagnosis Infrastructure:Expanded testing capacity across Argentina's public health system builds addressable patient pools for gluten-free pasta and baked goods in Buenos Aires and Córdoba provinces.
Market Restraints
- Modified Starch Import Dependence:Functional starch inputs for texture replication concentrate in Thai and European supply nodes, exposing Brazilian formulators to currency-driven cost volatility.
- INMETRO Certification Timelines:Brazil's conformity assessment procedures extend product launch windows by 8-14 months versus conventional food categories, trapping working capital in pipeline inventory.
- Price Sensitivity Thresholds:Mass-market Brazilian consumers exhibit limited willingness-to-pay premiums exceeding 35% for allergen-free alternatives versus standard formulations, compressing margin recovery.
Strategic Opportunities
- Colombian Market Entry:Underpenetrated retail infrastructure in Bogotá and Medellín offers first-mover positioning before domestic competitors establish gluten-free manufacturing capacity.
- Pharmacy Channel Expansion:Sugar-free diabetic-specialist SKUs migrate from hospital procurement into retail pharmacy chains, accessing reimbursed purchasing pools.
- Mercosur Harmonization:Pending regulatory alignment talks could collapse country-specific formulation requirements, enabling single-production-run economics across Brazil, Argentina, Paraguay, and Uruguay.
Industry Challenges
- Food Technologist Scarcity:Formulation expertise in hydrocolloid stabilization and protein denaturation control concentrates in São Paulo and Buenos Aires, constraining facility expansion into secondary Brazilian states.
- Dual Certification Burden:Simultaneous INMETRO and Argentine food code compliance requires parallel testing protocols, duplicating analytical costs for cross-border suppliers.
- Legacy Equipment Retrofit Costs:Gluten-free dedicated manufacturing lines demand segregated milling and extrusion infrastructure, raising capital intensity for mid-scale Argentine millers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Free from Food Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Dairy-Free, Nut-Free, Sugar-Free End User: Health-Conscious Consumers, Diabetics, Celiac Patients, Athletes Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Eco-Friendly, Recyclable, Resealable, Single-Serve |
| Companies Covered | Brazi Bites, Dr Schar AG / SPA, Danone SA, Bob's Red Mill Natural Foods, Jussara SA, Lactalis, Raisio PLC, Hero Group AG, Molinos Río de la Plata, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Free from Food Market Evolving Landscape
Controlled fermentation platforms and precision protein extraction are compressing the sensory gap between allergen-free substitutes and conventional formulations, reshaping competitive requirements across South American retail channels.
Enzymatic treatment of oat and chickpea proteins is collapsing the functional performance differential with dairy-derived casein and whey. Brazilian plant-based yogurt manufacturers adopt these isolates at commercial scale. The technology compresses ingredient cost structures while expanding flexitarian addressable markets beyond diagnosed allergen sufferers.
ANVISA's updated allergen cross-contamination disclosure rules force precautionary labeling on shared-facility production. Brazilian importers and domestic manufacturers reconfigure supply chains to segregate allergen-free lines. The regulation most acutely affects imported European baked goods, triggering local production investments to avoid warning-label penalties.
Pharmacy procurement managers in São Paulo and Rio de Janeiro unbundle sugar-free diabetic nutrition from hospital formulary contracts into retail channel distribution. Specialist retailers replace institutional purchasing as the dominant volume pathway. This shift concentrates margin capture in certified pharmacy networks while compressing traditional grocery penetration for therapeutic nutrition SKUs.
South America Free from Food Market Segmentation
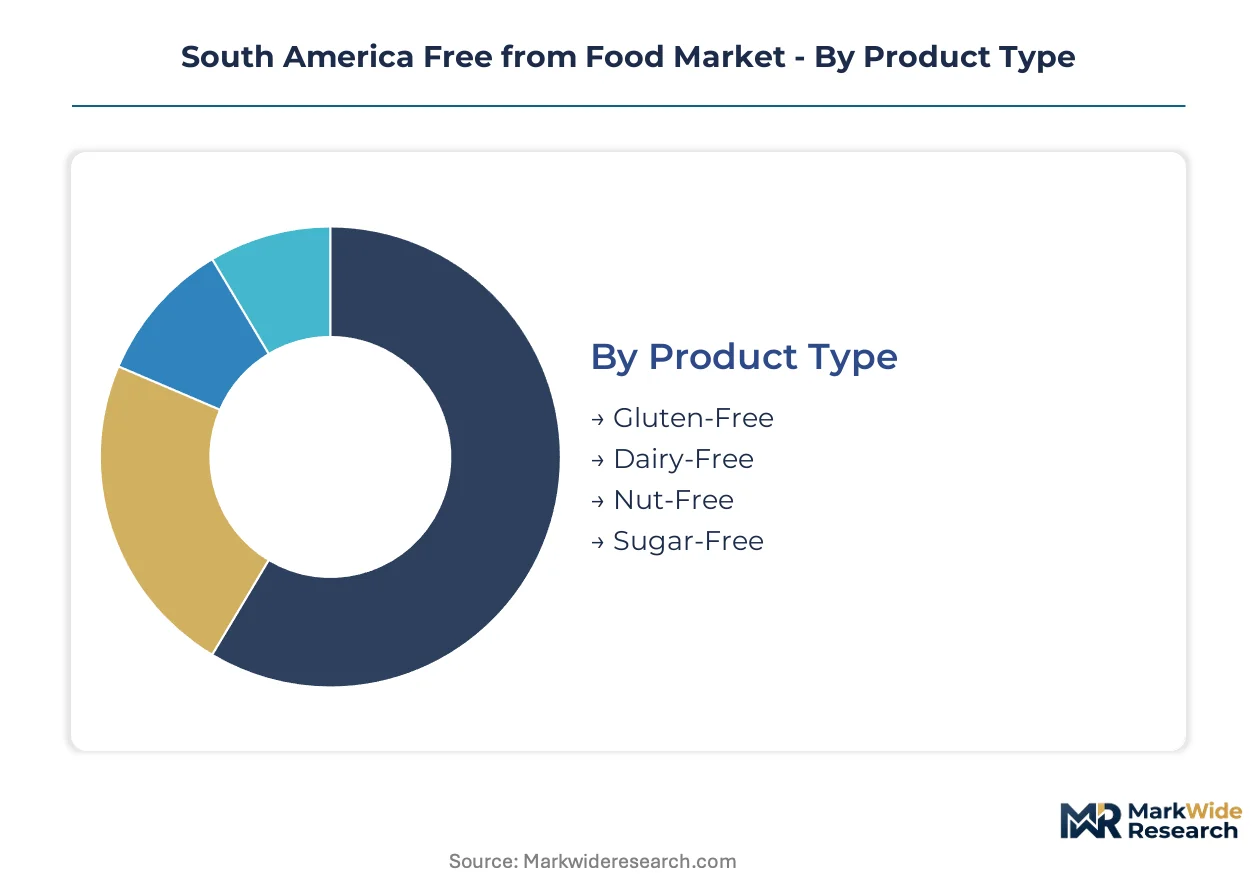
Segmentation in South America's free-from food market reveals distinct velocity profiles across product categories. Gluten-free SKUs rotate fastest through São Paulo's retail networks while sugar-free lines exhibit slower inventory turns but higher margin retention in pharmacy channels.
Product Type:
Reformulation cycle times vary dramatically across allergen categories, with dairy-free platforms iterating fastest on protein isolation technologies while nut-free lines face longer stability testing protocols.
- Gluten-Free:Formulated products exclude wheat, barley, and rye proteins through modified starch and hydrocolloid systems that replicate viscoelastic dough properties. Brazilian celiac associations in São Paulo and Rio de Janeiro drive concentrated demand through certified retail partnerships with Carrefour and GPA networks. ANVISA's precautionary labeling rules accelerate domestic manufacturing investments to avoid cross-contamination warnings on imported European baked goods.
- Dairy-Free:Plant-based alternatives leverage enzymatically processed oat and chickpea protein isolates to achieve functional parity with dairy-derived casein. São Paulo's flexitarian corridor generates rapid SKU turnover as Brazilian manufacturers adopt precision fermentation platforms at commercial scale. Oat-based yogurt formulations compress cost structures while expanding addressable markets beyond diagnosed lactose intolerance.
- Nut-Free:Segregated production lines eliminate peanut and tree nut proteins through dedicated milling infrastructure and supplier certification programs.
- Sugar-Free:Diabetic-specialist formulations concentrate in pharmacy procurement channels across Brazil's southeast corridor with premium pricing endurance.
Gluten-Free dominates installed base. Dairy-Free is where expansion concentrates.
End User:
Customer archetypes stratify sharply by price elasticity and channel preference, with diagnosed medical conditions commanding reimbursement pathways while lifestyle adopters drive volume through conventional retail.
- Health-Conscious Consumers:Flexitarian households in Brazil's metropolitan corridors purchase free-from products as preventive wellness investments rather than medical necessities. São Paulo's middle-class segments exhibit willingness-to-pay premiums up to 35% for clean-label positioning. These buyers rotate through supermarket private-label aisles and online subscription platforms with higher frequency than diagnosed patient groups.
- Diabetics:Therapeutic nutrition requirements create concentrated demand pools in pharmacy and hospital procurement channels across Rio de Janeiro. Sugar-free SKUs access reimbursed purchasing pools through ANVISA-registered diabetic specialty formulations. This segment exhibits lower price sensitivity and longer purchase cycles tied to medical consultation schedules.
- Celiac Patients:Argentina's expanded public health testing infrastructure builds diagnosed patient pools in Buenos Aires and Córdoba provinces with strict gluten-free adherence requirements.
- Athletes:Performance-oriented protein isolates and recovery formulations concentrate in specialty sports nutrition retail across Brazilian urban centers.
Health-Conscious Consumers generate highest absolute volume. Diabetics capture steepest margin expansion.
Distribution Channel:
Channel economics diverge on working capital intensity and certification requirements, with digital platforms compressing launch timelines while physical retail demands longer INMETRO compliance windows.
- Online Retail:E-commerce platforms enable direct-to-consumer distribution of imported European free-from brands without conventional retail slotting fees. Brazilian marketplace operators Mercado Libre and Amazon Brazil accelerate SKU proliferation for niche allergen-free categories. Digital channels bypass INMETRO certification delays that trap inventory in conventional retail pipelines.
- Supermarkets:Dedicated free-from aisles in Carrefour and GPA networks reshape consumer discovery patterns across São Paulo's metropolitan corridor. Brazilian chains expand shelf space for certified clean-label alternatives compliant with ANVISA's updated allergen disclosure mandates. Private-label penetration concentrates margin compression on national brand suppliers.
- Health Food Stores:Specialty retailers in Buenos Aires and Córdoba curate premium-positioned organic and non-GMO verified free-from assortments.
- Specialty Shops:Celiac-specific boutiques and diabetic nutrition centers provide consultation-driven purchasing in Argentina's provincial capitals.
Supermarkets anchor installed base. Online Retail is gaining share fastest.
Packaging Type:
Packaging specifications stratify by channel destination and consumer occasion, with pharmacy channels demanding extended shelf-life formats while convenience retail drives single-serve innovation.
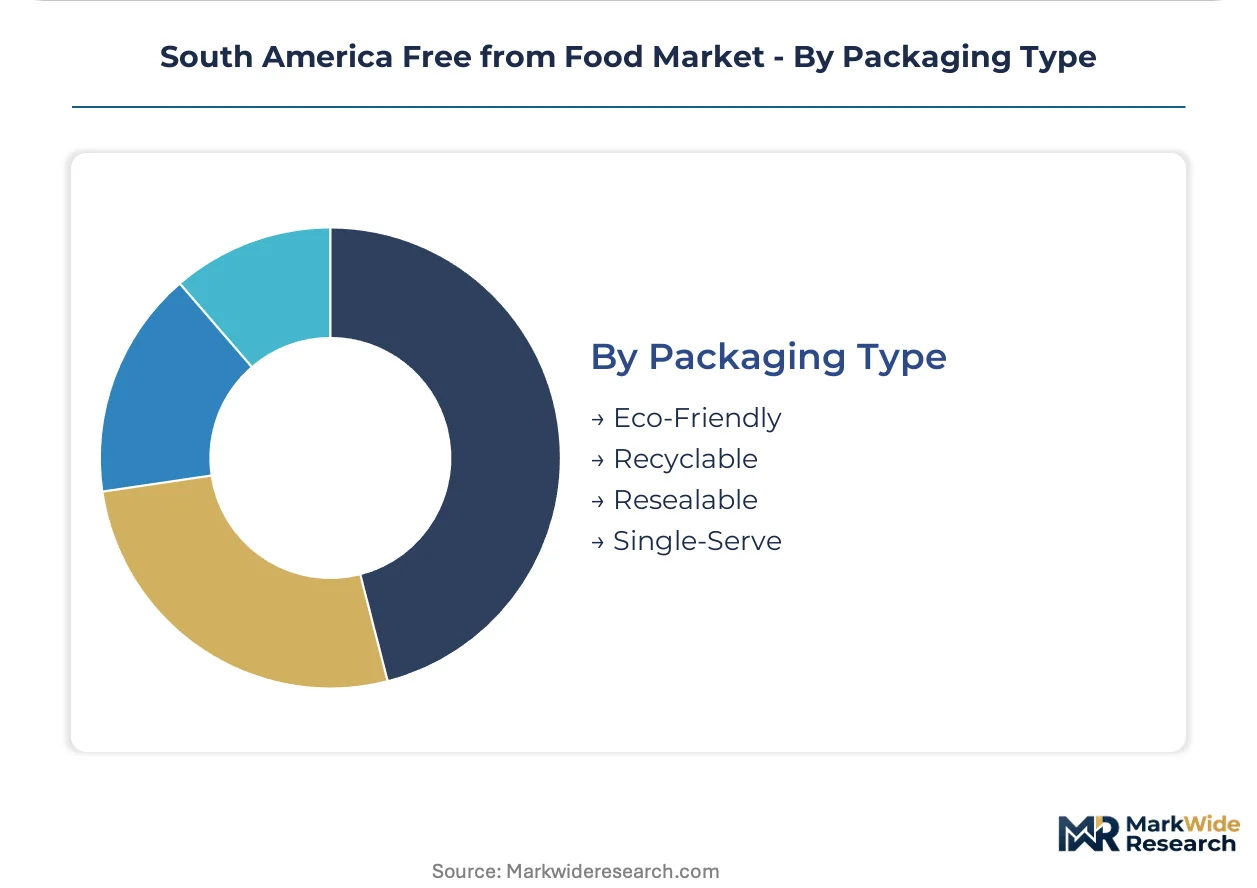
- Eco-Friendly:Compostable and biodegradable materials align with Brazilian sustainability preferences in São Paulo's premium supermarket segments. Suppliers face cost premiums of 15-25% versus conventional packaging but access shelf space in GPA's dedicated organic aisles. ANVISA's material safety assessments extend approval timelines for novel biodegradable films.
- Resealable:Zip-lock and screw-cap formats preserve product integrity across multiple consumption occasions in household-sized gluten-free and dairy-free SKUs. Argentine manufacturers prioritize these formats for Buenos Aires metropolitan distribution where pantry stocking patterns dominate. Resealable packaging commands 12-18% price premiums over standard formats.
- Recyclable:Mono-material polyethylene and polypropylene constructions simplify post-consumer waste streams for Brazilian municipal collection systems.
- Single-Serve:Portion-controlled packaging targets on-the-go consumption in Rio de Janeiro's convenience retail and airport channels.
Resealable dominates installed base. Eco-Friendly is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing premiums exceeding Argentine equivalents by 25-35% across certified gluten-free SKUs, while Colombian shelf prices trail both markets due to import tariff structures and nascent local manufacturing capacity.
Brazil
São Paulo's metropolitan corridor generates concentrated demand for dairy-free oat yogurt and certified gluten-free baked goods through Carrefour and GPA network expansion. ANVISA's precautionary allergen labeling mandate compels domestic reformulation investments to avoid cross-contamination warnings on European imports. Rio de Janeiro's pharmacy procurement channels anchor sugar-free diabetic nutrition distribution with reimbursed purchasing pools.
Argentina
Buenos Aires and Córdoba provinces build diagnosed celiac patient pools through expanded public health testing infrastructure, driving volume for gluten-free pasta and bread alternatives. The national food code provisions create technical barriers that segment production runs from Brazilian export formulations. Molinos Río de la Plata leverages localized ingredient sourcing to compete on price positioning in mass-market channels across the Pampas agricultural belt.
Colombia
Bogotá and Medellín present underpenetrated retail infrastructure for dedicated free-from aisles, offering first-mover positioning before domestic competitors establish gluten-free manufacturing capacity. The country's national food regulator maintains import certification requirements that extend product launch timelines versus Andean Community neighbors. Cali's emerging health-conscious consumer segments drive early adoption through specialty pharmacy and online retail channels.
Chile
Santiago's metropolitan zone concentrates demand for premium-positioned organic and non-GMO verified free-from assortments through specialized health food retailers. The national economic development agency promotes clean-label food processing investments through targeted incentive programs. Valparaíso's port infrastructure facilitates ingredient imports for modified starches and hydrocolloids that supply regional formulators.
Uruguay
Montevideo anchors Mercosur harmonization discussions that could collapse country-specific formulation requirements across member states. The country's compact geography enables rapid distribution of certified allergen-free products to pharmacy and supermarket channels. Punta del Este's tourism economy generates seasonal demand spikes for gluten-free and dairy-free restaurant and retail offerings.
South America Free from Food Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The South American free-from food market structures around three tiers: multinational CPG conglomerates with dedicated allergen-free divisions, regional millers with localized sourcing networks, and specialized gluten-free manufacturers with segregated production infrastructure. Consolidation pressures concentrate at the mid-tier where Argentine and Brazilian formulators compete for supermarket private-label contracts. Dominant competitive moves include portfolio diversification into adjacent plant-based categories and geographic expansion through Mercosur trade preferences.
Within the dedicated gluten-free manufacturing tier, Dr Schar AG / SPA and Molinos Río de la Plata exemplify divergent strategic positions. Dr Schar represents the European-import archetype with established segregated production infrastructure that sustains shelf presence across Brazilian and Argentine retail networks. Molinos Río de la Plata occupies a position as the regional sourcing specialist, competing through price positioning anchored in localized supply chains. Danone SA sits within the multinational platform tier, leveraging plant-based fermentation capabilities to anchor the dairy-free segment. These three players illustrate the competitive spectrum from global scale to regional responsiveness.
| Leading Market Players |
|---|
| Brazi Bites |
| Dr Schar AG / SPA |
| Danone SA |
| Bob's Red Mill Natural Foods |
| Jussara SA |
| Lactalis |
| Raisio PLC |
| Hero Group AG |
| Molinos Río de la Plata |
| Others |
Value Network & Pricing Analysis
São Paulo's enzymatic oat processing cluster concentrates functional protein isolation capacity, translating upstream ingredient scarcity into sustained premium capture for dairy-free formulations across Brazilian retail networks. ANVISA's precautionary labeling mandate compresses margin recovery timelines by forcing parallel certification investments that mass-market consumers resist funding through price acceptance.
Pricing Analysis
The customization-premium spread separates certified gluten-free SKUs with dedicated production lines from shared-facility alternatives bearing precautionary warnings. Three-tier pricing structure across premium pharmacy channels, standard supermarket aisles, and economy private-label tiers reflects certification grade and channel reimbursement access. Cost compression in standard tiers intensifies as Brazilian supermarket chains expand private-label penetration. Diagnosed celiac patients exhibit lowest price sensitivity through medical necessity, while flexitarian health-conscious consumers rotate rapidly at premiums exceeding thirty-five percent thresholds.
Supply Chain Analysis
Tariff exposure between Thai modified starch suppliers and Brazilian formulators dominates supply chain risk profiles across texture-replication ingredient categories. Functional hydrocolloid inputs concentrate in Thai, European, and Chinese manufacturing nodes, exposing South American producers to currency-driven cost volatility and extended shipping timelines. Single-source vulnerability persists for enzymatic oat protein isolates tethered to Nordic and North American extraction technology licensors. Distribution runs through Carrefour and GPA supermarket networks anchored in São Paulo's metropolitan corridor, with pharmacy procurement channels capturing diabetic-specialist sugar-free volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in hydrocolloid stabilization and protein denaturation control concentrates in São Paulo and Buenos Aires, constraining facility expansion and creating acquisition premiums for mid-scale Argentine millers with captive technical talent.
For Market Incumbents: Insulate margin position by securing backward integration into modified starch and hydrocolloid supply through long-term offtake agreements with Thai and European producers. Accelerate INMETRO certification pipelines to compress launch windows versus import competitors trapped in cross-contamination warning protocols. Channel control through dedicated free-from aisle partnerships with GPA and Carrefour networks defends shelf presence against private-label displacement. For New Entrants and Emerging Players: Build out Colombian market presence in Bogotá and Medellín before domestic competitors establish gluten-free manufacturing capacity, exploiting underpenetrated retail infrastructure and extended import certification timelines that disadvantage European incumbents. Pharmacy channel expansion for sugar-free diabetic-specialist SKUs offers reimbursed purchasing pool access with premium pricing endurance. Direct-to-consumer digital platforms bypass INMETRO certification delays through Mercado Libre and Amazon Brazil marketplace integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certified pharmacy-network suppliers with ANVISA-registered diabetic specialty formulations and institutional procurement contracts. Long-term viability across the projection horizon favors platform integrators with segregated gluten-free production infrastructure and Mercosur trade preference access. Acquisition targets should demonstrate localized ingredient sourcing capabilities or enzymatic protein isolation technology licenses. The signal to watch is Mercosur harmonization progress collapsing country-specific formulation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Production Infrastructure Investment | ANVISA's precautionary labeling rules penalize shared-facility imports, rewarding dedicated allergen-free lines with clean-label positioning. |
| Pharmacy Channel Partnership Expansion | Sugar-free diabetic-specialist SKUs access reimbursed purchasing pools through ANVISA-registered formulations in Rio de Janeiro procurement networks. |
| Enzymatic Oat Protein Technology Licensing | Precision fermentation platforms compress cost structures while expanding flexitarian addressable markets beyond diagnosed allergen sufferers. |
| Mercosur Harmonization Alignment | Regulatory convergence across Brazil, Argentina, Paraguay, and Uruguay would enable single-production-run economics collapsing dual certification burdens. |
| Colombian Market First-Mover Positioning | Underpenetrated retail infrastructure in Bogotá and Medellín offers shelf space establishment before domestic gluten-free manufacturing capacity matures. |
Research Methodology
Initial hypotheses were tested against primary input from food technology directors, ANVISA regulatory affairs specialists, supermarket category buyers, and pharmacy procurement managers and refined through secondary validation across customs trade records, INMETRO certification databases, ANVISA allergen labeling filings, and Nielsen retail audit data. Bottom-up volume modeling from facility-level production capacity and top-down demand triangulation from diagnosed patient population estimates and flexitarian adoption curves were reconciled to produce segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end user archetype, distribution channel, and packaging format. CAGRs were derived from fitted growth curves calibrated to historical certification timeline data and channel expansion trajectories. Industry-specific forecast inputs included ANVISA regulatory implementation schedules and Mercosur harmonization negotiation progress.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational CPG conglomerates with dedicated allergen-free divisions or regional millers with localized sourcing networks would shift outcomes. Forecasts embed assumptions regarding INMETRO certification processing timelines and Thai-European hydrocolloid supply continuity that regulatory acceleration or trade disruption would revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Street Vendors Market
Food Service
Restaurant Glassware Market
Food Service
Meal Kit Delivery Services Market
Food Service
United States Online Food Delivery Market
Food Service
Qatar Food Service Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Beverage Napkins Market
Food Service
Food Service Disposables Market
Food Service
Hospital Food Services Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Australia Foodservice Market
Food Service
Gas Floor Fryers Market
Food Service
India Full Service Restaurants Market
Food Service
Smoker Grill Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
United States Biodegradable Food Service Disposables Market