
 United States Online Food Delivery Market | 2026-2036
United States Online Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Online Food Delivery Market Intelligence
The FDA Food Safety Modernization Act is rebalancing capital allocation toward cold-chain integrity and real-time tracking across delivery networks. DoorDash leverages its merchant density in suburban corridors to sustain last-mile efficiency. Uber Eats anchors its position through grocery expansion beyond prepared meals. Grubhub competes on loyalty program depth within legacy urban markets.
United States online food delivery encompasses digital platforms that coordinate order placement, payment processing, and logistics fulfillment between food merchants and end consumers, typically operating through GPS-tracked driver networks with delivery windows under sixty minutes. Restaurant Delivery occupies the mature revenue core, while Grocery Delivery captures the fastest expansion as platform algorithms optimize basket size and route density. AI Algorithms segment margins concentrate in demand forecasting and dynamic pricing modules that reduce driver idle time.
The FDA enforces sanitary transport rules under FSMA that elevate packaging and temperature-monitoring costs for all platform participants. The FTC scrutinizes commission structures and driver classification standards that directly affect unit economics and labor compliance burdens. The USDA coordinates with state health departments on ghost kitchen inspections, creating fragmented permitting requirements across jurisdictions. Stakeholders must monitor evolving municipal caps on delivery fees and the spread of drone corridor pilot programs that could reset infrastructure assumptions.
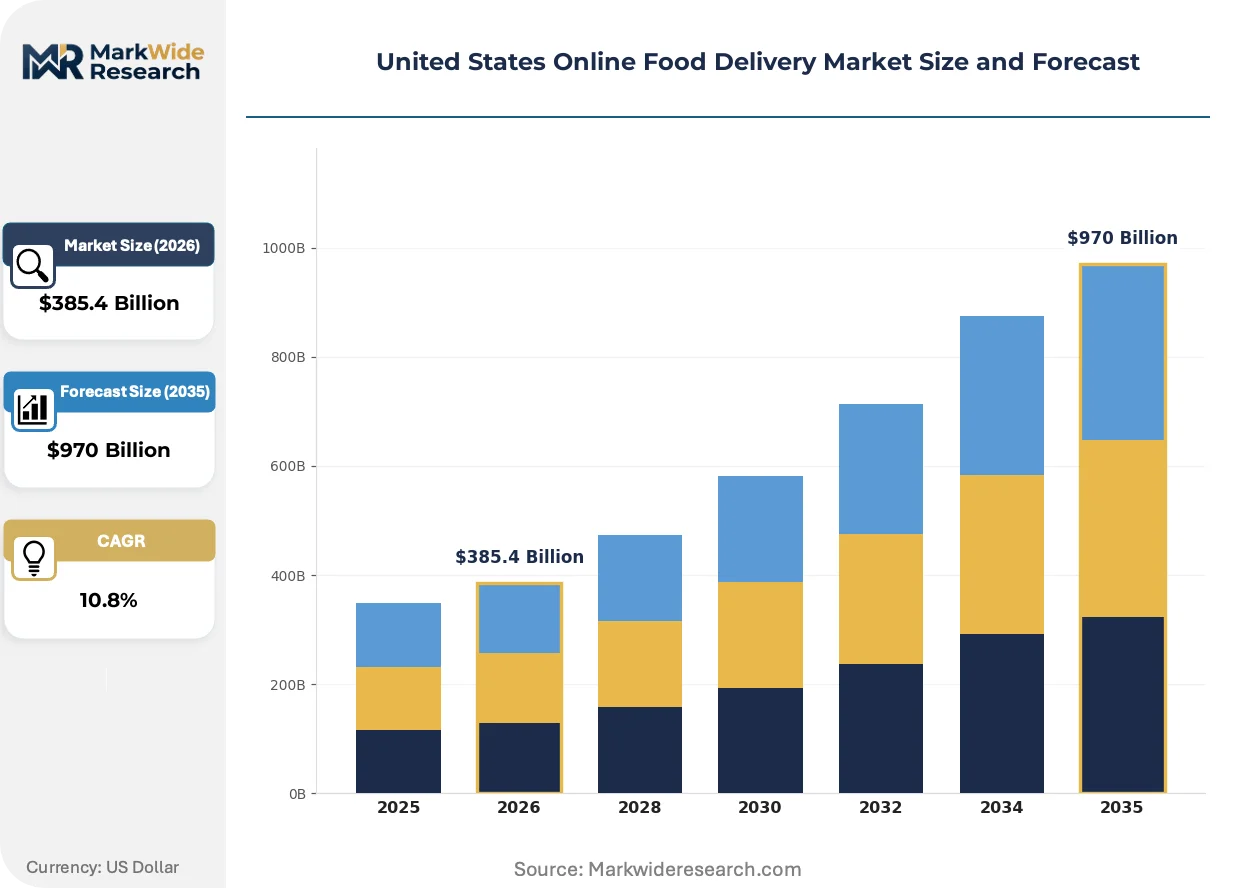
Market Dynamics
The FDA Food Safety Modernization Act's traceability mandates are forcing platforms to rebuild logistics infrastructure around real-time temperature monitoring and chain-of-custody documentation, compressing margins while raising barriers to entry.
Growth Catalysts
- Urban Density Concentration:Metropolitan corridors including New York City, Los Angeles, and Chicago generate sufficient order volume to support dedicated driver networks and sub-thirty-minute delivery windows.
- AI-Powered Route Optimization:Machine learning algorithms reduce driver idle time through demand forecasting and dynamic batching of multi-stop deliveries.
- FSMA Compliance Investment:The FDA's sanitary transport rules accelerate platform investment in cold-chain integrity, creating competitive differentiation for compliant operators.
Market Restraints
- Driver Classification Friction:The FTC's scrutiny of independent contractor standards elevates labor compliance costs and litigation exposure across platform networks.
- Commission Structure Caps:Municipal fee limits in jurisdictions including New York City and San Francisco constrain platform take rates and merchant profitability.
- Packaging Cost Escalation:Temperature-monitoring sensors and insulated containers required for FSMA compliance add per-unit material costs that platforms struggle to pass through.
Strategic Opportunities
- Grocery Basket Expansion:Platforms are migrating beyond prepared meals into full-basket grocery fulfillment, leveraging existing driver density for higher-margin per-trip revenue.
- Suburban Corridor Penetration:Lower-competition zones outside core urban centers offer route density improvements as household delivery frequency rises.
- Drone Corridor Pilots:FAA-sanctioned unmanned aerial vehicle test programs in select municipalities could reset last-mile cost assumptions for lightweight, time-sensitive orders.
Industry Challenges
- Ghost Kitchen Permitting Fragmentation:The USDA coordinates with state health departments on facility inspections, creating inconsistent licensing timelines across jurisdictions that delay market entry.
- Legacy POS Integration Complexity:Smaller merchant adoption of platform APIs remains uneven, requiring manual order transcription that elevates error rates and cancellation frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Online Food Delivery Market |
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $970 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Restaurant Delivery, Grocery Delivery, Meal Kits, On-Demand Delivery Customer Type: Individual Consumers, Corporate Clients, Families, Students Payment Model: Subscription Services, Pay-Per-Delivery, Commission-Based, Freemium Technology: Mobile Apps, Web Platforms, Delivery Drones, AI Algorithms |
| Companies Covered | DoorDash, Uber Eats, Grubhub, Postmates, Instacart, Amazon, Walmart, Domino's Pizza, Waiter.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Online Food Delivery Market Strategic Shifts & Innovations
Delivery platforms are converging on predictive logistics and automated fulfillment as the primary vectors for margin expansion, with technology investments concentrating on reducing the labor intensity of last-mile execution.
Autonomous delivery vehicles are overtaking human-driver dependence for fixed-route, high-frequency corridors. Quick-service chains in Phoenix and Houston are piloting sidewalk robots and small autonomous vans for sub-two-mile deliveries. This technology is compressing per-delivery labor costs while shifting capital requirements toward fleet ownership and maintenance infrastructure.
The FDA enforces escalating traceability requirements under FSMA Section 204 that mandate electronic record-keeping for high-risk foods. Platforms must now integrate blockchain or cloud-based tracking systems that capture handoff timestamps and temperature logs. Restaurant and grocery segments are responding by consolidating supplier relationships around vendors with pre-certified compliance systems.
Subscription-based ordering is displacing transactional purchasing as the dominant consumer relationship model. Major platforms now capture recurring revenue through monthly membership fees that subsidize delivery costs and lock in habitual usage patterns. This shift is most visible in dense coastal metros where household penetration of multiple competing subscriptions has compressed switching elasticity.
United States Online Food Delivery Market Segmentation
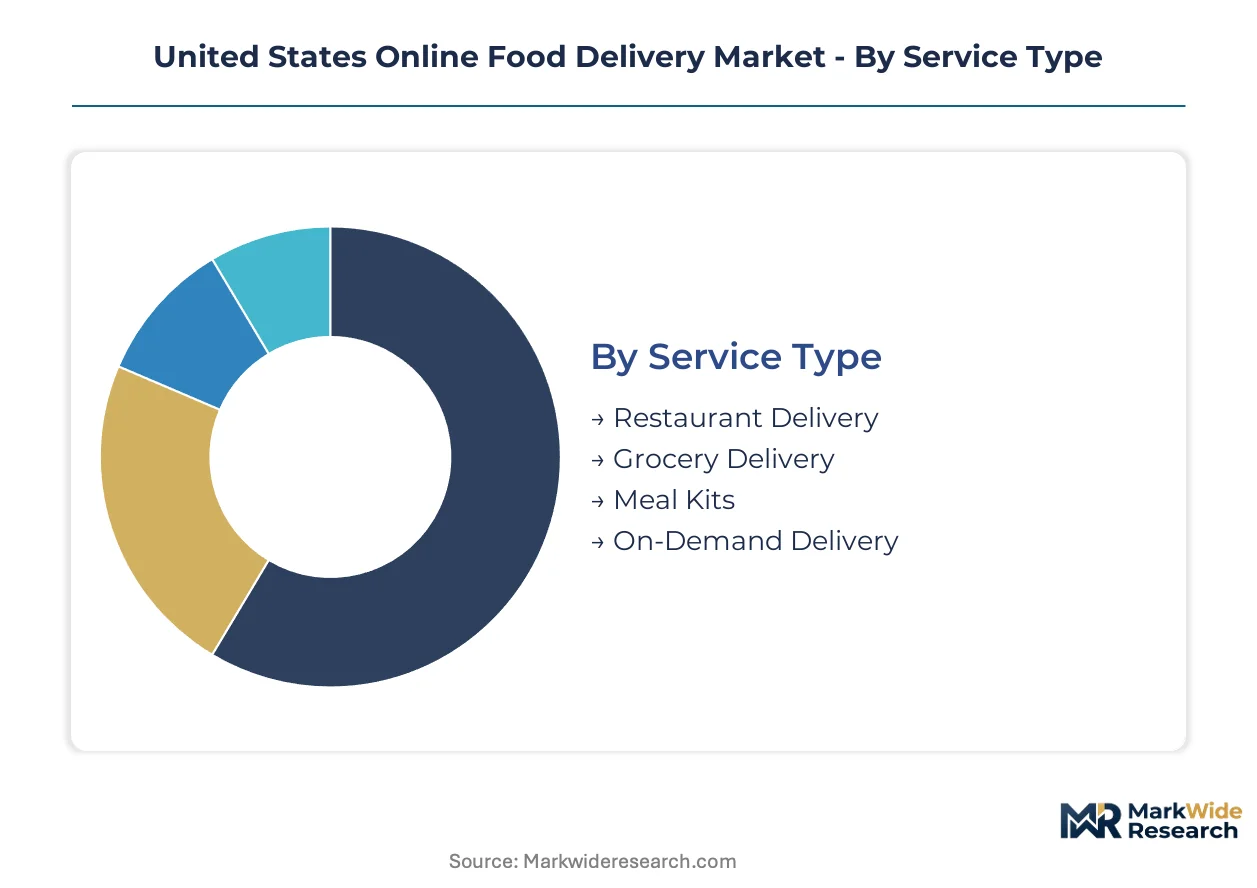
Platform operators configure capital deployment differently across service architectures, customer acquisition costs, and technology stacks. Segmentation reveals where cold-chain infrastructure, driver density, and algorithmic investment concentrate returns.
Service Type:
Capital intensity escalates sharply from prepared meals to temperature-controlled grocery fulfillment and specialized meal kit assembly.
- Restaurant Delivery:Established digital ordering pipelines connect quick-service chains to metropolitan driver networks. New York City, Los Angeles, and Chicago absorb the majority of order volume where sub-thirty-minute windows justify dedicated fleet investment.
- Grocery Delivery:Full-basket fulfillment demands refrigerated warehousing, real-time inventory synchronization, and route optimization for multi-stop trips. Suburban corridors outside core urban centers show the steepest household penetration gains as basket size economics improve.
- Meal Kits:Pre-portioned ingredient assembly requires centralized commissary infrastructure and precise demand forecasting to minimize spoilage.
- On-Demand Delivery:Convenience-store and pharmacy fulfillment leverages existing driver density for incremental trip revenue with minimal incremental capital.
Restaurant Delivery absorbs the bulk of installed capacity; Grocery Delivery is expanding most quickly.
Customer Type:
Acquisition economics and retention mechanics diverge sharply between habitual individual users and contracted corporate accounts with guaranteed volume floors.
- Individual Consumers:Single-user accounts drive platform liquidity through variable frequency and price sensitivity. Subscription bundling locks in recurring revenue across dense coastal metros where household penetration of multiple competing memberships has compressed switching elasticity.
- Corporate Clients:Enterprise catering contracts stabilize midday demand troughs and secure bulk order commitments. These accounts demand consolidated invoicing, dietary compliance documentation, and dedicated account management that elevates operational overhead.
- Families:Multi-person households generate larger average basket sizes and stronger subscription attachment for grocery and meal kit services.
- Students:Campus-adjacent demand clusters enable hyperlocal driver pooling and promotional pricing calibrated to limited discretionary budgets.
Individual Consumers anchor transaction volume; Corporate Clients deliver the most predictable margin contribution.
Payment Model:
Revenue recognition timing and cash flow profiles shift dramatically between upfront subscription commitments and per-transaction fees.
- Subscription Services:Monthly membership fees subsidize delivery costs and create habitual usage patterns. Platforms prioritize these relationships in dense urban corridors where frequency justifies fixed-cost coverage.
- Pay-Per-Delivery:Transactional pricing captures occasional users and price-sensitive segments without commitment friction. This model dominates in suburban expansion zones where household delivery frequency remains intermittent.
- Commission-Based:Merchant-funded revenue shares align platform incentives with restaurant sales volume but expose operators to municipal fee caps.
- Freemium:Tiered access structures convert free users to paid tiers through delivery fee waivers and priority service guarantees.
Subscription Services lock in the most durable revenue streams; Pay-Per-Delivery captures the widest addressable audience.
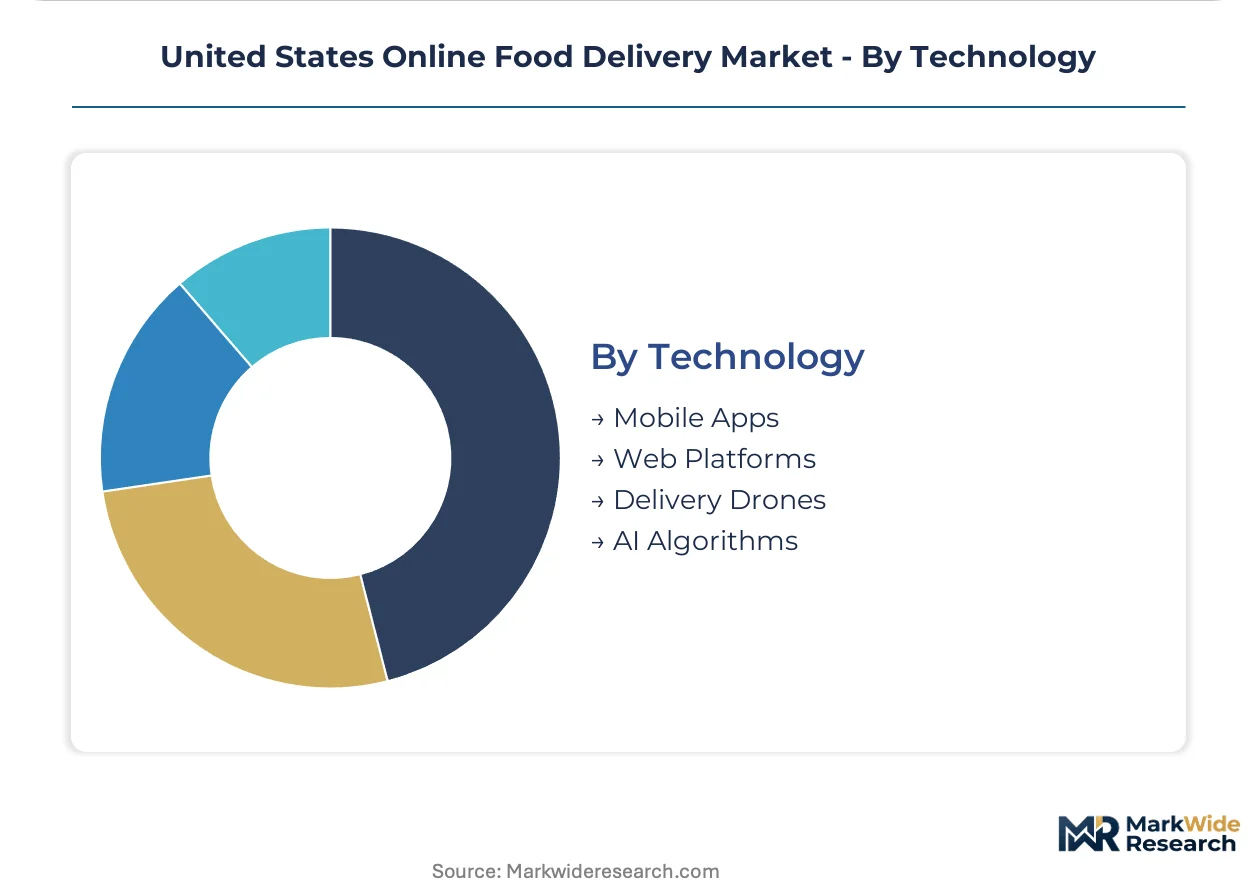
Technology:
Development spend and infrastructure depreciation schedules concentrate in mobile-first architectures and emerging autonomous fulfillment systems.
- Mobile Apps:Native iOS and Android applications dominate consumer touchpoints with GPS tracking, push notifications, and integrated payment rails. These platforms require continuous UX iteration and OS compatibility maintenance.
- Web Platforms:Browser-based ordering captures corporate procurement workflows and older demographic segments less inclined to install dedicated applications.
- Delivery Drones:FAA-sanctioned unmanned aerial vehicle pilots in select municipalities test lightweight, time-sensitive order fulfillment with radically different cost structures.
- AI Algorithms:Machine learning modules optimize demand forecasting, dynamic pricing, and driver batching to compress idle time and elevate per-trip efficiency.
Mobile Apps command the largest development budgets; AI Algorithms generate the most direct margin leverage per dollar invested.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City, Los Angeles, and Chicago generate the densest delivery demand corridors in the United States, where sub-thirty-minute windows and dedicated driver networks sustain platform unit economics. Metropolitan concentration shapes capital deployment across cold-chain infrastructure and algorithmic route optimization. FDA traceability mandates under FSMA Section 204 elevate compliance costs unevenly across state regulatory environments.
New York Metro
Manhattan and Brooklyn corridors absorb the highest per-capita delivery frequency nationally, driven by household penetration of multiple competing subscription services. New York City's municipal commission caps constrain platform take rates, compressing merchant profitability. Queens and the Bronx show accelerating driver pool expansion as platforms optimize batch density across outer-borough routes.
California
Los Angeles and San Francisco anchor West Coast demand, with Silicon Valley corporate catering contracts stabilizing midday volume troughs. Cal/OSHA enforcement of driver safety standards elevates compliance burdens beyond federal baselines. San Diego and Sacramento emerge as suburban penetration targets where lower competition supports route density improvements.
Texas
Houston and Dallas-Fort Worth corridors demonstrate the fastest household penetration gains for grocery basket expansion beyond prepared meals. The Texas Department of State Health Services coordinates ghost kitchen inspections with municipal health departments, creating fragmented permitting timelines. Austin's tech-sector density attracts autonomous delivery pilots testing sidewalk robots for sub-two-mile corridors.
Illinois
Chicago's urban core sustains dedicated driver networks through concentrated quick-service restaurant demand and corporate account volume. The Illinois Department of Agriculture enforces FSMA-aligned sanitary transport rules that elevate packaging and temperature-monitoring costs. Suburban collar counties show rising delivery frequency as platforms extend route optimization into lower-density zones.
Florida
Miami and Orlando corridors concentrate tourism-driven demand spikes and retiree household adoption of subscription services. The Florida Department of Health maintains state-level ghost kitchen inspection standards that exceed federal minimums in coastal jurisdictions. Tampa Bay emerges as a testbed for drone corridor pilots under FAA-sanctioned unmanned aerial vehicle programs.
United States Online Food Delivery Market Key Industry Players
Premium-margin players sit above commodity-margin players across subscription attachment and corporate account penetration, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: metropolitan-density specialists leveraging urban route optimization, suburban-expansion platforms capturing household frequency gains, and grocery-integrated operators extending beyond prepared meals. Dominant competitive moves include strategic partnerships with quick-service chains for exclusive digital ordering pipelines and technology licensing agreements for AI-powered demand forecasting modules.
Within the metropolitan-density tier, DoorDash and Uber Eats exemplify platform operators optimizing for driver batch efficiency across dense urban corridors. Grubhub occupies a position within legacy urban loyalty programs, representing the subscription-anchored archetype. These three companies anchor the competitive landscape through divergent capital allocation: DoorDash toward suburban corridor penetration, Uber Eats toward grocery basket expansion, and Grubhub toward corporate account depth within established metros.
| Leading Market Players |
|---|
| DoorDash |
| Uber Eats |
| Grubhub |
| Postmates |
| Instacart |
| Amazon |
| Walmart |
| Domino's Pizza |
| Waiter.com |
| Others |
Cost & Logistics Intelligence
Venture-backed platform consolidators and private-equity-rolled-up delivery networks anchor supply-side concentration, translating driver density advantages into pricing discipline across metropolitan corridors while municipal fee caps compress margin recovery in regulated jurisdictions.
Pricing Analysis
Throughput-based pricing anchors platform revenue models, with subscription memberships capturing habitual usage patterns and per-delivery fees serving occasional demand. Price differentiation separates premium subscription tiers with waived delivery fees from standard pay-per-transaction users and economy segments reliant on promotional subsidies. Pricing pressure stems from municipal commission caps in New York City and San Francisco that constrain merchant-funded take rates. Individual consumers exhibit highest price sensitivity, while corporate catering contracts demonstrate lowest elasticity due to consolidated invoicing and volume commitments.
Supply Chain Analysis
Domestic-content mandates under the FDA Food Safety Modernization Act reshape sourcing toward US-based cold-chain infrastructure and temperature-monitoring equipment suppliers. Geographic supply concentration draws from China for insulated packaging materials, Mexico for produce proximity sourcing, and domestic commissary networks for last-mile fulfillment. Raw material dependencies center on refrigerant gases, GPS tracking hardware, and compostable food-grade containers. Single-source vulnerability runs through concentrated ghost kitchen real estate in dense urban cores. Distribution feeds from centralized dark stores through driver networks to end consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
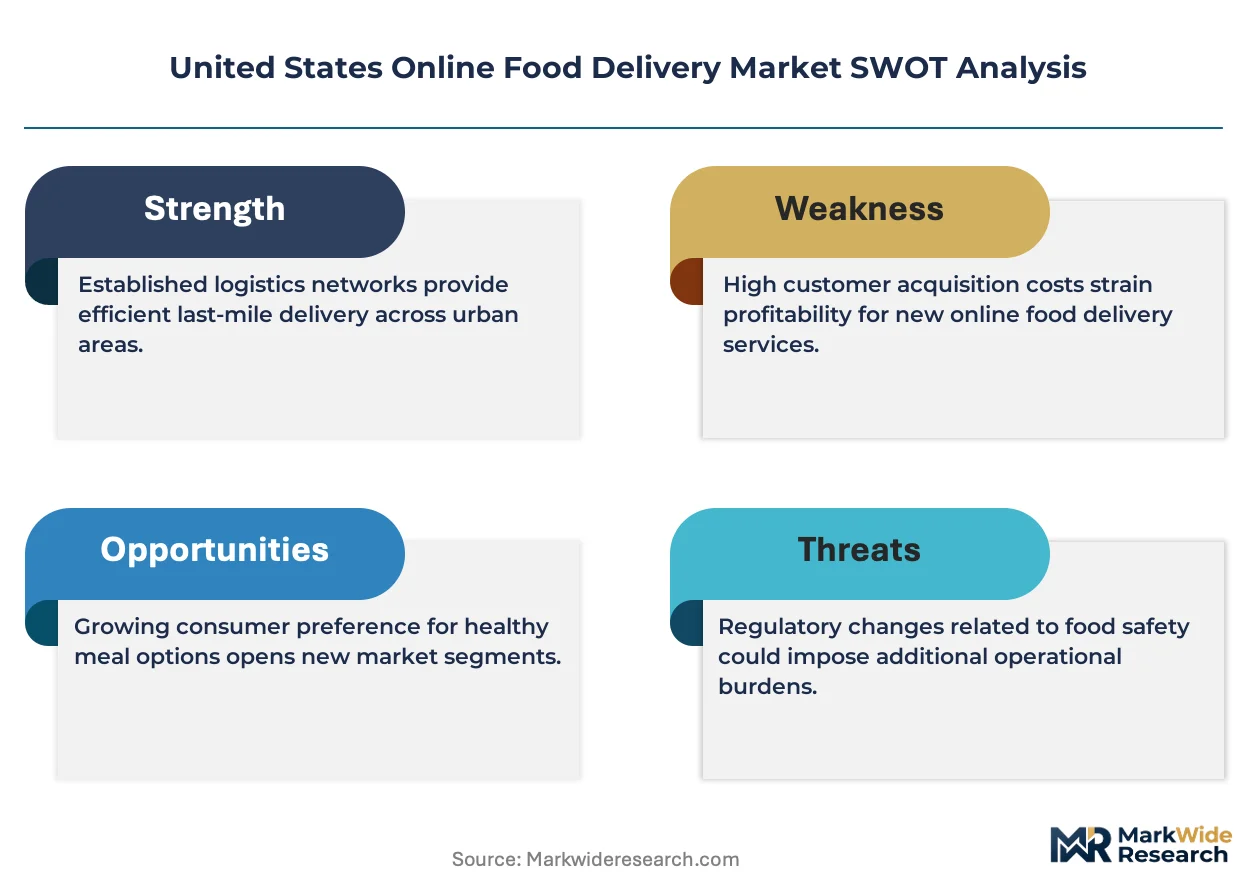
This market reads as a consolidation play where FSMA compliance investments and driver classification litigation are forcing subscale operators toward exit or acquisition.
For Market Incumbents: Cement market position through exclusive digital ordering pipelines with quick-service chains and backward integration into ghost kitchen real estate. The FTC's contractor classification scrutiny elevates labor compliance costs that favor scaled operators with legal infrastructure. Cold-chain certification investment creates defensive moats against non-compliant regional entrants. For New Entrants and Emerging Players: FAA drone corridor pilots in Florida and Texas open a window for autonomous last-mile specialization in lightweight, time-sensitive orders. White-space targets include suburban grocery basket expansion beyond prepared meals and corporate catering contracts stabilizing midday demand troughs. A go-to-market angle anchored in FSMA pre-certified supplier relationships accelerates permitting timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated delivery platforms with captive driver networks in secondary metros. Long-term viability hinges on subscription attachment rates and algorithmic route density. The signal to watch is municipal fee cap spread compressing take rates in additional jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | FSMA Section 204 compliance creates competitive differentiation for temperature-monitoring capabilities. |
| Autonomous Delivery Pilot Expansion | FAA-sanctioned drone corridors in Tampa Bay and Austin reset last-mile cost structures. |
| Corporate Catering Contract Acquisition | Enterprise accounts stabilize midday demand troughs with volume floors and lower churn. |
| Ghost Kitchen Real Estate Consolidation | Permitting fragmentation favors operators with pre-certified facilities across multiple jurisdictions. |
| Subscription Membership Tier Restructuring | Recurring revenue locks in habitual usage patterns and reduces customer acquisition cost intensity. |
Research Approach
Independent corroboration across platform operations executives, restaurant franchise development leads, municipal regulatory affairs officers, and cold-chain logistics specialists underwrites the qualitative findings. Secondary validation draws from FDA FSMA guidance documents, FTC enforcement actions, FAA unmanned aerial vehicle pilot announcements, and municipal delivery fee ordinance databases. Bottom-up driver network density modeling triangulates against top-down metropolitan household penetration estimates.
Rate-of-change decomposition isolates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include service architecture, customer acquisition model, payment structure, and technology stack. CAGRs derive from logistic diffusion curves applied to subscription penetration and grocery basket expansion trajectories. Forecast inputs incorporate driver classification litigation exposure and drone corridor regulatory momentum.
The model assumes a particular technology adoption path; alternative pathways for autonomous delivery would alter the outlook. Forecasts reflect assumptions around municipal fee cap diffusion and FSMA enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Inflight Catering Market
Food Service
Philippines Foodservice Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Vacuum Flask Market
Food Service
Flat Top Grills Market
Food Service
One-Off Chopsticks Market
Food Service
Europe Food Away from Home Market
Food Service
Cambodia Foodservice Market
Food Service
Countertop Pressure Fryer Market
Food Service
Australia Foodservice Market
Food Service
Portion Cups Market
Food Service
Lunch Takeout Market
Food Service
Food Delivery Services Market
Food Service
Charbroiler Market
Food Service
Global Online Food Delivery Services Market