
 Benelux Foodservice Market | 2026-2036
Benelux Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Foodservice Market Analysis
Healthcare facility dining is broadening as hospitals and eldercare campuses across Belgium and Luxembourg outsource meal operations to specialized contractors. Sodexo anchors this segment through long-term service agreements with major medical centers. Compass Group PLC leverages its scale to compete for integrated facilities management contracts that bundle foodservice with cleaning and maintenance.
Benelux foodservice encompasses the preparation, distribution, and sale of ready-to-consume meals and beverages through commercial and institutional channels, operating under strict HACCP temperature controls and allergen labeling protocols to ensure food safety across hot and cold service lines. Quick Service Restaurants dominate transaction volume due to drive-thru and digital ordering penetration, while Catering Services directed at corporate clients and educational institutions capture higher margin pools through contracted pricing and predictable volume commitments. Full-Service Restaurants occupy the premium tier, though their recovery trails delivery-optimized formats.
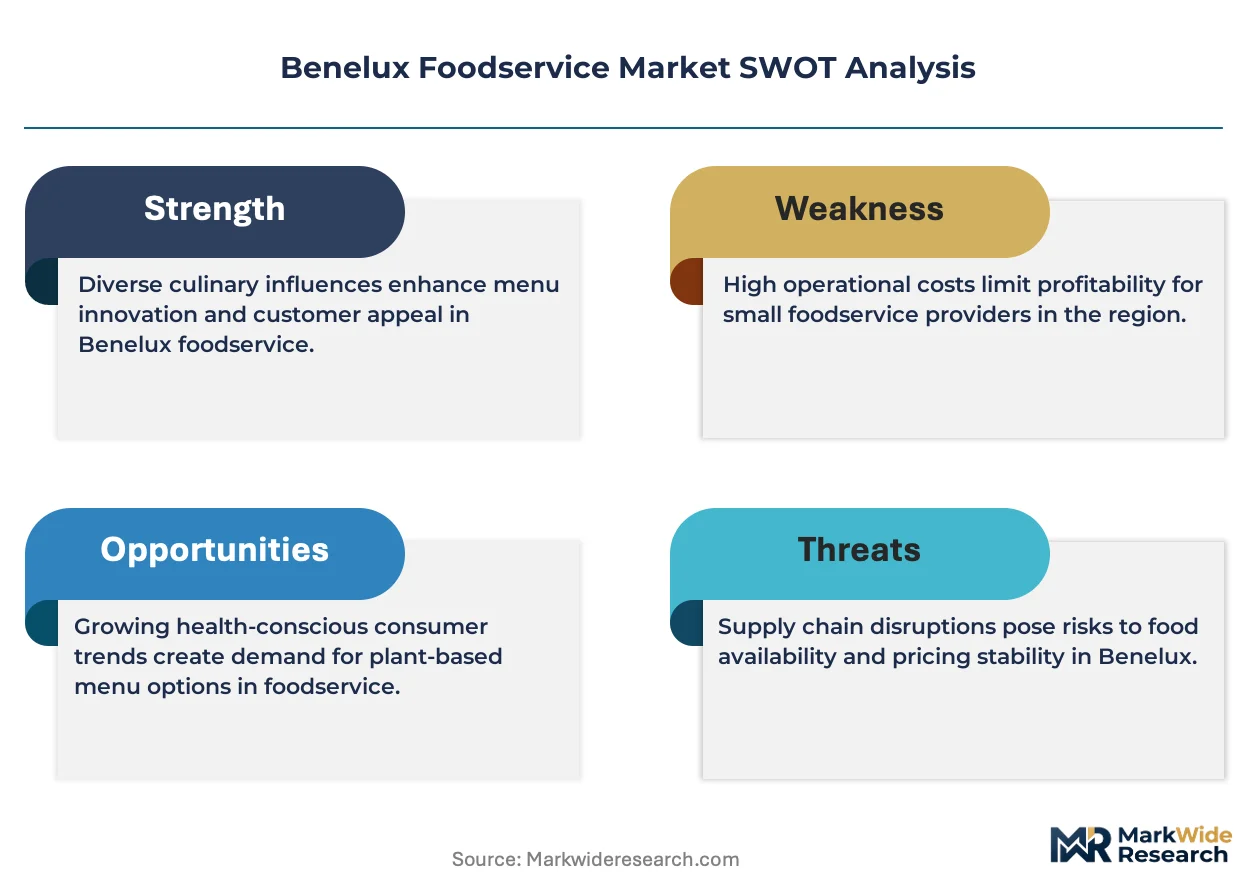
Belgium's Federal Agency for the Safety of the Food Chain (FASFC) and the Netherlands' Netherlands Food and Consumer Product Safety Authority (NVWA) enforce traceability and hygiene standards that elevate compliance costs for smaller operators. The EU Green Deal's farm-to-fork strategy pressures procurement teams to document sustainable sourcing and reduce packaging waste. Stakeholders must decide whether to build in-house delivery infrastructure or surrender margin to aggregator platforms as channel control becomes the decisive competitive variable.
Market Dynamics
The EU Green Deal's farm-to-fork strategy is forcing kitchen operators across Belgium, the Netherlands, and Luxembourg to reconfigure procurement systems and waste management protocols, creating competitive separation between operators with capital to adapt and those without.
Growth Catalysts
- Corporate On-Site Dining Mandates:Employers in Amsterdam and Rotterdam are expanding subsidized meal programs to retain talent, creating contracted revenue streams for foodservice operators with scale to serve large campuses.
- EU Green Deal Food Waste Targets:Mandatory reduction benchmarks are accelerating investment in portion-control technology and inventory management systems that cut spoilage while lowering input costs.
- Urban Food Hall Proliferation:Developers in Utrecht and Antwerp are converting retail space into multi-vendor dining halls, concentrating foot traffic and reducing individual operator marketing burdens.
Market Restraints
- Labor Cost Escalation:Minimum wage harmonization pressures across the three markets are compressing margins for operators dependent on front-of-house staffing models.
- Aggregator Platform Dependency:Delivery-first concepts in Dutch cities face margin erosion from platform fees that extract 15-30 percent of order value, limiting reinvestment capacity.
- HACCP Compliance Burden:Belgium's FASFC and the Netherlands' NVWA enforcement of temperature logging and allergen traceability elevates fixed costs for smaller independent operators.
Strategic Opportunities
- Healthcare Outsourcing Expansion:Belgian hospitals and Luxembourg eldercare campuses are unbundling meal operations, creating multi-year contract opportunities for specialized contractors with clinical nutrition expertise.
- Dark Kitchen Infrastructure:Underutilized industrial zones in Rotterdam and Liège offer low-rent locations for delivery-only production facilities that bypass prime real estate costs.
- CSRD-Driven Sustainable Sourcing:The EU's Corporate Sustainability Reporting Directive is creating procurement preference for operators who can document regional ingredient provenance and packaging reduction.
Industry Challenges
- Chef and Kitchen Manager Scarcity:Trained personnel capable of managing HACCP-compliant operations at scale are concentrated in major cities, leaving secondary markets underserved.
- Legacy POS Integration Friction:Full-service restaurants in Brussels and The Hague face technical debt when connecting traditional ordering systems to aggregator APIs and inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Foodservice Market |
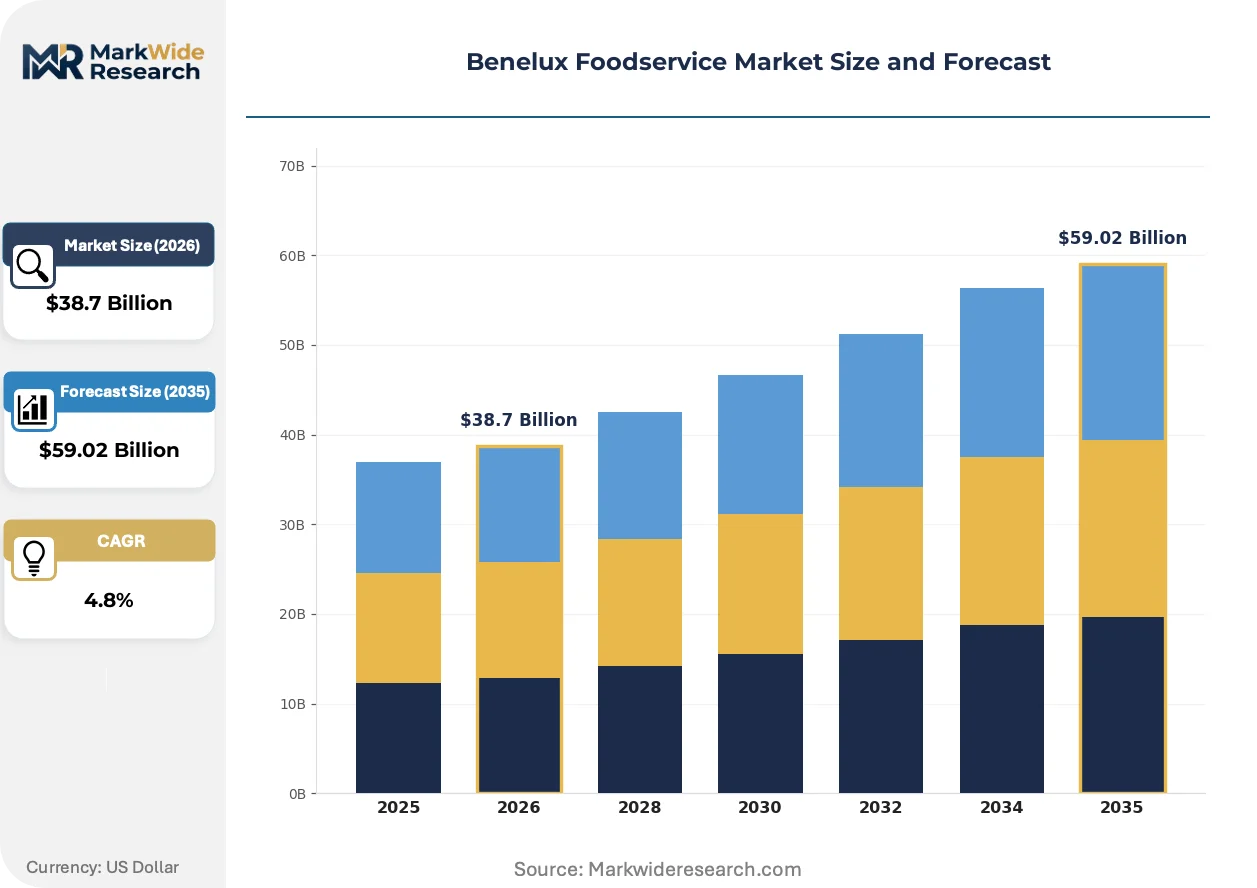
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick Service Restaurants, Cafés, Catering Services Customer Type: Retail Customers, Corporate Clients, Educational Institutions, Healthcare Facilities Product Type: Food Products, Beverages, Packaged Goods, Alcoholic Beverages Delivery Model: Takeaway, Dine-In, Delivery, Drive-Thru |
| Companies Covered | Compass Group PLC, Domino's Pizza, Inc., McDonald's Corporation, Doctor's Associates Inc., Starbucks Corporation, Yum! Brands, Inc., Sodexo, Autogrill S.p.A., Restaurant Brands International Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Foodservice Market Emerging Trajectories
Kitchen automation and data-driven procurement are compressing operational decision cycles across the Benelux foodservice landscape, separating operators who treat technology as infrastructure from those who treat it as overhead.
Cloud-connected kitchen display systems and automated prep line equipment are decentralizing production coordination across multi-location operators. Chains with five or more Benelux outlets are deploying these tools to synchronize menu updates and inventory alerts in real time. The technology is decentralizing authority from individual kitchen managers to centralized operations centers that monitor performance across dispersed sites.
The EU Green Deal's packaging waste reduction mandates are compelling operators to eliminate single-use plastics and shift to reusable container programs or certified compostable alternatives. Belgium's FASFC has aligned inspection protocols to verify compliance with new labeling and material standards. Full-service restaurants in Brussels face the steepest adaptation curve as they balance dine-in presentation standards against takeout packaging requirements.
Consolidated procurement through group purchasing organizations is displacing direct supplier relationships for mid-size operators in the Netherlands. Independent restaurants in Amsterdam and Rotterdam are joining buying cooperatives to match the ingredient pricing and delivery terms secured by larger chains. The shift is most visible among operators with annual food purchases between 500,000 and 2 million euros who previously negotiated alone.
Benelux Foodservice Market Segmentation
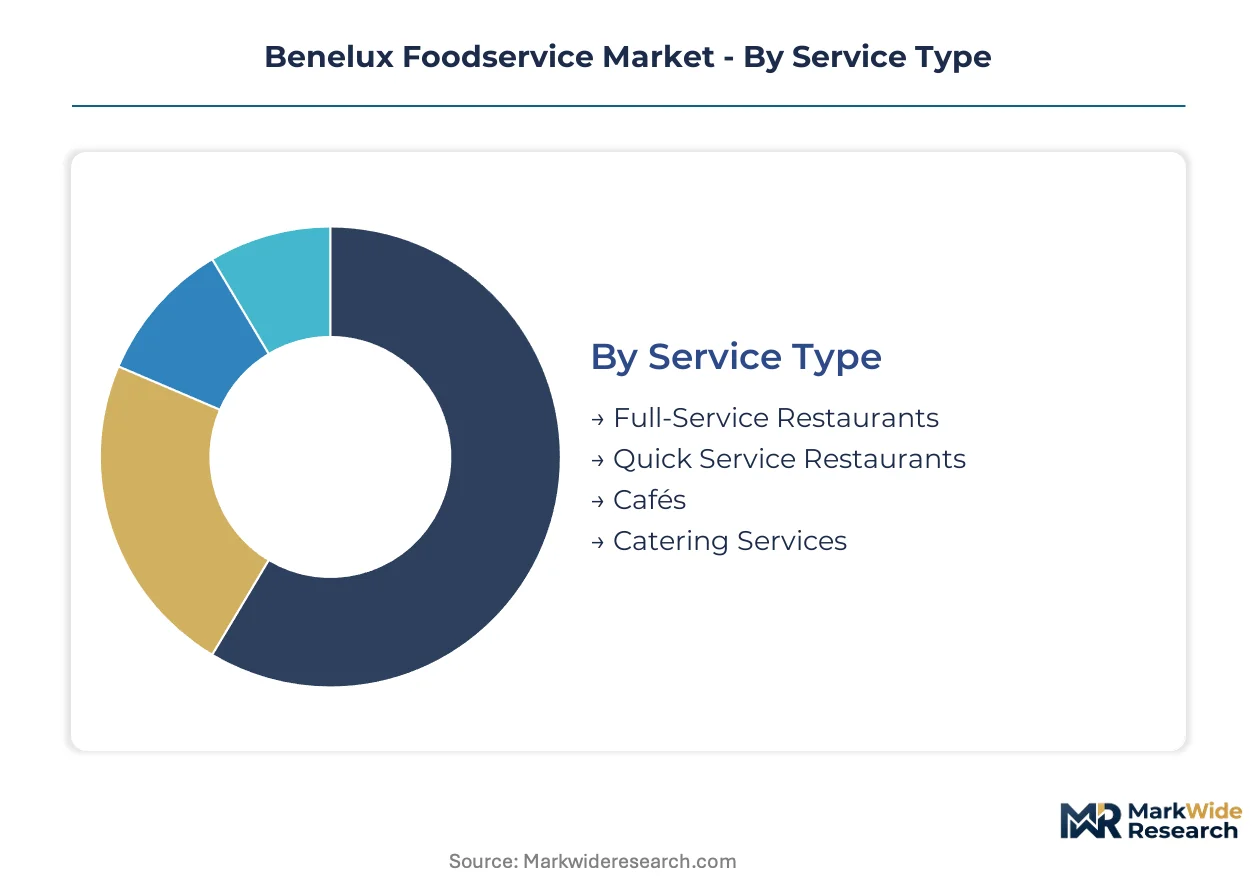
Segmentation in Benelux foodservice separates operators by regulatory exposure and margin architecture. Certification burdens from Belgium's FASFC and the Netherlands' NVWA vary sharply across service formats, while delivery economics reshape customer access patterns.
Service Type:
Belgium's FASFC mandates HACCP temperature logging for all hot service lines, though audit frequency intensifies for high-volume formats. The Netherlands' NVWA aligns enforcement with EU Green Deal waste tracking requirements.
- Full-Service Restaurants:Table-service operations with extended menu cycles and front-of-house labor intensity. Demand concentrates in Brussels and The Hague where expense-account dining and tourism traffic sustain premium pricing, though recovery from pandemic-era restrictions lags delivery-optimized competitors.
- Quick Service Restaurants:Standardized menu formats with drive-thru and digital ordering infrastructure. Amsterdam and Rotterdam operators capture volume through aggregator platform partnerships, absorbing 15-30 percent platform fees that compress reinvestment capacity.
- Cafés:Beverage-forward formats with limited food preparation. Belgian urban centers sustain independent operators through breakfast and afternoon traffic patterns.
- Catering Services:Contracted meal provision for institutional clients. Luxembourg eldercare campuses and Dutch corporate campuses outsource to specialized contractors with clinical nutrition capabilities.
Quick Service Restaurants sits at the top of the volume ranking, with Catering Services climbing the fastest.
Customer Type:
Margin stability varies by contract structure, with multi-year institutional agreements offering predictability against volatile retail traffic.
- Corporate Clients:Subsidized on-site dining programs and contracted catering for meetings and events. Amsterdam and Rotterdam employers expand meal benefits to retain talent, creating recurring revenue streams for operators with campus-scale service capability.
- Healthcare Facilities:Hospital and eldercare meal operations requiring clinical nutrition expertise and allergen-controlled preparation. Belgian medical centers unbundle foodservice from facilities management, awarding long-term contracts to specialized contractors.
- Retail Customers:Individual transaction-based demand through restaurants, cafés, and digital ordering platforms. Aggregator dependency erodes margin for independent operators in Dutch cities.
- Educational Institutions:School and university meal programs with price-controlled contracts and high-volume, time-constrained service windows.
Retail Customers maintains the broadest addressable base, while Healthcare Facilities demonstrates the steepest contract value expansion.
Product Type:
EU Green Deal packaging mandates and FASFC labeling requirements impose differentiated compliance costs across product categories.
- Food Products:Prepared meals and ingredients subject to HACCP temperature controls and allergen traceability. Hot service lines in Belgian operations face intensified FASFC inspection protocols.
- Beverages:Non-alcoholic drinks with lower regulatory burden but compressed margin from commodity pricing.
- Alcoholic Beverages:Beer, wine, and spirits with licensing requirements varying across Belgium, Netherlands, and Luxembourg jurisdictions.
- Packaged Goods:Pre-portioned and shelf-stable items with EU Green Deal-driven shifts from single-use plastics to certified compostable or reusable alternatives.
Food Products commands the largest revenue share, with Packaged Goods gaining share fastest on delivery-format proliferation.
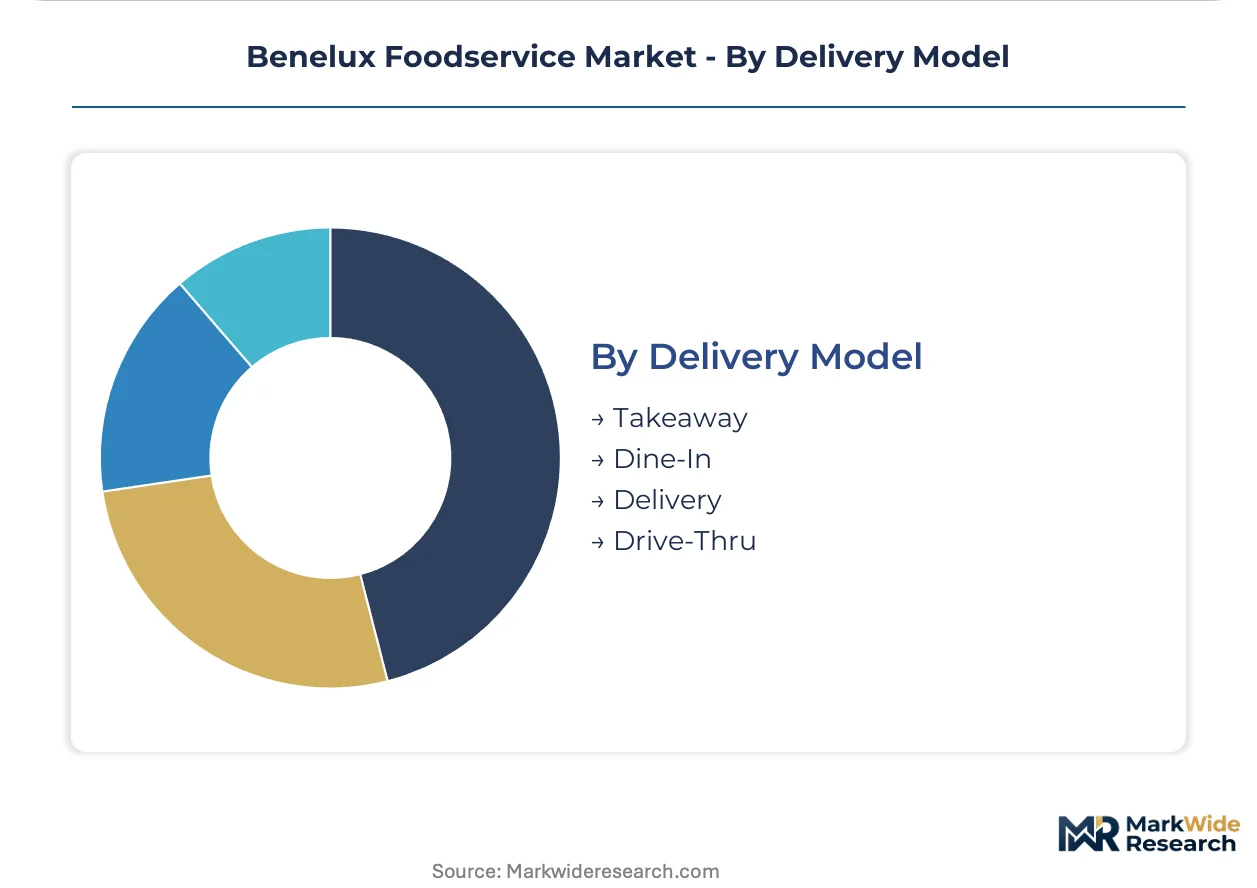
Delivery Model:
Channel control has become the decisive competitive variable as operators weigh infrastructure investment against aggregator platform surrender.
- Delivery:Platform-mediated and in-house logistics reaching residential and workplace addresses. Rotterdam and Utrecht operators face margin erosion from aggregator fees that extract substantial order value.
- Dine-In:On-premise consumption with higher labor intensity and real estate costs. Brussels full-service restaurants balance presentation standards against takeout packaging requirements.
- Takeaway:Customer-collected orders with lower logistical complexity but packaging compliance burdens from EU Green Deal mandates.
- Drive-Thru:Vehicle-based service with dedicated infrastructure requirements, concentrated in Quick Service Restaurant formats at peripheral locations.
Delivery leads transaction growth, with Drive-Thru expanding most quickly on new-format development in Dutch suburban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration across Belgium, the Netherlands, and Luxembourg follows compliance-cost differentials in food safety enforcement and labor regulation, concentrating capital-intensive formats in jurisdictions with clearer operational pathways while smaller operators retreat to lower-audit-frequency segments.
Netherlands
Amsterdam and Rotterdam anchor delivery-first concept proliferation, with urban food halls concentrating multi-vendor operations under single-roof logistics. The Netherlands Food and Consumer Product Safety Authority enforces HACCP temperature logging that elevates fixed costs for independent operators. Utrecht developers are converting retail vacancies into shared-kitchen infrastructure, reducing individual operator capital burdens.
Belgium
Brussels sustains full-service restaurant demand through expense-account dining and institutional tourism traffic, though recovery lags delivery-optimized competitors. The Federal Agency for the Safety of the Food Chain intensifies audit frequency for high-volume hot service lines, compressing margins for operators without scale. Antwerp food hall conversions are redirecting foot traffic from standalone venues to centralized dining destinations.
Luxembourg
Eldercare campuses and financial sector headquarters drive contracted catering demand with multi-year service agreements. EU Green Deal waste-tracking requirements apply uniformly, though smaller market size limits supplier diversification. Luxembourg City corporate dining contracts prioritize operators with integrated facilities management capabilities beyond standalone foodservice.
Benelux Foodservice Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional catering consolidating around integrated service providers while retail formats fragment across platform-dependent independents and vertically integrated chains. The Netherlands and Belgium exhibit contrasting structures: Dutch delivery-first markets favor scale-driven operators with aggregator tolerance, while Belgian full-service retains independent density despite compliance burdens. Three archetypes dominate: multinational contract caterers with facilities management bundling, quick-service chains with captive delivery infrastructure, and platform-dependent dark kitchen operators. Competitive moves concentrate on M&A-driven geographic densification and strategic partnerships with real estate developers for food hall anchoring.
Among multinational contract caterers, Compass Group PLC and Sodexo occupy positions exemplifying the integrated facilities management archetype, bundling foodservice with cleaning and maintenance to capture multi-year institutional agreements. McDonald's Corporation anchors the quick-service tier with drive-thru and digital ordering infrastructure that bypasses aggregator dependency. These three entities represent the scale-driven, compliance-resilient operator category best positioned for EU Green Deal adaptation and HACCP enforcement intensification.
| Leading Market Players |
|---|
| Compass Group PLC |
| Domino's Pizza, Inc. |
| McDonald's Corporation |
| Doctor's Associates Inc. |
| Starbucks Corporation |
| Yum! Brands, Inc. |
| Sodexo |
| Autogrill S.p.A. |
| Restaurant Brands International Inc. |
| Others |
Supply Flow & Price Mechanics
Contracted catering premiums diverge sharply from aggregator-dependent retail margins across the Benelux foodservice landscape, with multi-year institutional agreements anchoring pricing power in Luxembourg eldercare and Dutch corporate campuses while platform fees compress reinvestment capacity for delivery-first operators in Amsterdam and Rotterdam.
Pricing Analysis
Distributor margins on specialty ingredients and fresh produce widen the cost base for independent full-service restaurants in Brussels against vertically integrated quick-service chains. Three-tier pricing structure across premium full-service, standard fast-casual, and economy dark-kitchen tiers reflects HACCP certification investment and real estate positioning. Pricing pressure stems from minimum wage harmonization across Belgium, Netherlands, and Luxembourg compressing front-of-house labor models. Healthcare facilities and corporate campuses demonstrate lowest price sensitivity due to subsidized meal program structures, while retail customers face pass-through volatility from commodity protein and energy costs.
Supply Chain Analysis
Single-source vulnerability sits with specialized clinical nutrition suppliers serving Belgian hospital networks and Luxembourg eldercare campuses. Geographic supply concentration draws from the Netherlands for greenhouse vegetables and dairy, Belgium for processed proteins and chocolate derivatives, and France for wine and specialty ingredients. Fresh produce, sustainable packaging materials, and allergen-controlled preparation inputs face tight specification requirements. Supply chain risk centers on EU Green Deal packaging waste mandates disrupting legacy supplier relationships. Distribution runs through consolidated procurement cooperatives in the Netherlands and direct-to-operator relationships in Belgian full-service segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Benelux foodservice market functions as a geographic-arbitrage play where Dutch delivery-first infrastructure investments and Belgian compliance-heavy full-service operations create divergent capital intensity profiles against Luxembourg's concentrated institutional contracting environment.
For Market Incumbents: Hedge platform dependency exposure by developing captive delivery infrastructure in Rotterdam and Utrecht corridors where industrial zone rents support dark-kitchen consolidation. Reinforce HACCP compliance capabilities as Belgium's FASFC intensifies audit frequency for high-volume hot service lines, creating separation from undercapitalized independents. Prioritize multi-year facilities management bundling in Luxembourg City where corporate headquarters demand integrated service beyond standalone foodservice.
For New Entrants and Emerging Players: Cloud-connected kitchen display systems offer a technology-first wedge to capture mid-size operator segments with annual food purchases between 500,000 and 2 million euros currently underserved by legacy POS integration. Target Antwerp and Utrecht food hall developments where shared infrastructure reduces individual capital burdens and developer partnerships provide foot traffic concentration. Deploy group purchasing organization membership as primary go-to-market mechanism to match chain-level ingredient pricing without scale requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance cost escalation and EU Green Deal adaptation requirements outstrip independent operator balance sheet capacity. Frame long-term viability around operators with demonstrated HACCP infrastructure and documented sustainable sourcing capabilities capable of serving institutional contract renewal cycles. Target specialized healthcare catering contractors with clinical nutrition expertise and existing Belgian hospital relationships. Monitor CSRD-driven procurement preference shifts as signal for which operators capture corporate campus contract expansions.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Infrastructure Expansion | Underutilized industrial zones in Rotterdam and Liège bypass prime real estate costs for delivery-only production. |
| CSRD-Driven Sustainable Sourcing Certification | Documented regional ingredient provenance and packaging reduction secure procurement preference from corporate clients. |
| Healthcare Facilities Management Bundling | Integrated foodservice with cleaning and maintenance captures multi-year agreements with Belgian medical centers. |
| Aggregator Platform Independence | Captive delivery infrastructure in Dutch cities retains margin otherwise surrendered to 15-30 percent platform fees. |
| Food Hall Developer Partnerships | Multi-vendor anchoring in Utrecht and Antwerp concentrates marketing burden reduction and shared logistics. |
Methodological Framework
Bottom-up outlet-level modeling reconciled against top-down procurement flow tracking forms the analytical core of this study. Primary interviews with foodservice operations directors, procurement managers at institutional clients, kitchen equipment distributors, and regulatory compliance officers at Belgium's FASFC and Netherlands' NVWA supplied operational data. Secondary validation drew from EU Green Deal implementation reports, HACCP audit disclosure patterns, food hall development permits in Amsterdam-Rotterdam-Utrecht corridor, and corporate catering contract award notices in Luxembourg. Triangulation between operator-reported margin structures and buyer-side contract terms established volume and value estimates.
Input-output matrices map ingredient procurement through preparation to service delivery across segmentation dimensions including service format, customer type, product category, and delivery model. CAGRs derive from outlet expansion trajectories in urban food halls, contracted catering seat growth in healthcare and corporate segments, and platform-mediated delivery penetration rates. Forecast inputs incorporate labor cost harmonization schedules, EU packaging waste reduction compliance timelines, and real estate conversion patterns from retail to foodservice in Belgian and Dutch city centers.
The model holds under steady regulatory enforcement intensity and stable aggregator platform fee structures; deviation in FASFC audit frequency acceleration or NVWA traceability mandate expansion would shift compliance cost assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Meal Voucher Market
Food Service
Russia Foodservice Market
Food Service
Europe Cloud Kitchen Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Flat Top Grills Market
Food Service
Europe Food Service Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Shaker Bottles Market
Food Service
Online Grocery Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Commercial Griddle Market
Food Service
Workplace Service Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Ship Catering Service Market