
 United Arab Emirates Foodservice Market | 2026-2036
United Arab Emirates Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Foodservice Market Analytics
Meal bundling across quick service and catering formats is hardening as the dominant configuration pattern in the UAE foodservice landscape. Americana Restaurants International PLC leverages its multi-brand portfolio to sustain bundled offerings across mall and airport locations. Alamar Foods Company anchors its competitive stance through specialized pizza and chicken delivery infrastructure. Kamal Osman Jamjoom Group differentiates via controlled retail-foodservice integration across beauty and lifestyle destinations.
Foodservice encompasses the commercial preparation, assembly, and distribution of ready-to-consume meals through organized away-from-home channels, spanning temperature-controlled supply chains, standardized portion protocols, and real-time inventory management systems that ensure safety and consistency at scale. Quick service dominates transaction volume across the UAE, while full service captures disproportionate margin pools in Dubai's luxury hotel corridor. Online delivery channels are expanding fastest, though walk-in traffic retains structural importance in Abu Dhabi's institutional and retail-anchored locations.
MOHAP enforces food safety and hygiene standards across all commercial kitchen operations, while municipal authorities in Dubai and Abu Dhabi regulate licensing, waste management, and outdoor seating permissions. Compliance with these overlapping frameworks shapes capital deployment decisions for new kitchen builds and cloud facility expansions. Stakeholders must monitor how evolving delivery-platform regulations and sustainability mandates reshape last-mile economics and packaging requirements across emirate-level jurisdictions.
Market Dynamics
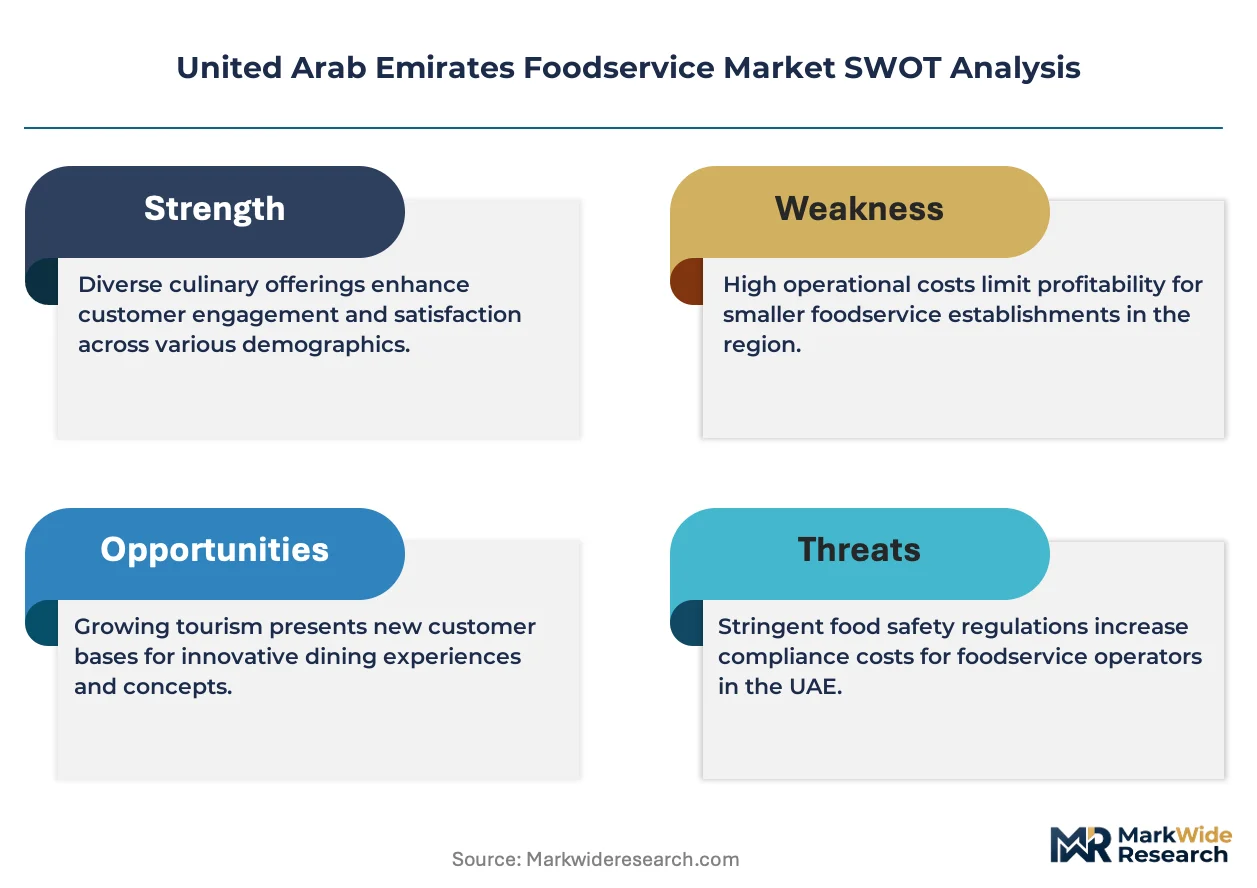
Cloud kitchen proliferation is compressing real estate requirements for UAE foodservice operators while MOHAP's food safety modernization raises compliance thresholds for multi-location brands. This structural tension between asset-light expansion and regulatory intensity defines capital allocation priorities across Dubai and Abu Dhabi.
Growth Catalysts
- MOHAP Food Safety Modernization:Standardized HACCP protocols reduce inspection friction for chains operating across multiple emirates. Large operators gain speed-to-market advantages through pre-certified kitchen designs.
- Corporate Catering Demand:Dubai International Financial Centre and Abu Dhabi Global Market tenants require bundled meal solutions for workforce feeding. Quick service operators capture recurring volume through contract structures.
- Airport Concession Expansion:Dubai Airports and Abu Dhabi International tender new F&B zones with revenue-sharing terms favoring established multi-brand portfolios. Premium positioning opportunities concentrate in transit corridors.
Market Restraints
- Imported Protein Cost Volatility:UAE foodservice depends on chilled beef and poultry shipments from Brazil, Australia, and India. Freight rate fluctuations compress margin predictability for steakhouse and burger formats.
- Labor Permit Quota Rigidity:Ministry of Human Resources and Emiratisation caps expatriate kitchen staffing ratios. Commissary automation requirements rise to maintain output per work visa.
- Cloud Kitchen Zoning Restrictions:Dubai Municipality limits dark kitchen clustering in residential districts. Operators face site scarcity in high-delivery-demand neighborhoods.
Strategic Opportunities
- Sharjah and Northern Emirates Penetration:Ajman and Ras Al Khaimah exhibit quick service density gaps relative to per-capita income growth. First-mover brands capture mall and highway service station anchorage.
- AI-Driven Demand Forecasting:Machine learning platforms reduce prepared-food waste in central commissaries. Integration with delivery aggregator data streams enables dynamic production scheduling.
- Extended Producer Responsibility Mandates:Dubai's single-use plastics reduction timeline accelerates compostable packaging adoption. Suppliers securing MOCCAE-approved biodegradable materials gain preferred vendor status.
Industry Challenges
- Multi-Emirate Licensing Complexity:Dubai Department of Economic Development and Abu Dhabi Department of Culture and Tourism maintain non-harmonized F&B permit requirements. Brands expanding across emirates duplicate compliance documentation.
- Talent Retention in Specialized Cuisine:Authentic Japanese and Levantine kitchen brigades command premium compensation. Training pipelines for Emirati culinary program graduates remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Foodservice Market |
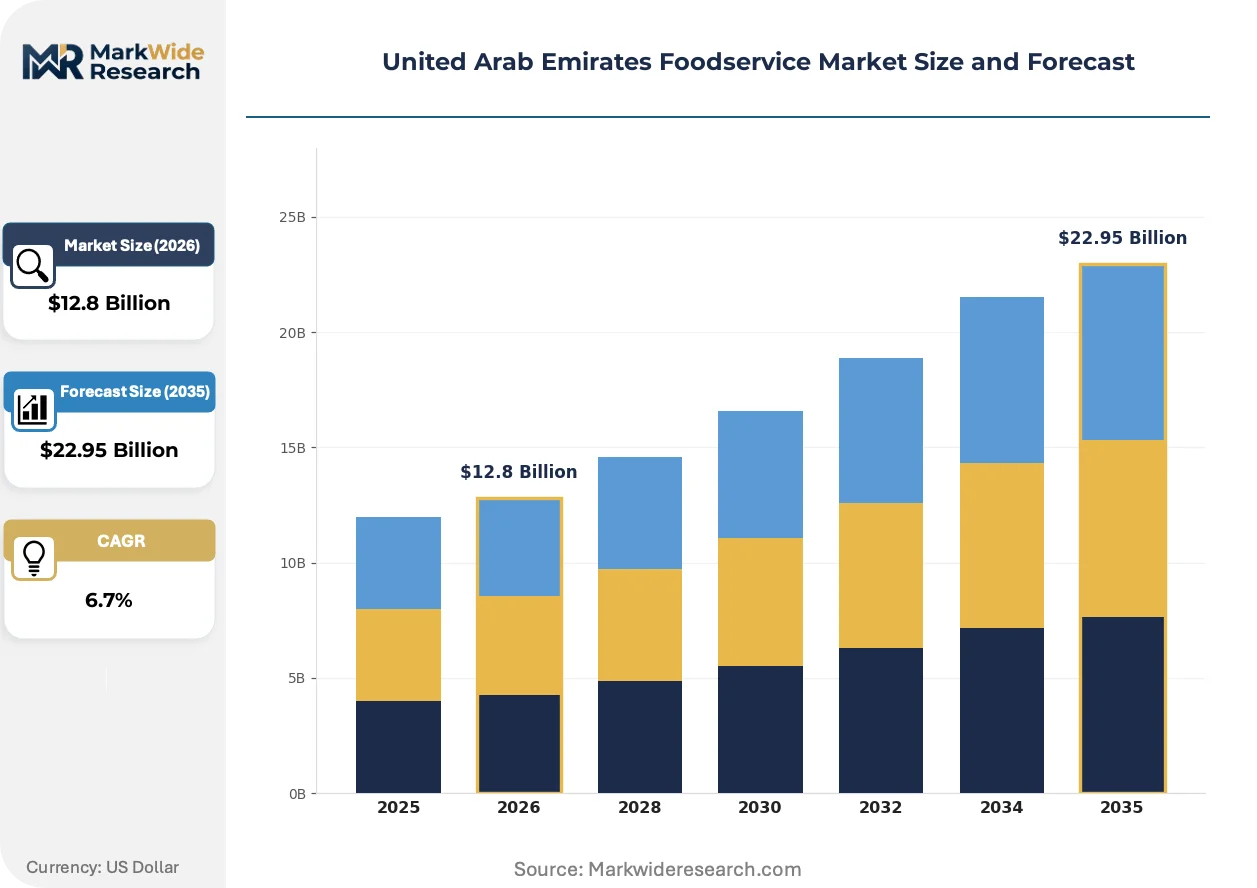
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service, Full Service, Cafés, Catering Customer Type: Restaurants, Hotels, Institutional, Retail Cuisine Type: Middle Eastern, Asian, Fast Food, International Delivery Channel: Online, Walk-in, Drive-thru, Takeaway |
| Companies Covered | Alamar Foods Company, Kamal Osman Jamjoom Group, Americana Restaurants International PLC, LuLu Group International, Rebel Foods, Apparel Group, The Olayan Group, Binhendi Enterprises, Al Khaja Group Of Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Foodservice Market Evolving Landscape
Operational technology deployment across UAE foodservice is compressing labor dependency while regulatory pressure on packaging and sourcing intensifies. Three interconnected shifts are restructuring competitive requirements.
Automated kitchen equipment is decentralizing production control from central commissaries to satellite locations. Robotic fry stations and automated beverage dispensers enable consistent output with reduced skilled labor. Full-service hotel operators in Dubai's hospitality corridor adopt these systems to maintain brand standards across property portfolios without chef density.
MOHAP's 2025 food traceability mandate requires blockchain-enabled supply chain documentation for high-risk categories. Large-scale catering contractors must implement lot-tracking systems from import through service. Hotel F&B departments in Abu Dhabi are prioritizing suppliers with pre-integrated compliance platforms to avoid procurement disruption.
Corporate procurement teams are consolidating vendor relationships through annual catering contracts with performance guarantees. Individual meal reimbursement models are contracting as facilities management firms bundle foodservice into integrated workplace contracts. This concentration is most visible in Dubai's free zone clusters where multinational tenants demand standardized service level agreements across global and regional headquarters locations.
United Arab Emirates Foodservice Market Segmentation
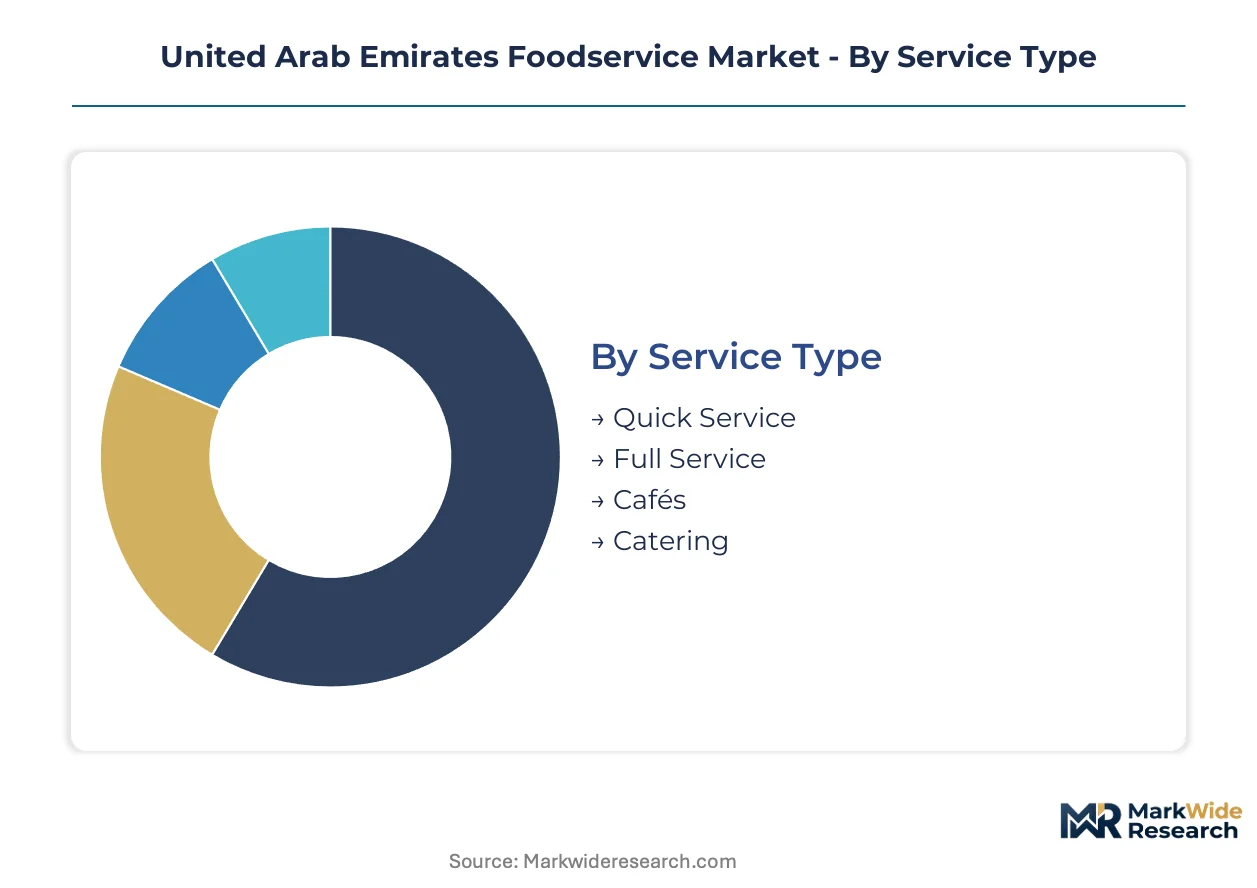
Segmentation in UAE foodservice reveals how operators balance standardized, scalable formats against customized, experience-driven propositions. Each dimension—service model, customer interface, cuisine positioning, and access channel—carries distinct capital requirements and regulatory exposure across Dubai, Abu Dhabi, and the Northern Emirates.
Service Type:
Customization spans from assembly-line standardization to bespoke preparation, with capital intensity and labor dependency varying sharply across the spectrum.
- Quick Service:High-throughput formats with standardized portion protocols and limited menu breadth dominate transaction volume. Dubai mall operators and airport concessionaires deploy these models to capture corporate catering contracts and transit passenger flows with minimal kitchen footprint.
- Full Service:Table-service establishments with extended preparation timelines anchor premium spend in Dubai's hotel hospitality corridor. These operations require chef brigades and front-of-house staffing that strain MOHAP compliance and labor permit quotas.
- Cafés:Beverage-forward formats with limited food assembly occupy retail-anchored locations in Abu Dhabi's institutional zones.
- Catering:Off-premise production for events and corporate contracts demands commissary infrastructure and HACCP-certified cold chains.
Leading the category by volume: Quick Service. Growing fastest: Catering.
Customer Type:
Cost tier differentiation separates high-frequency, low-margin channels from contract-anchored institutional relationships with pricing power.
- Restaurants:Standalone and mall-based operators serving walk-in and delivery customers across all emirates. Dubai's density of international dining destinations concentrates competition, while Sharjah and Ajman present whitespace for format replication.
- Hotels:Integrated F&B operations within Dubai's luxury hospitality corridor generate disproportionate margin pools through guest capture and event hosting. These properties face intensifying MOHAP traceability mandates for imported proteins.
- Institutional:Workplace, healthcare, and education feeding contracts in Abu Dhabi Global Market and Dubai International Financial Centre bundle meal solutions under multi-year agreements.
- Retail:Foodservice embedded within hypermarkets and convenience formats serves grab-and-go demand along highway corridors.
Commanding highest margins: Hotels. Expanding most quickly: Institutional.
Cuisine Type:
Application context—casual daily consumption versus occasion-driven dining—determines location strategy and supply chain configuration.
- Middle Eastern:Levantine and Emirati preparations dominate local preference, requiring specialized kitchen brigades that command premium compensation and complicate talent retention under Ministry of Human Resources and Emiratisation quotas.
- Asian:Japanese, Korean, and Southeast Asian formats cluster in Dubai's premium malls and hotel developments, with authentic preparation standards necessitating imported specialist labor.
- Fast Food:Burger, pizza, and fried chicken chains leverage centralized commissaries and delivery-aggregator integration for scale.
- International:Mediterranean, European, and fusion concepts target expatriate professional populations in free zone clusters.
Highest penetration: Middle Eastern. Steepest expansion trajectory: Asian.
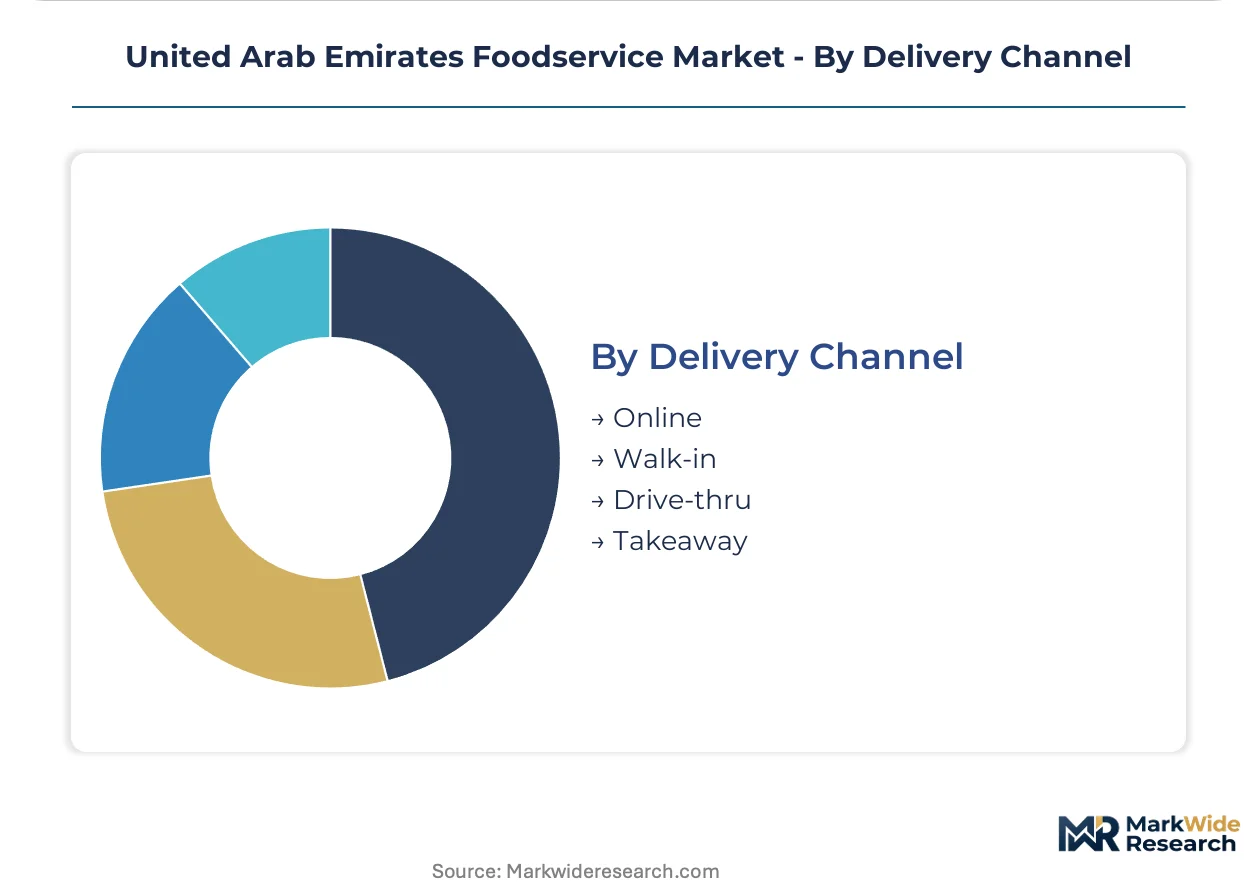
Delivery Channel:
Geographic concentration of demand—residential density versus transit corridors—shapes channel economics and real estate requirements.
- Online:Aggregator-mediated ordering with last-mile fulfillment through cloud kitchens or restaurant-operated dark facilities. Dubai Municipality zoning restrictions limit clustering in high-demand residential districts, compressing available sites.
- Walk-in:Physical patronage retains structural importance in Abu Dhabi's retail-anchored and institutional locations where facilities management firms bundle foodservice into integrated workplace contracts.
- Drive-thru:Vehicle-accessible formats concentrate along highway service stations and suburban corridors in Sharjah and Ras Al Khaimah.
- Takeaway:Counter pickup without dine-in seating occupies lower-rent retail positions with minimal front-of-house investment.
Dominating transaction growth: Online. Retaining margin stability: Walk-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in central commissaries and cloud kitchens serving Dubai and Abu Dhabi, while consumption spreads across all seven emirates with pronounced density in hospitality corridors. This geographic mismatch shapes logistics infrastructure and regulatory compliance costs.
Dubai
Hotel F&B and airport concessions anchor premium foodservice spend in the emirate's hospitality corridor. Dubai Municipality enforces zoning restrictions that limit dark kitchen clustering in residential districts. Dubai International Financial Centre tenants drive corporate catering demand through bundled meal contracts.
Abu Dhabi
Institutional feeding contracts in Abu Dhabi Global Market and government district facilities concentrate demand for standardized meal solutions. The Abu Dhabi Department of Culture and Tourism regulates F&B licensing with requirements distinct from Dubai's framework. Walk-in traffic retains structural importance in retail-anchored locations across the capital.
Sharjah
Quick service density gaps relative to per-capita income growth create whitespace for format replication in mall and highway service station locations. Sharjah's municipal authorities maintain separate permitting requirements from Dubai and Abu Dhabi. Industrial zone foodservice for manufacturing workforces presents underdeveloped contract catering opportunities.
Northern Emirates
Ajman and Ras Al Khaimah exhibit rising disposable income without proportional foodservice infrastructure expansion. Ras Al Khaimah's tourism development pipeline includes hotel F&B requirements that outpace local supplier capacity. Highway corridor locations between emirates capture transit passenger flows with limited competitive density.
United Arab Emirates Foodservice Market Competitive Landscape
The competitive structure tilts toward multi-brand portfolio operators with established mall and airport concession relationships. Large players leverage pre-certified kitchen designs to accelerate multi-emirate expansion under MOHAP's standardized HACCP protocols. Three archetypes dominate: integrated retail-foodservice hybrids, specialized delivery infrastructure operators, and global franchise license holders. Competitive moves concentrate on cloud kitchen site acquisition in high-delivery-demand neighborhoods and corporate catering contract consolidation.
Within the multi-brand portfolio tier, Americana Restaurants International PLC and Alamar Foods Company occupy positions shaped by mall anchorage and delivery specialization respectively. Kamal Osman Jamjoom Group exemplifies retail-foodservice integration across lifestyle destinations. These three entities represent distinct capital deployment strategies—franchise network scaling, delivery-first infrastructure, and controlled vertical integration—without any single approach commanding decisive share.
| Leading Market Players |
|---|
| Alamar Foods Company |
| Kamal Osman Jamjoom Group |
| Americana Restaurants International PLC |
| LuLu Group International |
| Rebel Foods |
| Apparel Group |
| The Olayan Group |
| Binhendi Enterprises |
| Al Khaja Group Of Companies |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap operators across Sharjah and Ras Al Khaimah exercise disciplined pricing through captive procurement relationships with Brazilian and Australian protein suppliers, while sovereign-backed hospitality groups in Dubai's hotel corridor absorb freight volatility through long-term contract structures that insulate premium F&B margins from spot market turbulence.
Pricing Analysis
Margin tightening in quick service formats reflects freight rate volatility on chilled beef and poultry shipments from Brazil, Australia, and India. Three-tier pricing structure across premium hotel F&B, standard mall quick service, and economy cloud kitchen delivery anchors the dominant model. Price differentiation separates MOHAP-certified operators with pre-integrated traceability platforms from uncertified competitors facing procurement disruption. Cost-down pressure on steakhouse and burger formats accelerates because facilities management firms consolidate vendor relationships through annual catering contracts with performance guarantees. Institutional buyers in Dubai International Financial Centre and Abu Dhabi Global Market exhibit lowest price sensitivity, while independent cloud kitchen operators competing for aggregator-mediated delivery demand face highest price elasticity.
Supply Chain Analysis
MOHAP's 2025 blockchain-enabled traceability mandate gates supplier qualification, forcing lot-tracking system investments from import through service. Geographic supply concentration centers on Brazil, Australia, and India for chilled beef and poultry, with secondary protein sourcing from regional GCC processors. Raw material dependencies include temperature-controlled shipping containers, specialized cold chain logistics providers, and MOCCAE-approved biodegradable packaging materials. Supply chain risk hinges on single-source vulnerability in specialized cuisine kitchen brigades commanding premium compensation under Ministry of Human Resources and Emiratisation quotas. Distribution runs through central commissaries serving multi-location brands, with satellite cloud kitchens handling last-mile fulfillment in high-delivery-demand neighborhoods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's food safety modernization operates as a cost-of-compliance story, erecting barrier-to-entry moats for operators with pre-certified kitchen designs while marginalizing smaller players unable to absorb HACCP protocol investments across multiple emirates.
For Market Incumbents: Acquire cloud kitchen real estate in Dubai's high-delivery-demand residential districts before municipal zoning restrictions harden site scarcity. Consolidate corporate catering contracts in Dubai International Financial Centre and Abu Dhabi Global Market through performance-guaranteed annual agreements that lock out emerging competitors. Threat substitution from delivery-aggregator platform fee escalation demands backward integration into proprietary last-mile fulfillment infrastructure.
For New Entrants and Emerging Players: AI-driven demand forecasting platforms reduce prepared-food waste in central commissaries, offering a technology-first wedge against incumbent operators with legacy production scheduling. Target Sharjah and Ras Al Khaimah quick service whitespace where per-capita income growth outpaces foodservice infrastructure density. Go-to-market through mall and highway service station anchorage captures first-mover advantage before established brands replicate format.
For Investors and Strategic Acquirers: Distressed-cycle entries favor MOHAP-pre-certified multi-brand portfolio operators in Dubai and Abu Dhabi facing temporary margin compression from imported protein cost volatility. Long-term viability over the analysis window rests on cloud kitchen site portfolios with defensible zoning positions and corporate catering contract backlogs. Signal to monitor: Dubai Municipality relaxation of dark kitchen clustering restrictions in residential districts, which would trigger asset revaluation for early site acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Site Acquisition | Pre-positions operators ahead of Dubai Municipality zoning scarcity in high-delivery-demand neighborhoods. |
| MOHAP Certification Investment | Accelerates multi-emirate expansion through standardized HACCP protocols reducing inspection friction. |
| Corporate Catering Contract Consolidation | Captures recurring volume from Dubai International Financial Centre and Abu Dhabi Global Market tenants. |
| AI-Driven Demand Forecasting Deployment | Reduces prepared-food waste through machine learning integration with delivery aggregator data streams. |
| Compostable Packaging Supplier Lock-Up | Secures MOCCAE-approved biodegradable materials preferred vendor status ahead of extended producer responsibility mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cloud kitchen operators, hotel F&B directors, corporate catering procurement managers, and MOHAP compliance officers. Bottom-up modeling triangulated against top-down emirate-level consumption estimates derived from Dubai Department of Economic Development and Abu Dhabi Department of Culture and Tourism licensing databases. Secondary sources included MOHAP food safety directives, Dubai Municipality zoning regulations, freight rate indices for chilled protein shipments, and delivery-aggregator platform disclosed transaction metrics.
Granularity-level framing applied segment-specific modeling across service type, customer interface, cuisine positioning, and delivery channel dimensions. CAGRs were derived from emirate-level population projections, per-capita foodservice spend trajectories, and corporate catering contract growth patterns. Industry-specific forecast inputs incorporated MOHAP traceability mandate implementation timelines and cloud kitchen site supply constraints under Dubai Municipality zoning restrictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged freight rate volatility or accelerated Ministry of Human Resources and Emiratisation expatriate staffing quota reductions. Model assumptions reflect MOHAP regulatory enforcement intensity and delivery-platform fee structure stability. A model refresh is warranted upon material change in Dubai Municipality cloud kitchen zoning policy or MOHAP food traceability mandate scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Egypt Food Service Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Food Service Utensils Market
Food Service
Food Service Market
Food Service
UAE Food Service Market
Food Service
Bahrain Food Service Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
GCC Food Service Market
Food Service
Air Fryer Market
Food Service
Inflight Catering Market
Food Service
Quick-Service Restaurants Market
Food Service
Europe Cloud Kitchen Market
Food Service
Latin America Online Grocery Market
Food Service
Food and Grocery Retail Market