
 Quick-Service Restaurants Market | 2026-2036
Quick-Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Quick-Service Restaurants Market Analysis
ISO 22000 food safety management certification is reorganizing competitive access across the quick-service restaurant sector. McDonald's leverages its captive supply chain to maintain consistency across thousands of locations. Domino's anchors its position through proprietary delivery logistics technology. KFC differentiates with localized menu engineering that navigates diverse regulatory environments.
Quick-service restaurants are commercial foodservice establishments characterized by limited menu breadth, standardized preparation protocols, and service times typically under three minutes from order to handoff. Their primary purpose is delivering caloric and convenience value to time-constrained consumers through high-throughput, low-price-point transactions. Burgers and pizza segments carry mature margin pools sustained by decades of brand equity and operational refinement. The delivery service type captures the fastest structural expansion as third-party platform economics and native app infrastructure reshape customer acquisition. Value-tier pricing occupies disproportionate volume share in emerging markets where price elasticity drives trial and frequency.
FDA food code standards, municipal health department grading systems, and EU Green Deal packaging directives collectively elevate compliance costs while filtering out subscale operators. OSHA kitchen safety protocols and local fire suppression mandates further shape facility design and labor deployment. Stakeholders must monitor how AI-driven labor scheduling intersects with evolving minimum wage frameworks across multiple jurisdictions.
Market Dynamics
Digital ordering platforms are restructuring customer acquisition economics across the quick-service restaurant sector, compressing traditional location-based traffic models while elevating data monetization capabilities. The tension between third-party aggregator fees and native app infrastructure investments dominates capital allocation decisions.
Growth Catalysts
- ISO 22000 Certification:Food safety management standards are filtering out subscale operators and consolidating competitive access among certified chains in the European Union and North America.
- Cloud Kitchen Infrastructure:Delivery-optimized production facilities are expanding addressable markets without real estate premiums, particularly in China's tier-one urban clusters.
- Municipal Plastic Bans:Packaging compliance mandates in California, France, and Germany are accelerating biodegradable material adoption and reshaping supplier relationships.
Market Restraints
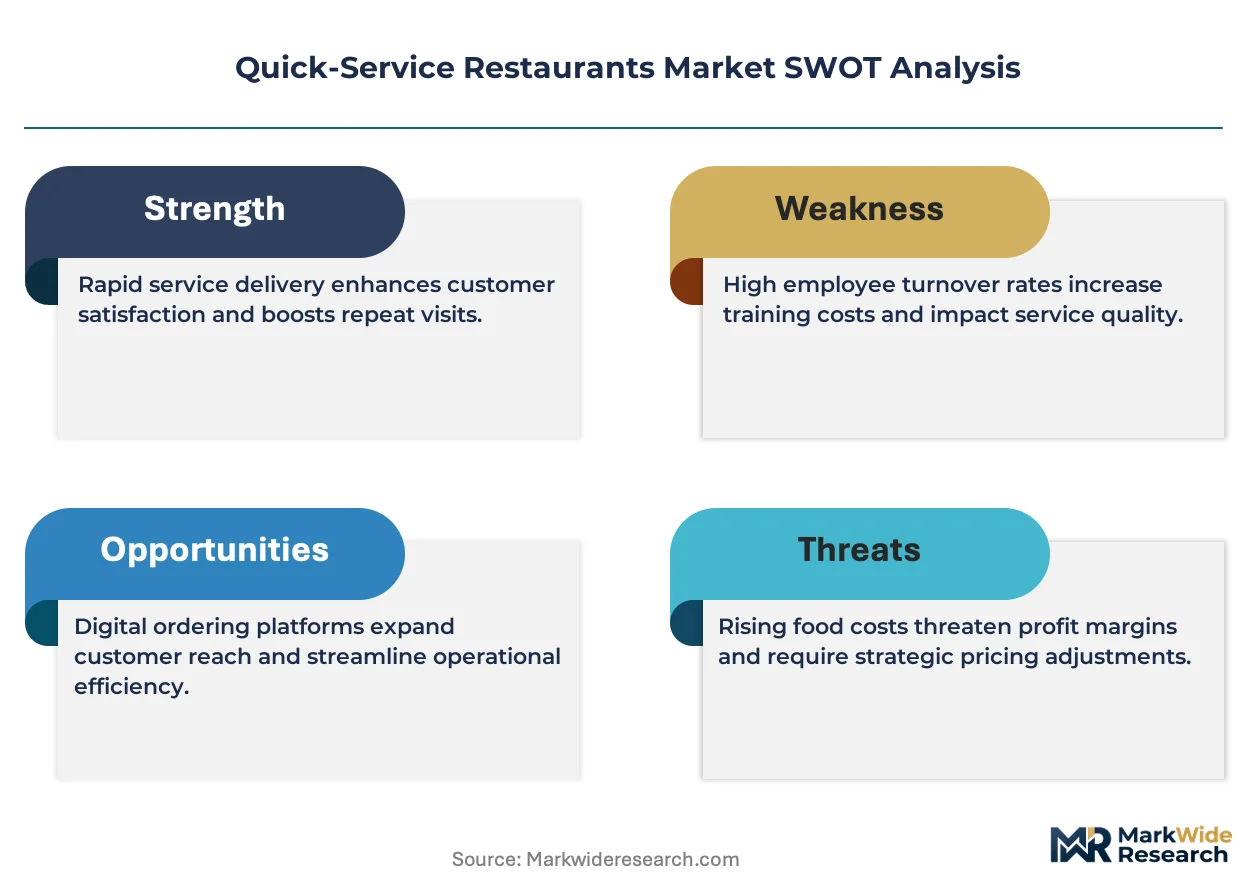
- Protein Input Volatility:Beef and poultry commodity price swings compress margin predictability for burger and chicken-centric operators across multiple jurisdictions.
- Third-Party Platform Concentration:Delivery aggregator duopolies in major metropolitan markets extract 15-30% commission structures that erode unit economics.
- Refrigerant Transition Costs:F-Gas Regulation compliance in Europe and EPA SNAP program requirements in the United States necessitate equipment retrofit capital.
Strategic Opportunities
- India Tier-Two Urban Expansion:Underpenetrated secondary cities present whitespace for value-tier formats as disposable income rises and working-hour compression accelerates.
- AI-Driven Labor Scheduling:Machine learning workforce optimization converging with predictive demand forecasting reduces overtime exposure and improves throughput.
- EU Green Deal Packaging Incentives:Circular economy subsidies and extended producer responsibility frameworks reward early movers in compostable packaging.
Industry Challenges
- Kitchen Automation Talent Scarcity:Maintenance technicians for robotic fry stations and automated beverage systems command premium wages and limited labor pool depth.
- Multi-Jurisdiction Wage Compliance:Divergent minimum wage frameworks across municipal, state, and federal layers complicate unified labor cost modeling.
- Legacy POS Integration Friction:Cloud-native ordering stacks require expensive middleware to communicate with decades-old franchisee back-office systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quick-Service Restaurants Market |
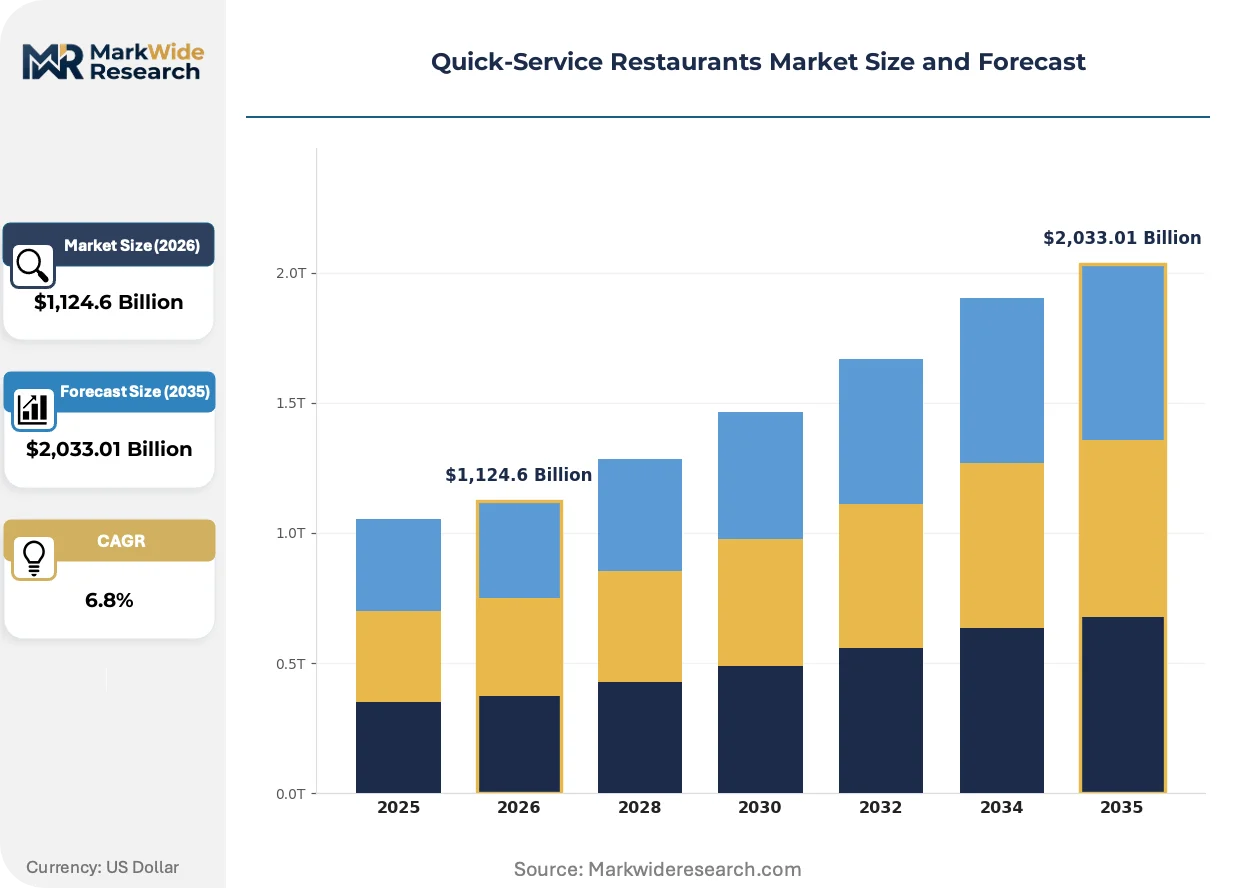
| Market Size in 2026 | $1,124.6 Billion |
| Market Size in 2035 | $2,033.01 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sandwiches, Pizza, Salads Service Type: Dine-in, Takeaway, Delivery, Drive-thru Customer Type: Families, Business Professionals, Students, Tourists Price Tier: Economy, Mid-range, Premium, Value |
| Companies Covered | Subway, Luckin Coffee, Mixue Ice Cream & Tea, Raising Cane's, Domino's, McDonald's, KFC, Jersey Mike's, Starbucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quick-Service Restaurants Market Emerging Trajectories
Operational technology is converging with consumer-facing digital infrastructure to compress service times while expanding menu personalization capabilities. Three developments are restructuring competitive positioning.
Computer vision quality control systems are supplanting manual inspection protocols at production lines. Major chains deploy camera arrays that assess burger assembly accuracy and fry color consistency in real time. This compression of human oversight is enabling 24-hour operations with reduced supervision labor.
EU Green Deal packaging directives are mandating fiber-based alternatives to petroleum-derived containers. Industrial consequence includes reformulation of hot-food packaging to maintain structural integrity above 80°C. QSR operators in Germany, France, and the Netherlands are accelerating supplier qualification timelines to meet 2025 compliance windows.
Subscription-based meal programs are displacing transactional purchasing among urban professional segments. Chains in Seoul, Tokyo, and Shanghai bundle daily coffee and lunch credits through mobile wallets. This behavioral pivot locks frequency and reduces customer acquisition cost volatility for operators with dense urban footprints.
Quick-Service Restaurants Market Segmentation
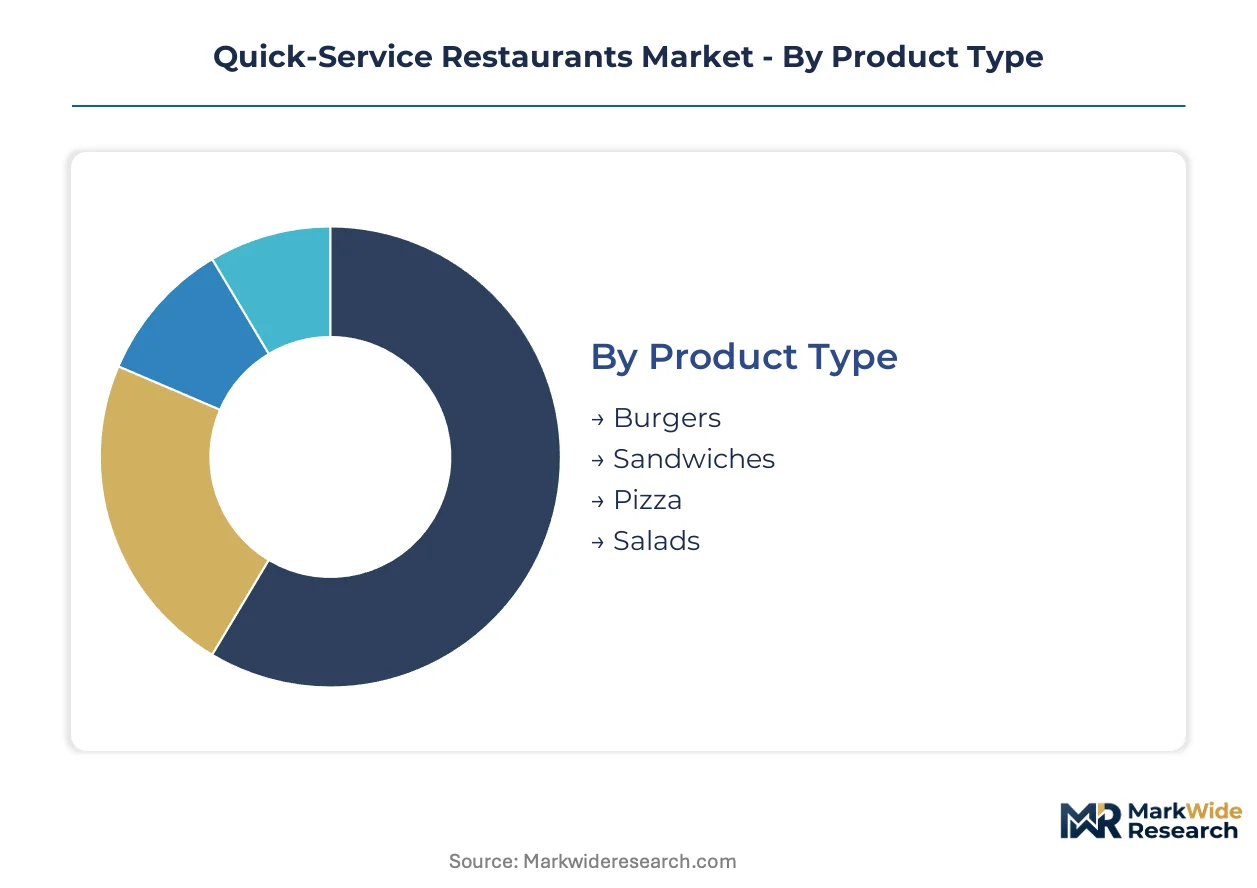
Segmentation in quick-service restaurants reveals how operational format and price positioning filter customer access. Operators configure supply chains and labor models differently across these dimensions, creating distinct margin architectures that resist easy substitution.
Product Type:
Burger and pizza formats face the most acute substitution pressure from cloud kitchens and convenience retail, while salad and sandwich specialists defend through health-positioned differentiation.
- Burgers:Ground beef patties with standardized bun specifications dominate throughput economics. Demand concentrates in US Sun Belt metropolitan corridors where drive-thru lane capacity determines market share. Commodity beef volatility and labor-intensive assembly constrain margin expansion.
- Pizza:Yeast-leavened dough platforms with modular topping configurations sustain delivery-optimized production. Demand clusters in European urban agglomerations where dinner occasion frequency supports dedicated ovens. Third-party platform commission structures erode operator profitability.
- Sandwiches:Cold-cut and grilled protein configurations on sliced bread or flatbread substrates.
- Salads:Raw vegetable and protein bowl assemblies with refrigerated supply chain dependencies.
Burgers retain volume leadership; salads hold the steepest expansion curve.
Service Type:
Cost tier stratification separates capital-light formats from real estate-intensive models, with delivery infrastructure commanding premium technology investment.
- Delivery:Third-party platform and native app order fulfillment with off-premise consumption. Cloud kitchen penetration in Shanghai and Seoul reduces real estate burden while expanding addressable radius.
- Drive-thru:Vehicle-based order and pickup lanes with dedicated menu boards and payment windows. US suburban and exurban development patterns sustain lane throughput optimization.
- Dine-in:On-premise consumption with seating capacity and facility maintenance requirements.
- Takeaway:Counter order with off-premise consumption and minimal service labor.
Drive-thru retains volume leadership; delivery holds the steepest expansion curve.
Customer Type:
Application context determines daypart concentration and transaction frequency, with business professionals driving weekday lunch density and families anchoring weekend volume.
- Business Professionals:Time-compressed weekday lunch occasions with mobile pre-ordering preferences. Tokyo and London financial districts sustain premium grab-and-go formats with subscription bundling.
- Families:Multi-person transactions with children's menu requirements and play area amenities. US highway corridor locations capture interstate travel occasions.
- Students:Price-elastic demand with value-tier sensitivity and campus proximity requirements.
- Tourists:Occasional trial with location convenience and menu familiarity priorities.
Families retain volume leadership; business professionals hold the steepest expansion curve.
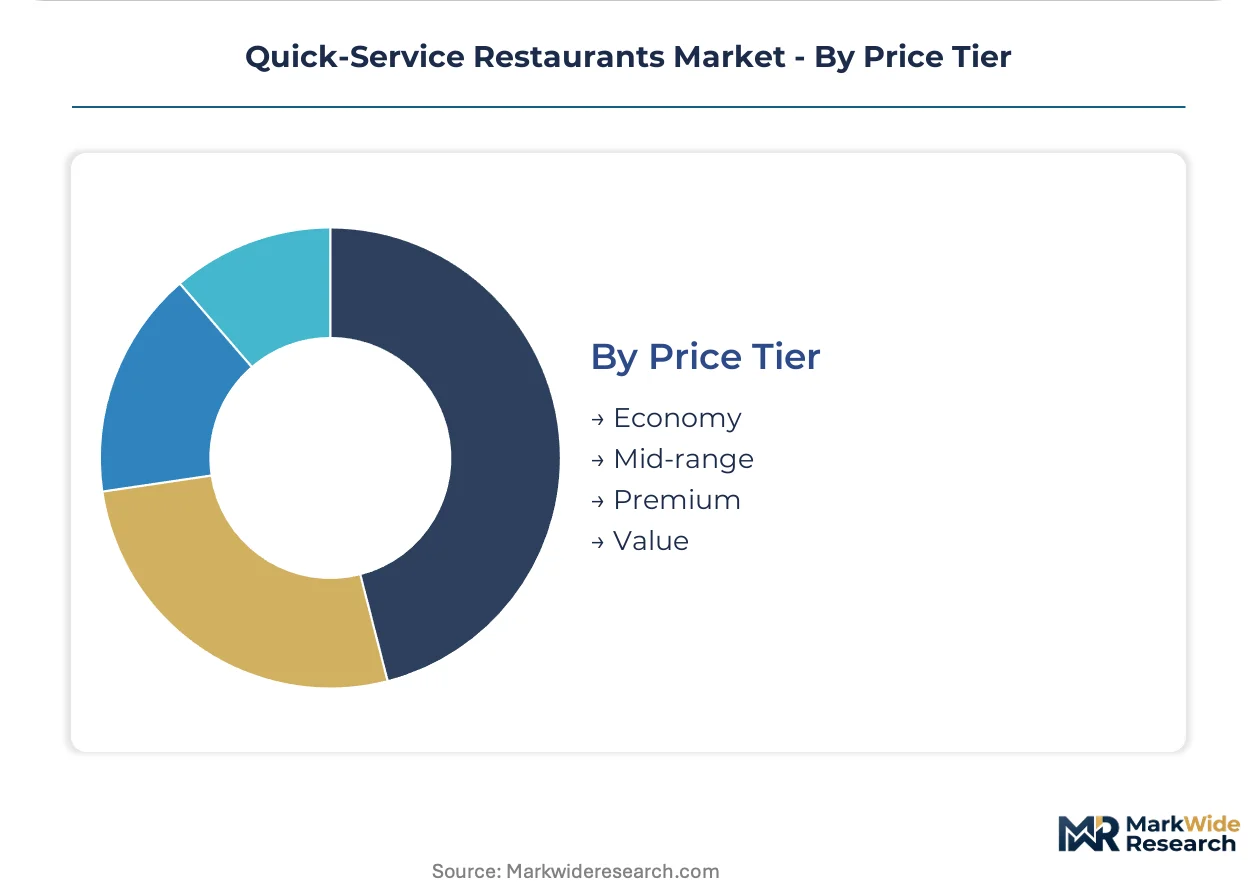
Price Tier:
Margin structure varies dramatically across tiers, with economy operators defending through supply chain scale and premium formats extracting surplus through ingredient provenance.
- Value:Sub-dollar menu pricing with limited item counts and extreme throughput optimization. India's tier-two cities sustain expansion as disposable income rises.
- Economy:Low-price positioning with standardized portions and minimal customization.
- Mid-range:Moderate pricing with modest ingredient upgrades and broader menu breadth.
- Premium:Elevated price points with chef-driven formulations and dine-in experience investment.
Value retains volume leadership; premium holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging incentives and municipal plastic bans across multiple jurisdictions are redirecting capital toward compliant supply chains. FDA menu labeling enforcement and ISO 22000 certification requirements are elevating operational barriers. Cloud kitchen proliferation in dense urban clusters is compressing real estate costs while expanding service radii.
United States
Drive-thru lane optimization and subscription bundling dominate capital deployment in Sun Belt metropolitan corridors. FDA food code standards and OSHA kitchen safety protocols elevate facility design costs. Dallas-Fort Worth and Atlanta sustain aggressive expansion as exurban development patterns concentrate traffic volume.
China
Digital wallet integration and tier-one city working-hour compression sustain transaction frequency growth. SAMR food safety inspections and municipal environmental compliance tighten operational standards. Shanghai and Beijing cloud kitchen clusters reduce real estate premiums while expanding delivery radii beyond traditional catchment zones.
Germany
F-Gas Regulation refrigerant transition and EU Green Deal packaging mandates compress margin structures for legacy operators. ECHA chemical compliance and extended producer responsibility frameworks reward early movers in compostable materials. Berlin and Munich drive-thru modernization captures suburban commuter density.
India
Disposable income growth in tier-two urban centers creates whitespace for value-tier format expansion. FSSAI food safety licensing and state-level municipal health codes filter subscale entrants. Bangalore and Hyderabad technology corridor proximity sustains business professional demand density with mobile pre-ordering preferences.
Japan
Subscription-based meal programs and grab-and-go format density anchor urban professional retention. METI energy efficiency standards and PMDA food additive regulations shape ingredient sourcing. Tokyo financial district and Osaka commercial zones sustain premium positioning with dense urban footprints.
Quick-Service Restaurants Market Vendor Landscape
Player mix skews toward diversified global chains with captive supply infrastructure and regional specialists with format-specific density. Market structure concentrates around three archetypes: vertically integrated operators controlling upstream protein and packaging inputs, technology-forward chains deploying proprietary logistics software, and value-tier specialists optimizing throughput in emerging market urban corridors. Dominant competitive moves include cloud kitchen network expansion and AI-driven labor scheduling platform deployment.
Among diversified global operators, McDonald's exemplifies supply chain vertical integration, Domino's anchors delivery logistics technology specialization, and KFC represents localized menu engineering adaptation. These three occupy distinct competitive positions without direct format overlap. Regional density specialists include Luckin Coffee in Chinese tier-one urban clusters and Mixue Ice Cream & Tea in value-tier expansion markets. Subway and Jersey Mike's sandwich formats compete on customization speed rather than production technology differentiation.
| Leading Market Players |
|---|
| Subway |
| Luckin Coffee |
| Mixue Ice Cream & Tea |
| Raising Cane's |
| Domino's |
| McDonald's |
| KFC |
| Jersey Mike's |
| Starbucks |
| Others |
Supply Flow & Price Mechanics
Long-term protein supply contracts with take-or-pay provisions lock in cost visibility for burger and chicken-centric operators across North American and European markets, insulating unit economics from commodity spot volatility while constraining menu flexibility.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-certified chains and subscale independents, with EU Green Deal compliance adding a secondary tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient provenance and digital integration depth. Pricing pressure stems from third-party delivery platform commissions eroding operator margins. Value-tier consumers in India's tier-two cities exhibit highest price sensitivity; Tokyo business professionals show lowest elasticity due to subscription bundling.
Supply Chain Analysis
Strait of Hormuz transit risk concentrates edible oil and spice import dependencies for Middle Eastern and South Asian QSR networks. Protein inputs draw from Brazil, the United States, and Thailand; packaging materials hinge on Chinese manufacturing clusters. Single-source vulnerability in biodegradable container supply chains intensifies as EU Green Deal deadlines approach. Distribution runs through captive cold-chain networks for vertically integrated chains and third-party logistics for emerging operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quick-service restaurants operate as a defensive-moat sector where regulatory entrenchment through ISO 22000 certification and FDA compliance creates sustainable barriers against subscale competitors.
For Market Incumbents: Shield market position through backward integration into protein processing and accelerated cloud kitchen deployment in Shanghai and Seoul clusters. Third-party platform commission structures and municipal plastic bans represent acute threats requiring certification investment and supplier relationship restructuring. For New Entrants and Emerging Players: Anchor in India's tier-two urban corridors and Southeast Asian secondary cities where value-tier whitespace persists. Cloud kitchen formats with native app infrastructure offer the most penetrable entry vector against established real estate-heavy competitors. For Investors and Strategic Acquirers: Capital is best deployed toward technology-forward chains with proprietary logistics software and dense urban footprints across the analysis window. Acquisition targets should demonstrate AI-driven labor scheduling capabilities and subscription program traction. Watch third-party platform fee regulation as the critical inflection signal for unit economics revision.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Network Expansion | Reduces real estate burden while extending delivery radius beyond traditional catchment zones in tier-one cities. |
| AI-Driven Labor Scheduling Deployment | Optimizes workforce allocation against predictive demand curves, reducing overtime exposure in high-wage jurisdictions. |
| ISO 22000 Certification Investment | Filters subscale competitors from European Union and North American market access through compliance barriers. |
| Biodegradable Packaging Transition | Secures EU Green Deal compliance and circular economy subsidies ahead of 2025 regulatory windows. |
| Subscription Program Launch | Locks customer frequency and reduces acquisition cost volatility among urban professional segments. |
Methodological Framework
Desk research of SEC filings, customs trade databases, and municipal health department records preceded structured interviews with QSR operations directors, supply chain procurement leads, franchise development executives, and third-party platform account managers. Primary fieldwork across United States, China, Germany, India, and Japan markets combined with secondary validation from FDA food code documentation, EU Green Deal regulatory texts, and SAMR inspection protocols. Bottom-up unit economics modeling triangulated against top-down market sizing from trade association data.
Variance decomposition across product type, service format, customer segment, price tier, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs derived from historical trajectory analysis and structural growth factor weighting. Forecast inputs incorporated cloud kitchen penetration curves, digital wallet adoption rates, and protein commodity price cycle positioning.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued platform commission structures; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as municipal wage frameworks and refrigerant transition timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Restaurant Griddle Market
Food Service
Mobile Food Services Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Commercial Griddle Market
Food Service
Limited-Service Restaurants Market
Food Service
Meal Voucher Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Commercial Air Fryer Market
Food Service
Kuwait Food Service Market
Food Service
Commercial Cutlery Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Food Service Gloves Market
Food Service
Commercial Tableware Services Market
Food Service
Light Meal Market