
 Commercial Steam Table Market | 2026-2036
Commercial Steam Table Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Steam Table Market Outlook
Modular configuration is decoupling steam table purchasing from full kitchen suite decisions, letting buyers mix manufacturers across stations. Vollrath Company leverages its broad distribution network to capture replacement-cycle demand in institutional kitchens. Duke Manufacturing anchors its position through captive fabrication of stainless steel bases and welded frames. APW Wyott differentiates with specialized heating-element engineering for high-volume buffet operations.
A commercial steam table is a thermostatically controlled foodservice appliance that maintains prepared food at safe serving temperatures between 140°F and 185°F using moist heat from an open or sealed water reservoir, typically constructed from 14- to 16-gauge stainless steel with fiberglass or mineral-wool insulation. Floor models dominate capital expenditure budgets in hotel banquet installations where permanent infrastructure supports heavy throughput. Portable units represent the fastest-growing configuration as catering operators seek flexible equipment for off-premise events and ghost kitchen pop-ups. Stainless steel commands the material mix due to NSF sanitation compliance and resistance to chloride pitting from acidic foods.
The US Food and Drug Administration's Food Code provisions on hot-holding temperatures directly shape steam table thermostat calibration requirements and operator training protocols. NSF International certification governs equipment approval for school cafeteria and healthcare foodservice bids, creating a gatekeeping function for market access. The Department of Energy's test procedures for commercial kitchen equipment are tightening standby energy consumption limits, forcing redesigns of heating element geometry and control logic. Stakeholders must monitor how evolving efficiency standards interact with durability expectations in 24-hour casino and airport food operations.
Market Dynamics
The US Department of Energy's tightening standby energy consumption limits are forcing redesigns of heating element geometry and control logic across the commercial steam table manufacturing base.
Growth Catalysts
- Full-service restaurant expansion:Buffet format rollouts across North American foodservice chains are pulling capital expenditure toward permanent floor-model installations in new construction.
- FDA Food Code alignment:Hot-holding temperature provisions are mandating thermostat calibration investments that favor replacement-cycle demand over repair.
- Southern US construction activity:Hotel development and foodservice construction in Texas, Florida, and Georgia are concentrating demand for heavy-throughput banquet infrastructure.
Market Restraints
- Stainless steel input volatility:14- to 16-gauge 304-grade sheet pricing fluctuations compress margin visibility for NSF-certified fabricators.
- Heating element supply concentration:Specialized mineral-insulated cable production clusters in East Asian manufacturing zones create single-source vulnerability.
- Substitution by induction warming:Dry-heat alternatives eliminate water reservoir maintenance but sacrifice moisture retention in protein holding.
Strategic Opportunities
- Ghost kitchen proliferation:Portable steam table configurations serve pop-up and delivery-only operations requiring rapid deployment without fixed infrastructure.
- Modular station mixing:Decoupled purchasing from full kitchen suite decisions lets buyers source specialized buffet equipment independent of primary cooking line vendors.
- DOE efficiency standard advancement:Improved insulation and heating element designs open differentiation for early-compliant manufacturers in institutional bidding.
Industry Challenges
- NSF certification timeline compression:School cafeteria and healthcare foodservice bids require current certification cycles that lag product development schedules.
- Integration with legacy banquet infrastructure:Existing hotel kitchen layouts constrain dimensional flexibility for new equipment specifications.
- 24-hour operation durability expectations:Casino and airport food operations demand heating element longevity that exceeds standard warranty coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Steam Table Market |
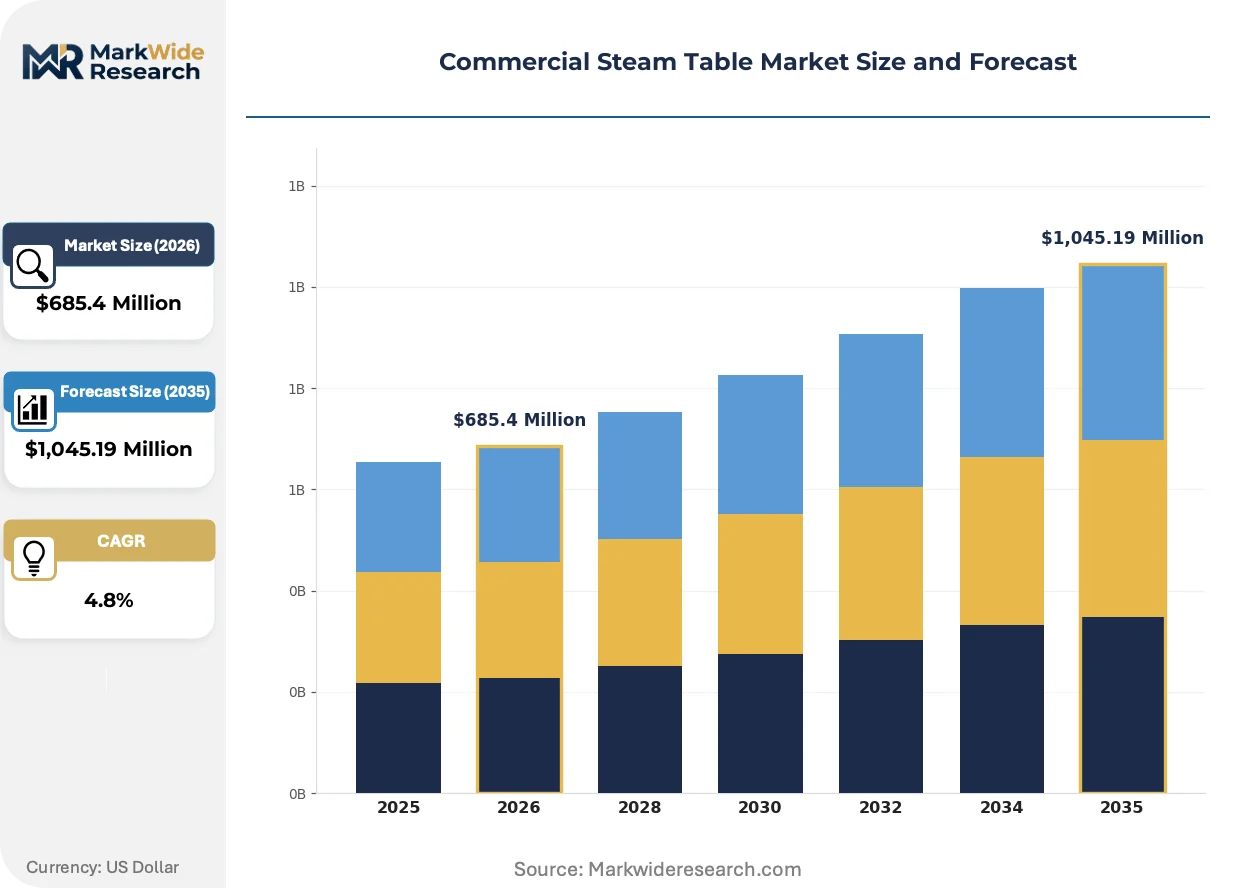
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor Model, Portable, Custom Built End User: Restaurants, Catering Services, Hotels, Cafeterias Application: Buffet Service, Food Holding, Cooking, Food Preparation Material: Stainless Steel, Aluminum, Glass, Plastic |
| Companies Covered | Advance Tabco, Duke Manufacturing, Vollrath Company, APW Wyott, Cres Cor, Winco, Eagle Group, Hatco Corporation, Vulcan Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Steam Table Market Strategic Shifts
Equipment design is pivoting toward energy recovery and connectivity as regulatory pressure intersects with labor cost constraints in high-volume foodservice operations.
Induction-assisted hybrid steam tables are absorbing standby energy losses through closed-loop heat recovery systems that redirect exhaust thermal energy back into the water reservoir. Casino buffet operators in Nevada and Atlantic City are piloting these configurations to maintain 24-hour throughput without the penalty of continuous element cycling. The technology is absorbing capital allocation that previously flowed to conventional gas-fired holding equipment.
The US Department of Energy's test procedures for commercial kitchen equipment are compressing allowable standby power draws below 1.0 kW for large-capacity units. Manufacturers are responding with segmented heating zones that activate only when food pans are detected, reducing baseline consumption during idle periods. Floor-model producers serving hotel banquet installations face the steepest redesign burden as these units carry the highest thermal mass.
Equipment-as-a-service contracts are displacing outright purchase in catering and event rental channels, unbundling maintenance and calibration from capital budgets. Off-premise event operators in Florida and Texas are favoring monthly subscription models that include portable unit rotation and NSF compliance verification. This shift concentrates fleet ownership among specialized rental companies while fragmenting end-user procurement authority.
Commercial Steam Table Market Segmentation
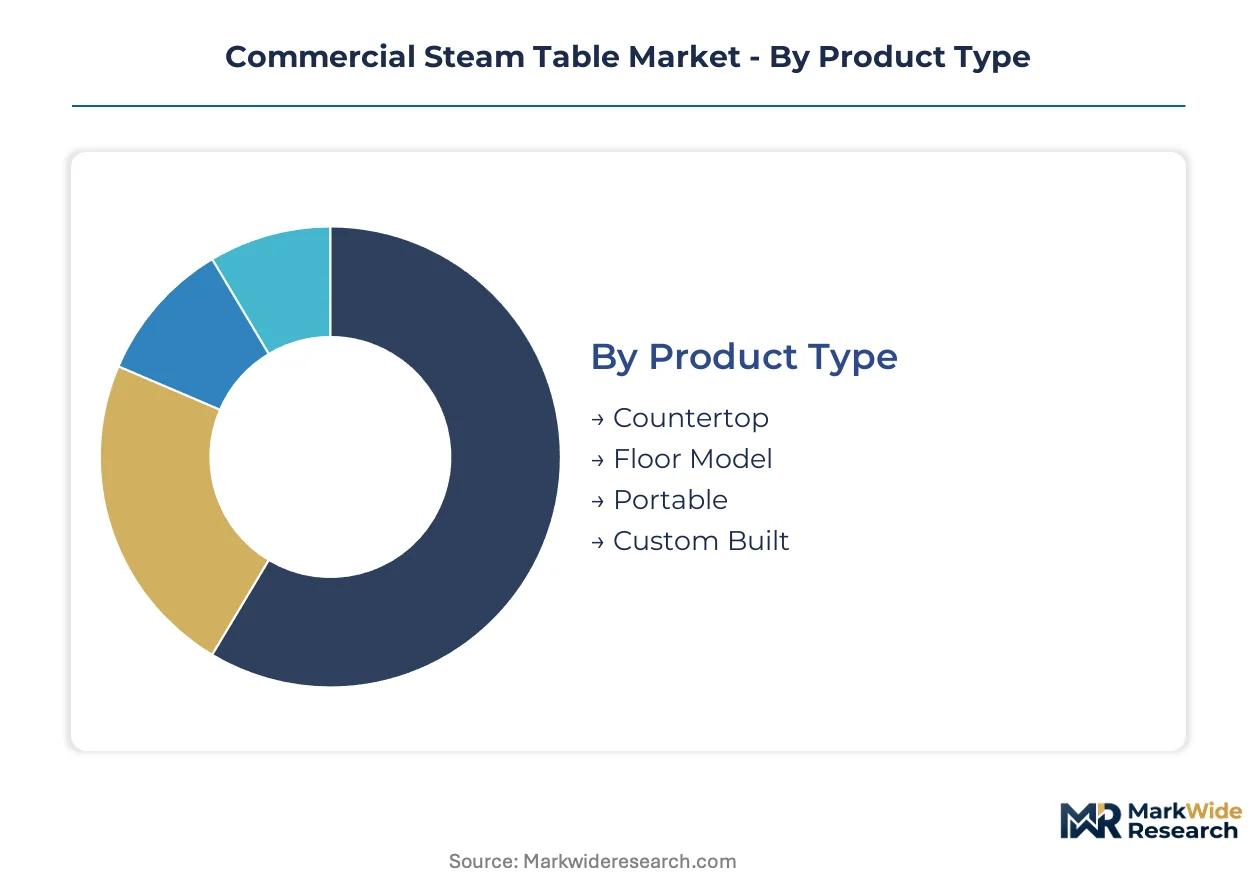
Steam table purchasing decisions fragment across equipment mobility, thermal performance requirements, and sanitation compliance tiers. Each segmentation axis carries distinct specification standards and channel dynamics that shape manufacturer positioning.
Product Type:
Thermal mass and installation permanence define the specification hierarchy across commercial steam table configurations.
- Floor Model:Permanent installations with welded stainless steel frames and integrated plumbing dominate hotel banquet halls and institutional cafeterias where throughput exceeds 500 covers per service. Capital expenditure concentration in Texas and Florida hotel construction sustains demand for heavy-duty welded construction with mineral-wool insulation.
- Portable:Castor-mounted units with detachable electrical connections serve catering operators and ghost kitchen pop-ups requiring rapid deployment without fixed infrastructure. Off-premise event growth in southern US metropolitan areas drives replacement cycles for NSF-certified portable configurations with lighter gauge stainless construction.
- Countertop:Compact units with reduced well depth fit existing kitchen lines where floor space constraints prohibit full-size installations.
- Custom Built:Fabricated-to-specification units accommodate irregular architectural dimensions in legacy hotel kitchen renovations.
Floor models lead on scale; portable units lead on momentum.
End User:
Volume throughput and operating hour intensity separate procurement specifications across foodservice channels.
- Hotels:Banquet departments demand 24-hour rated heating elements and redundant thermostat systems for continuous service in Nevada and Atlantic City casino properties. DOE standby efficiency compliance adds specification complexity for large-capacity floor installations.
- Restaurants:Full-service chains expanding buffet formats across North America pull capital toward permanent installations with calibrated thermostat precision for FDA Food Code alignment.
- Catering Services:Mobile operators prioritize rapid deployment and subscription-based fleet access over capital ownership.
- Cafeterias:School and healthcare foodservice bids require current NSF certification cycles that compress vendor qualification timelines.
Hotels lead on scale; catering services lead on momentum.
Application:
Moisture retention requirements and temperature stability tolerances differentiate functional deployment.
- Buffet Service:Open-well configurations with visible food presentation demand precise thermostat calibration between 140°F and 185°F for protein safety. Casino operators pilot induction-assisted hybrid systems with closed-loop heat recovery to maintain continuous service without excessive standby consumption.
- Food Holding:Back-of-house sealed-well units prioritize thermal stability over presentation for kitchen staging and line support.
- Cooking:High-output steam table variants with elevated wattage density support limited rethermalization functions in constrained kitchen footprints.
- Food Preparation:Dual-temperature zones accommodate both hot holding and controlled cooling for prep-line workflow integration.
Buffet service leads on scale; food holding leads on momentum.
Material:
Corrosion resistance and sanitation compliance drive material selection against chloride exposure from acidic foods.
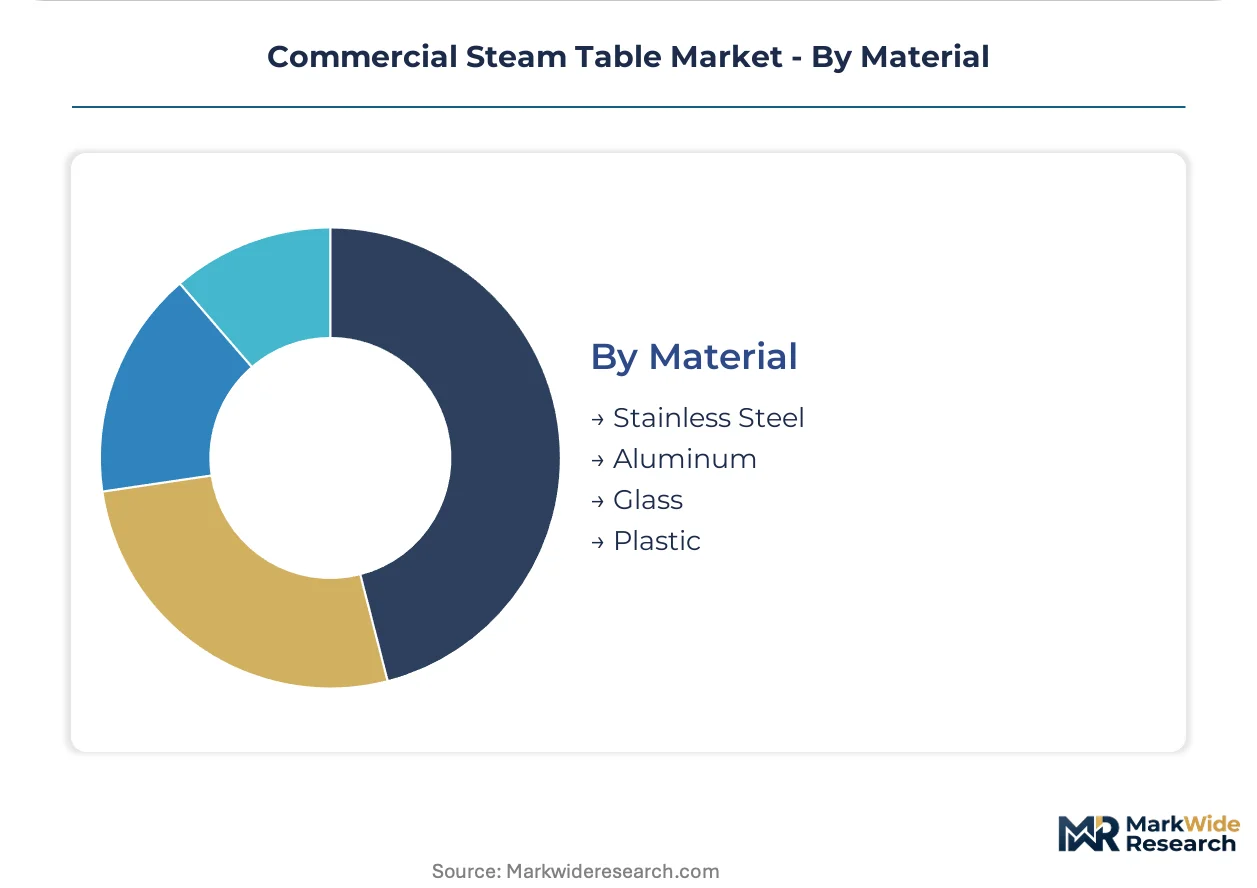
- Stainless Steel:14- to 16-gauge 304-grade construction with NSF certification dominates institutional procurement due to pitting resistance and weldability. Input price volatility for sheet steel compresses margin visibility for certified fabricators.
- Aluminum:Lighter weight alternative for portable configurations where thermal conductivity trade-offs are acceptable for reduced mobility burden.
- Glass:Tempered sneeze guard panels and display surfaces integrate with stainless bases for front-of-house buffet presentation.
- Plastic:Polypropylene well inserts and handle components reduce conductive heat transfer in operator touch points.
Stainless steel leads on scale; aluminum leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial steam table manufacturing originated in the American Midwest during the post-war institutional foodservice expansion, with Wisconsin and Ohio metalworking clusters establishing the welded stainless steel fabrication standards that still govern NSF certification requirements today.
United States
Hotel construction in Texas and Florida drives heavy-throughput floor-model demand for casino and resort banquet operations. The Department of Energy's standby energy consumption limits below 1.0 kW for large-capacity units force heating element redesigns across domestic fabricators. Atlanta and Dallas-Fort Worth anchor distribution networks serving institutional kitchen replacement cycles.
Germany
Precision engineering traditions in commercial kitchen equipment concentrate fabrication expertise in North Rhine-Westphalia and Baden-Württemberg. REACH chemical regulations govern insulation material selection and heating element coatings for EU market access. The Mittelstand sector of family-owned metalworkers supplies modular steam table components to pan-European foodservice distributors.
China
Guangdong and Zhejiang provinces host component manufacturing clusters for mineral-insulated heating cables and stamped stainless steel wells. GB standards for commercial kitchen equipment safety shape export-oriented production for Southeast Asian and Middle Eastern markets. Ningbo and Foshan serve as primary export hubs for cost-competitive portable configurations.
Italy
Emilia-Romagna's foodservice equipment district integrates steam table production with broader commercial kitchen suite manufacturing. CE marking requirements for electrical safety and energy efficiency drive product development timelines for Mediterranean hotel and restaurant chains. Bologna-based fabricators specialize in custom-built configurations for heritage hotel renovations.
India
Institutional cafeteria expansion in Maharashtra and Karnataka generates demand for NSF-compliant stainless steel construction at localized price points. BIS certification for commercial kitchen equipment creates compliance barriers for imported units. Mumbai and Bengaluru anchor fabrication networks serving hotel chains and IT campus foodservice operations.
Commercial Steam Table Market Competitive Environment
The competitive structure tilts toward integrated metalworking specialists with captive stainless steel fabrication capabilities. Mid-sized domestic manufacturers and diversified foodservice equipment conglomerates split volume across institutional and commercial channels. Strategic archetypes include welded-frame specialists, heating-element engineering houses, and broad-line distributors leveraging replacement-cycle proximity. Capacity expansion in southern US manufacturing zones and backward integration into mineral-insulated cable production represent dominant competitive vectors.
Among diversified foodservice equipment manufacturers, Vollrath Company, Duke Manufacturing, and APW Wyott exemplify distinct strategic positions. Vollrath anchors the broad-distribution archetype through extensive institutional kitchen coverage. Duke Manufacturing occupies the integrated-fabrication tier with captive stainless steel base production. APW Wyott represents the specialized-engineering vector focused on high-volume buffet thermal performance. These three entities collectively illustrate how scale, vertical control, and technical differentiation segment competitive positioning in thermostatically controlled holding equipment.
| Leading Market Players |
|---|
| Advance Tabco |
| Duke Manufacturing |
| Vollrath Company |
| APW Wyott |
| Cres Cor |
| Winco |
| Eagle Group |
| Hatco Corporation |
| Vulcan Equipment |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange 304-grade stainless steel price volatility cascades through three-tier pricing structures across premium NSF-certified, standard commercial-grade, and economy non-certified equipment tiers, compressing margin visibility for domestic fabricators while amplifying cost advantages for Guangdong-based component assemblers serving portable unit demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified institutional bids from commercial kitchen replacements and budget catering rentals. Price differentiation hinges on certification grade and heating element warranty duration. Pricing pressure stems from aluminum substitution in portable configurations eroding stainless steel premium positioning. School and healthcare cafeterias exhibit highest price sensitivity due to public procurement constraints; casino operators show lowest sensitivity prioritizing 24-hour durability over capital cost.
Supply Chain Analysis
NSF certification timelines gate market access for imported units, compressing vendor qualification windows and favoring incumbent domestic fabricators with established approval cycles. Mineral-insulated heating cable production concentrates in China, South Korea, and Japan; stamped stainless steel wells source primarily from Guangdong and Zhejiang provinces. Supply chain risk centers on single-source vulnerability for specialized MI cable assemblies. Distribution runs through foodservice equipment dealers and institutional GPO contracts rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between southern US hotel construction premiums and East Asian component manufacturing costs, with the Department of Energy's standby efficiency standards widening the compliance-cost gap between domestic and imported equipment.
For Market Incumbents: To counter induction-assisted hybrid technology absorption in Nevada casino properties, anchor replacement-cycle demand through captive fabrication of welded stainless steel frames and backward integration into mineral-wool insulation production. Deepen channel control in Texas and Florida distribution networks before efficiency standard redesigns accelerate. For New Entrants and Emerging Players: Segmented heating zone technology with pan-detection sensors offers entry leverage into ghost kitchen subscription fleets where capital constraints favor equipment-as-a-service models. Target catering operators in Dallas-Fort Worth and Atlanta metropolitan areas with portable unit rotation contracts bundled with NSF compliance verification. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized fabricators possessing captive stainless steel base production and current NSF certification cycles for school cafeteria bidding. Long-term viability favors welded-frame specialists over broad-line distributors given modular station mixing trends. Watch for DOE standby efficiency standard advancement as inflection trigger for consolidation among non-compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral-Insulated Cable Production | Reduces single-source vulnerability from East Asian heating element suppliers for 24-hour rated equipment. |
| NSF Certification Cycle Acceleration | Compresses vendor qualification timelines to capture school and healthcare institutional replacement demand. |
| Equipment-as-a-Service Launch | Captures ghost kitchen and catering operator segments shifting procurement from capital to operating budgets. |
| Segmented Heating Zone Development | Aligns product portfolios with DOE standby efficiency limits below 1.0 kW for large-capacity floor models. |
| Southern US Manufacturing Footprint Expansion | Positions fabrication capacity proximate to Texas and Florida hotel construction activity and active foodservice development. |
Study Parameters
Coverage spans the United States, Germany, China, Italy, and India, with primary inputs from each market cluster combining interviews with foodservice equipment procurement managers, hotel banquet directors, institutional kitchen maintenance supervisors, and NSF certification specialists with secondary validation against Department of Energy test procedure filings, FDA Food Code provisions, customs trade data for stainless steel sheet imports, and foodservice construction permits in Texas and Florida. Bottom-up unit shipment estimates triangulate against top-down capital expenditure analysis across hotel, restaurant, and catering channels.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon, with segmentation modeling across product type, end user, application, and material dimensions plus regional regulatory cluster differentiation. CAGRs derive from installed base replacement cycles, new construction permit trajectories, and efficiency standard compliance timelines. Forecast inputs incorporate heating element technology roadmaps and southern US foodservice development pipelines.
The model holds under stable stainless steel input pricing and unchanged DOE efficiency test procedures; deviation in mineral-insulated cable supply disruptions or accelerated standby power draw compression would shift equipment cost structures and replacement timing. A model refresh is warranted upon material change in Department of Energy commercial kitchen equipment rulemaking or NSF International certification protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Global Combi Ovens Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Food Service Gloves Market
Food Service
Mobile Food Services Market
Food Service
Sandwich Toasters Market
Food Service
Europe Vending Machine Market
Food Service
Latin America Online Grocery Market
Food Service
Food Service Market
Food Service
Commercial Tableware Services Market
Food Service
Beverage Vending Machine Market
Food Service
Vietnam Online Food Delivery Market
Food Service
North America Food Platform-To-Consumer Delivery Market