
 Charbroiler Market | 2026-2036
Charbroiler Market Size, Share, and Industry Trends Forecast 2026-2036
Charbroiler Market Analysis
China is rewriting charbroiler manufacturing dynamics as domestic foundries expand stainless-steel fabrication capacity for export markets. Middleby Corporation leverages vertical integration across burner assembly and control systems to sustain margin structure in premium gas charbroiler lines. ITW Food Equipment Group LLC anchors North American distribution through broadline foodservice dealer networks. Welbilt competes on European certification breadth, navigating Ecodesign and CE marking requirements for commercial kitchen equipment.
A charbroiler is a commercial cooking appliance that generates radiant and convective heat through gas burners, electric elements, or charcoal combustion to sear proteins and vegetables at surface temperatures exceeding 260°C. Stainless-steel construction with cast-iron grates defines durability standards, while infrared burner configurations improve thermal efficiency in high-volume kitchen environments. Gas charbroilers occupy the largest revenue share due to operational familiarity and lower energy costs in legacy restaurant infrastructure. Electric charbroilers represent the fastest-growing product category as urban operators confront natural-gas hookup restrictions and ventilation code limitations. Floor-model installations dominate chain restaurant deployments, whereas countertop configurations expand in food trucks and catering operations where space constraints dictate equipment selection.
The U.S. Department of Energy imposes minimum efficiency standards on commercial gas cooking equipment, compelling manufacturers to redesign burner geometry and insulation packages. The EPA's emissions guidelines for commercial kitchens in ozone-nonattainment areas restrict volatile organic compound output from gas-fired charbroilers, filtering product eligibility in California and Texas metropolitan zones. NSF International sanitation certification remains mandatory for foodservice equipment acceptance across U.S. school and hospital cafeteria contracts. Stakeholders must monitor municipal electrification mandates in major metropolitan areas, as building code amendments in New York City and Seattle already prohibit new gas connections in commercial construction.
Market Dynamics
The U.S. Department of Energy's commercial cooking equipment efficiency standards are forcing a wholesale redesign of burner geometry and insulation systems across gas charbroiler portfolios. Manufacturers must recalibrate thermal output specifications while maintaining searing performance thresholds above 260°C surface temperature.
Growth Catalysts
- EPA emissions guidelines:Volatile organic compound restrictions in California and Texas metropolitan ozone-nonattainment areas are filtering product eligibility and accelerating replacement cycles for non-compliant legacy equipment.
- Urban electrification mandates:Municipal building code amendments in New York City and Seattle prohibiting new gas connections in commercial construction are redirecting capital toward electric charbroiler installations.
- Food truck proliferation:Mobile catering operations demanding compact countertop configurations are expanding addressable equipment demand beyond traditional brick-and-mortar restaurant footprints.
Market Restraints
- Stainless-steel input volatility:Foundry capacity concentration in Chinese export markets exposes margin structures to raw material price swings and freight cost fluctuations.
- Ventilation infrastructure lock-in:Legacy restaurant buildings with Type I hood systems designed for gas combustion impose technical constraints on electric charbroiler retrofits absent costly ductwork modifications.
- Natural-gas hookup cost differentials:Existing utility infrastructure in Texas, Florida, and California maintains operational cost advantages that slow electric equipment penetration in suburban expansion zones.
Strategic Opportunities
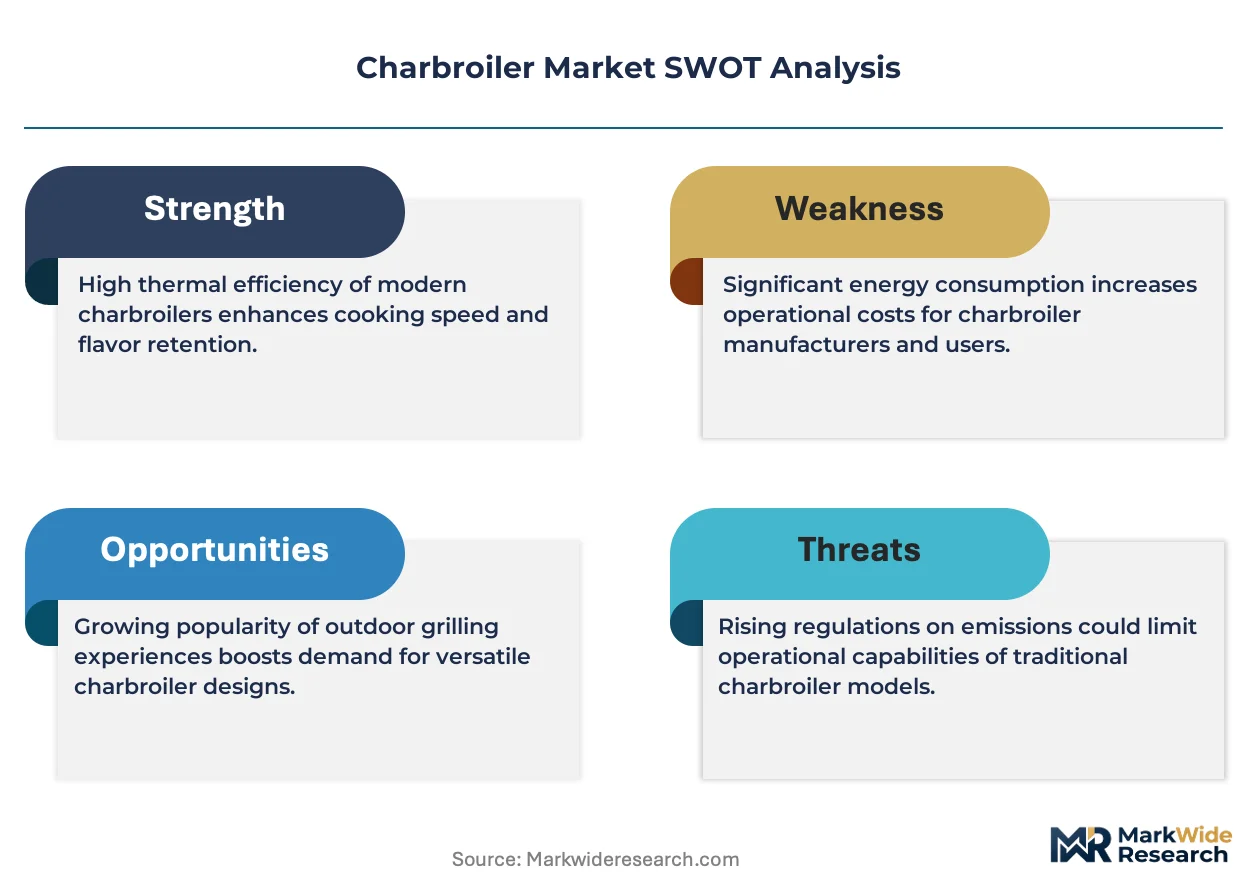
- Infrared burner convergence:Integration of ceramic radiant elements with precision temperature controls is opening premium positioning in high-volume steakhouse chains seeking consistent sear patterns.
- NSF sanitation certification arbitrage:Mandatory certification requirements for U.S. school and hospital cafeteria contracts create defensive moats for compliant manufacturers against uncertified import competition.
- Catering channel digitization:Direct-to-operator e-commerce platforms are compressing traditional broadline dealer margins and enabling equipment manufacturers to capture disintermediated service revenue.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in gas-air mixture optimization and flame pattern design is concentrating among aging workforce cohorts with limited apprenticeship pipeline replenishment.
- Dual certification complexity:Simultaneous navigation of U.S. DOE efficiency standards, EPA emissions testing, and NSF sanitation protocols extends product development timelines and strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Charbroiler Market |
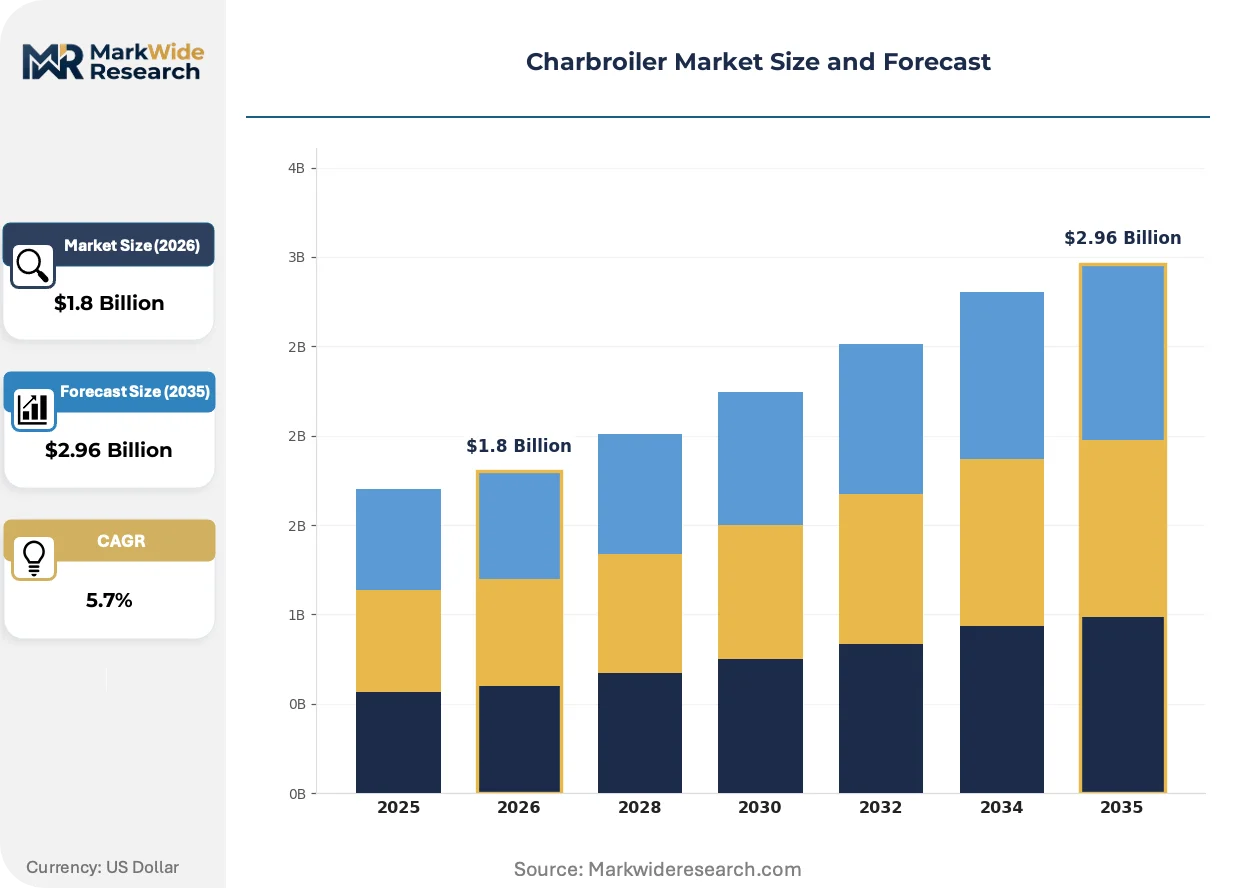
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Charbroilers, Electric Charbroilers, Charcoal Charbroilers, Combination Charbroilers Installation: Countertop, Floor Model, Built-in, Portable End User: Restaurants, Food Trucks, Catering Services, Cafeterias Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | ITW Food Equipment Group LLC, Middleby Corporation, Welbilt (Garland Group Ltd.), The Vollrath Company LLC, Wells Manufacturing Inc., Champion Tuff Grills, Avantco Equipment, Dukers Appliance Co., The Montague Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Charbroiler Market Emerging Trajectories
Equipment intelligence and thermal management architectures are redefining competitive differentiation in commercial charbroiler supply. Control system sophistication now separates premium installations from commodity alternatives.
Infrared ceramic burner technology is virtualizing traditional convective heat transfer in high-throughput kitchen environments. National steakhouse chains with standardized menu specifications are adopting these configurations to reduce temperature recovery time between protein batches. The technology is virtualizing equipment selection criteria away from raw BTU output toward thermal consistency metrics and energy consumption per cover served.
The U.S. Department of Energy's amended commercial gas cooking equipment standards are mandating minimum thermal efficiency thresholds that legacy cast-iron burner designs cannot satisfy without geometric redesign. Manufacturers are responding by narrowing flame port configurations and adding forced-air premix systems that alter combustion dynamics. Floor-model gas charbroilers in the 36-inch and 48-inch width categories face the steepest compliance redesign burden due to higher baseline fuel consumption rates.
Foodservice procurement through consolidated purchasing cooperatives is compressing vendor negotiation cycles and unbundling after-sales service from equipment transactions. Multi-unit restaurant operators in Texas and California are aggregating volume commitments to extract pricing concessions and standardized warranty terms. This consolidation is most visible among emerging fast-casual chains with 50-200 unit footprints seeking to replicate enterprise-grade procurement discipline without dedicated supply chain infrastructure.
Charbroiler Market Segmentation
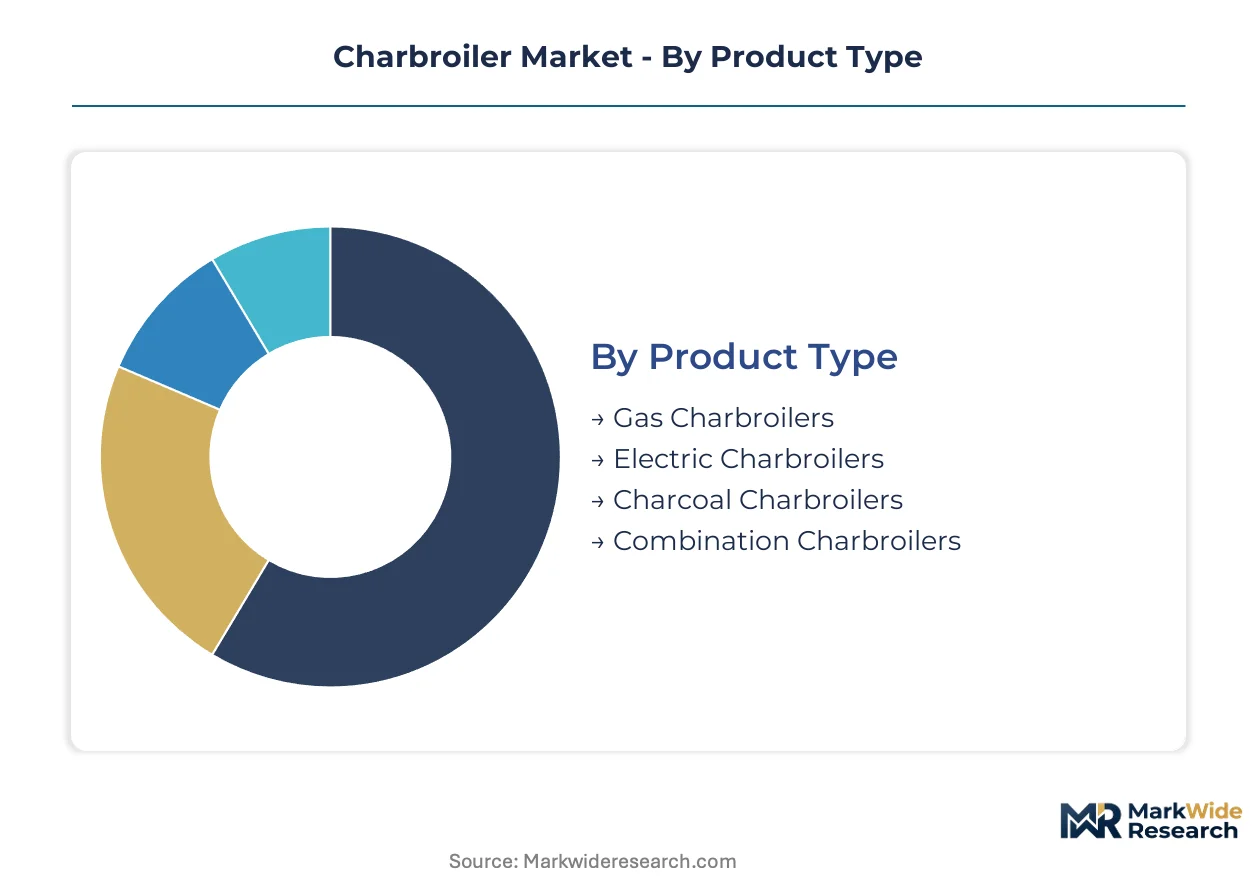
Charbroiler procurement patterns diverge sharply across equipment configurations and operator scale. Segmentation reveals which product categories command replacement premiums versus long depreciation cycles.
Product Type:
Gas charbroilers turn over slowest due to hood infrastructure lock-in, while electric models accelerate replacement as municipal codes shift. Charcoal units cycle fastest in mobile catering where equipment abuse is highest.
- Gas Charbroilers:Burner assemblies deliver radiant heat above 260°C through cast-iron grates with forced-air premix systems. Full-service steakhouse chains in Texas and Florida maintain this installed base despite electrification mandates elsewhere, constrained by Type I hood investments and natural-gas rate advantages.
- Electric Charbroilers:Infrared ceramic elements and precision coil configurations eliminate combustion ventilation requirements. Urban operators in New York City and Seattle confront municipal gas-connection prohibitions, redirecting capital toward electric installations in new commercial construction.
- Charcoal Charbroilers:Combustion of hardwood or briquette fuel generates signature smoke flavor profiles. Barbecue specialists and independent restaurants seeking menu differentiation sustain demand despite operational labor intensity.
- Combination Charbroilers:Modular platforms switch between gas, electric, or hybrid thermal sources. Multi-concept operators requiring equipment flexibility across kitchen footprints represent the primary demand concentration.
Gas charbroilers dominate installed base. Electric charbroilers are where expansion concentrates.
Installation:
Capital deployment varies by real estate commitment duration. Permanent installations depreciate over decade-plus horizons while mobile configurations compress amortization schedules.
- Countertop:Compact footprints under 36 inches width fit food trucks and catering staging areas with severe space constraints. Food truck proliferation in Texas and California metropolitan zones accelerates procurement cycles for these configurations.
- Floor Model:Heavy-duty frames with casters or fixed legs support 36-inch to 72-inch cooking surfaces. Chain restaurant deployments in Florida and California concentrate demand for standardized 48-inch widths with NSF certification for institutional contracts.
- Built-in:Custom fabrication integrates charbroiler modules into permanent kitchen architecture. High-end hospitality and casino foodservice operations in Nevada and New Jersey specify these for aesthetic and workflow integration.
- Portable:Lightweight construction with quick-disconnect utilities serves outdoor events and temporary foodservice. Catering operators and festival concessionaires in California and Texas rotate these through high-utilization seasonal cycles.
Floor-model installations anchor chain restaurant standardization. Countertop configurations are climbing the fastest.
End User:
Volume concentration and procurement sophistication separate institutional buyers from fragmented independents. Contract terms and warranty negotiation power scale with unit count.
- Restaurants:Full-service and quick-service operators constitute the core revenue pool. Steakhouse chains and fast-casual expansion in Texas, California, and Florida drive equipment specification toward thermal consistency metrics.
- Food Trucks:Mobile operators demand compact, high-output configurations with simplified utility connections. Regulatory compliance with local fire codes and propane storage limits shapes product selection in municipal permitting environments.
- Catering Services:Event-based operators prioritize rapid setup and breakdown with portable or countertop units. Seasonal demand spikes and equipment transport abuse compress replacement cycles relative to fixed installations.
- Cafeterias:School and hospital foodservice contracts mandate NSF sanitation certification and standardized warranty terms. Procurement through purchasing cooperatives in California and Texas aggregates volume for pricing concessions.
Restaurants dominate installed base. Food trucks are gaining share fastest.
Distribution Channel:
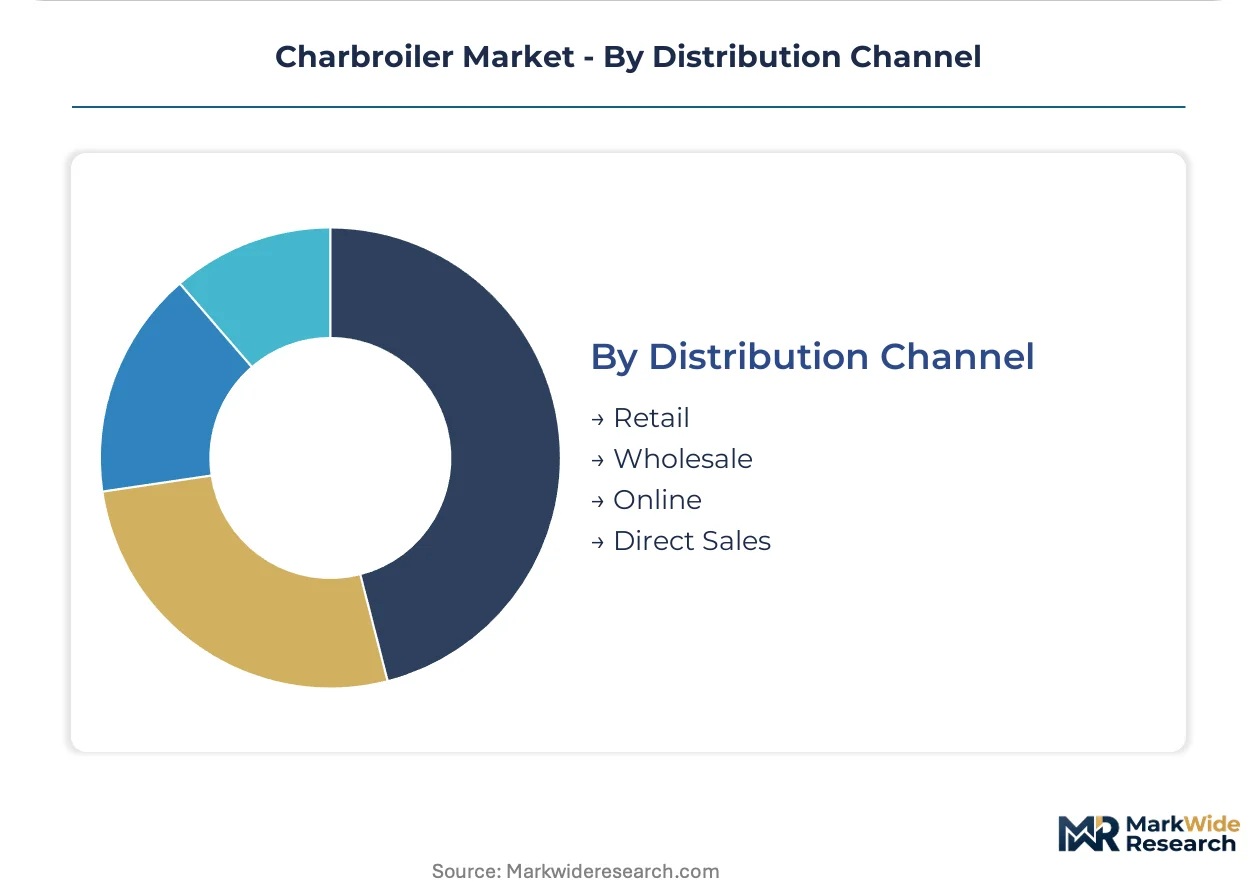
Channel selection reflects operator scale and technical support requirements. Large chains bypass intermediaries while independents rely on dealer networks for specification guidance.
- Retail:Dealer showrooms and kitchen equipment supply houses serve independent operators requiring hands-on evaluation. Broadline foodservice dealer networks in North America anchor this channel for specification-heavy purchases.
- Wholesale:Volume pricing and standardized terms flow through purchasing cooperatives and dealer consortia. Multi-unit operators with 50-200 unit footprints leverage aggregated commitments for concession extraction.
- Online:Direct-to-operator e-commerce platforms compress traditional dealer margins. Catering and food truck operators with clear specification requirements increasingly bypass showroom intermediaries.
- Direct Sales:Manufacturer field teams manage enterprise accounts and chain rollouts with customized service bundling. National steakhouse chains and institutional buyers negotiate directly for standardized fleet deployments.
Wholesale channels dominate institutional procurement. Online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foundries supply stainless-steel fabrication capacity that feeds export markets across North America and Europe. Equipment procurement concentrates in metropolitan zones where foodservice expansion outpaces national averages and municipal codes reshape fuel-source decisions.
United States
Full-service and quick-service restaurants in Texas, California, and Florida are expanding kitchen equipment upgrades faster than national averages. The U.S. Department of Energy imposes minimum efficiency standards on commercial gas cooking equipment, compelling burner geometry redesigns. Houston and Dallas metropolitan zones maintain natural-gas infrastructure advantages that slow electric charbroiler penetration despite coastal electrification mandates.
China
Domestic foundries are expanding stainless-steel fabrication capacity specifically for export-market charbroiler production. The country's national industrial standards regulator oversees GB standards compliance for commercial kitchen equipment manufacturing. Zhejiang and Guangdong province industrial clusters are scaling radiant burner assembly lines to serve North American and European OEM demand.
Germany
Commercial kitchen operators prioritize thermal efficiency certifications under Ecodesign and CE marking requirements for equipment acceptance. The EU Green Deal framework pressures foodservice operations toward lower-emission cooking technologies. Bavaria and North Rhine-Westphalia host distributor networks that channel German-engineered control systems into pan-European foodservice supply chains.
Japan
Compact kitchen footprints in urban dining establishments favor electric and infrared charbroiler configurations over gas-dependent alternatives. METI energy efficiency guidelines shape commercial cooking equipment procurement specifications for institutional buyers. The Kanto region around Tokyo concentrates demand for high-precision thermal control systems in premium steakhouse and hotel kitchen deployments.
United Kingdom
Post-Brexit regulatory divergence creates dual certification burdens for equipment importers serving both UK and EU markets. The country's national standards body maintains alignment pressure with European CE marking while developing independent conformity assessment routes. London and Southeast England foodservice operators are piloting electric charbroiler installations ahead of anticipated municipal gas-connection restrictions.
Charbroiler Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in burner assembly and control module fabrication. The vendor base organizes around three strategic tiers: diversified foodservice equipment conglomerates with broadline distribution, regional stainless-steel fabricators serving price-sensitive channels, and niche specialists in infrared ceramic technology. Consolidation pressures concentrate among mid-scale manufacturers facing dual certification complexity across U.S. DOE efficiency standards and European Ecodesign requirements. Dominant competitive moves include backward integration into captive stainless-steel supply and geographic expansion through distributor network acquisition.
Among diversified equipment conglomerates, Middleby Corporation and ITW Food Equipment Group LLC exemplify platform-scale positioning across burner technology and distribution architecture. Welbilt anchors European market access through certification breadth under Ecodesign and CE marking protocols. These three entities represent contrasting strategic archetypes: Middleby Corporation demonstrates vertical control across component manufacturing; ITW Food Equipment Group LLC occupies broadline dealer network anchoring; Welbilt exemplifies regulatory-complexity navigation as competitive differentiation.
| Leading Market Players |
|---|
| ITW Food Equipment Group LLC |
| Middleby Corporation |
| Welbilt (Garland Group Ltd.) |
| The Vollrath Company LLC |
| Wells Manufacturing Inc. |
| Champion Tuff Grills |
| Avantco Equipment |
| Dukers Appliance Co. |
| The Montague Company |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors from Zhejiang and Guangdong provinces transmit stainless-steel cost volatility directly into North American equipment pricing, amplifying margin compression for fabricators lacking captive foundry relationships while creating price differentiation between integrated and import-dependent manufacturers.
Pricing Analysis
DOE efficiency standards dictate the pricing tier structure across gas charbroiler portfolios. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and burner technology sophistication. Cost compression in mid-tier gas configurations is intensifying because forced-air premix system redesigns strain engineering bandwidth. Independent restaurant operators in Texas and Florida exhibit highest price sensitivity, while steakhouse chains prioritize thermal consistency metrics over unit economics.
Supply Chain Analysis
Chinese domestic foundries in Zhejiang and Guangdong provinces hold dominant stainless-steel fabrication capacity for export-market charbroiler production. Raw material dependencies center on nickel-alloy stainless grades, cast-iron grate stock, and ceramic infrared burner substrates. Single-source vulnerability concentrates in Chinese export foundries exposed to freight cost swings and tariff policy shifts. Distribution runs through broadline foodservice dealer networks anchored by ITW Food Equipment Group LLC's North American footprint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated purchasing cooperatives as multi-unit operators with 50-200 unit footprints aggregate volume commitments, extracting pricing concessions that compress traditional dealer margins.
For Market Incumbents: Insulate margin structures through backward integration into captive stainless-steel supply and burner assembly manufacturing. Middleby Corporation's vertical control model offers defensive precedent against import competition. Prioritize NSF sanitation certification investment to maintain institutional contract eligibility against uncertified Asian imports. For New Entrants and Emerging Players: Establish a beachhead in electric charbroiler configurations for urban operators confronting municipal gas-connection prohibitions in New York City and Seattle. Target food truck and mobile catering segments where countertop specifications and rapid replacement cycles reduce incumbent brand loyalty. Deploy direct-to-operator e-commerce platforms to bypass entrenched dealer networks. For Investors and Strategic Acquirers: EPA emissions guidelines for California and Texas ozone-nonattainment areas reshape the acquisition landscape by filtering product eligibility and accelerating replacement cycles. Long-term viability favors manufacturers with dual certification capability across DOE efficiency standards and European Ecodesign requirements. Target mid-scale fabricators facing compliance complexity but holding established distributor relationships. Monitor municipal electrification mandate adoption velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Infrared Burner Technology Integration | Ceramic radiant elements with precision controls open premium positioning in steakhouse chains seeking sear consistency. |
| NSF Certification Investment | Mandatory sanitation protocols create defensive moats for compliant manufacturers against uncertified import competition. |
| Direct-to-Operator E-Commerce Platform | Digital channels compress traditional broadline dealer margins and enable disintermediated service revenue capture. |
| Backward Integration into Foundry Operations | Captive stainless-steel supply insulates margin structures from Chinese export market price volatility. |
| Dual Certification Capability Buildout | Simultaneous DOE and Ecodesign compliance extends addressable market across North American and European procurement. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at stainless-steel foundries, procurement leads at multi-unit restaurant operators, foodservice dealer network heads, and aftermarket service technicians provided operational perspective. Secondary validation drew from DOE efficiency standard dockets, EPA emissions testing protocols, NSF certification databases, and customs trade records. Bottom-up equipment shipment analysis and top-down foodservice construction spending estimates were reconciled through iterative triangulation.
Calibration against historical replacement cycles and regulatory compliance deadlines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include fuel source, installation configuration, end-user scale, and regional regulatory cluster. CAGRs were derived from slope analysis of equipment procurement trajectories correlated with foodservice establishment growth and code amendment timelines. Infrared technology adoption curves and municipal electrification mandate propagation served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in foodservice labor availability, commercial construction lending rates, and stainless-steel commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry export capacity expansion. Quarterly review of DOE standard implementation progress, EPA nonattainment area designations, and municipal building code amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Supermarkets Market
Food Service
Snack Subscription Box Service Market
Food Service
Limited-Service Restaurants Market
Food Service
Global Meal Kit Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Online Grocery Market
Food Service
United States Quick Service Restaurants Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Pizza Oven Market
Food Service
South America Free from Food Market
Food Service
Qatar Food Service Market
Food Service
US Food Service Market
Food Service
Malaysia Food Service Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Restaurants in Belgium Market