
 Rotisseries Market | 2026-2036
Rotisseries Market Size, Share, and Industry Trends Forecast 2026-2036
Rotisseries Market Analytics
Buyer concentration among quick-service restaurant chains is decoupling from traditional equipment procurement patterns as smaller independent operators and food trucks multiply their share of rotisserie purchases. Alto-Shaam leverages its halo heat technology to dominate premium commercial installations across North American foodservice chains. Henny Penny sustains manufacturing scale advantages in high-volume gas and electric models for franchise systems. Hobart competes through integrated kitchen system sales that bundle rotisseries with warewashing and food preparation equipment.
A rotisserie is a cooking appliance that rotates meat on a spit or in a basket around a heat source, typically operating at temperatures between 250°F and 500°F with motorized rotation mechanisms ensuring even heat distribution and self-basting. The device serves commercial kitchens and outdoor entertainment settings by producing consistent, high-yield roasted proteins with minimal operator intervention. Commercial units command the largest installed base due to durability requirements and throughput demands in restaurants and catering operations. Electric fuel types are gaining fastest among new installations as operators respond to indoor air quality rules and utility rebate programs. Tabletop configurations occupy a specialized niche where space constraints in food trucks and small kitchens override capacity needs.
The U.S. Department of Energy sets minimum efficiency standards for commercial cooking equipment through its Appliance and Equipment Standards Program, while the EPA's Energy Star certification creates procurement preference among institutional buyers seeking operating cost reductions. NSF International sanitation standards govern materials and cleanability for food contact surfaces, effectively filtering non-compliant imports from commercial distribution channels. Stakeholders must monitor how municipal electrification mandates and building code revisions reshape fuel type viability across major metropolitan equipment markets.
Market Dynamics
Electrification mandates from municipal building codes and the U.S. Department of Energy's commercial kitchen efficiency standards are forcing a generational shift away from gas-fired rotisserie architectures toward induction and electric heating systems.
Growth Catalysts
- Food truck proliferation:Mobile foodservice operators require compact, high-output rotisserie units that fit constrained vehicle footprints while maintaining throughput. This end-use channel is multiplying equipment procurement volumes.
- Energy Star procurement preference:Institutional buyers including school districts and hospital systems prioritize EPA-certified equipment to secure utility rebates and operating cost reductions.
- Induction heating maturation:Magnetic field cooking technology now delivers thermal response speeds matching gas systems, removing the final performance barrier to electrification.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet metal price swings compress manufacturer margins and complicate long-term contract pricing with foodservice distributors.
- Gas infrastructure lock-in:Existing restaurant buildouts with dedicated natural gas lines create switching cost friction against electric replacement cycles.
- NSF certification timeline:Sanitation testing protocols for new electric heating element designs extend product launch windows by 4-8 months versus legacy gas models.
Strategic Opportunities
- India foodservice modernization:Quick-service chicken chains in Mumbai, Delhi, and Bangalore are importing commercial rotisserie capacity as protein consumption rises.
- Cloud kitchen convergence:Ghost kitchen operators bundle rotisserie output with automated packaging and delivery logistics, creating equipment-plus-service demand.
- Infrastructure Act rebates:Federal electrification incentives lower net acquisition costs for electric models in qualified commercial kitchen renovations.
Industry Challenges
- Field technician scarcity:Induction coil and solid-state power electronics repair requires electrical engineering skills absent from traditional gas equipment service networks.
- Legacy control system integration:New electric rotisseries must communicate with existing kitchen management software and IoT platforms through fragmented API standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotisseries Market |
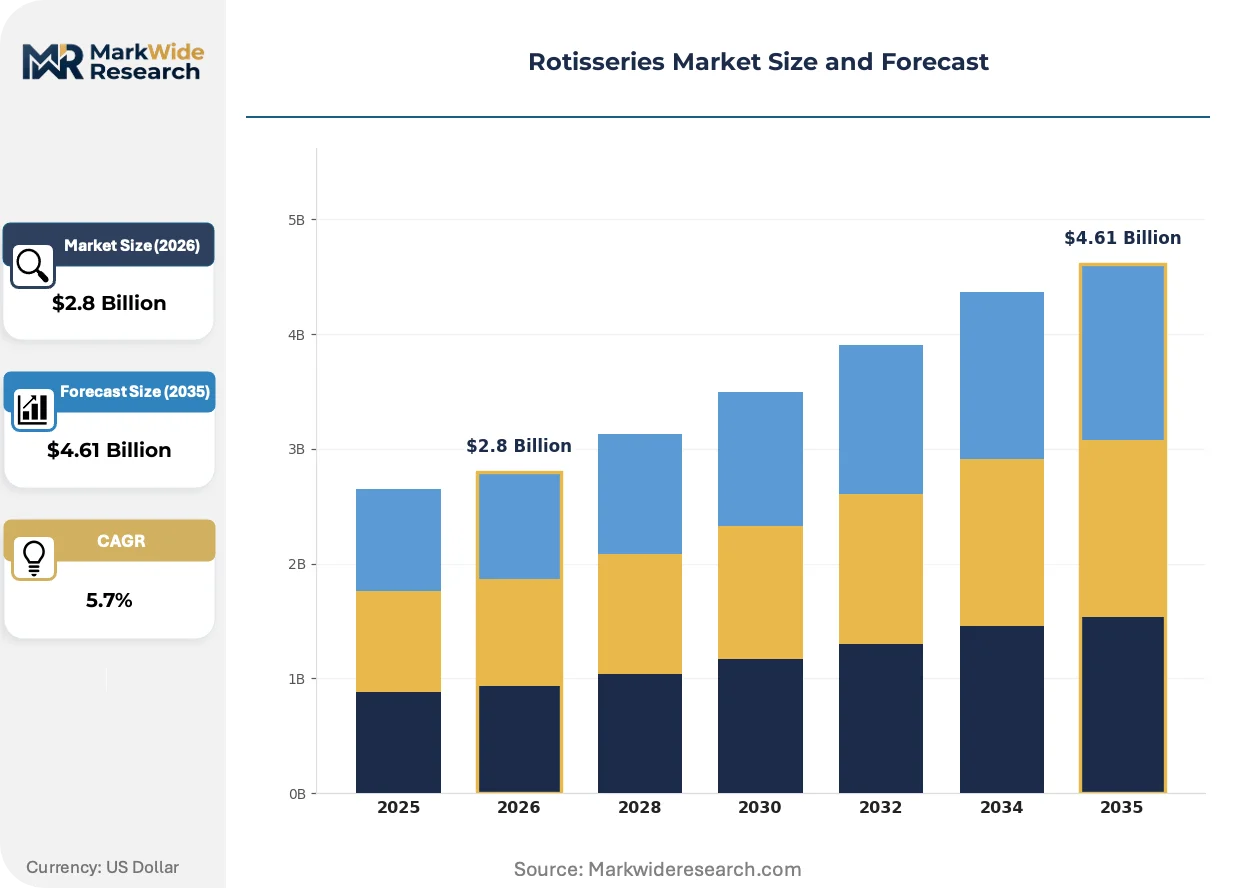
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Commercial, Outdoor, Built-in Fuel Type: Electric, Charcoal, Gas, Wood End User: Restaurants, Catering Services, Home Users, Food Trucks Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Alto-Shaam, Henny Penny, Hickory Industries, Hobart, Rotisol, The Vollrath Company, Nemco, TurboChef Technologies, Champion Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotisseries Market Evolving Landscape
Active thermal management and connected cooking platforms are compressing operator skill requirements while expanding remote monitoring capabilities across distributed foodservice footprints.
Induction rotisserie systems are expanding into high-volume quick-service installations previously dominated by gas architectures. Chains with drive-thru chicken programs are piloting electric models in California and New York markets where municipal electrification mandates take effect earliest. This technology is expanding into franchise systems by eliminating vent hood requirements and reducing kitchen infrastructure costs.
EPA Energy Star certification thresholds for commercial cooking equipment tightened in 2023, disqualifying several legacy gas rotisserie platforms from federal procurement preference lists. Manufacturers now optimize heating element geometry and insulation packages to meet the updated efficiency benchmarks. Institutional buyers in K-12 and healthcare segments are accelerating replacement cycles to capture available rebate funding before program sunset dates.
Equipment-as-a-service contracting is displacing capital purchase models among independent restaurant operators with constrained balance sheets. Distributors bundle rotisserie hardware with preventive maintenance and parts replacement into monthly subscriptions. This shift is most visible in the United States, where equipment finance platforms have standardized underwriting for foodservice assets.
Rotisseries Market Segmentation
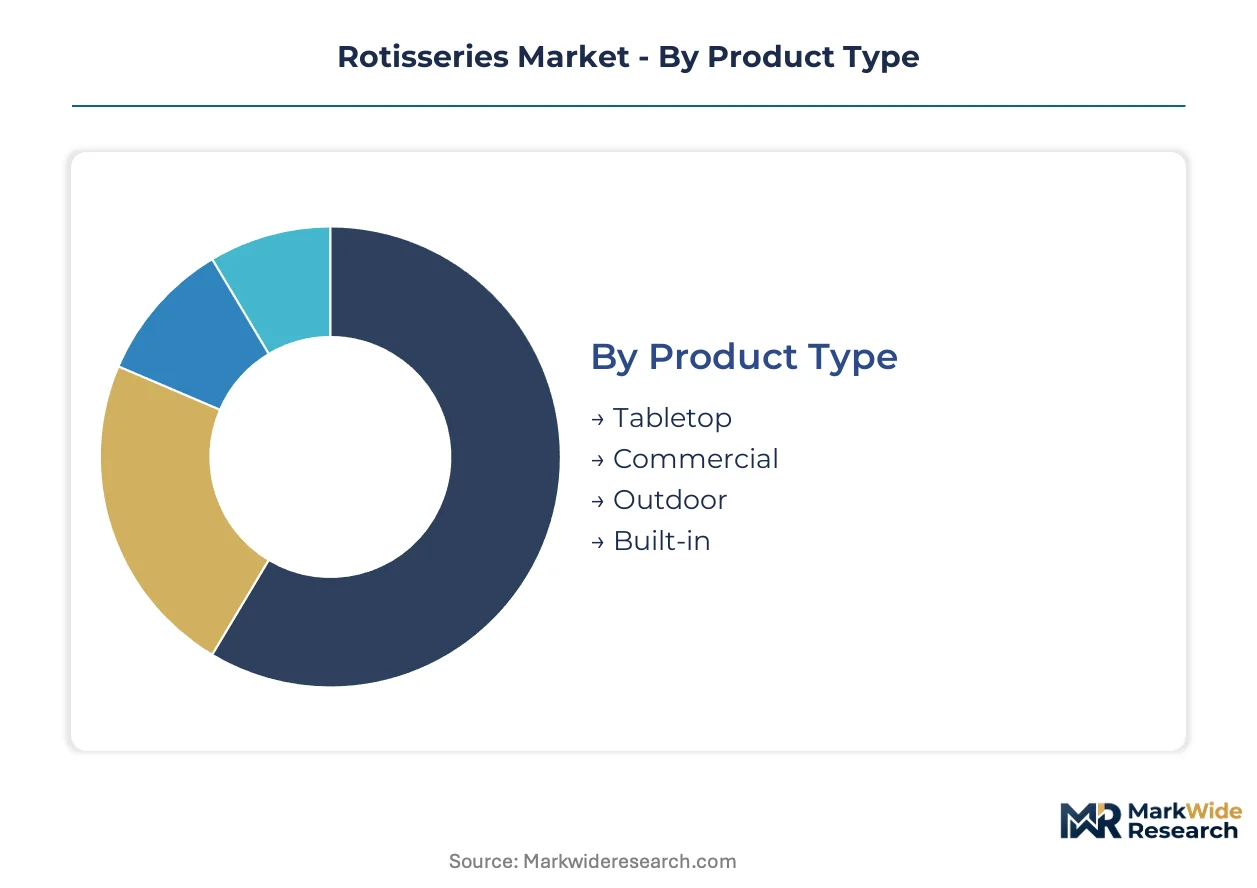
Rotisserie equipment procurement splits across four distinct category axes, each revealing divergent margin structures and channel control points. Product type and fuel type categories concentrate manufacturing capacity among specialized suppliers, while end user and distribution channel fragmentation creates pricing power dispersion across the value chain.
Product Type:
Supply concentration tilts toward commercial-grade fabricators with NSF-certified production lines and volume contract relationships with foodservice distributors.
- Commercial:Heavy-duty stainless steel construction supports continuous operation in high-throughput kitchens. Restaurant chains and institutional cafeterias in the United States drive replacement demand as electrification mandates accelerate equipment turnover cycles.
- Tabletop:Compact footprint designs prioritize thermal efficiency in space-constrained installations. Food truck operators across California, Texas, and Florida represent the fastest-expanding customer base for these units.
- Outdoor:Weather-resistant housing and portable fuel connections serve residential entertainment and event catering applications.
- Built-in:Custom kitchen integration requires specialized installation coordination with general contractors and HVAC specialists.
Today's leader: Commercial. Tomorrow's challenger: Tabletop.
Fuel Type:
Cost tier stratification separates premium electric induction systems from legacy gas infrastructure and commodity combustion alternatives.
- Electric:Induction coil and radiant element designs eliminate vent hood requirements and reduce kitchen infrastructure costs. Municipal electrification mandates in New York City, San Francisco, and Seattle are forcing adoption timelines in commercial renovations.
- Gas:Natural gas and propane architectures retain installed base dominance where utility infrastructure already exists. Independent operators in Texas, Pennsylvania, and Ohio exhibit slower switching behavior due to capital replacement friction.
- Charcoal:Smoke flavor generation appeals to specialty barbecue concepts and competitive cooking segments.
- Wood:Hard fuel combustion requires manual fire management and specialized operator training for consistent temperature control.
Electric commands the steepest expansion trajectory as regulatory pressure compounds with utility rebate availability.
End User:
Application intensity varies dramatically across customer types, with commercial operators demanding durability certifications absent from residential purchase criteria.
- Restaurants:Quick-service chicken chains and full-service independents specify NSF-listed units with automated rotation controls and programmable temperature profiles.
- Food Trucks:Mobile operators prioritize compact dimensions, dual-fuel flexibility, and rapid heat recovery between service rushes.
- Catering Services:Event-based volume demands drive rental and lease arrangements over capital acquisition.
- Home Users:Residential purchasers respond to countertop convenience and outdoor entertainment aesthetics rather than throughput metrics.
Restaurants anchor current procurement volumes. Food trucks are climbing the fastest among expansion trajectories.
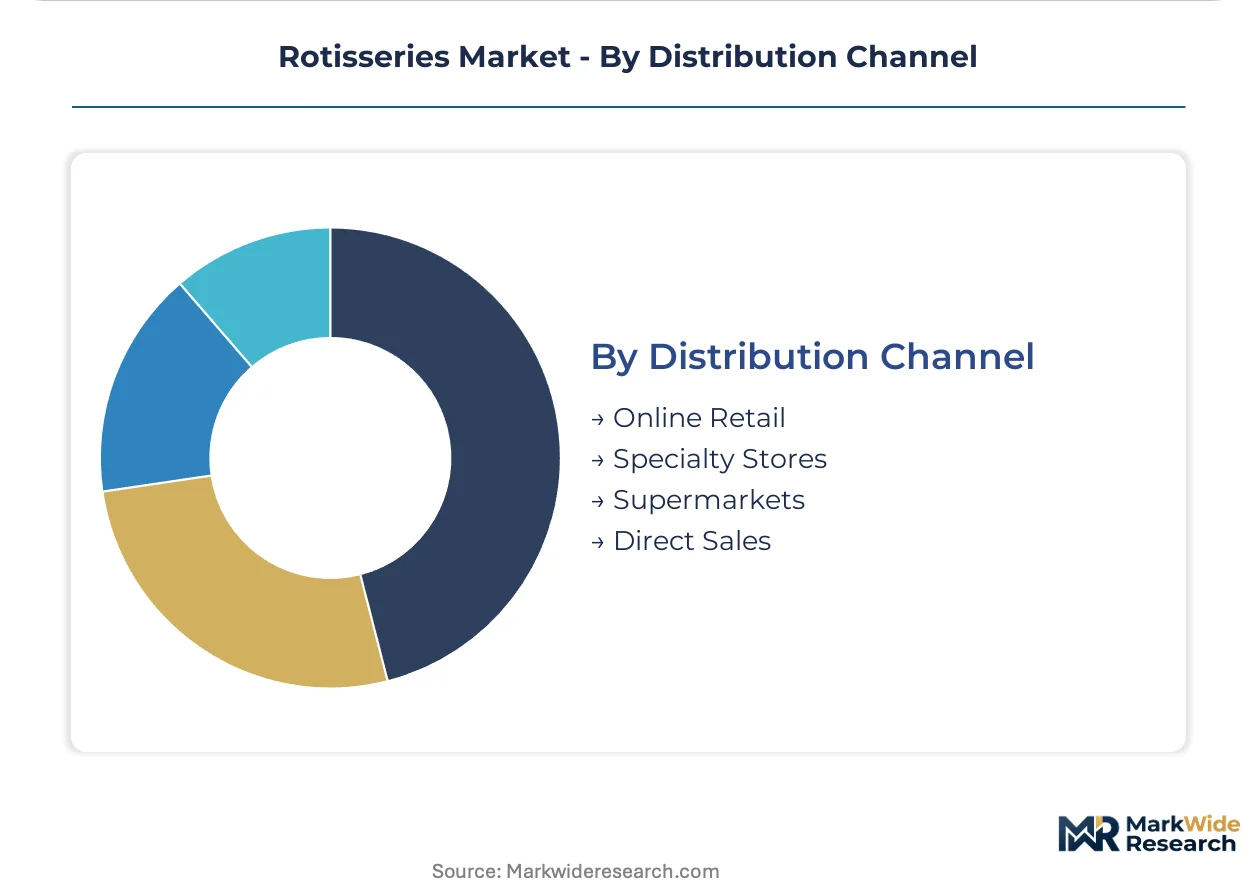
Distribution Channel:
Customer type determines channel selection, with institutional buyers bypassing retail intermediaries while independents rely on specialized dealer networks.
- Direct Sales:Manufacturer representatives negotiate fleet pricing with multi-unit restaurant operators and institutional foodservice management companies.
- Specialty Stores:Foodservice equipment dealers provide specification consulting, installation coordination, and maintenance contract bundling.
- Online Retail:E-commerce platforms capture residential and small independent purchases with standardized shipping logistics.
- Supermarkets:Mass retail channels move entry-level consumer units with limited commercial applicability.
Direct sales capture the largest transaction values. Online retail is gaining share fastest in the sub-commercial segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled foodservice equipment technicians and commercial kitchen engineers concentrate in the United States, Germany, China, India, and Brazil, anchoring regional demand clusters for rotisserie manufacturing and aftermarket service networks.
United States
Quick-service chicken chains and independent operators drive replacement cycles as electrification mandates reshape procurement. The EPA's Energy Star certification creates institutional preference for certified equipment among school districts and hospital systems. California, Texas, and Florida food truck operators multiply compact tabletop unit orders.
Germany
Precision engineering traditions support high-specification commercial kitchen equipment fabrication for export markets. The EU Green Deal and national building efficiency codes accelerate electric and induction model adoption in commercial renovations. Baden-Württemberg industrial clusters around Stuttgart supply precision motor and control systems for automated rotation mechanisms.
China
Rising urban middle-class protein consumption expands quick-service restaurant chains requiring high-throughput cooking equipment. The MIIT energy efficiency standards for commercial appliances push domestic manufacturers toward electric heating designs. Guangdong Province manufacturing zones near Shenzhen export countertop and commercial-grade units throughout Southeast Asia.
India
Quick-service chicken chains in Mumbai, Delhi, and Bangalore import commercial rotisserie capacity as organized foodservice expands. The BIS certification requirements for electrical appliances filter non-compliant imports from distribution channels. Maharashtra state industrial corridors near Pune develop domestic assembly capacity for mid-tier commercial units.
Brazil
Churrasco barbecue culture sustains demand for charcoal and gas-fired rotisserie architectures in traditional restaurants. ANVISA sanitation standards govern food contact surface materials for commercial equipment imports. São Paulo state foodservice equipment distributors anchor procurement networks serving the Mercosur trade bloc.
Rotisseries Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified kitchen equipment conglomerates bundling rotisseries with warewashing and preparation systems; specialized rotisserie fabricators with dedicated thermal engineering expertise; and commercial oven manufacturers extending product lines into rotating-spit configurations. Competitive moves concentrate on portfolio diversification into adjacent cooking platforms and geographic expansion through distributor network partnerships.
Among North American diversified equipment suppliers, Alto-Shaam, Henny Penny, and Hobart occupy positions spanning premium commercial installations and high-volume franchise system supply. These companies exemplify the conglomerate archetype through integrated kitchen system offerings. Specialized European fabricators including Rotisol represent the focused engineering tier with dedicated rotisserie expertise. The competitive terrain rewards thermal efficiency optimization and regulatory compliance speed rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Alto-Shaam |
| Henny Penny |
| Hickory Industries |
| Hobart |
| Rotisol |
| The Vollrath Company |
| Nemco |
| TurboChef Technologies |
| Champion Industries |
| Others |
Value Network & Pricing Analysis
Grade 304 stainless steel sheet metal moves from South Korean and Chinese mills through three distinct pricing tiers: premium induction systems with NSF certification and service bundling, standard electric models for franchise procurement, and economy gas units for independent operators. Input cost volatility compresses margins at the economy tier while electrification mandates shift procurement preference toward premium electric architectures with longer payback periods.
Pricing Analysis
Bundled equipment-as-a-service contracts separate premium pricing from transactional unit sales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service intensity. Cost compression in the economy tier intensifies because stainless steel price swings eliminate buffer margins. Food truck operators exhibit highest price sensitivity, while institutional buyers with Energy Star rebate access show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from quick-service chains, while specialty dealers manage specification-heavy independent restaurant procurement. Manufacturing concentrates in China, Germany, and the United States. Production draws from precision motors sourced from Baden-Württemberg clusters, induction coils from Guangdong Province, and stainless steel sheet from South Korean mills. Single-source vulnerability in semiconductor components for induction control systems creates delivery risk. Distribution runs through foodservice equipment dealers with NSF-certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotisseries market functions as a stable compounder where regulatory electrification mandates drive consistent replacement demand across commercial kitchen installations.
For Market Incumbents: Deepen backward integration into precision motor and induction coil production to defend margins against input volatility. Expand certified service networks in California and New York ahead of municipal electrification deadlines. Alto-Shaam and Henny Penny face emerging competition from European specialists targeting premium electric segments. For New Entrants and Emerging Players: Enter via tabletop electric configurations for food truck operators in Texas and Florida, where space constraints override brand loyalty. Cloud kitchen operators represent underpenetrated demand for compact, high-output units with IoT integration. Partner with equipment finance platforms to offer subscription-based acquisition models. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack capital to fund electric certification timelines and induction R&D. Five-to-ten year viability favors specialists with thermal engineering IP and established NSF relationships. Target acquisition profiles include European fabricators with automated rotation patents and distressed domestic gas-equipment manufacturers with installed base access. Watch California's Title 24 building code enforcement as inflection indicator for national electrification pace.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Technology Migration | EPA Energy Star thresholds disqualify legacy gas platforms from institutional procurement preference. |
| Equipment-as-a-Service Launch | Monthly subscription models penetrate independent operators with constrained balance sheets. |
| NSF Certification Investment | Sanitation testing protocols filter non-compliant imports from commercial distribution channels. |
| Food Truck Distribution Partnership | Compact tabletop configurations capture fastest-expanding end-use channel in California and Texas. |
| Cloud Kitchen Integration | Automated packaging and delivery logistics create equipment-plus-service demand from ghost operators. |
Research Methodology
Bottom-up foodservice operator modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with commercial kitchen equipment distributors, restaurant chain procurement directors, food truck operators, NSF certification engineers, and municipal building code officials combined with secondary validation. Sources include U.S. Department of Energy efficiency standards filings, EPA Energy Star certified product databases, NSF International sanitation listings, and foodservice equipment customs records. Triangulation between demand-side procurement patterns and supply-side production volumes validates segment-level outputs.
Input-output matrices map product type, fuel type, end user, and distribution channel dimensions across the projection horizon. CAGRs derive from replacement cycle analysis, regulatory mandate timelines, and end-use channel expansion rates. Induction heating adoption curves, food truck fleet growth, and Energy Star rebate program participation serve as industry-specific forecast inputs. Volume and value outputs reflect reconciliation between manufacturer shipment data and distributor sell-through tracking.
Inputs from EPA certification databases and municipal building code filings were available through the study window; gaps in food truck operator survey coverage introduce uncertainty bands in tabletop segment projections. Forecasts reflect assumptions around electrification mandate enforcement consistency and stainless steel price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Beverage Napkins Market
Food Service
Latin America Inflight Catering Market
Food Service
Global Sushi Restaurants Market
Food Service
Portion Cups Market
Food Service
Singapore Food Service Market
Food Service
Commercial Charbroiler Market
Food Service
Global Food Retail Market
Food Service
Street Vendors Market
Food Service
Charbroiler Market
Food Service
Commercial Grills Market
Food Service
Tabletop Pizza Oven Market
Food Service
Food Away from Home Market
Food Service
Mobile Food Services Market
Food Service
Bottled Water Cooler Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Switzerland Food Service Market