
 Commercial Slush Machine Market | 2026-2036
Commercial Slush Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Slush Machine Market Outlook
Convenience store chains is hardening as the dominant end-use vertical for commercial slush equipment. Taylor Company leverages its frozen beverage systems expertise to anchor relationships with major convenience retail operators. Elmeco competes through specialized Italian-engineered cooling systems that sustain premium positioning in European foodservice channels.
A commercial slush machine is a refrigerated dispensing appliance that freezes and agitates sugar-based liquid mixtures into a semi-frozen consistency, typically operating between -2°C and -4°C with continuous auger or paddle rotation to prevent solidification. The equipment serves quick-service restaurants, cinemas, and amusement venues requiring high-throughput frozen drink production. Floor-standing units dominate volume deployment in high-traffic locations where throughput requirements exceed countertop capacity. Frozen beverages as a use case captures the largest margin pool, while food trucks represent the fastest-growing end-user segment driven by mobile equipment downsizing trends.
NSF International standards govern sanitation and material safety for slush equipment sold in the United States, while CE marking and EU energy-efficiency directives regulate market access across European member states. These frameworks elevate compliance costs for smaller manufacturers while favoring established players with certified testing infrastructure. Stakeholders must monitor evolving energy-labeling thresholds and refrigeration refrigerant phase-down schedules to anticipate equipment redesign cycles and procurement timing.
Market Dynamics
Convenience store chains in the United States, Germany, and Japan are expanding frozen beverage programs, creating concentrated procurement power that compresses equipment margins while elevating throughput specifications for slush machine manufacturers.
Growth Catalysts
- EU Energy-Efficiency Labeling:The F-Gas Regulation and energy-labeling directives are accelerating refrigerant transitions toward lower-GWP alternatives, forcing equipment redesigns that favor manufacturers with certified testing infrastructure.
- Mobile Foodservice Expansion:Food trucks and mobile catering units are demanding compact, high-efficiency slush equipment, creating incremental volume in a previously underserved end-use segment.
- NSF International Sanitation Standards:Tightening material safety and cleanability requirements in the United States are raising barriers for uncertified imports while validating premium positioning for compliant domestic suppliers.
Market Restraints
- Refrigerant Input Volatility:Hydrofluorocarbon phase-down schedules under the Kigali Amendment are compressing supply availability and inflating costs for compressor-dependent cooling systems.
- Supply Concentration in Compressor Manufacturing:Critical refrigeration components originate from a narrow base of specialized suppliers in Germany and Japan, exposing equipment assemblers to allocation risk.
- Substitution by Pre-Packaged Frozen Beverages:Bag-in-box and ready-to-dispense frozen drink formats are capturing share in low-throughput locations, displacing capital-intensive on-premise equipment.
Strategic Opportunities
- Underpenetrated Japanese Convenience Retail:Frozen beverage attachment rates in Japanese convenience stores trail US benchmarks, presenting white-space expansion for equipment vendors with localized cooling specifications.
- Convergence of IoT and Predictive Maintenance:Connected slush machines with remote diagnostics and automated cleaning cycles are enabling subscription-based service models that decouple revenue from unit sales.
- Carbon Reduction Incentives:The US Inflation Reduction Act and EU Green Deal subsidies for energy-efficient commercial refrigeration are creating procurement pull for next-generation equipment with documented efficiency gains.
Industry Challenges
- Refrigeration Technician Scarcity:Specialized service capabilities for sealed-system repairs are concentrating in urban markets, extending downtime for rural and exurban equipment deployments.
- NSF Certification Timeline Compression:Sanitation validation cycles are lengthening as testing laboratories face backlog, delaying product launches and freezing engineering resources on legacy platforms.
- Legacy POS Integration Friction:New equipment with automated inventory tracking requires middleware development to connect with entrenched point-of-sale systems in major convenience retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Slush Machine Market |
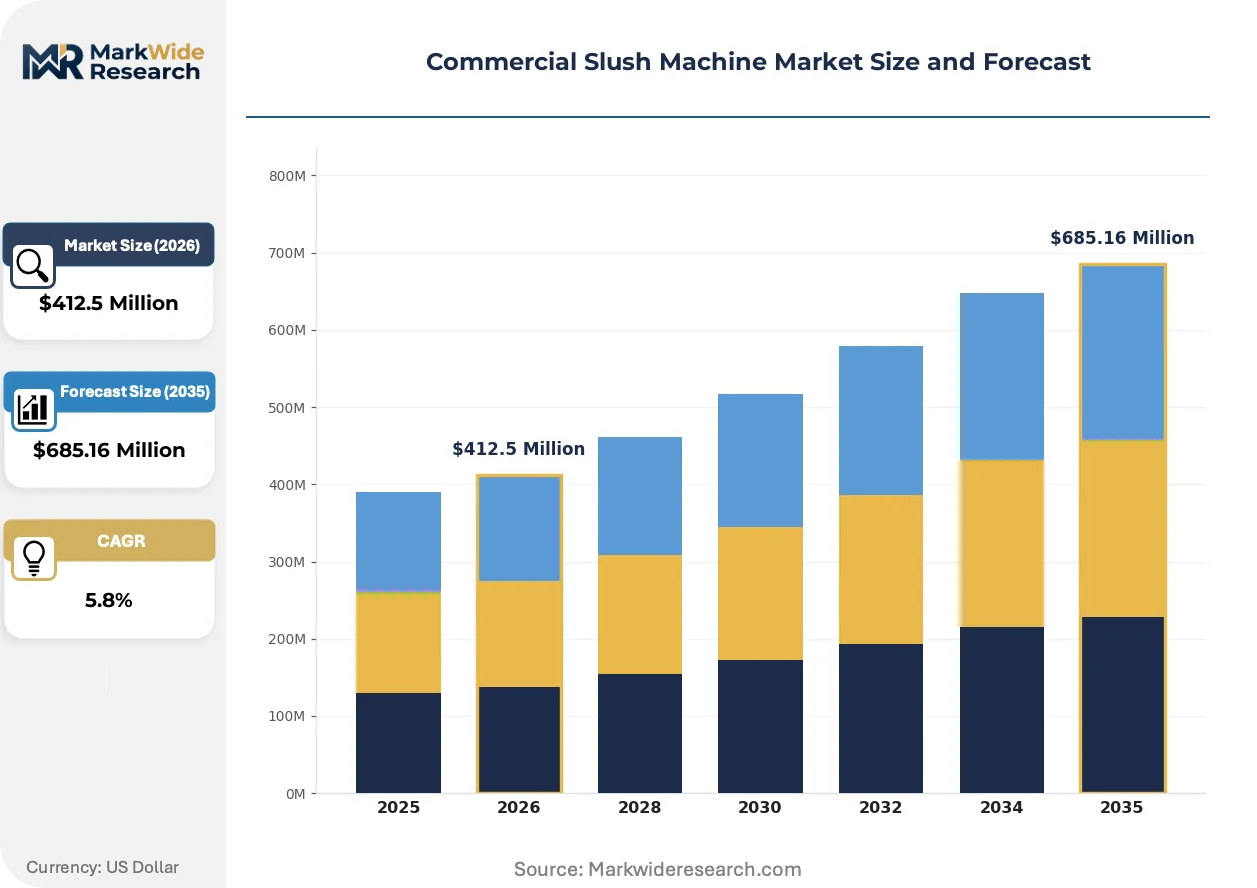
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Floor-standing, Portable, Industrial End User: Restaurants, Cafes, Food Trucks, Amusement Parks Use Case: Frozen Beverages, Cocktails, Desserts, Smoothies Power Rating: 500W, 1000W, 1500W, 2000W |
| Companies Covered | Taylor Company, Elmeco, Bunn-O-Matic Corporation, Donper America, Cofrimell, Vollrath, Electro Freeze, Carpigiani Group, Grindmaster-Cecilware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Slush Machine Market Strategic Shifts
Equipment intelligence and energy compliance are rewriting competitive differentiation in commercial slush systems. Manufacturers are racing to embed connectivity and sustainability credentials ahead of regulatory deadlines and buyer procurement refresh cycles.
Magnetic drive auger systems are eliminating mechanical seals and reducing maintenance intervals in high-throughput environments. Convenience store operators with 24-hour beverage programs are adopting these platforms fastest. This technology is rewriting total cost of ownership calculations by compressing service labor requirements and extending equipment lifecycles.
REACH restrictions on per- and polyfluoroalkyl substances are forcing gasket and seal material substitutions across equipment sold in European member states. Manufacturers with in-house polymer engineering capabilities are securing first-mover advantage in reformulation. The affected segment spans mid-capacity floor-standing units where thermal bridging risks are highest.
Leasing and equipment-as-a-service arrangements are displacing outright purchase in convenience retail procurement. Major chains are unbundling capital expenditure from operational budgets, favoring suppliers with captive financing arms. This pattern is most visible in the United States, where private-equity-backed store rollups prioritize balance-sheet efficiency over long-term asset ownership.
Commercial Slush Machine Market Segmentation
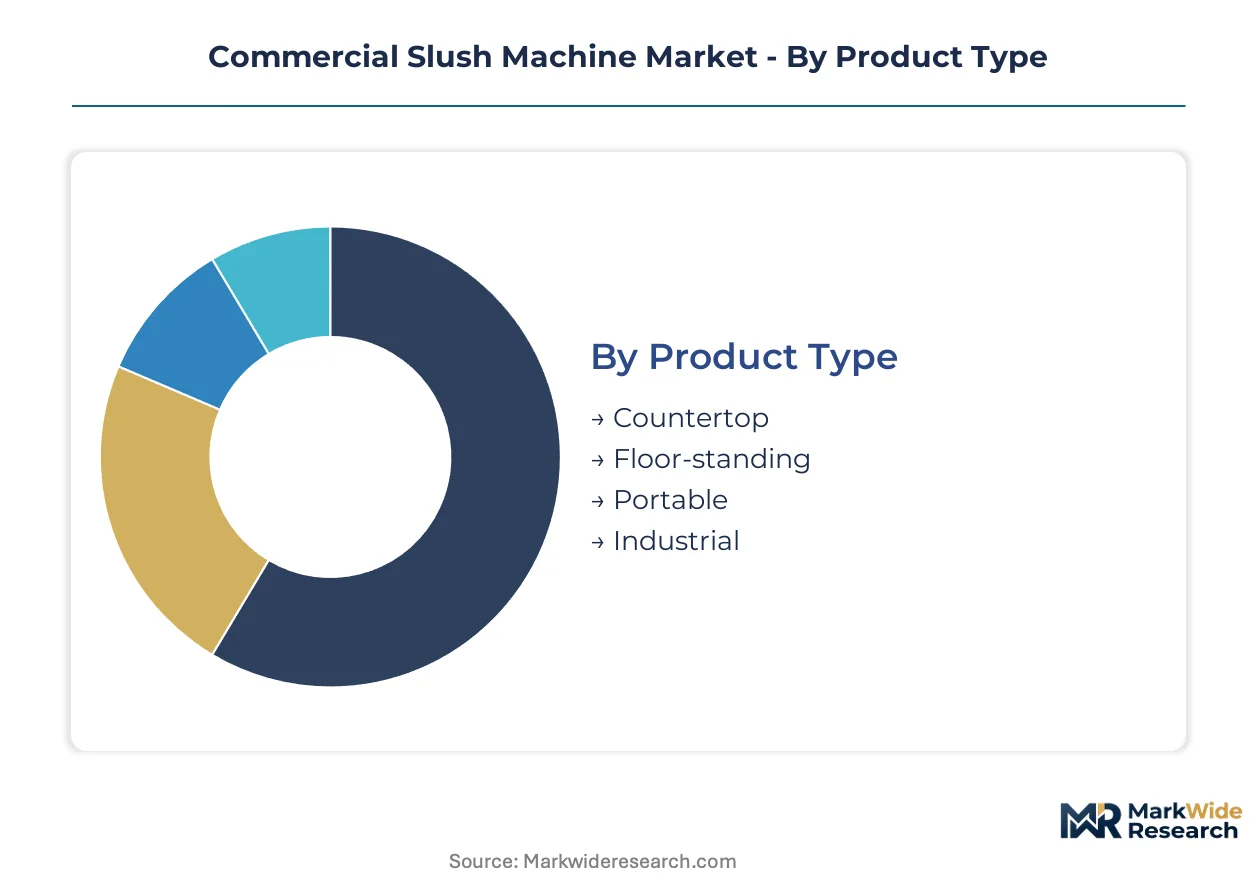
Equipment specification varies sharply across deployment contexts, with certification requirements and throughput demands fragmenting the addressable market into distinct procurement tiers. Understanding these divisions reveals where margin pools concentrate and where volume growth accelerates.
Product Type:
NSF International certification applies universally to units sold in the United States, while CE marking and EU energy-efficiency labeling govern European market access, with floor-standing units facing additional structural safety validations.
- Floor-standing:High-capacity units with dual or triple dispensing bowls serve 24-hour convenience store operations and cinema concessions requiring continuous output. Demand concentrates in the United States convenience retail sector, where chains like 7-Eleven and Circle K specify throughput rates above 100 servings per hour. NSF sanitation validation and energy compliance elevate procurement costs, compressing margins for uncertified competitors.
- Countertop:Compact single-bowl systems fit quick-service restaurant backbars and small-format cafes with space constraints below 0.5 square meters. Japanese convenience stores favor these units for frozen beverage trial programs, though attachment rates trail US benchmarks. CE marking and reduced refrigerant charge requirements under F-Gas Regulation favor European-engineered cooling systems.
- Portable:Battery-compatible or generator-ready units serve mobile catering and event-based deployment.
- Industrial:Continuous-batch systems for centralized production facilities supplying multiple retail endpoints.
Leading the category by volume: floor-standing. Growing fastest: portable.
End User:
Procurement authority and specification complexity diverge sharply between consolidated chain operators and fragmented independent accounts.
- Restaurants:Full-service and quick-service operators deploy countertop units for frozen beverage attachment to existing drink programs. Chains with centralized procurement negotiate equipment-as-a-service arrangements, unbundling capital expenditure from operational budgets. Private-equity-backed rollups in the United States prioritize balance-sheet efficiency over long-term asset ownership.
- Food Trucks:Mobile operators demand compact, high-efficiency equipment with generator compatibility and reduced vibration tolerance. This segment climbs the fastest as municipal food truck permitting expands across US metropolitan areas and European capitals. Downsized refrigeration systems and magnetic drive auger technology address maintenance access constraints in mobile deployment.
- Cafes:Independent coffee-focused operators with lower throughput requirements and price sensitivity.
- Amusement Parks:Seasonal high-traffic venues with extreme throughput peaks and extended idle periods.
Volume concentrates with restaurants. Steepest expansion trajectory: food trucks.
Use Case:
Margin structure and equipment specification intensity vary by product viscosity, alcohol content, and temperature stability requirements.
- Frozen Beverages:Sugar-based slush mixtures operating between -2°C and -4°C with continuous auger rotation capture the largest margin pool in convenience retail. Major chains specify automated cleaning cycles and IoT-enabled remote diagnostics to reduce service labor. The US Inflation Reduction Act subsidies for energy-efficient commercial refrigeration accelerate procurement of next-generation equipment.
- Cocktails:Alcohol-infused frozen drinks require modified cooling curves and corrosion-resistant materials for bar and hospitality deployment.
- Desserts:Higher-viscosity formulations with particulate inclusions demand specialized auger geometry and slower rotation speeds.
- Smoothies:Fresh fruit-based products with shorter holding times and stricter sanitation protocols.
Frozen beverages dominate revenue. Cocktails expand most quickly in European hospitality channels.
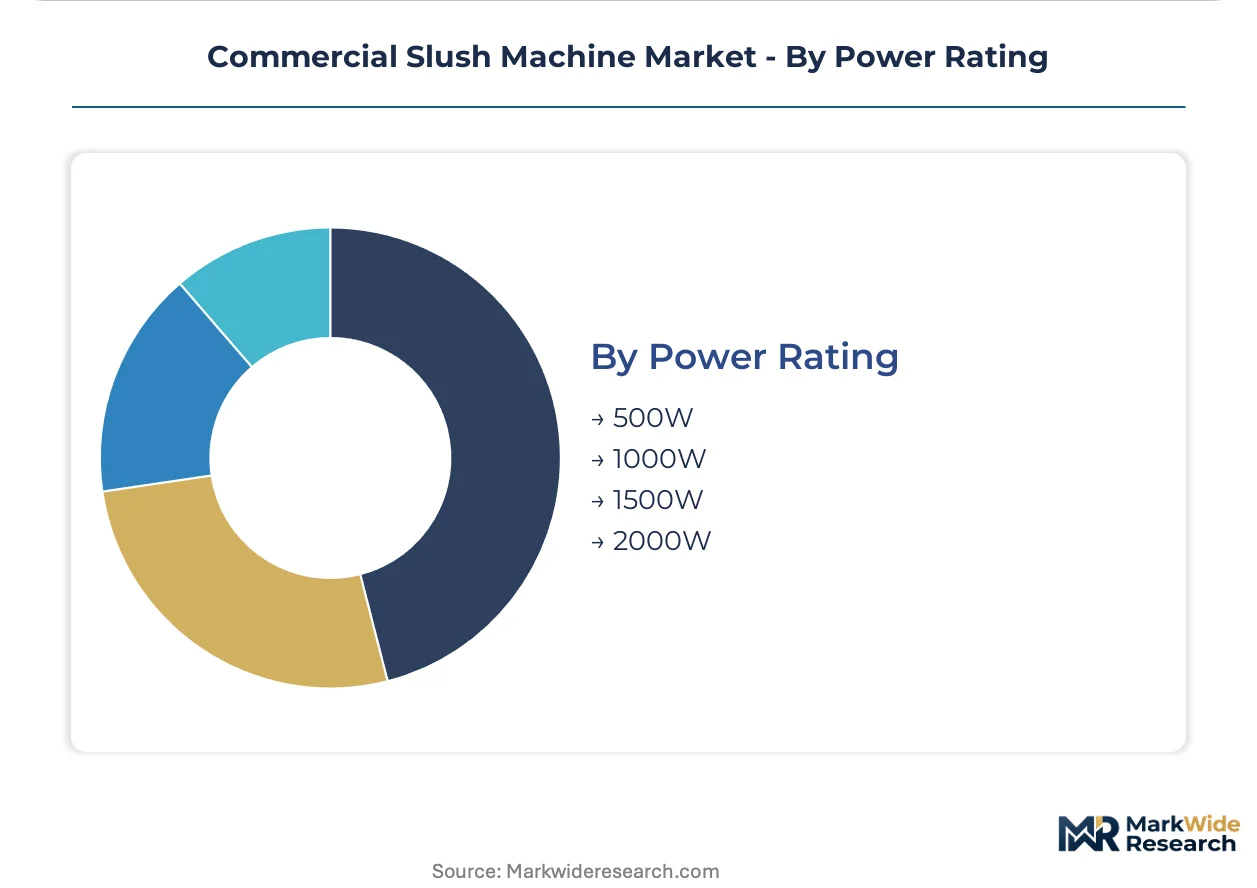
Power Rating:
Energy consumption tiers align with regulatory thresholds and operational cost sensitivity across end-use segments.
- 2000W:High-output systems for 24-hour convenience store chains and cinema multiplexes with sustained demand. EU energy-efficiency labeling and F-Gas Regulation refrigerant phase-downs force equipment redesigns favoring manufacturers with certified testing infrastructure. Carbon reduction incentives under the EU Green Deal subsidize procurement of documented efficiency gains.
- 1500W:Mid-capacity floor-standing units balancing throughput and energy cost for regional convenience operators.
- 1000W:Countertop systems for cafes and small-format quick-service restaurants with moderate volume requirements.
- 500W:Compact portable units for food trucks and mobile catering with battery or generator power constraints.
2000W systems lead by installed base. 500W portable configurations gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level tax incentives across the United States are concentrating frozen beverage equipment deployment in high-traffic retail corridors. Municipal permitting reforms in German industrial cities and Japanese prefectural subsidy programs are accelerating convenience store modernization.
United States
Convenience store chains in Texas and Florida are expanding 24-hour frozen beverage programs to capture highway traffic volume. The Inflation Reduction Act subsidizes energy-efficient commercial refrigeration procurement for documented efficiency gains. Dallas-Fort Worth anchors the largest concentration of equipment deployment, with Circle K and 7-Eleven specifying throughput rates above 100 servings per hour.
Germany
EU energy-efficiency labeling and F-Gas Regulation refrigerant phase-downs are forcing equipment redesigns across Baden-Württemberg manufacturing clusters. CE marking requirements and structural safety validations elevate compliance costs for market access. Stuttgart-based cooling system specialists are securing first-mover advantage in lower-GWP alternative integration.
Japan
Prefectural subsidy programs in Tokyo and Osaka are accelerating convenience store frozen beverage attachment trials, though penetration trails US benchmarks. METI efficiency standards and JIS certification requirements govern equipment specification. Kanto region operators favor compact countertop units for space-constrained urban formats.
Italy
REACH restrictions on per- and polyfluoroalkyl substances are forcing gasket material substitutions across Emilia-Romagna equipment fabrication. ECHA compliance timelines favor manufacturers with in-house polymer engineering capabilities. Bologna-area specialists dominate mid-capacity floor-standing production for European foodservice channels.
United Kingdom
Cinema multiplex operators in London and the Southeast are retrofitting high-output slush systems for concession throughput peaks. UKCA marking transitions post-Brexit are extending product validation cycles for imported equipment. Greater Manchester distribution hubs are consolidating spare parts logistics for national service coverage.
Commercial Slush Machine Market Competitive Environment
Top-tier vendors anchor premium-tier positioning through certified testing infrastructure, while mid-scale fabricators compete on regional compliance agility. The vendor base stratifies across three tiers: multinational frozen beverage system specialists, regional cooling equipment houses, and mobile-focused compact equipment entrants. Two dominant competitive moves are reshaping positioning: captive financing arms for equipment-as-a-service arrangements, and backward integration into compressor subsystem sourcing.
Within the multinational specialist tier, Taylor Company and Elmeco exemplify divergent geographic anchoring strategies. Taylor Company occupies a position calibrated to United States convenience retail procurement power, while Elmeco represents Italian-engineered cooling system specialization for European foodservice channels. Bunn-O-Matic Corporation sits within the mid-tier fabricator group, leveraging domestic certification infrastructure to validate premium positioning against uncertified import competition.
| Leading Market Players |
|---|
| Taylor Company |
| Elmeco |
| Bunn-O-Matic Corporation |
| Donper America |
| Cofrimell |
| Vollrath |
| Electro Freeze |
| Carpigiani Group |
| Grindmaster-Cecilware |
| Others |
Value Chain & Pricing Dynamics
United States convenience store chains wield concentrated procurement power that compresses equipment margins while elevating throughput specifications, locking the market into equipment-as-a-service pricing models that unbundle capital expenditure from operational budgets.
Pricing Analysis
Short lead-time premiums command pricing advantages for NSF-certified domestic suppliers against import competition facing extended validation cycles. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in mid-capacity floor-standing units is intensifying because refrigerant redesign cycles under F-Gas Regulation inflate engineering overhead. Regional convenience operators exhibit highest price sensitivity, while 24-hour chains with captive financing arms prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
NSF and CE certification gating restricts component sourcing to qualified suppliers with documented testing infrastructure. Compressor subsystems concentrate in Germany and Japan, while polymer engineering for gasket reformulation clusters in Italy. Critical inputs include hydrofluorocarbon refrigerants, magnetic drive auger assemblies, and corrosion-resistant bowl materials. Single-source vulnerability in specialized cooling component manufacturing exposes assemblers to allocation risk. Distribution runs through authorized service networks with regional spare parts hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where compressor subsystem sourcing and captive financing arms determine competitive endurance.
For Market Incumbents: Deepen backward integration into lower-GWP compressor technology to secure supply continuity amid Kigali Amendment phase-downs. Expand certified testing infrastructure to compress NSF validation timelines against emerging import competition. Magnetic drive auger patents and refrigerant redesign capabilities represent defensible moats. For New Entrants and Emerging Players: The price-point gap between Italian-engineered premium cooling systems and economy-tier Asian imports opens white-space for mid-market positioning. Target Japanese convenience retail with compact countertop units localized for METI efficiency standards. Pursue food truck mobile catering through generator-compatible portable configurations with reduced vibration tolerance. For Investors and Strategic Acquirers: The window for entry favors equipment-as-a-service operators with integrated financing platforms over pure hardware manufacturers. Long-term viability hinges on recurring revenue streams decoupled from unit sales cycles. Monitor IoT-enabled predictive maintenance adoption rates as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Sourcing | Secures supply continuity for Taylor Company and Elmeco amid German-Japanese component allocation constraints. |
| Equipment-as-a-Service Platform Launch | Enables Circle K and 7-Eleven to unbundle capital expenditure through captive financing arms. |
| Magnetic Drive Auger Patent Portfolio | Reduces maintenance intervals for 24-hour convenience operations with continuous beverage programs. |
| Lower-GWP Refrigerant Redesign | Aligns product lines with EU F-Gas Regulation deadlines and IRA subsidy qualification thresholds. |
| IoT Predictive Maintenance Integration | Supports subscription revenue models with remote diagnostics for slush equipment deployed across convenience retail networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with convenience store procurement directors, food truck operators, refrigeration service technicians, and OEM product managers combined with NSF International certification databases, EU energy-efficiency labeling registries, and compressor manufacturer technical specifications. Bottom-up equipment deployment estimates triangulated against top-down frozen beverage consumption trends.
Shipment volume reconciliation against refrigerant import data and convenience store chain capex disclosures validated segment-level projections across the modeling period. Segmentation dimensions included product type, end-user vertical, use case viscosity requirements, and power rating tiers. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Forecast inputs incorporated F-Gas Regulation phase-down schedules and municipal food truck permitting expansion trajectories.
Inputs from NSF International and METI were available through the study window; gaps in real-time food truck deployment counts introduce uncertainty bands in mobile segment projections. Forecasts reflect assumptions about refrigerant technology transition timelines and convenience retail consolidation patterns. A model refresh is warranted upon material change in IRA subsidy program structure or Kigali Amendment enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Coffee Equipment and Supplies Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Global Frozen Drink Machines Market