
 Specialty Commercial Deep Fryers Market | 2026-2036
Specialty Commercial Deep Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Commercial Deep Fryers Market Analytics
Induction heating technology is reconfiguring fryer architecture by replacing open-flame gas systems with precision electromagnetic coils that cut thermal lag and energy waste. The Middleby Corporation leverages its vertical manufacturing footprint to control component costs across countertop and floor fryer lines. Henny Penny anchors its position through R&D intensity in automated filtration systems that extend oil life cycles for high-volume operators. Electrolux Professional competes on European regulatory compliance, building CE-marked units that preempt Ecodesign Directive thresholds.
Specialty commercial deep fryers are thermostatically controlled vessels designed to maintain oil temperatures between 300°F and 375°F for consistent food preparation in high-throughput foodservice environments; most units employ stainless steel tanks with sediment zones and integrated filtration to manage particulate accumulation and oil degradation. Floor fryers dominate capital deployment among chain restaurants due to tank capacity and recovery speed, while automated fryers represent the fastest-growing technology segment as labor costs pressure operators toward programmable cook cycles and automatic basket lifts. Electric fryers command margin pools in urban installations where gas hookup restrictions and ventilation codes limit combustion-based equipment.
The U.S. Department of Energy sets minimum efficiency standards for commercial fryers under its Appliance and Equipment Standards Program, while the EPA oversees F-gas management in refrigeration-linked fryer components; in Europe, the Ecodesign Directive and REACH compliance shape material selection and energy labeling requirements for equipment sold across EU member states. Stakeholders must monitor how dual carbon goals in China and the EU AI Act's emerging classification of automated kitchen equipment reshape certification burdens and competitive access.
Market Dynamics
Induction heating coils are replacing open-flame gas burners across quick service restaurant fryer fleets, compressing thermal recovery times while triggering ventilation and electrical infrastructure retrofits that reshape operator capital planning.
Growth Catalysts
- Extended Menu Diversification:Chain restaurants in Texas, California, and Florida are expanding fryer counts to support chicken, seafood, and plant-based protein lines that require dedicated oil systems.
- EU Ecodesign Directive Thresholds:Tightening efficiency mandates for gas and electric fryer categories are accelerating replacement cycles among European foodservice operators seeking compliant equipment.
- Food Truck Permitting Surge:Mobile foodservice permitting activity in Florida and California is driving countertop electric fryer demand where gas hookups are physically impossible.
Market Restraints
- Stainless Steel Input Volatility:Tank and sediment zone fabrication depends on nickel-chromium alloy pricing that fluctuates with mining output from Indonesian and Philippine suppliers.
- Ventilation Code Friction:Urban jurisdictions in New York and Chicago enforce stringent hood and fire suppression requirements that add $15,000-$40,000 to gas fryer installations.
- Air Fryer Substitution:Countertop convection ovens marketed as oil-free alternatives are capturing trial orders from health-positioned fast-casual concepts.
Strategic Opportunities
- Automated Filtration Convergence:Integration of IoT oil monitoring with automated filtration cycles creates premium positioning for high-volume operators in Texas and California.
- India Foodservice Modernization:Quick service chain expansion in Mumbai and Bangalore presents untapped demand for CE-marked equipment compliant with BIS electrical safety standards.
- US Department of Energy Standards:Anticipated 2027 efficiency threshold updates will trigger preemptive replacement demand among operators seeking to avoid stranded asset risk.
Industry Challenges
- Electrical Infrastructure Retrofit Complexity:Induction fryer adoption requires 480V three-phase power upgrades that extend installation timelines and disrupt operational continuity.
- Oil Quality Certification Labor Gap:Automated filtration systems require technicians trained in polar compound testing and discard point protocols that exceed traditional equipment service skill sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Commercial Deep Fryers Market |
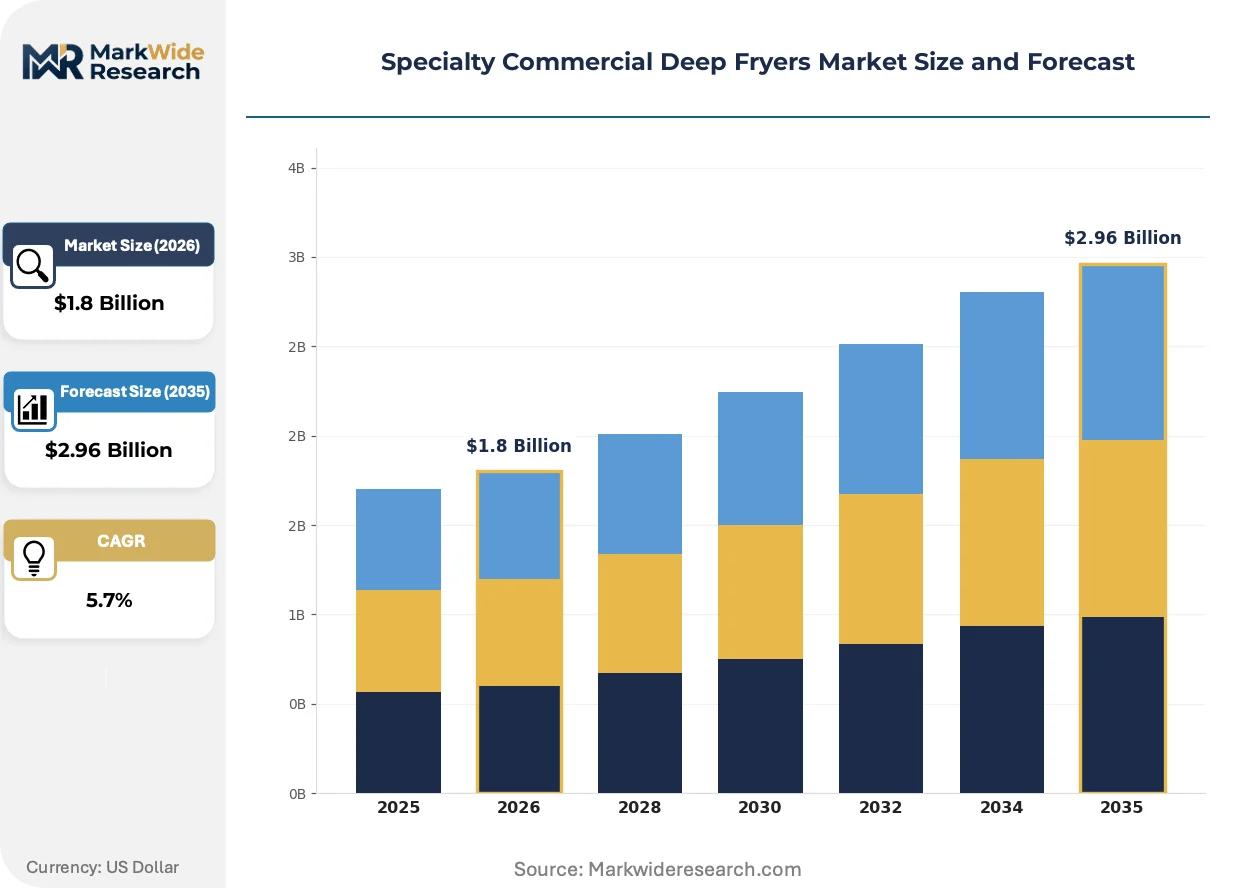
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Fryers, Floor Fryers, Gas Fryers, Electric Fryers Application: Restaurants, Food Trucks, Catering Services, Institutional Kitchens Technology: Manual Fryers, Automated Fryers, Digital Fryers, Induction Fryers End User: Quick Service Restaurants, Cafes, Diners, Bakeries |
| Companies Covered | The Middleby Corporation, Electrolux Professional, Henny Penny, Frymaster, Illinois Tool Works Inc., Standex International Corporation, Ali Group, Pitco, Avantco Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Commercial Deep Fryers Market Evolving Landscape
Electromagnetic heating architectures and automated cook-cycle programming are converging to eliminate labor touchpoints while redefining energy efficiency benchmarks across commercial kitchen equipment procurement.
Induction coil arrays are collapsing the thermal lag between batch cycles that previously constrained gas fryer throughput. High-volume operators in Texas and California are retrofitting floor fryer lines with electromagnetic vessels that reach setpoint in under ninety seconds. This compression of recovery time is collapsing the throughput gap between single and double-vat configurations, reducing capital intensity per pound of output.
The EU F-Gas Regulation is restricting hydrofluorocarbon use in refrigeration-linked fryer components including oil cooling systems. Equipment manufacturers serving European markets are redesigning heat exchangers around natural refrigerants and CO2 cascade systems. French and German operators are prioritizing CE-marked units that preempt 2027 phase-down thresholds, shifting procurement criteria toward total lifecycle carbon metrics.
Equipment-as-a-service contracts are displacing capital purchase models among mid-scale regional chains. Distributors in Florida and Ohio are bundling fryer hardware with preventive maintenance and oil management subscriptions that transfer filtration labor to service providers. This unbundling of ownership from operation is most visible among sandwich and chicken concepts with 15-50 unit footprints seeking to preserve balance sheet capacity for real estate expansion.
Specialty Commercial Deep Fryers Market Segmentation
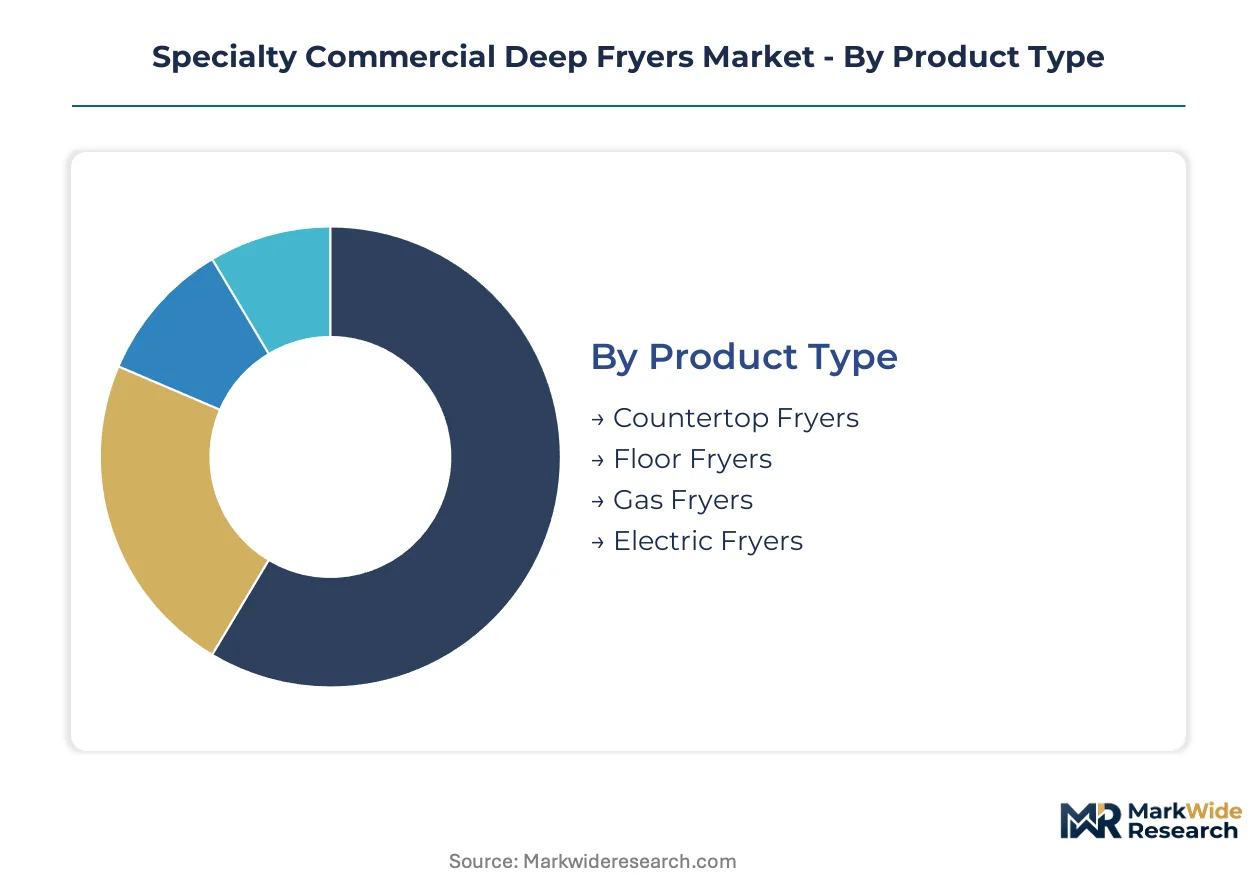
Deep fryer procurement patterns diverge sharply across operational environments. Equipment specifications, energy infrastructure, and labor models dictate which configurations dominate each foodservice vertical.
Product Type:
High-volume kitchens demand tank capacity and recovery speed; constrained footprints prioritize electrical flexibility and mobility.
- Countertop Fryers:Compact stainless steel vessels with 15-30 lb oil capacity designed for front-of-house visibility and space-constrained installations. Food truck operators in Florida and California specify these units where gas hookups are unavailable and ventilation hoods are impractical.
- Floor Fryers:Free-standing units with 40-80 lb tanks, sediment zones, and integrated filtration for continuous batch production. Chain restaurants in Texas deploy these for chicken and seafood lines requiring dedicated oil systems and rapid recovery between cycles.
- Gas Fryers:Open-flame or infrared burner systems delivering 90,000-150,000 BTU for thermal recovery. Suburban and exurban locations with existing gas infrastructure favor these for operating cost predictability.
- Electric Fryers:Immersion element or induction coil heating with precise thermostat control. Urban installations in New York and Chicago specify these where fire codes restrict combustion equipment and hood requirements escalate installation costs.
Established volume favors floor fryers; emerging adoption favors countertop units.
Application:
Throughput requirements and mobility constraints segment demand across fixed and itinerant foodservice models.
- Restaurants:Permanent installations with dedicated utility connections and ventilation infrastructure. Full-service and fast-casual concepts in California prioritize automated filtration and programmable cook cycles to reduce labor touchpoints.
- Food Trucks:Mobile operations requiring 208V or 240V electrical compatibility and compact footprints. Permitting density in Florida drives specification of electric countertop units with NSF certification for mobile food safety compliance.
- Catering Services:Event-based deployment with intermittent high-volume bursts. Rental and lease models dominate as operators seek equipment-as-a-service contracts to preserve capital for event logistics.
- Institutional Kitchens:Schools, hospitals, and corporate cafeterias with standardized menus and procurement protocols. USDA and FDA compliance requirements shape stainless steel grade and oil temperature logging specifications.
Fixed-location volume anchors restaurant procurement; mobility requirements accelerate food truck specification.
Technology:
Labor cost pressure and energy efficiency mandates are reconfiguring control architectures across fryer fleets.
- Manual Fryers:Thermostatic controls with operator-managed basket timing and filtration scheduling. Legacy installations in cost-sensitive diners and independent cafes retain these for capital avoidance.
- Automated Fryers:Programmable cook cycles with automatic basket lifts, shake timers, and oil quality monitoring. Quick service restaurants in Texas and California deploy these to compress labor per output unit and standardize product consistency.
- Digital Fryers:Touchscreen interfaces with recipe storage, HACCP logging, and IoT connectivity. Regional chains with 15-50 unit footprints specify these for centralized menu management and compliance documentation.
- Induction Fryers:Electromagnetic coil heating eliminating open flames and reducing thermal lag to under ninety seconds. High-volume operators retrofitting California and Texas kitchens specify these despite 480V three-phase infrastructure requirements.
Manual systems retain installed base; induction configurations are climbing the fastest.
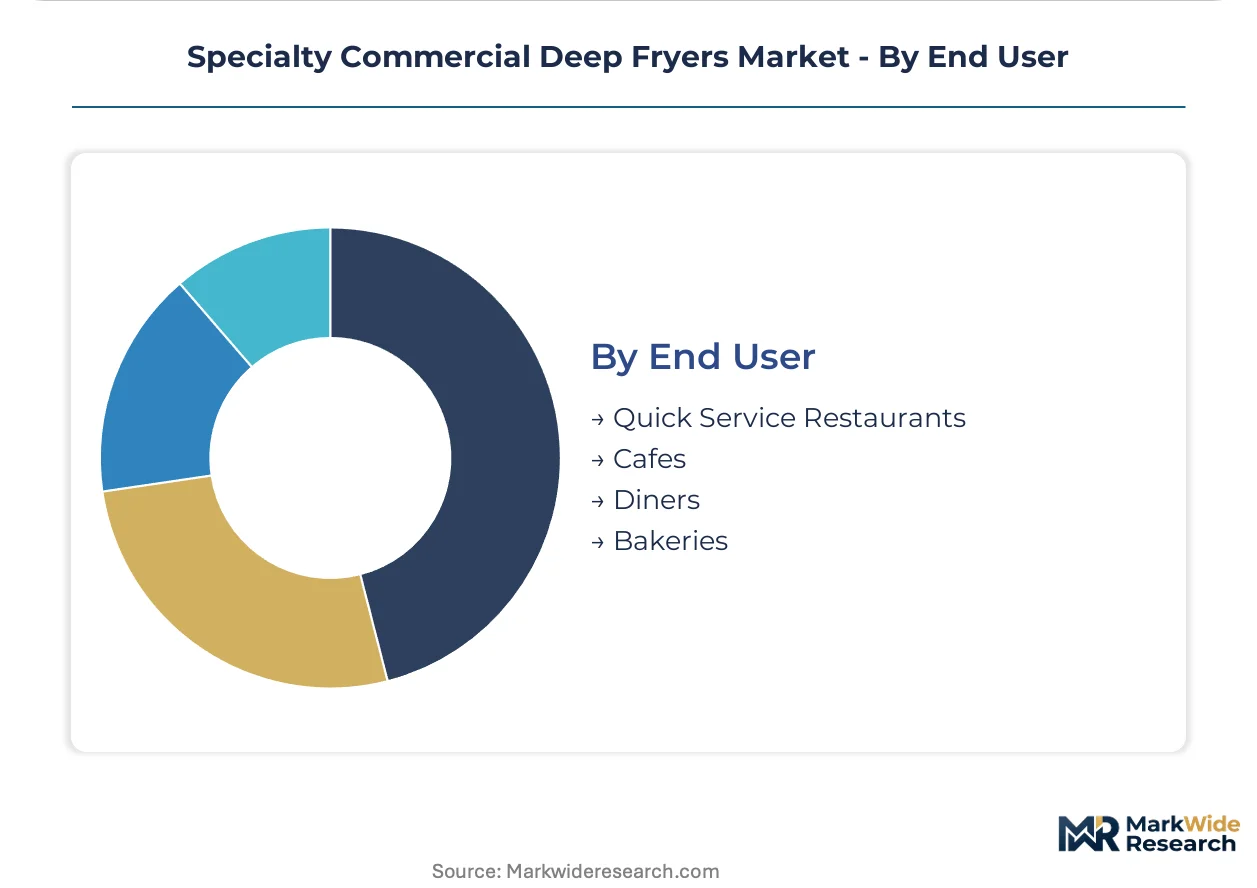
End User:
Menu complexity and throughput velocity determine equipment specification intensity across foodservice formats.
- Quick Service Restaurants:High-frequency fryer utilization with dedicated protein lines and extended operating hours. Chains in Texas, California, and Florida expand fryer counts to support chicken, seafood, and plant-based offerings.
- Cafes:Limited fried menu items with intermittent batch requirements. Smaller electric countertop units dominate where coffee and beverage sales anchor the revenue model.
- Diners:All-day breakfast and comfort food menus with moderate throughput. Cost-sensitive operators prioritize gas floor fryers with basic filtration for french fry and protein production.
- Bakeries:Specialized applications including doughnuts, fritters, and churros requiring precise temperature stability for yeast-raised and cake batters.
Quick service restaurants concentrate capital deployment; bakeries represent specialized niche specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Italian manufacturers export precision-engineered fryer systems to quick service restaurant operators across North America and the Middle East, establishing Europe as the primary sourcing corridor for high-efficiency commercial kitchen equipment.
United States
Chain restaurant expansion in Texas, California, and Florida drives floor fryer procurement for dedicated chicken and seafood lines. The U.S. Department of Energy's Appliance and Equipment Standards Program mandates minimum efficiency thresholds that accelerate replacement cycles among legacy gas fryer installations. Houston and Dallas operators retrofit kitchens with induction coil systems despite 480V three-phase infrastructure requirements.
Germany
Industrial kitchen equipment fabricators in Baden-Württemberg and North Rhine-Westphalia supply CE-marked fryers compliant with Ecodesign Directive thresholds. The EU F-Gas Regulation restricts hydrofluorocarbon use in refrigeration-linked oil cooling systems, forcing heat exchanger redesigns around natural refrigerants. Stuttgart-area manufacturers preempt 2027 phase-down deadlines with CO2 cascade system integration.
China
Dual carbon goals reshape material selection and energy labeling for equipment targeting domestic foodservice modernization. The Ministry of Ecology and Environment enforces stricter emissions standards on manufacturing facilities producing stainless steel tanks and sediment zones. Shanghai and Guangzhou quick service chains specify automated filtration systems to compress labor costs per output unit.
India
Quick service expansion in Mumbai and Bangalore generates demand for equipment compliant with BIS electrical safety standards. The Bureau of Indian Standards certifies countertop electric units for food truck operators where gas hookups remain unavailable. Karnataka-based cloud kitchen clusters prioritize NSF-certified compact fryers with 208V compatibility.
United Arab Emirates
Hospitality sector investment in Dubai and Abu Dhabi drives specification of premium automated fryers with IoT oil monitoring. MOHAP food safety regulations mandate HACCP logging capabilities for commercial kitchen equipment procurement. Dubai International Airport concession operators deploy high-recovery floor fryers for 24-hour continuous batch production.
Specialty Commercial Deep Fryers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base clusters around three strategic archetypes: diversified kitchen equipment conglomerates with vertical manufacturing footprints, filtration-technology specialists leveraging R&D intensity, and regional fabricators serving cost-sensitive independent operators. Competitive moves concentrate on automated cook-cycle programming and equipment-as-a-service contract structures that transfer maintenance liability to distributors.
Within the diversified equipment tier, The Middleby Corporation and Electrolux Professional occupy positions anchored by multi-product portfolio breadth and regulatory compliance capabilities. Henny Penny exemplifies the filtration-specialist archetype through concentrated investment in oil life-cycle extension systems. Among North American-focused manufacturers, Illinois Tool Works Inc. and Standex International Corporation represent the mid-scale industrial conglomerate model with captive distribution channels. Ali Group and Pitco sit within the European quality-certification tier, leveraging CE marking and REACH compliance as competitive differentiators for export markets.
| Leading Market Players |
|---|
| The Middleby Corporation |
| Electrolux Professional |
| Henny Penny |
| Frymaster |
| Illinois Tool Works Inc. |
| Standex International Corporation |
| Ali Group |
| Pitco |
| Avantco Equipment |
| Others |
Value Network & Pricing Analysis
Nickel-chromium alloy volatility from Indonesian and Philippine mining output determines both the spread between induction and gas fryer pricing tiers and the geographic clustering of stainless steel tank fabrication. Buyers face compressed margins when alloy prices spike, forcing tier migration toward standard-efficiency gas units despite long-term operating cost penalties.
Pricing Analysis
The technology-generation pricing gap separates legacy open-flame gas systems from electromagnetic induction architectures and emerging IoT-enabled digital fryers. Three-tier pricing structure across premium automated filtration, standard programmable electric, and economy manual gas levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Middleby and Electrolux are consolidating component sourcing across countertop and floor product lines. Quick service restaurant chains with 15-50 unit footprints exhibit highest price sensitivity, while Dubai airport concessionaires and hospital systems prioritize lifecycle efficiency over acquisition cost.
Supply Chain Analysis
Contract manufacturing capacity for heating elements and control systems concentrates among specialized EMS providers in China, South Korea, and Taiwan serving the commercial kitchen equipment sector. Stainless steel tank fabrication draws from nickel-chromium alloy stockpiles in Indonesia and the Philippines, with electromagnetic coil assemblies sourcing copper windings from Chinese foundries. Single-source vulnerability runs through Indonesian nickel export licensing fluctuations that disrupt alloy pricing predictability. Distribution runs through manufacturer-direct sales teams for chain accounts and regional foodservice equipment distributors serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among quick service restaurant chains with 15-50 unit footprints that negotiate fleet-wide equipment-as-a-service contracts, fragmenting the independent operator segment and compressing distributor margins.
For Market Incumbents: Harden automated filtration R&D moats against emerging IoT-native entrants by accelerating oil quality sensor integration and securing exclusive service technician training partnerships. Vertical integration into electromagnetic coil manufacturing reduces exposure to Taiwanese copper winding price volatility. Prioritize CE marking investments ahead of EU F-Gas Regulation phase-down deadlines to preempt competitor positioning in German and French export markets. For New Entrants and Emerging Players: Cloud kitchen clusters in Bangalore and Mumbai represent the most penetrable entry point for CE-marked equipment compliant with BIS electrical safety standards, where incumbent presence remains thin and procurement protocols favor certified imports over domestic alternatives. Food truck permitting corridors in Florida and California offer secondary white-space for NSF-certified compact electric units with 208V compatibility. Go-to-market execution through equipment-as-a-service bundling with preventive maintenance subscriptions neutralizes capital-constrained buyer resistance. For Investors and Strategic Acquirers: Anticipated U.S. Department of Energy efficiency threshold updates reshape the acquisition landscape by stranding legacy gas fryer installed bases and elevating premium positioning for induction-ready manufacturers. Five-to-ten year viability favors targets with captive electromagnetic heating technology and established 480V three-phase installation service networks. Monitor quarterly permitting velocity for food trucks and cloud kitchens in Texas, Florida, and Karnataka as demand inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Filtration Integration | IoT oil monitoring extends equipment life cycles for high-volume Texas and California operators. |
| Induction Heating Transition | Electromagnetic coil adoption compresses thermal recovery below ninety seconds in retrofit installations. |
| Equipment-as-a-Service Expansion | Subscription bundling transfers maintenance liability to distributors serving 15-50 unit regional chains. |
| CE Marking Preemption | Early Ecodesign Directive compliance secures German and French procurement preference ahead of 2027 thresholds. |
| Cloud Kitchen Penetration | BIS-certified compact fryers capture Mumbai and Bangalore demand from underserved quick service expansion. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with quick service restaurant operations directors, foodservice equipment procurement managers, commercial kitchen design consultants, and aftermarket service technicians; and secondary validation against U.S. Department of Energy Appliance Standards Program filings, EU Ecodesign Directive compliance databases, NSF certification registries, and Bureau of Indian Standards electrical safety listings. Bottom-up unit shipment estimates by product type and technology tier were triangulated against top-down manufacturer revenue disclosures.
Forecast inputs span induction versus gas fryer replacement cycles, food truck permitting velocity in Florida and California, cloud kitchen cluster formation in India, and EU F-Gas Regulation phase-down compliance timelines. Segmentation dimensions modeled include product type, heating technology, automation level, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical replacement cycle data and anticipated efficiency standard revision impacts. Oil price volatility and stainless steel alloy input costs were treated as exogenous sensitivity variables.
Stress conditions across nickel-chromium alloy pricing, 480V three-phase infrastructure retrofit completion rates, and air fryer substitution trial conversion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timing and chain restaurant expansion cadence. Quarterly review of food truck permitting data, EU F-Gas Regulation enforcement actions, and induction fryer installation backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Slush Machine Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Meal Delivery Carts and Racks Market
Food Service Equipment
Global Frozen Drink Machines Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Beverage Refrigeration Market