
 Convection Ovens Market | 2026-2036
Convection Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Convection Ovens Market Analysis
Market Dynamics
Commercial kitchen equipment distribution is reconfiguring around direct-to-operator digital platforms and consolidated foodservice dealer networks. Miele leverages its premium brand equity to sustain pricing power in built-in residential segments across European markets. Blodgett anchors its position through specialized heavy-duty oven engineering for high-volume restaurant chains. Bosch competes on integrated smart-home connectivity, extending its appliance ecosystem into convection-enabled cooking systems.
Convection ovens employ forced-air circulation via integrated fans to distribute heat uniformly, reducing cook times by 25-30% compared with conventional radiant models; this thermal efficiency serves commercial kitchens requiring throughput maximization and residential users seeking precision baking. Built-in ovens dominate margin pools in premium residential channels, while commercial ovens lead volume throughput in foodservice deployment. Electric energy source variants are displacing gas configurations in regions with decarbonization mandates, though dual fuel retains share among chef-centric professional users. Catering application demand tracks event industry recovery and ghost kitchen proliferation.
The US Department of Energy enforces minimum efficiency standards for commercial cooking equipment, while the EU Ecodesign Directive and CE marking requirements shape product compliance costs for manufacturers accessing European markets. China's GB standards and SAMR oversight govern domestic appliance safety and energy labeling, influencing export-oriented production decisions. Stakeholders must monitor evolving electrification subsidies and carbon border adjustments that will determine competitive cost structures across manufacturing footprints.
Market Dynamics
Electrification mandates across major economies are forcing a wholesale reconfiguration of energy sourcing in commercial and residential convection oven manufacturing, compressing gas equipment lifecycles while elevating compliance engineering costs.
Growth Catalysts
- EU Ecodesign Directive:Energy efficiency thresholds are accelerating electric convection oven adoption in European foodservice operations, creating replacement demand for aging gas-fired equipment.
- Ghost kitchen proliferation:Delivery-only restaurant formats in urban United States clusters are deploying compact high-throughput convection systems to maximize output per square meter.
- China's hospitality infrastructure investment:Hotel construction pipelines in tier-one cities are specifying built-in convection ovens as standard amenity packages.
Market Restraints
- Steel and aluminum input volatility:Stainless steel enclosure costs fluctuate with commodity index movements, compressing margin predictability for mid-tier manufacturers.
- Gas-to-electric retrofit complexity:Existing commercial kitchen ventilation and electrical infrastructure in legacy United States restaurants limits rapid equipment switching.
- Dual fuel technical ceiling:Combined gas-electric systems face inherent efficiency trade-offs that prevent full electrification benefits from being realized.
Strategic Opportunities
- India commercial foodservice:Organized restaurant chains in Mumbai and Delhi are modernizing kitchen equipment bases, creating first-mover positioning for energy-efficient convection suppliers.
- Cloud-connected predictive maintenance:IoT sensor integration with convection ovens enables remote diagnostics and service revenue streams.
- United States IRA commercial electrification incentives:Tax credits for electric cooking equipment purchases are narrowing total-cost-of-ownership gaps versus gas alternatives.
Industry Challenges
- Commercial kitchen technician shortage:Skilled service personnel capable of repairing sophisticated fan-motor and control-board assemblies are concentrated in major metropolitan areas.
- Multi-certification timelines:Simultaneous UL, CE marking, and GB standard compliance testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convection Ovens Market |
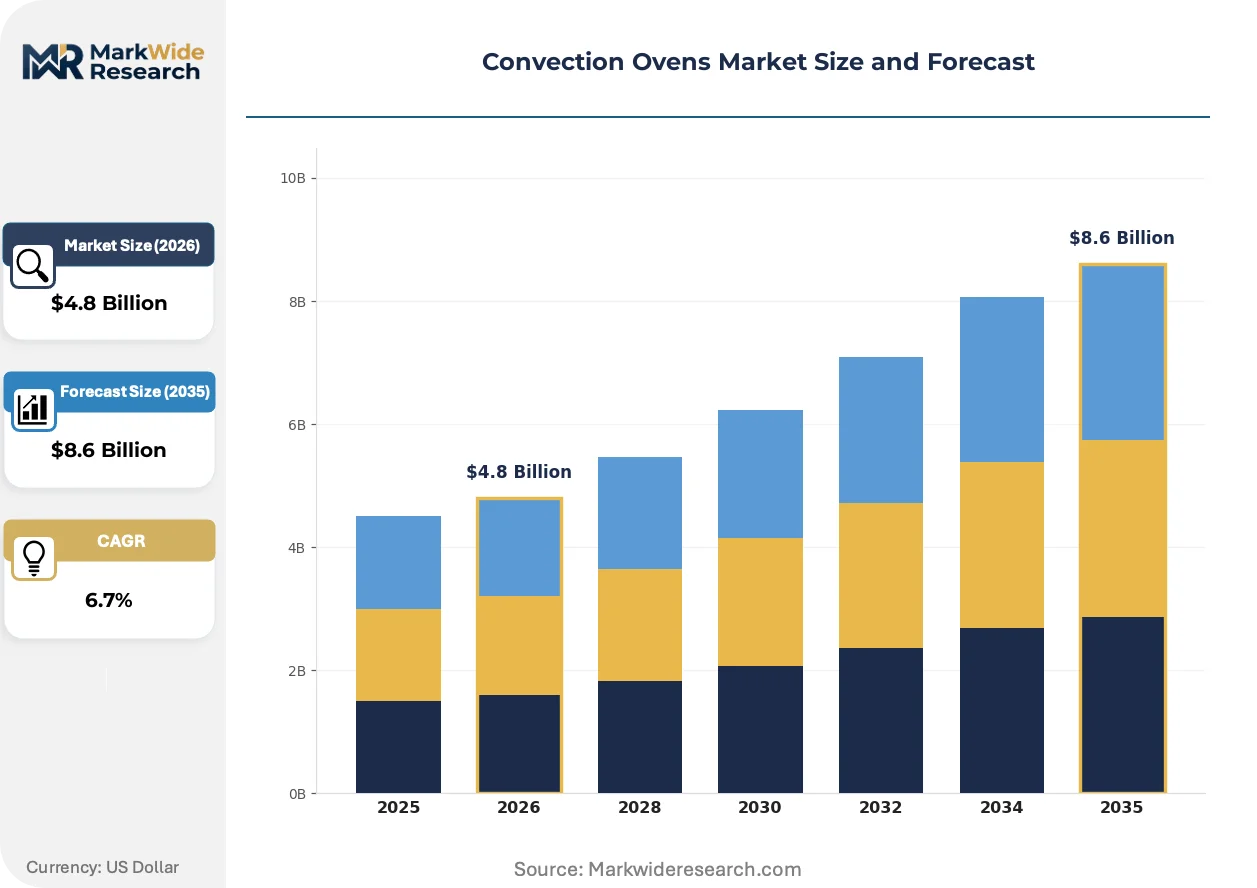
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Ovens, Commercial Ovens, Built-in Ovens, Industrial Ovens Application: Residential Cooking, Bakery, Restaurant Services, Catering Energy Source: Electric, Gas, Dual Fuel, Solar End User: Households, Food Service Providers, Hotels, Catering Companies |
| Companies Covered | Miele, Breville, Blodgett, Bosch, Ninja, Moffat, Thermador, Cooking Performance Group, Wolf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convection Ovens Market Emerging Trajectories
Connected cooking platforms and precision thermal management systems are redefining equipment value propositions, shifting competitive advantage from hardware durability toward data-enabled operational optimization.
Smart convection ovens equipped with embedded sensors and Wi-Fi connectivity are digitizing kitchen workflow management. Full-service restaurant chains in the United States are piloting these systems to synchronize cook cycles with point-of-sale demand signals. The technology is digitizing how kitchen labor is scheduled and inventory is depleted, compressing food waste metrics.
REACH chemical restrictions and F-Gas Regulation phase-downs in Europe are eliminating certain insulation and refrigerant-adjacent materials from convection oven supply chains. Manufacturers serving EU markets are reformulating thermal barrier compounds and redesigning blower motor housings. Commercial equipment lines face the steepest compliance cost increases due to larger material volumes.
Foodservice operators are consolidating vendor relationships and demanding lifecycle service bundling rather than transactional equipment purchases. Dealer networks in Germany are responding with subscription-based maintenance packages. This pattern is most pronounced in high-volume bakery and quick-service verticals where uptime penalties exceed capital depreciation concerns.
Convection Ovens Market Segmentation
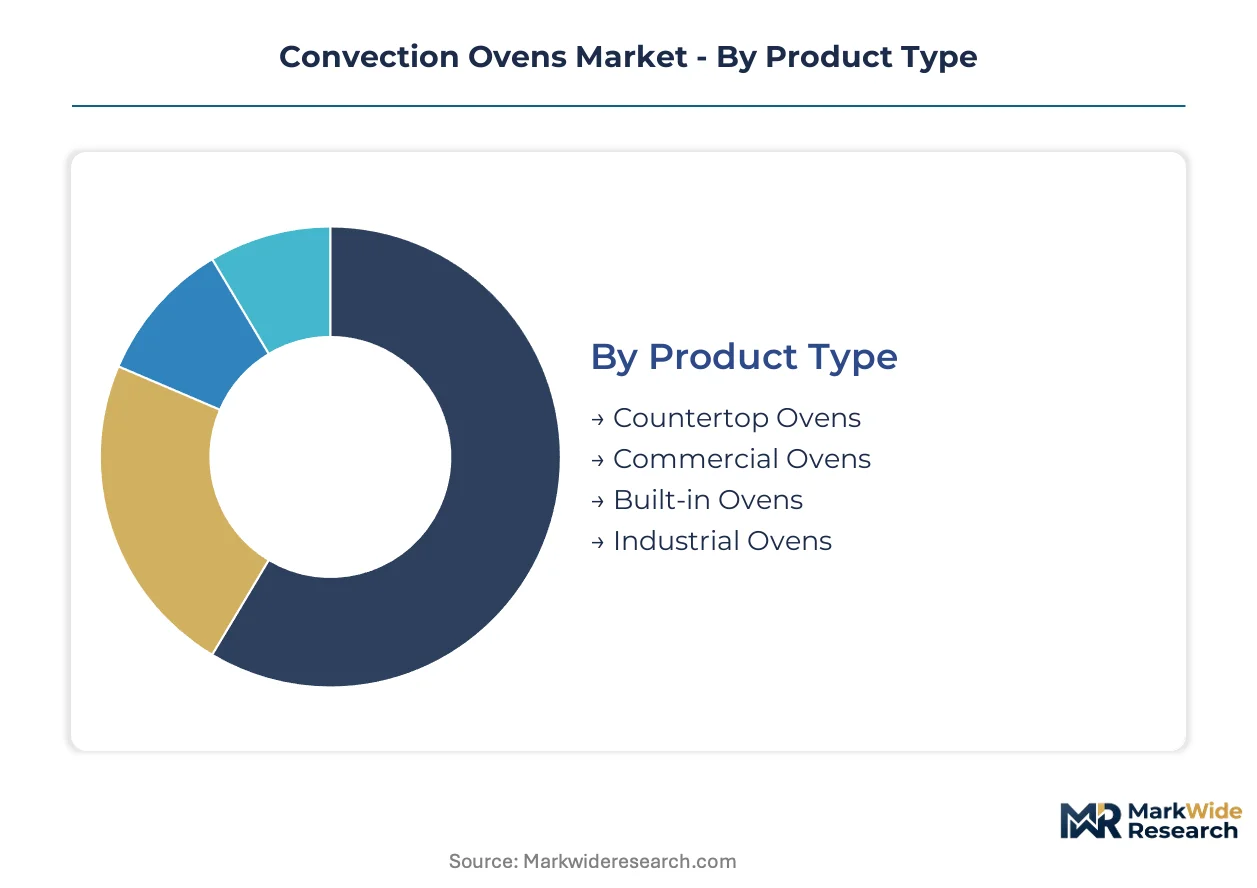
Convection oven segmentation reveals divergent service requirements across installation types and operational intensities. Built-in residential units demand specialized technician networks for warranty repairs, while commercial deployments prioritize uptime guarantees over capital costs.
Product Type:
After-sales-service intensity varies dramatically across installation formats, with built-in and commercial systems requiring dedicated technician certification programs that countertop units bypass entirely.
- Built-in Ovens:These appliances integrate permanently into kitchen cabinetry with hardwired electrical connections and custom trim kits. Demand clusters in Germany and the United States where residential renovation cycles favor premium kitchen specifications; manufacturers must maintain authorized installer networks to preserve warranty coverage.
- Commercial Ovens:Heavy-duty stainless steel enclosures house high-capacity fan systems rated for continuous daily operation. United States ghost kitchen operators and European hotel chains specify these for throughput maximization; service contracts now bundle predictive maintenance to minimize downtime penalties.
- Countertop Ovens:Portable plug-in units serve small foodservice operations and residential secondary cooking stations.
- Industrial Ovens:Large-format systems support centralized bakery production and contract manufacturing facilities.
Built-in Ovens holds the largest share; momentum sits with Commercial Ovens.
Application:
Volume concentration follows end-use operational rhythms, with restaurant and catering applications running equipment through multiple daily cycles that accelerate wear patterns versus residential intermittent use.
- Restaurant Services:Full-service and quick-service kitchens deploy convection systems as primary cooking platforms for protein roasting and vegetable preparation. United States chain operators standardize on specific models to simplify training and parts inventory; the segment climbs the fastest as delivery-format proliferation expands kitchen counts.
- Catering:Mobile and event-based foodservice requires equipment that withstands transport vibration and rapid setup cycles. European event industry recovery and corporate hospitality spending in China drive replacement of aging equipment fleets; rental-service bundling is displacing outright purchase in this segment.
- Residential Cooking:Home kitchens prioritize even baking performance and self-cleaning convenience over throughput.
- Bakery:Dedicated pastry operations demand precise humidity control and consistent temperature recovery after door openings.
Restaurant Services commands the greatest volume; Catering shows the steepest expansion trajectory.
Energy Source:
Regulatory pressure is reconfiguring procurement criteria, with electric variants gaining specification share where decarbonization mandates override chef preference for gas responsiveness.
- Electric:Resistance-element and induction-based systems dominate new construction specifications in jurisdictions with electrification mandates. The EU Ecodesign Directive and United States IRA commercial incentives narrow total-cost-of-ownership gaps against gas alternatives; foodservice operators in California and New York face regulatory deadlines accelerating fleet conversion.
- Dual Fuel:Combined gas cooktop and electric oven configurations retain preference among professional chefs seeking responsive stovetop control with dry oven heat. High-end residential markets in Germany and professional kitchens in Italy specify these systems despite premium pricing; efficiency trade-offs limit penetration in markets with strict carbon targets.
- Gas:Conventional gas-fired convection retains installed base in legacy United States restaurants where electrical infrastructure upgrades prove cost-prohibitive.
- Solar:Photovoltaic-integrated systems serve off-grid commercial installations and sustainability-certified hospitality operations in sun-rich climates.
Electric captures the dominant position; Dual Fuel defends its niche most tenaciously.
End User:
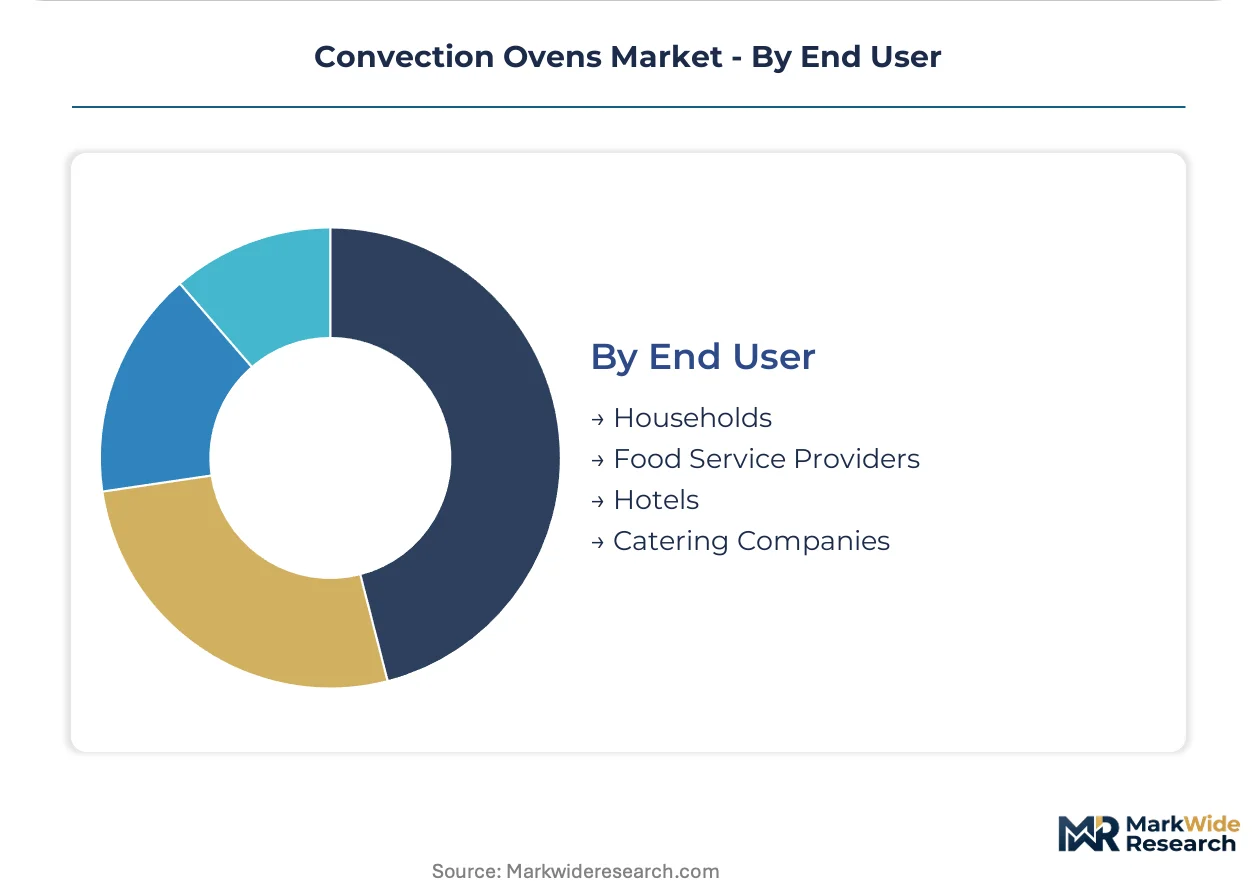
Procurement authority fragmentation shapes sales channel strategy, with consolidated foodservice groups negotiating enterprise pricing while dispersed households purchase through retail intermediaries.
- Food Service Providers:Multi-unit restaurant operators and contract foodservice companies standardize equipment specifications across locations to reduce training burden and spare parts complexity. United States institutional caterers and European motorway service area operators deploy convection systems at scale; procurement teams now require IoT connectivity for centralized performance monitoring.
- Hotels:Full-service properties specify built-in convection as standard in-suite amenities and commercial-grade systems for banquet production. Construction pipelines in China's tier-one cities and renovation cycles in United States urban centers drive specification activity; brand standards increasingly mandate energy efficiency certifications.
- Households:Individual consumers select based on kitchen design integration and brand reputation.
- Catering Companies:Event-focused operators balance equipment portability against output capacity.
Food Service Providers generate the highest absolute demand; Hotels exhibit the most concentrated growth concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Energy enforces efficiency standards that shape commercial kitchen equipment procurement across North American foodservice operations. Regulatory pressure from Brussels to Beijing is reconfiguring manufacturer compliance strategies and end-user purchasing criteria.
United States
Ghost kitchen clusters in New York, Los Angeles, and Chicago deploy compact high-throughput convection systems to maximize output per square meter. The Inflation Reduction Act offers commercial electrification tax credits that narrow total-cost-of-ownership gaps versus gas alternatives. California and New York face regulatory deadlines that accelerate electric equipment fleet conversion in legacy restaurants.
Germany
Residential renovation cycles favor premium built-in kitchen specifications with hardwired electrical connections and custom trim integration. The EU Ecodesign Directive mandates energy efficiency thresholds that accelerate electric convection adoption and compress gas equipment lifecycles. Bavaria and North Rhine-Westphalia concentrate authorized installer networks that preserve warranty coverage for Miele and Bosch deployments.
China
Hotel construction pipelines in Shanghai, Beijing, and Shenzhen specify built-in convection ovens as standard in-suite amenity packages. GB standards and SAMR oversight govern domestic appliance safety and energy labeling, influencing export-oriented production decisions. The Yangtze River Delta hosts manufacturing clusters that supply both domestic hospitality infrastructure and international commercial foodservice markets.
India
Organized restaurant chains in Mumbai and Delhi modernize kitchen equipment bases, creating first-mover positioning for energy-efficient convection suppliers. BIS certification requirements and FSSAI food safety protocols shape import compliance timelines for foreign manufacturers. Maharashtra and Gujarat concentrate commercial foodservice investment as organized retail and hospitality formats expand beyond tier-one cities.
United Kingdom
Full-service restaurant chains standardize equipment specifications to simplify training and parts inventory across multi-location operations. REACH chemical restrictions eliminate certain insulation materials from convection oven supply chains, forcing thermal barrier compound reformulation. London and the Southeast anchor dealer networks that bundle subscription-based maintenance packages for high-volume bakery and quick-service verticals.
Convection Ovens Market Vendor Landscape
Premium appliance specialists and commercial foodservice engineers split the market into distinct capability domains with limited overlap. The installed base fragments across residential built-in channels, heavy-duty restaurant chains, and compact countertop formats. Three archetypes dominate: heritage European premium brands, North American commercial specialists, and Asian-origin volume manufacturers. Consolidation pressures favor portfolio diversification and strategic service bundling over pure equipment sales.
Within the heritage premium tier, Miele and Bosch exemplify sustained pricing power through authorized installer networks and smart-home ecosystem integration. Blodgett anchors the heavy-duty commercial segment where specialized engineering for continuous daily operation commands specification loyalty among United States ghost kitchen operators and European hotel chains. These three names represent the strategic poles around which mid-tier competitors and private-label alternatives orbit.
| Leading Market Players |
|---|
| Miele |
| Breville |
| Blodgett |
| Bosch |
| Ninja |
| Moffat |
| Thermador |
| Cooking Performance Group |
| Wolf |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese stainless steel fabrication is compressing supplier margins across convection oven enclosure manufacturing, forcing tier-one producers to absorb cost volatility while mid-tier competitors retreat from long-term contract bidding.
Pricing Analysis
Geographic price spreads between German-engineered premium built-in units and Asian-origin commercial equipment now exceed three-to-one at wholesale, with Miele and Bosch commanding authorized-installer premiums while Chinese manufacturers compete on landed cost. Three-tier pricing structure across premium, standard, and economy levels reflects UL/CE certification grade differentials rather than raw performance specifications. Pricing pressure stems from steel and aluminum input volatility that mid-tier manufacturers cannot hedge effectively. Ghost kitchen operators in the United States exhibit highest price sensitivity due to square-meter constraints, while European hotel chains prioritize lifecycle service bundling over capital cost.
Supply Chain Analysis
Export-control regimes restricting high-efficiency motor technology to Chinese manufacturers are fragmenting fan-system sourcing, with European and North American producers retaining advanced blower engineering while Asian suppliers dominate resistance-element production. Supply concentrates in China for steel enclosures and heating elements, Germany for precision control systems, and Italy for dual-fuel burner assemblies. Raw material dependencies include nickel-alloy stainless steel, aluminum extrusions, and ceramic insulation compounds. Single-source vulnerability sits with high-temperature fan motors from concentrated European suppliers. Distribution runs through consolidated foodservice dealer networks in North America and authorized installer channels in European residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convection ovens market is recovering from pandemic-depressed hospitality capital expenditure cycles, with foodservice equipment replacement demand now accelerating as restaurant foot traffic normalizes across major economies.
For Market Incumbents: Entrench specification loyalty through predictive maintenance service bundling that locks ghost kitchen operators into multi-year uptime guarantees. Deepen backward integration into stainless steel enclosure fabrication to offset commodity volatility compressing mid-tier margins. Invest in UL/CE dual-certification engineering to collapse multi-certification timelines that currently delay product launches by 8-14 months.
For New Entrants and Emerging Players: Build out cloud-connected predictive maintenance platforms targeting the technician shortage concentrated in United States metropolitan areas, where incumbent service networks are thinnest. Target India's organized restaurant chains in Mumbai and Delhi with energy-efficient electric convection systems ahead of electrification mandate convergence. Pursue direct-to-operator digital distribution to bypass consolidated dealer networks that incumbent brands dominate.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among commercial foodservice providers bundling subscription-based maintenance packages, offering superior cash-flow quality versus transactional residential equipment sales. Long-term viability favors targets with established IoT connectivity platforms and certified technician networks rather than pure hardware manufacturers. Monitor United States IRA commercial electrification incentive renewal signals as inflection indicators for electric equipment adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | IoT sensor integration enables remote diagnostics and recurring service revenue streams for ghost kitchen operators. |
| Backward Integration into Steel Fabrication | Captive supply of stainless steel enclosures insulates margin predictability from commodity index volatility. |
| Dual-Certification Engineering Investment | Simultaneous UL and CE marking compliance collapses product launch cycles currently extended by sequential testing. |
| Direct-to-Operator Digital Distribution | Bypassing consolidated foodservice dealer networks captures margin currently absorbed by intermediary markups. |
| India Market Entry Partnership | BIS certification and FSSAI compliance through local joint venture accelerates access to modernizing restaurant chains. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial kitchen equipment procurement directors, ghost kitchen facility managers, hotel engineering executives, authorized service technician network heads, and residential appliance retail category buyers. Secondary validation drew from United States Department of Energy efficiency standard filings, EU Ecodesign Directive implementation reports, China SAMR GB standard publications, and customs trade data for stainless steel and aluminum inputs. Bottom-up equipment shipment data triangulated against top-down hospitality construction pipeline estimates.
Calibration against historical replacement cycles and regulatory mandate timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product installation type, application intensity, energy source configuration, and end-user procurement authority. CAGRs were derived from equipment replacement elasticity coefficients and electrification subsidy uptake curves. Forecast inputs incorporated ghost kitchen square-meter efficiency constraints and technician shortage severity indices by metropolitan area.
Stress conditions across steel price volatility bands, electrification subsidy renewal scenarios, and hospitality construction cancellation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate enforcement timelines and replacement cycle normalization. Material shifts in EU carbon border adjustment implementation or United States IRA incentive structure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global High Pressure Processing (HPP) Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Brewing Boiler Market
Food Processing Equipment
Electric Chicken Scalder Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market