
 Reach-In Refrigerators Market | 2026-2036
Reach-In Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Reach-In Refrigerators Market Analytics
Foodservice operator procurement is pivoting toward dual-temperature units that consolidate refrigerated and frozen storage in compact kitchen footprints. True Manufacturing Co., Inc. anchors its position through deep vertical integration in its Missouri manufacturing campus. Turbo Air Inc. competes aggressively on energy efficiency ratings and extended compressor warranties. Traulsen specializes in premium stainless-steel construction for institutional healthcare and education kitchens.
Reach-in refrigerators are self-contained commercial cooling cabinets designed for back-of-house food storage, typically constructed with galvanized or stainless-steel interiors, foamed-in-place polyurethane insulation, and forced-air evaporator systems maintaining temperatures between 32°F and 41°F for refrigerated goods. Their primary purpose is preserving food safety while enabling rapid inventory access in high-throughput commercial kitchens. Glass-door configurations command margin premiums by combining merchandising visibility with storage functionality in front-of-house deployments. Freestanding installation types dominate retrofit applications where built-in cabinetry constraints do not apply. Dual-temperature units represent the fastest-expanding temperature range segment as operators seek equipment consolidation.
The US Department of Energy and EPA Energy Star program shape product efficiency baselines and procurement eligibility for federal foodservice contracts. NSF International sanitation standards and UL safety certifications govern material specifications and electrical compliance for North American market access. Stakeholders must monitor evolving state-level refrigerant phase-down schedules and their impact on compressor technology roadmaps.
Market Dynamics
The US Department of Energy's updated commercial refrigeration efficiency standards are compressing design cycles and forcing compressor technology transitions across the supply base.
Growth Catalysts
- Variable-speed compressor adoption:DOE efficiency mandates are accelerating migration from fixed-speed to electronically commutated motor systems, cutting energy consumption by 15-30% in retrofit-ready units.
- Quick-service restaurant expansion:Chains are enlarging cold storage footprints to support fresh-ingredient menus, driving replacement demand for legacy single-temperature cabinets.
- Southeast Asia food retail modernization:Vietnam, Thailand, and Indonesia are witnessing concentrated supermarket and foodservice infrastructure investment, pulling imported commercial refrigeration equipment.
Market Restraints
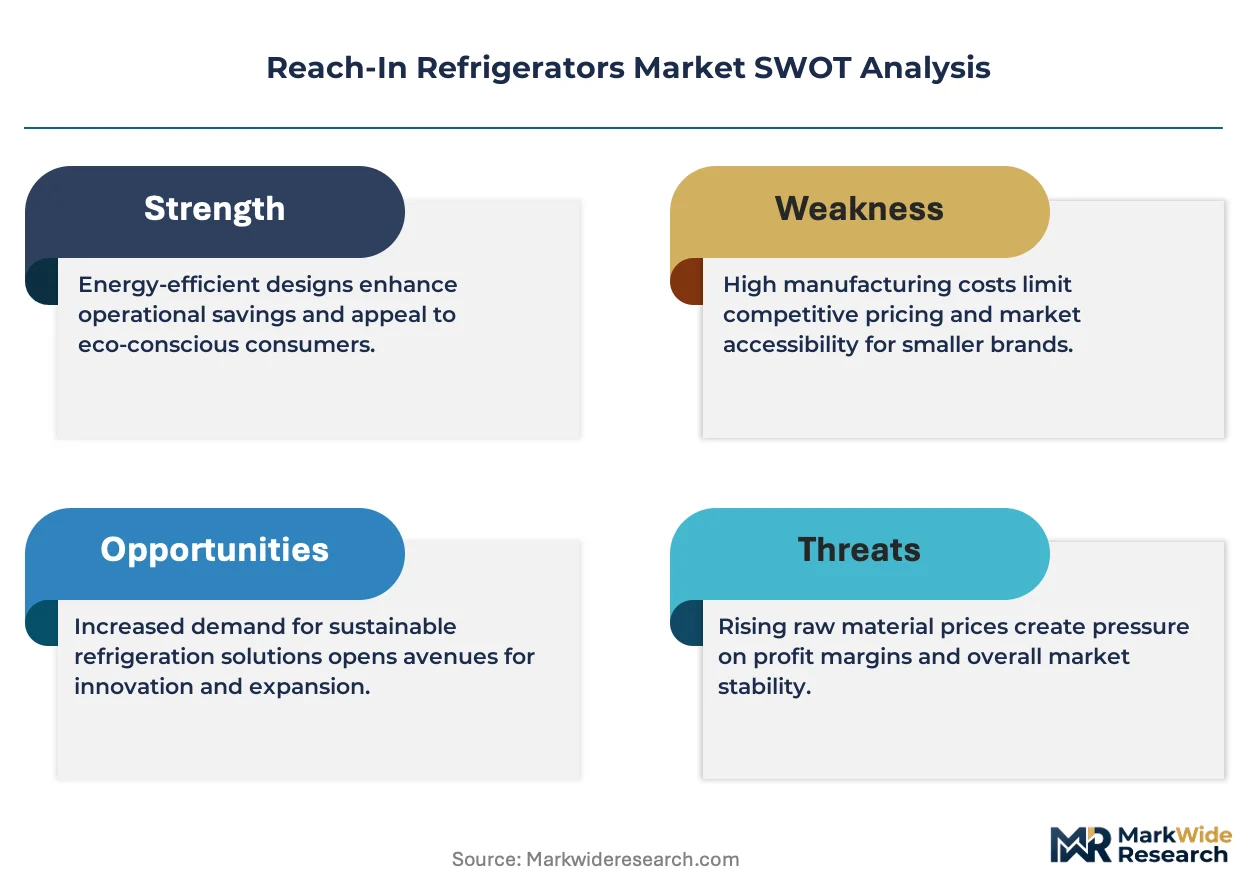
- Copper and steel input volatility:Foamed-in-place polyurethane insulation and stainless-steel enclosure costs fluctuate with commodity indexes, compressing margin predictability for manufacturers.
- Refrigerant phase-down schedules:State-level hydrofluorocarbon restrictions in California and New York are fragmenting compliance requirements ahead of federal alignment.
- Substitution by walk-in systems:Large-format foodservice operators are bypassing reach-in cabinets entirely for custom walk-in installations in new-build kitchens.
Strategic Opportunities
- Indonesia cold chain underpenetration:Traditional wet markets still dominate protein and produce distribution, creating whitespace for modern refrigeration infrastructure.
- Dual-temperature convergence:Combination refrigerated-frozen cabinets are capturing operator preference by consolidating two appliances into one footprint.
- Glass-door merchandising integration:Front-of-house visibility features are commanding price premiums in fast-casual and convenience store deployments.
Industry Challenges
- NSF/UL certification timelines:Sanitation and electrical safety approvals stretch 6-12 months, delaying product launches and freezing design iterations.
- Legacy system integration friction:New variable-speed units require controller compatibility with existing kitchen management systems, complicating retrofit sales.
- Refrigerant technician skill gaps:The transition to low-global-warming-potential alternatives demands retraining across the service technician workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reach-In Refrigerators Market |
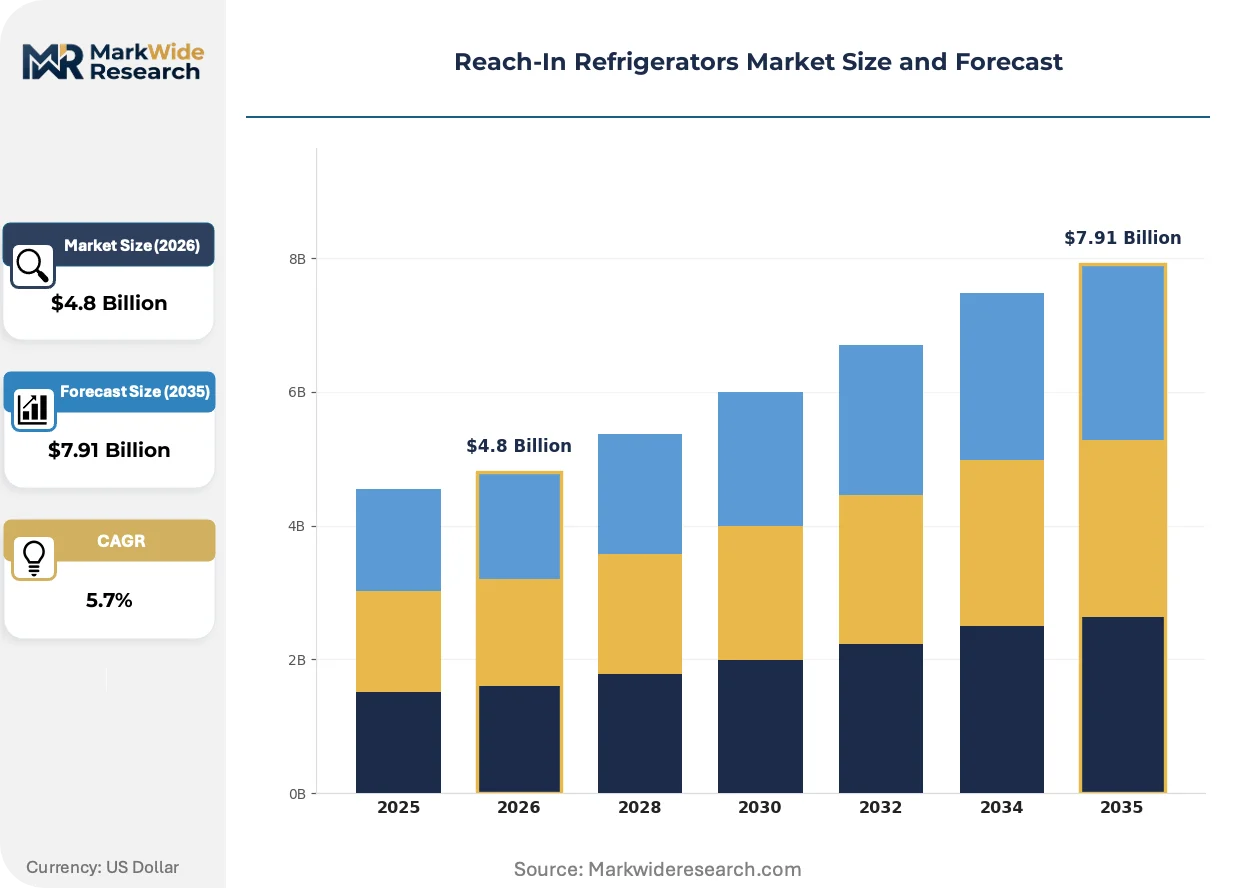
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Door, Double-Door, Triple-Door, Glass-Door End User: Restaurants, Supermarkets, Hotels, Convenience Stores Installation Type: Built-In, Freestanding, Countertop, Modular Temperature Range: Refrigerated, Freezer, Dual Temperature, Specialty |
| Companies Covered | True Manufacturing Co., Inc., Turbo Air Inc., Traulsen, Hoshizaki America, Inc., Delfield, Hussmann, Illinois Tool Works, Ali Group, AHT Cooling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reach-In Refrigerators Market Evolving Landscape
Equipment design is pivoting around energy compliance deadlines, with compressor architecture and insulation chemistry undergoing simultaneous overhaul.
Electronically commutated motor compressors are overtaking traditional fixed-speed reciprocating designs in mid-capacity reach-in units. Foodservice operators facing utility rebate eligibility requirements are specifying these systems for replacement purchases. The technology is overtaking legacy designs by enabling continuous modulation rather than on-off cycling, extending component life while satisfying DOE energy conservation standards.
The EPA Energy Star program and DOE test procedure updates are tightening allowable energy consumption metrics for commercial refrigerators. Manufacturers must redesign evaporator coil geometry and fan control logic to maintain certification eligibility. Glass-door configurations face disproportionate scrutiny due to display lighting loads, pushing suppliers toward LED retrofit kits and low-emissivity glazing.
Equipment-as-a-service models are penetrating the institutional buyer segment, unbundling capital expenditure from operational budgets. Universities and hospital systems are favoring multi-year service contracts with guaranteed uptime clauses over outright purchase. This shift concentrates most visibly in the Northeast and Mid-Atlantic states, where facility managers prioritize budget predictability over asset ownership.
Reach-In Refrigerators Market Segmentation
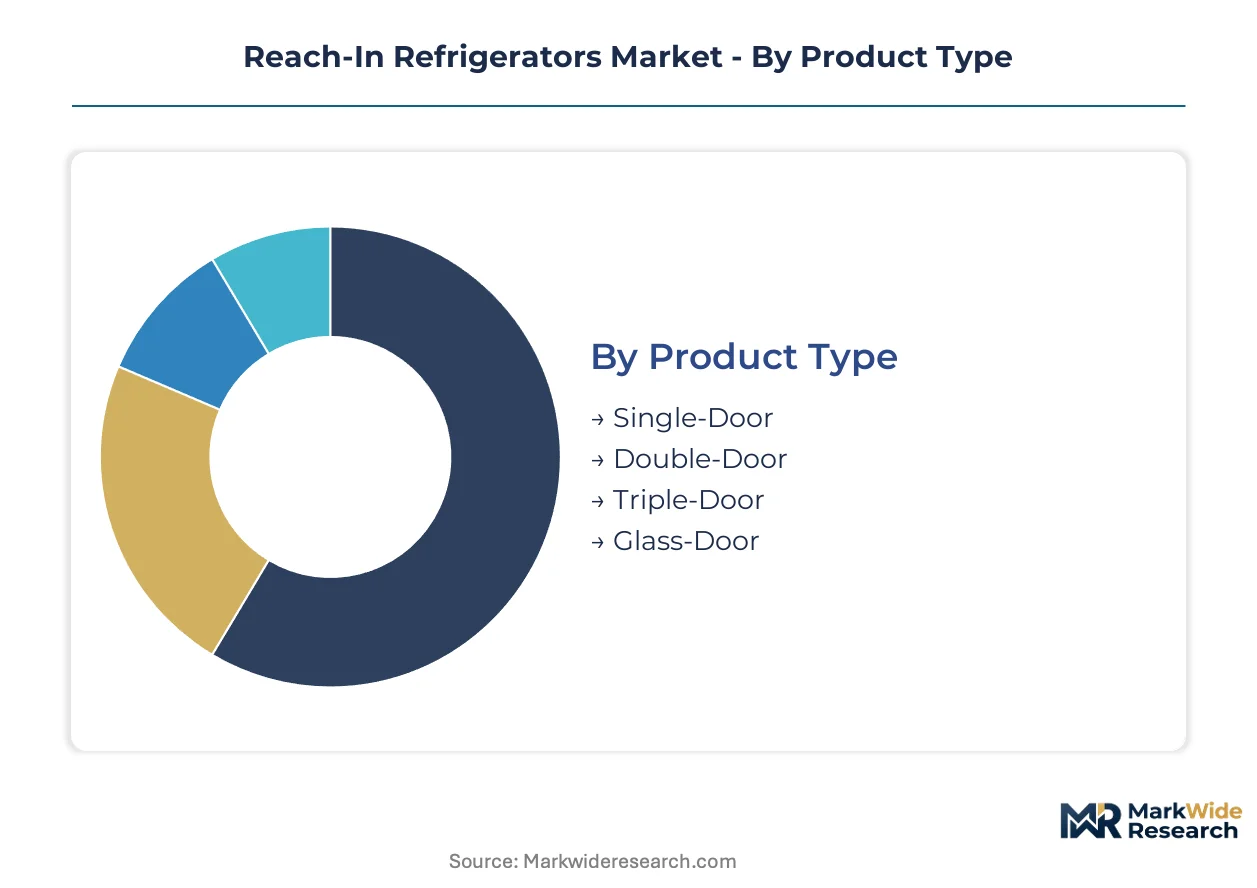
Reach-in refrigerator purchasing decisions cascade across multiple technical and operational dimensions. Equipment specification determines NSF/UL certification pathways, energy rebate eligibility, and kitchen workflow integration. The following categories capture how buyers navigate these trade-offs.
Product Type:
NSF International sanitation standards and DOE efficiency certifications apply uniformly across door configurations, though glass-door variants face additional thermal performance scrutiny under Energy Star test procedures.
- Single-Door:Compact footprint suits independent restaurants and food trucks with constrained back-of-house space. Demand concentrates in urban foodservice clusters across Vietnam and Indonesia where real estate premiums squeeze kitchen layouts. The configuration sacrifices capacity for maneuverability in tight prep lines.
- Glass-Door:Merchandising visibility drives front-of-house deployment in fast-casual chains and convenience stores. Operators in Thailand's expanding retail sector specify these for grab-and-go beverage displays. Low-emissivity glazing and LED lighting retrofits address disproportionate Energy Star scrutiny on display thermal loads.
- Double-Door:Balances capacity against floor space in mid-scale hotel kitchens.
- Triple-Door:High-volume institutional cafeterias prioritize raw storage capacity over spatial efficiency.
Leading the category by volume: Single-Door. Growing fastest: Glass-Door.
End User:
Procurement authority and specification complexity vary sharply across buyer types, with institutional purchasers subject to federal contract eligibility requirements and rebate program compliance.
- Restaurants:Quick-service chains dominate replacement demand as fresh-ingredient menu expansions enlarge cold storage footprints. Southeast Asian franchise operators in Vietnam and Indonesia are retiring legacy single-temperature cabinets for dual-temperature consolidation. Procurement prioritizes variable-speed compressor eligibility for utility rebate capture.
- Supermarkets:Food retail modernization across Thailand pulls imported commercial refrigeration for fresh produce and protein sections. Hypermarket operators specify modular configurations that scale with floor plan reconfigurations. California's hydrofluorocarbon restrictions complicate cross-border equipment sourcing for regional chains.
- Hotels:Full-service properties balance banquet prep capacity against space constraints in retrofit renovations.
- Convenience Stores:24-hour operations prioritize glass-door merchandising integration with rapid restock access.
Dominant buyer by unit volume: Restaurants. Expanding most quickly: Supermarkets.
Installation Type:
Retrofit versus new-build decisions determine specification flexibility, with freestanding units bypassing cabinetry constraints that complicate built-in deployments.
- Freestanding:Dominates replacement cycles where existing kitchen layouts resist modification. US foodservice operators facing DOE efficiency deadlines favor these for plug-and-play compliance upgrades. The configuration avoids structural integration costs and permits equipment relocation during renovation cycles.
- Built-In:Custom cabinetry integration commands premium positioning in upscale hotel and resort developments. Specification requires precise dimensional coordination with millwork contractors, extending project timelines. Demand concentrates in greenfield construction across Indonesia's hospitality expansion.
- Countertop:Prep-line adjacency drives adoption in compact urban restaurants.
- Modular:Scalable configurations attract supermarket operators with seasonal volume fluctuations.
Highest shipment volume: Freestanding. Steepest expansion trajectory: Built-In.
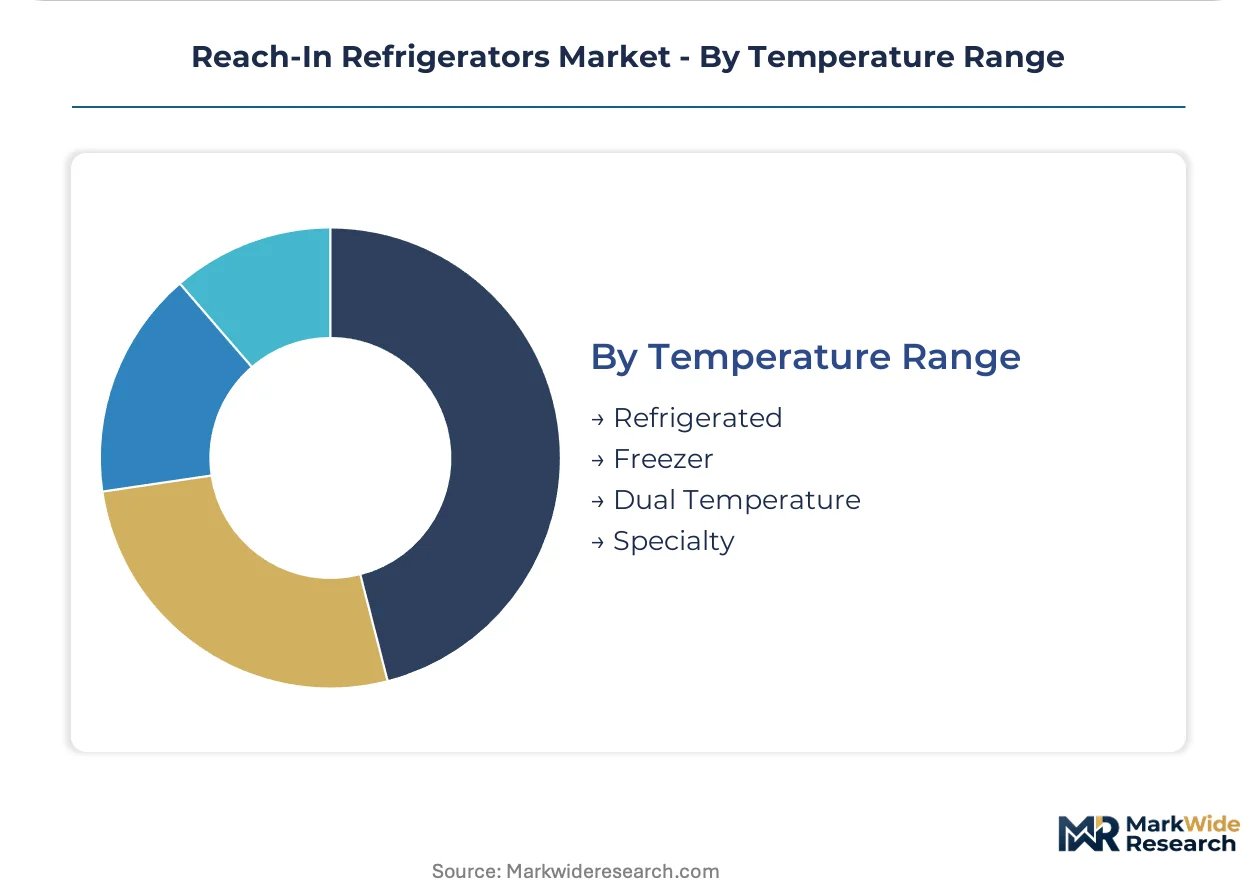
Temperature Range:
Regulatory compliance intensity varies by thermal specification, with dual-temperature units navigating both refrigerated and frozen storage standards simultaneously.
- Dual Temperature:Consolidation of refrigerated and frozen storage into single footprints captures operator preference across all end-use segments. Quick-service chains in the US specify these to compress kitchen equipment counts. The configuration satisfies fresh-protein and frozen-dessert storage within one NSF-certified cabinet.
- Refrigerated:Standard 32°F to 41°F operation remains baseline specification for produce and dairy storage. Demand concentrates in Southeast Asian wet market modernization where cold chain infrastructure replaces ambient distribution. EPA Energy Star compliance is mandatory for federal contract eligibility.
- Freezer:Sub-zero operation requires more intensive insulation and compressor capacity.
- Specialty:Precision temperature control serves wine storage and medical applications with narrow thermal tolerances.
Category volume leader: Refrigerated. Gaining share fastest: Dual Temperature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in the United States and China, while consumption accelerates across Southeast Asian food retail modernization and European energy efficiency retrofits.
United States
Quick-service restaurant chains drive replacement demand as fresh-ingredient menu expansions enlarge cold storage footprints. The Department of Energy's updated commercial refrigeration efficiency standards compress design cycles and mandate variable-speed compressor migration. Missouri hosts concentrated manufacturing operations where deep vertical integration supports domestic supply.
China
Food retail infrastructure investment pulls commercial refrigeration equipment for supermarket and convenience store expansions. MIIT efficiency directives and GB standards govern compressor technology transitions and refrigerant specifications. Yangtze River Delta manufacturing clusters produce components for domestic installation and regional export.
Vietnam
Urban foodservice clusters squeeze kitchen layouts, favoring compact single-door configurations for independent restaurants and food trucks. The country's national standards body implements commercial equipment safety certifications aligned with regional harmonization. Ho Chi Minh City and Hanoi concentrate hospitality construction pulling imported reach-in units.
Thailand
Hypermarket operators specify modular refrigeration configurations that scale with floor plan reconfigurations. The country's energy efficiency program tightens allowable consumption metrics for commercial cooling equipment. Bangkok retail corridors deploy glass-door units for grab-and-go beverage merchandising visibility.
Indonesia
Traditional wet markets dominate protein and produce distribution, creating whitespace for modern refrigeration infrastructure. The national industrial ministry promotes cold chain development through facility investment incentives. Java's hospitality expansion in Jakarta and Bali pulls built-in cabinetry-integrated units for upscale resort developments.
Reach-In Refrigerators Market Competitive Landscape
Top-tier vendors anchor premium stainless-steel construction and deep manufacturing integration, while mid-tier competitors compete on energy efficiency ratings and extended warranty terms. The market structure reflects consolidation around established fabrication expertise alongside specialist positioning in institutional healthcare and education segments. Strategic archetypes include vertically integrated domestic manufacturers, efficiency-focused technology licensors, and premium-material specialists. Competitive moves concentrate on compressor technology transitions and Southeast Asian distribution partnerships.
Among US-based fabricators, True Manufacturing Co., Inc. and Turbo Air Inc. occupy positions reflecting divergent strategic emphases—one through captive manufacturing infrastructure, the other through aggressive energy efficiency positioning. Traulsen exemplifies the premium-material specialist archetype. These three named entities anchor the competitive landscape without exhaustively representing market participants.
| Leading Market Players |
|---|
| True Manufacturing Co., Inc. |
| Turbo Air Inc. |
| Traulsen |
| Hoshizaki America, Inc. |
| Delfield |
| Hussmann |
| Illinois Tool Works |
| Ali Group |
| AHT Cooling Systems |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant chains dominate procurement volumes and enforce per-unit transactional pricing with volume-tiered rebates. Their specification power compresses margin structures upstream, forcing fabricators to absorb commodity swings or lose shelf placement.
Pricing Analysis
Margin tightening in mid-tier stainless-steel enclosures reflects copper and steel index volatility. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified institutional units from basic restaurant-grade cabinets and import alternatives. Cost-down pressure on economy imports accelerates because Southeast Asian buyers prioritize first-cost over lifecycle efficiency. Independent restaurants exhibit highest price sensitivity; hospital systems with capital-equipment budgets show lowest.
Supply Chain Analysis
Workforce availability in Missouri manufacturing clusters and Yangtze River Delta fabrication zones determines output elasticity. Production concentrates in the United States, China, and Vietnam. Component sourcing draws from foamed-in-place polyurethane insulation suppliers, compressor motor foundries, and low-emissivity glass processors. Single-source vulnerability in electronically commutated motor controllers threatens variable-speed unit ramps. Distribution runs through foodservice equipment dealers and direct OEM sales forces to institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable-speed compressor technology is displacing fixed-speed reciprocating designs, compressing design cycles and recertification timelines. Stakeholders must position around this transition phase.
For Market Incumbents: Hedge legacy fixed-speed inventory exposure by accelerating electronically commutated motor platform migration before DOE enforcement deadlines. Capture backward integration into compressor controller supply to defend margin position against component cost volatility. Prioritize NSF recertification investment for dual-temperature configurations to maintain federal contract eligibility. For New Entrants and Emerging Players: Foodservice equipment dealers represent the most accessible channel anchor for market penetration. Indonesia's wet market modernization offers whitespace with lower incumbent saturation than Vietnam or Thailand. Pursue glass-door merchandising integration as the differentiated entry angle for fast-casual and convenience store segments. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fabricators with captive Missouri or Yangtze River Delta production. Long-term viability hinges on refrigerant transition readiness and Southeast Asian distribution partnerships. Watch California hydrofluorocarbon restriction enforcement as the inflection signal for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Compressor Platform Migration | DOE efficiency mandates force technology transition across all capacity tiers. |
| Dual-Temperature Product Line Expansion | Quick-service chains consolidate equipment counts, pulling combination cabinet demand. |
| Southeast Asian Distribution Partnership | Vietnam, Thailand, and Indonesia food retail modernization pulls imported refrigeration. |
| NSF/UL Recertification Acceleration | Six-to-twelve month approval timelines delay product launches without parallel filing. |
| Equipment-as-a-Service Model Launch | Northeast universities and hospital systems favor uptime-guaranteed contracts over purchase. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with foodservice procurement directors, commercial kitchen designers, refrigeration service technicians, and OEM product managers combined with secondary validation. Foodservice Equipment Manufacturers Association reports, DOE efficiency standard dockets, EPA Energy Star certification databases, and import-export customs documentation provided quantitative anchors. Bottom-up equipment shipment analysis and top-down foodservice construction spending triangulation verified market sizing.
Reconciling production data from Missouri and Yangtze River Delta manufacturing clusters with end-use demand signals across quick-service chains, hospital systems, and supermarket operators generated volume and value outputs. Segmentation modeling captured door configuration, temperature range, installation type, and end-use vertical dimensions across the projection horizon. CAGRs derived from equipment replacement cycle analysis and regulatory deadline impact assessment. Compressor technology transition curves and refrigerant phase-down schedules served as industry-specific forecast inputs.
Caveats apply where copper and steel commodity volatility, state-level hydrofluorocarbon restriction fragmentation, or walk-in system substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about DOE enforcement timing and Southeast Asian infrastructure investment continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Specialty Commercial Deep Fryers Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Commercial Cookers Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market