
 North America Countertop Ice Makers Market | 2026-2036
North America Countertop Ice Makers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Countertop Ice Makers Market Insights
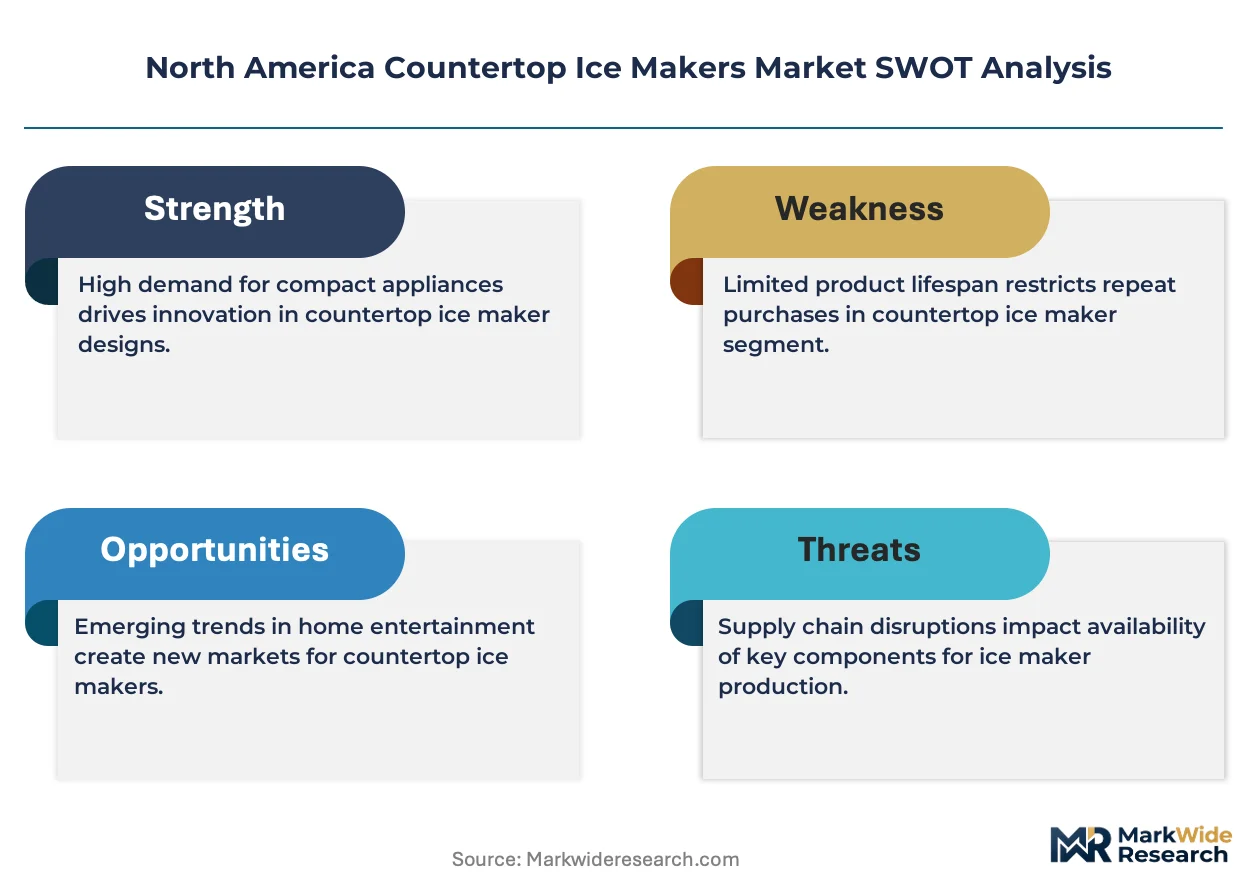
The U.S. Department of Energy appliance efficiency standards is realigning procurement criteria for residential and light-commercial refrigeration equipment. Scotsman Ice Systems leverages its scale in nugget-ice technology to sustain premium positioning across hospitality channels. NewAir competes aggressively on direct-to-consumer pricing, while Hoshizaki Corporation anchors its North American presence through specialized distribution to healthcare and foodservice accounts.
Countertop ice makers are self-contained, electrically powered appliances designed to produce ice within compact footprints typically under 16 inches in height, utilizing compressor-driven refrigeration cycles with integrated water reservoirs or plumbed connections. These units serve residential kitchens, recreational vehicles, and small commercial settings where full-size ice machines prove impractical. Portable and nugget-ice configurations command disproportionate attention from buyers seeking flexibility and chewable ice textures, while built-in and undercounter formats occupy established positions in outdoor kitchen and bar installations. The 25–50 lbs/day capacity tier dominates household volumes, whereas 100–150 lbs/day units capture margin pools in boutique hospitality and urgent-care healthcare settings.
The DOE maintains jurisdiction over minimum efficiency requirements, while the EPA ENERGY STAR program shapes voluntary premium positioning through certified performance thresholds. Health Canada and PMRA coordinate cross-border standards that affect import compliance for manufacturers serving Canadian provinces. Stakeholders must monitor evolving federal efficiency rulemakings and provincial refrigerant phase-down schedules to anticipate product redesign cycles and certification investments.
Market Dynamics
The U.S. Department of Energy appliance efficiency standards are compressing manufacturer design cycles and forcing rapid retooling of compressor architectures across the North American countertop ice maker supply base.
Growth Catalysts
- Outdoor Kitchen Expansion:Residential outdoor kitchen installations in Texas and Florida are generating concentrated demand for compact ice production equipment with weather-resistant housings and plumbed connectivity options.
- EPA ENERGY STAR Certification:Voluntary premium positioning through certified performance thresholds is creating tiered product differentiation that rewards efficiency investments with retail placement advantages.
- Nugget-Ice Texture Preference:Hospitality and healthcare settings are standardizing on chewable ice formats for patient comfort and beverage presentation, pulling specialized compressor technologies into mid-market price bands.
Market Restraints
- Refrigerant Phase-Down Schedules:Provincial refrigerant regulations in Canada and evolving EPA mandates are forcing premature obsolescence of existing compressor inventories and accelerating R&D spend.
- Copper and Aluminum Input Volatility:Heat exchanger materials face commodity price swings that compress margin pools for manufacturers without captive metal sourcing or long-term supply agreements.
- Water Quality Variability:Hard water conditions across the southwestern United States accelerate scale buildup and shorten product lifecycles, creating warranty cost concentration.
Strategic Opportunities
- RV and Marine Channels:Recreational vehicle manufacturers in Indiana and marine outfitters along the Gulf Coast represent underpenetrated demand for 12V and battery-compatible portable units.
- Healthcare Urgent-Care Expansion:Boutique healthcare settings in suburban corridors require 100–150 lbs/day capacity tiers with antimicrobial touch surfaces and quiet operation profiles.
- Smart Home Integration:Wi-Fi-enabled ice level monitoring and filter replacement alerts are converging with broader kitchen appliance connectivity standards to create subscription service attach rates.
Industry Challenges
- Refrigeration Technician Shortage:Compressor-driven repair expertise is concentrating in legacy appliance service networks, leaving direct-to-consumer brands dependent on mail-in warranty programs with extended resolution timelines.
- Cross-Border Certification Complexity:Health Canada and PMRA coordination requirements add 4–6 month pre-market approval delays for manufacturers seeking unified North American product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Countertop Ice Makers Market |
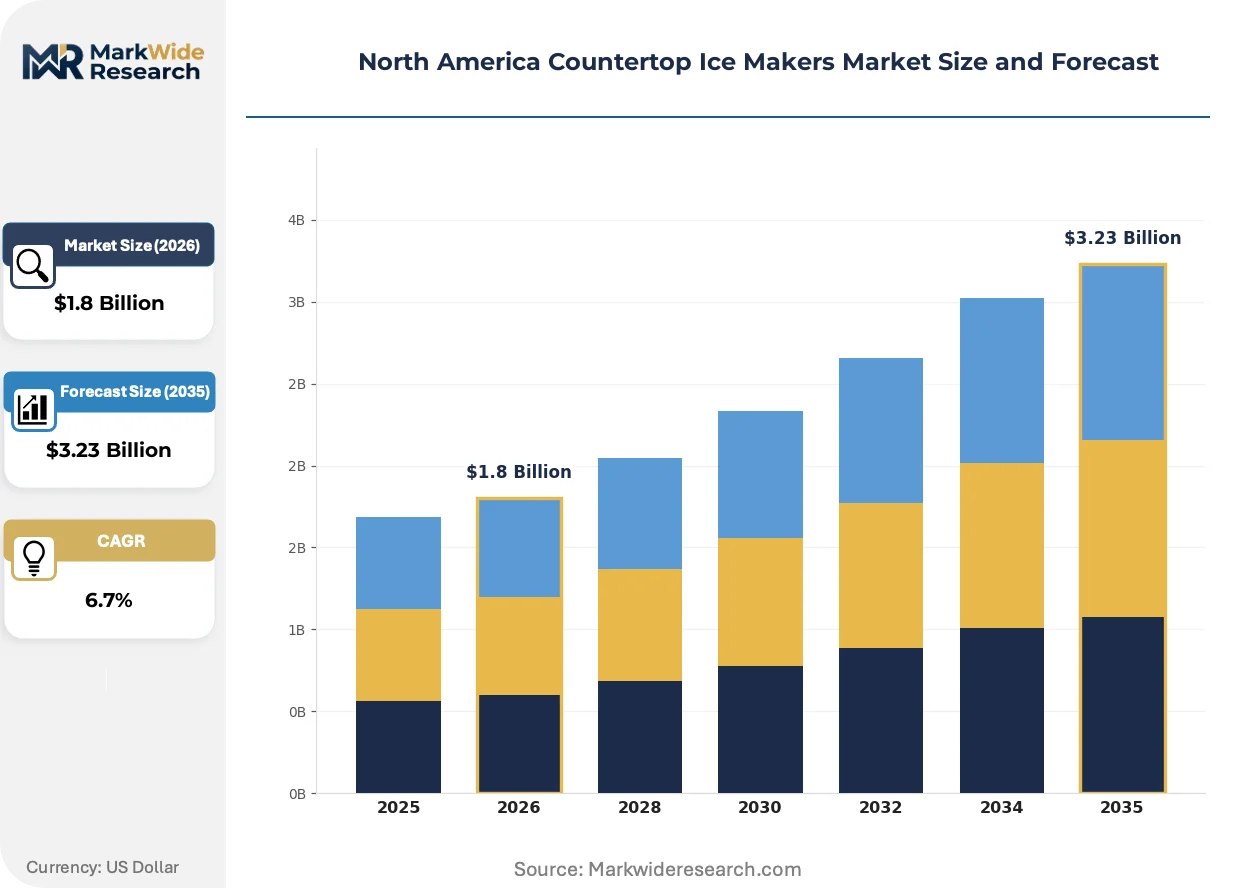
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-in, Undercounter, Modular End User: Household, Commercial, Hospitality, Healthcare Ice Production Capacity: 25 lbs/day, 50 lbs/day, 100 lbs/day, 150 lbs/day Ice Shape: Cubed, Nugget, Flake, Crushed |
| Companies Covered | Scotsman Ice Systems, NewAir, Whynter, MC Appliance, GE Appliances, Magic Chef, Frigidaire, Hoshizaki Corporation, Aterian Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Countertop Ice Makers Market Trends and Innovations
Active redesign of compressor architectures and control systems is compressing product development timelines while opening new application contexts for countertop ice production equipment.
Brushless DC compressor technology is expanding into residential and light-commercial countertop ice makers, replacing traditional AC motor designs with variable-speed refrigeration cycles that modulate ice production to ambient conditions. Boutique hospitality operators in Florida and Texas are specifying these units for outdoor bar installations where thermal load fluctuates seasonally. The technology is expanding into price tiers previously occupied by fixed-speed alternatives, forcing incumbent manufacturers to accelerate cost-down programs or cede premium positioning.
The EPA ENERGY STAR program is tightening certified performance thresholds for compact refrigeration equipment, eliminating marginal performers from retail channel access and consolidating shelf space among redesigned 2024–2025 product families. Big-box retailers are conditioning purchase orders on demonstrated compliance, shifting procurement criteria upstream in manufacturer planning cycles. The southern United States residential replacement market is responding fastest, with efficiency-driven purchase intent correlating to higher electricity rate environments.
Direct-to-consumer brands are unbundling after-sales service from product purchase, replacing traditional dealer networks with video-guided self-service repair modules and mail-in component exchange programs. This model is displacing legacy appliance service infrastructure for sub-$500 price point units, concentrating margin capture in brand-operated digital channels. The shift is most visible in online-first purchasing patterns among millennial and Gen Z household formations in metropolitan Texas corridors.
North America Countertop Ice Makers Market Segmentation
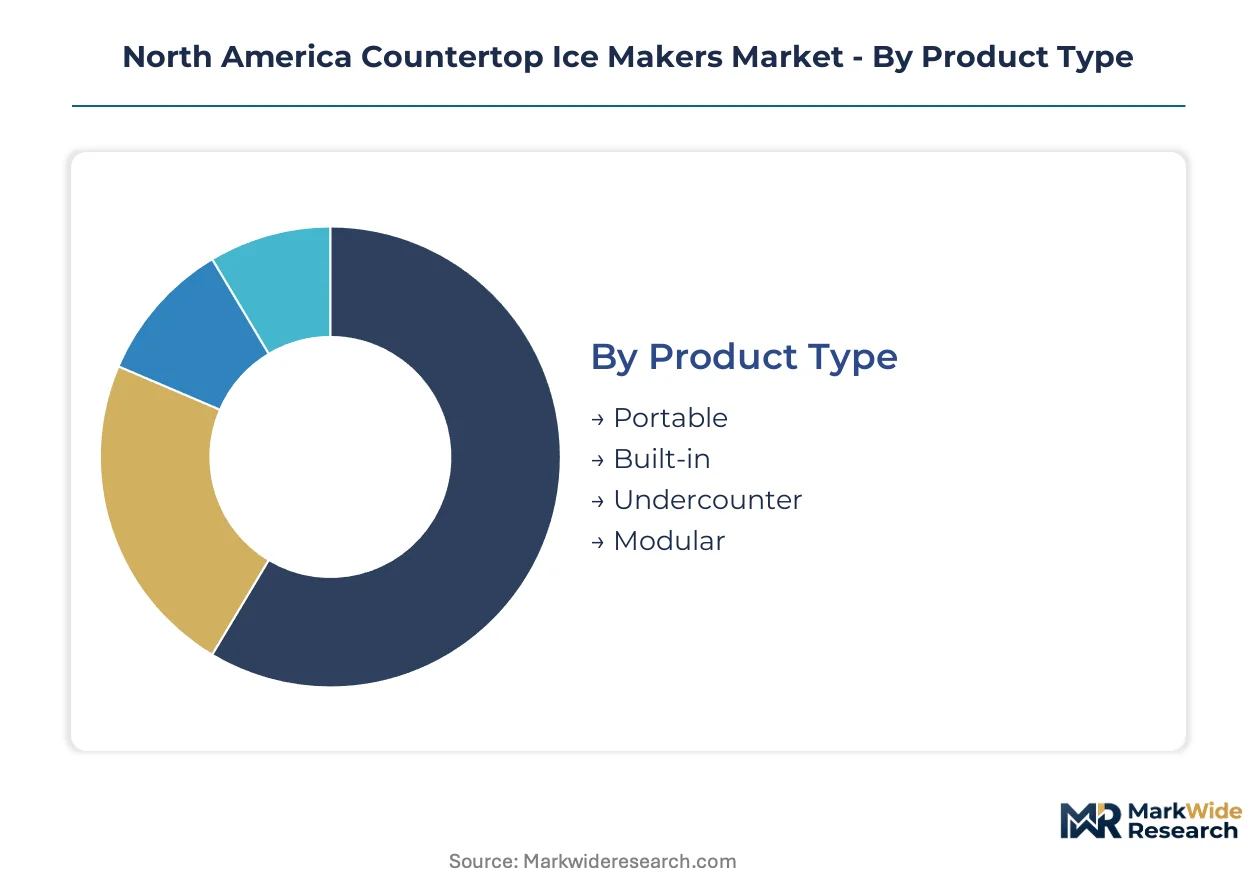
Countertop ice maker purchasing decisions split across installation constraints, daily volume requirements, and ice texture specifications. Manufacturers configure compressor architectures and control systems differently for each axis, creating distinct margin pools and certification pathways.
Product Type:
Compressor architecture and plumbing connectivity define the four installation formats.
- Portable:Self-contained units with integrated water reservoirs and 120V AC or 12V DC power options. Demand concentrates in Texas and Florida recreational vehicle channels where outdoor mobility requirements dominate purchasing criteria.
- Built-in:Flush-mount designs with front ventilation and cabinet-ready panel integration. Residential outdoor kitchen installations in Houston and Miami suburbs are standardizing on these formats for aesthetic cohesion with grilling equipment.
- Undercounter:Freestanding units with finished sides and reversible door hinges. Boutique hospitality operators in Austin and Orlando specify these for bar installations where space constraints preclude full-size equipment.
- Modular:Separate ice head and bin configurations allowing capacity expansion. Healthcare urgent-care clinics in suburban Dallas corridors deploy these for scalable ice production during seasonal patient volume spikes.
Mature deployment sits with Built-in formats. Newer deployment is concentrated in Portable configurations.
End User:
Volume thresholds and regulatory exposure shape procurement patterns across four buyer categories.
- Household:Residential purchasers prioritizing 25–50 lbs/day capacities with nugget-ice options. Texas and Florida electricity rate environments are pulling efficiency-certified units into this segment fastest.
- Commercial:Small foodservice operators with 100+ lbs/day requirements and NSF certification mandates. Independent coffee chains in California and New York metro areas represent concentrated demand.
- Hospitality:Boutique hotels and event venues standardizing on chewable ice textures for beverage presentation. Florida beachfront properties are specifying weather-resistant housings with antimicrobial touch surfaces.
- Healthcare:Urgent-care and dental clinics requiring quiet operation profiles and patient-safe ice formats. Suburban Phoenix and Atlanta corridors show fastest clinic expansion rates.
Procurement maturity centers on Commercial accounts. Healthcare represents the steepest expansion trajectory.
Ice Production Capacity:
Daily output tiers align with compressor sizing and thermal load engineering.
- 25 lbs/day:Single-serve residential units with thermoelectric or small compressor systems. Apartment dwellers in metropolitan Texas corridors favor these for countertop footprints under 14 inches.
- 50 lbs/day:Mid-tier residential and light-commercial workhorses with enhanced insulation. Florida vacation rental operators specify these for guest turnover efficiency.
- 100 lbs/day:Brushless DC compressor systems with variable-speed modulation. Boutique hospitality in Austin and Nashville bars deploy these for production flexibility.
- 150 lbs/day:Heavy-duty reciprocating compressors with continuous-duty cycles. Healthcare clinics in suburban Houston and Miami require these for peak demand coverage.
Volume concentration rests with 50 lbs/day tiers. 100 lbs/day configurations are climbing the fastest.
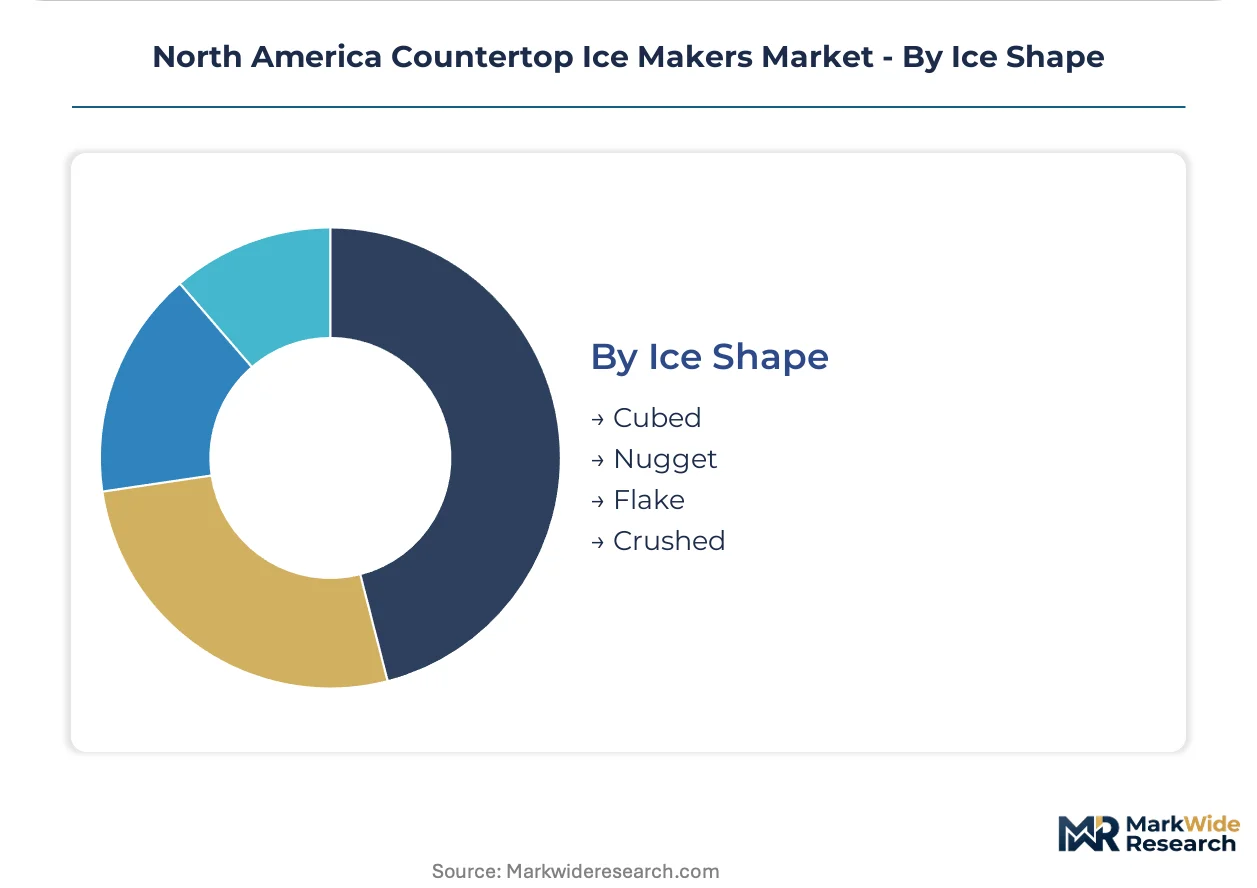
Ice Shape:
Freezing method and evaporator design determine ice crystal structure and end-use suitability.
- Cubed:Traditional full-cube and half-cube formats from vertical evaporator plates. General foodservice accounts in California and Illinois maintain baseline demand for cocktail and cooling applications.
- Nugget:Compressed flake ice with 80% ice-to-water ratio and chewable texture. Healthcare and hospitality settings across Texas and Florida are standardizing on this format for patient comfort and beverage differentiation.
- Flake:Thin, moldable ice for seafood displays and therapeutic applications. Coastal seafood markets in Seattle and Boston specify these for product preservation.
- Crushed:Fragmented cube or nugget ice for blended beverages and rapid cooling. Quick-service beverage chains in the Southwest favor these for frozen drink programs.
Established preference centers on Cubed formats. Nugget configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American countertop ice maker demand through its sprawling suburban outdoor kitchen corridor, where residential installations and hospitality procurement concentrate in a single metropolitan footprint.
United States
Texas and Florida generate outsized demand through residential outdoor kitchen expansion and hospitality retrofit cycles. The EPA ENERGY STAR program tightens certified performance thresholds for compact refrigeration equipment, eliminating marginal performers from retail channel access. Dallas-Fort Worth urgent-care clinics deploy 100–150 lbs/day modular configurations for scalable ice production during seasonal patient volume spikes.
Canada
Cross-border appliance import flows concentrate in Ontario and Quebec provinces where Health Canada and PMRA coordinate certification requirements. Provincial refrigerant phase-down schedules under federal environmental mandates force premature obsolescence of existing compressor inventories. Toronto-area hospitality distributors stock weather-resistant portable units for seasonal cottage and recreational property markets.
Mexico
Nuevo León and Jalisco manufacturing clusters supply component assemblies and finished goods for re-export to US distribution channels. Mexican federal energy efficiency standards align with US DOE appliance regulations to maintain cross-border market access. Monterrey-based fabricators produce heat exchanger subassemblies for integration into US-branded finished products.
North America Countertop Ice Makers Market Competitive Landscape
The competitive structure tilts toward specialized refrigeration equipment manufacturers with established distribution infrastructure. Consolidation pressures concentrate shelf space among redesigned 2024–2025 product families that satisfy tightening efficiency thresholds. Three archetypes dominate: legacy commercial refrigeration specialists with hospitality channel depth, direct-to-consumer brands with digital-first distribution, and diversified appliance conglomerates with mass retail placement. Strategic moves center on compressor architecture redesign cycles and cross-border certification investments to unify North American product launches.
Among established refrigeration specialists, Scotsman Ice Systems and Hoshizaki Corporation exemplify the premium-tier archetype through nugget-ice technology specialization and healthcare channel anchoring. NewAir occupies a position within the direct-to-consumer tier where aggressive pricing and video-guided self-service repair models displace legacy appliance service infrastructure. GE Appliances represents diversified conglomerate positioning with mass retail access and integrated smart home connectivity development.
| Leading Market Players |
|---|
| Scotsman Ice Systems |
| NewAir |
| Whynter |
| MC Appliance |
| GE Appliances |
| Magic Chef |
| Frigidaire |
| Hoshizaki Corporation |
| Aterian Inc |
| Others |
Pricing and Supply Chain Analysis
EPA ENERGY STAR certification requirements are compressing procurement criteria for big-box retail placement, forcing manufacturers to absorb compressor redesign costs or surrender shelf space to compliant rivals. This specification-driven buyer consolidation is reshaping margin allocation across the supply base.
Pricing Analysis
Throughput-based pricing anchors the countertop ice maker market, with daily production capacity tiers commanding distinct value pools. Premium-mid-economy pricing differentiation separates brushless DC compressor systems from fixed-speed alternatives, with certification grade and after-sales service bundling as secondary drivers. Cost compression in the sub-$500 direct-to-consumer tier is intensifying because mail-in warranty models displace dealer service networks. Household purchasers in electricity-rate-sensitive markets exhibit highest price sensitivity, while healthcare procurement committees prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Freight cost escalation from Nuevo León and Jalisco manufacturing clusters to US distribution centers is compressing landed margins for component assemblies. Heat exchanger subassemblies draw from Monterrey fabricators while compressor motors source from established Asian supply bases, creating tariff exposure at multiple nodes. Copper and aluminum input volatility represents the dominant structural risk, with commodity price swings transmitting directly to manufacturer cost structures. Distribution runs through big-box retail channels conditioned on ENERGY STAR compliance, with direct-to-consumer digital channels capturing growing share in metropolitan Texas corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America countertop ice maker market reads as a cost-of-compliance story where EPA ENERGY STAR thresholds erect barrier-to-entry moats that reward pre-certified incumbents with retail channel access.
For Market Incumbents: Anchor nugget-ice technology specialization against brushless DC compressor commoditization by accelerating R&D cycles ahead of refrigerant phase-down mandates. Defend hospitality channel positioning through captive distribution agreements that lock out direct-to-consumer entrants. Compressor architecture redesign investment represents the critical lever for sustaining premium tier access. For New Entrants and Emerging Players: Direct-to-consumer video-guided repair modules offer the lowest-friction route around legacy service infrastructure concentration. Target RV and marine channels in Indiana and Gulf Coast corridors where 12V compatibility requirements filter out established residential-focused rivals. White-label supply from Nuevo León fabricators enables rapid product launch without captive manufacturing investment. For Investors and Strategic Acquirers: The window for entry favors diversified appliance conglomerates with existing ENERGY STAR certification infrastructure and mass retail relationships. Long-term viability centers on manufacturers with backward integration into compressor sourcing or exclusive distribution partnerships with healthcare GPOs. Watch refrigerant regulation acceleration in Canada as the signal for forced product obsolescence cycles and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Architecture Redesign | EPA ENERGY STAR compliance secures big-box retail shelf space and eliminates marginal competitors. |
| Backward Integration into Heat Exchanger Production | Captive sourcing of copper-aluminum subassemblies insulates margin pools from commodity volatility. |
| Direct-to-Consumer Digital Channel Expansion | Video-guided self-service repair models displace legacy appliance service infrastructure in sub-$500 tier. |
| Healthcare GPO Partnership Development | Antimicrobial surface certification and quiet operation profiles unlock urgent-care clinic procurement. |
| Cross-Border Certification Unification | Health Canada and PMRA coordination reduces 4-6 month pre-market approval delays for unified launches. |
Research Methodology
Multi-period observation of ENERGY STAR certification adoption rates, refrigerant regulation trajectories, and outdoor kitchen installation permits anchored the trend analysis, supplemented by interviews with appliance manufacturing executives, HVAC distribution channel managers, big-box retail category buyers, and healthcare facilities procurement directors. Secondary validation drew from EPA rulemaking dockets, DOE appliance standards documentation, Health Canada import compliance records, and customs trade flow data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Input-output matrix modeling connected compressor cost structures, certification investment requirements, and channel margin allocations to derive volume and value trajectories over the projection horizon. Segmentation dimensions included installation format, end-use category, daily production capacity tier, and ice crystal structure. CAGRs were computed from modeled annual growth rates applied across discrete forecast intervals. Industry-specific inputs incorporated provincial refrigerant phase-down schedules and regional electricity rate environments.
The model holds under stable regulatory enforcement and commodity price bands; deviation in tariff escalation or refrigerant availability would shift manufacturer cost structures and retail pricing power. Forecasts reflect documented assumptions regarding efficiency standard adoption curves and distribution channel evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Retail Cooler Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Kegerator Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Commercial Catering Equipment Market