
 Pizza Oven Market | 2026-2036
Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Oven Market Intelligence
Refractory ceramic fiber insulation is rebalancing thermal mass economics across pizza oven product lines, reducing preheat times and fuel consumption for commercial operators. Marra Forni leverages its Italian manufacturing heritage to anchor premium wood-fired equipment positioning in North American foodservice channels. Middleby Corporation sustains broad category coverage through its portfolio breadth across conveyor and gas-fired systems for high-volume restaurant chains. Ooni Pizza Ovens competes aggressively in the portable segment with compact gas and wood-fired designs targeting residential users and outdoor kitchens.
A pizza oven is a thermally insulated chamber engineered to sustain temperatures between 700°F and 900°F, utilizing refractory materials, steel, or ceramic composites to achieve rapid heat transfer for baking flatbread products. Its primary commercial purpose centers on delivering consistent crust texture and topping caramelization in foodservice environments where throughput and repeatability determine operational viability. Gas-fired installations dominate restaurant deployments due to operational simplicity and code compliance, while wood-fired systems command premium positioning in artisan pizzerias where flavor differentiation justifies higher capital and labor costs. Portable configurations represent the fastest-growing installation type, fueled by residential outdoor kitchen expansion and food truck mobility requirements.
Commercial kitchen operators in the United States navigate NSF International sanitation standards and local fire department ventilation mandates that dictate hood and flue specifications for wood-burning installations. European manufacturers comply with CE marking requirements and EU Ecodesign regulations governing appliance energy efficiency and emissions profiles. Stakeholders must monitor evolving municipal bans on solid-fuel combustion in dense urban cores, as these ordinances directly threaten wood-fired oven deployment strategies and redirect capital toward gas or electric alternatives.
Market Dynamics
Refractory ceramic fiber insulation is compressing thermal mass requirements across commercial pizza oven architectures, forcing manufacturers to redesign heat retention systems while food truck operators accelerate fleet standardization around portable configurations.
Growth Catalysts
- EU Ecodesign Regulation:Energy efficiency mandates are accelerating replacement cycles in European commercial kitchens, pulling demand toward gas-fired systems with certified combustion performance.
- Food truck mobility:Mobile dining formats are standardizing on compact, rapid-deployment oven configurations that prioritize footprint reduction and multi-fuel compatibility.
- Refractory ceramic fiber:Advanced insulation materials are reducing preheat times by half compared to traditional brick linings, lowering operational costs for high-volume pizzerias.
Market Restraints
- Refractory material supply:Concentrated sourcing of high-grade alumina-silicate ceramics from Italian and Chinese suppliers creates input cost volatility for insulation-dependent oven lines.
- Municipal solid-fuel bans:Urban ordinances restricting wood combustion in dense cores of New York, London, and Milan are structurally capping addressable market for traditional wood-fired installations.
- Electric resistance heating:Grid-dependent alternatives threaten gas-fired positioning where electrification mandates advance, particularly in California and EU member states with decarbonization timelines.
Strategic Opportunities
- India foodservice expansion:Underpenetrated organized pizza chain infrastructure presents white space for conveyor and deck oven deployment as quick-service formats proliferate in tier-2 cities.
- US Inflation Reduction Act:Commercial kitchen equipment efficiency incentives are creating subsidy pathways for electric and high-efficiency gas oven upgrades in independent restaurants.
- Outdoor residential kitchens:Backyard cooking installation growth is pulling compact, dual-fuel portable designs into home improvement retail channels previously dominated by built-in appliances.
Industry Challenges
- Refractory installation certification:Specialized masonry and insulation skills required for traditional wood-fired oven construction face shrinking labor pools, extending project timelines.
- NSF/ANSI 4 compliance:Sanitation certification for commercial hot food holding equipment demands costly redesign cycles for manufacturers targeting US foodservice.
- Legacy ventilation integration:Hood and flue reconfiguration costs for existing kitchens often exceed equipment purchase price, stalling replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Oven Market |
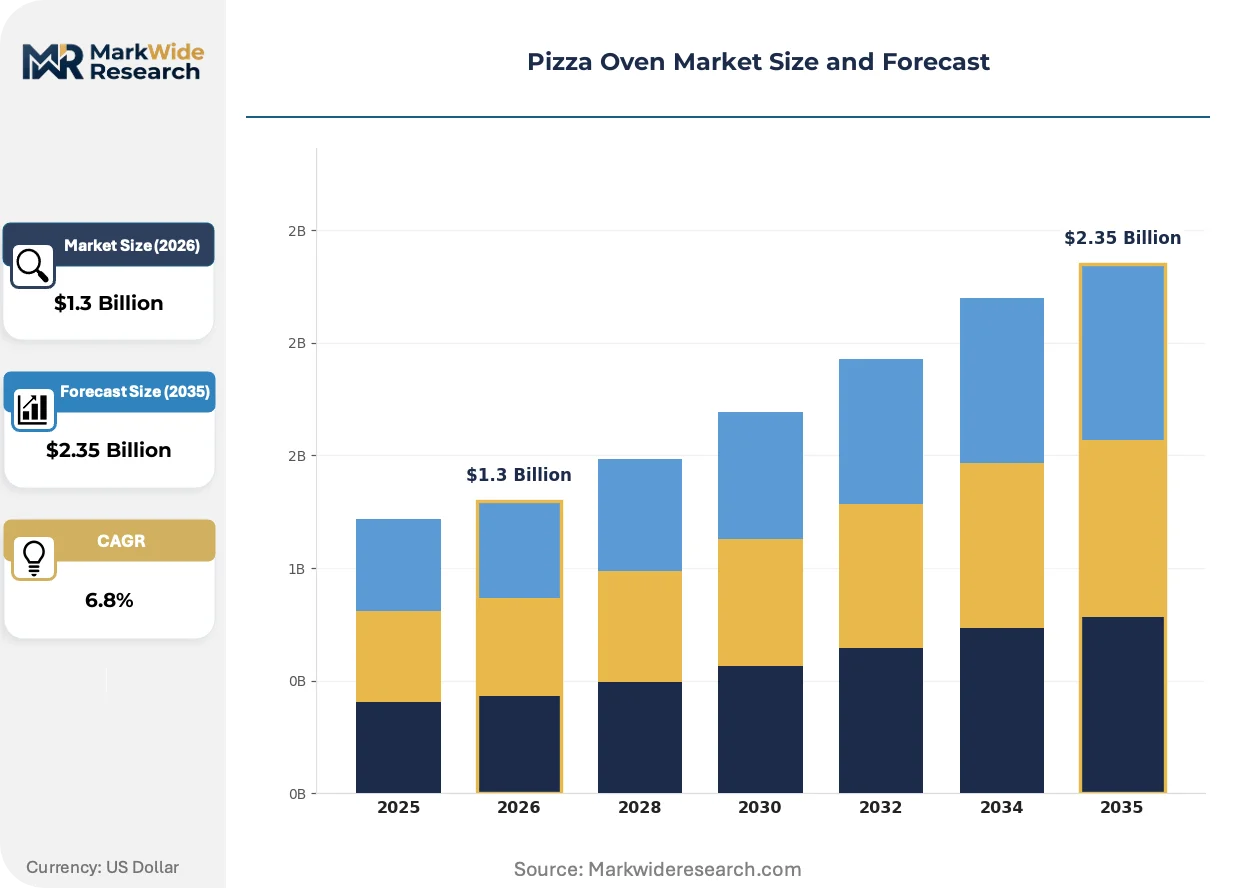
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Electric, Wood-Fired, Conveyor End User: Restaurants, Food Trucks, Bakeries, Home Users Installation Type: Built-In, Portable, Freestanding, Custom Capacity: Single, Double, Commercial, Large Volume |
| Companies Covered | Morello Forni Italia, Forno Bravo, Wood Stone Corporation, Marra Forni, Middleby Corporation, Le Panyol, EarthStone Wood-Fire Ovens, Ooni Pizza Ovens, Gozney, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Oven Market Strategic Shifts & Innovations
Active thermal management systems and smart combustion controls are redefining operational benchmarks across pizza oven categories, while regulatory pressure on emissions and energy intensity accelerates hardware refresh cycles in mature markets.
Refractory ceramic fiber insulation is consolidating its position as the dominant thermal barrier material in commercial pizza oven construction. High-volume pizzeria chains are specifying ceramic fiber-lined decks and domes to achieve sub-20-minute preheat protocols. This material transition is consolidating supplier relationships around specialized ceramic manufacturers and compressing margins for traditional brick-fabrication subcontractors.
EU Ecodesign regulations governing appliance energy efficiency and emissions profiles are tightening compliance thresholds for gas-fired commercial cooking equipment. Manufacturers must now certify NOx and particulate outputs across standardized load profiles to maintain CE marking eligibility. Italian and Spanish oven fabricators are most exposed, redirecting R&D toward staged combustion and secondary air injection systems.
Food truck operators are unbundling equipment procurement from vehicle fit-out contracts, creating direct manufacturer relationships that bypass traditional foodservice distribution. This channel disintermediation is compressing distributor margins while rewarding oven makers with dedicated mobile-configured product lines. The pattern is most pronounced in Texas, California, and Florida where permit density for mobile food units exceeds national averages.
Pizza Oven Market Segmentation
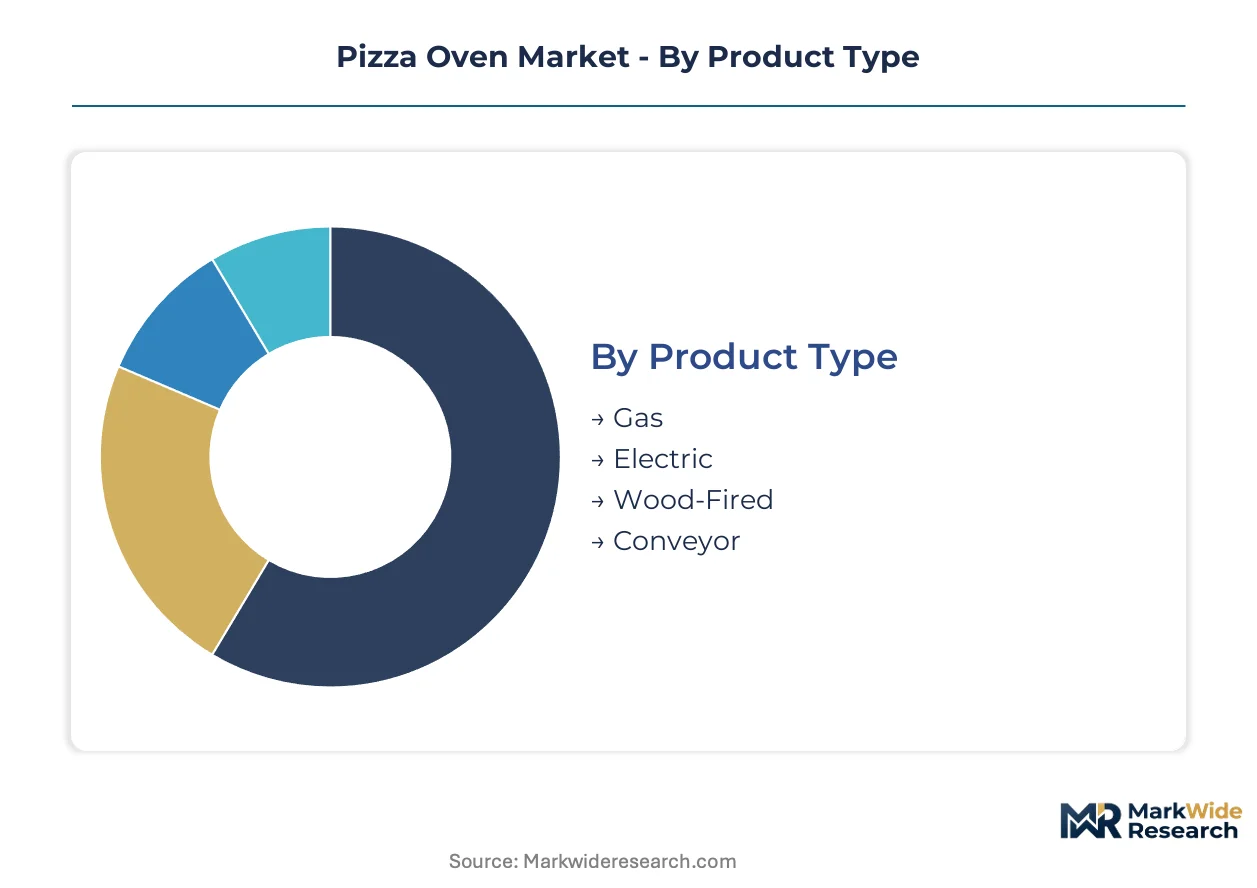
Pizza oven segmentation reveals distinct capital intensity thresholds across product architectures. Equipment buyers face fundamentally different upfront commitments depending on fuel type, mobility requirements, and throughput specifications. Understanding these tiered investment profiles enables manufacturers to align financing programs and service contracts with customer cash flow patterns.
Product Type:
Capital intensity varies sharply across fuel and conveyor architectures, with wood-fired installations demanding the highest upfront outlay for ventilation infrastructure and refractory materials.
- Gas:Atmospheric and infrared burner configurations dominate restaurant deployments due to operational simplicity and municipal code compliance. Demand concentrates in United States quick-service chains where fire department ventilation mandates favor controlled combustion systems over solid-fuel alternatives.
- Wood-Fired:Refractory dome construction and specialized flue engineering sustain premium positioning in artisan pizzerias. Italian equipment exports anchor this segment, though municipal solid-fuel bans in dense urban cores of New York and London constrain addressable market expansion.
- Electric:Resistance and induction heating elements suit electrification mandates advancing in California and EU member states. Compact footprints appeal to ghost kitchen operators facing space constraints.
- Conveyor:Continuous belt systems prioritize throughput consistency for high-volume pizza chains. NSF certification requirements drive specification standardization across United States foodservice procurement.
Most installed capacity flows through Gas. Expansion is steepest in Conveyor.
End User:
Customer scale determines equipment specification complexity, with enterprise restaurant groups driving standardization while fragmented operators prioritize flexibility.
- Restaurants:Full-service and quick-service operators specify deck and conveyor configurations based on menu breadth and peak-hour throughput requirements. Equipment procurement cycles align with franchise expansion timelines and renovation schedules.
- Food Trucks:Mobile dining formats demand compact, rapid-deployment ovens with multi-fuel compatibility. Texas, California, and Florida permit density exceeds national averages, pulling manufacturer attention toward dedicated mobile-configured product lines.
- Bakeries:Artisan bread and pastry operations repurpose pizza oven thermal mass for diversified product portfolios. Dual-use applications justify higher capital investment in refractory-lined equipment.
- Home Users:Residential outdoor kitchen expansion drives portable and freestanding demand through home improvement retail channels. Compact gas and wood-fired designs from specialized manufacturers target this segment.
Restaurants command the largest installed base. Food Trucks are climbing the fastest.
Installation Type:
Permanence of installation dictates supply chain and service model requirements, with portable configurations disrupting traditional distribution economics.
- Built-In:Masonry and custom metal enclosures integrate with commercial kitchen architecture. Project timelines extend due to coordination with general contractors and ventilation specialists.
- Portable:Compact designs with rapid deployment protocols serve food truck mobility and residential outdoor kitchen requirements. This segment is gaining share fastest as channel disintermediation compresses distributor margins.
- Freestanding:Self-supporting units balance mobility with commercial-grade output for catering operations and temporary installations. NSF sanitation certification remains mandatory for commercial deployment.
- Custom:Bespoke refractory construction serves flagship restaurant concepts and hospitality venues seeking visual differentiation. Italian and Spanish fabricators dominate this niche through artisan manufacturing heritage.
Built-In retains the largest footprint. Portable shows the steepest expansion trajectory.
Capacity:
Throughput specification determines manufacturing scale economics, with commercial and large-volume lines consolidating around specialized production facilities.
- Single:Compact deck units serve low-volume operators and specialty menu items. Residential and small independent restaurant demand sustains this tier.
- Double:Twin-chamber configurations balance throughput flexibility with footprint efficiency. Bakeries and mid-scale pizzerias favor this architecture for product diversification.
- Commercial:High-output deck and conveyor systems target franchise chains and institutional foodservice. Equipment financing programs and extended service contracts characterize procurement in this tier.
- Large Volume:Continuous conveyor and multi-deck installations serve stadium catering, commissary kitchens, and central production facilities. Custom engineering and installation supervision extend project duration and capital commitment.
Commercial capacity dominates current installations. Large Volume is expanding most quickly as ghost kitchen and commissary infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian manufacturing clusters in Modena and Reggio Emilia anchor artisan equipment exports, while municipal solid-fuel bans in dense urban cores redirect capital toward gas-fired alternatives across multiple continents.
United States
Food truck permit density in Texas, California, and Florida exceeds national averages, pulling manufacturer attention toward mobile-configured product lines. The US Inflation Reduction Act creates subsidy pathways for commercial kitchen equipment efficiency upgrades. NSF International sanitation standards and local fire department ventilation mandates dictate hood specifications for wood-burning installations in New York and Chicago.
Italy
Artisan equipment exports sustain regional manufacturing clusters in Modena and Reggio Emilia. EU Ecodesign regulations tighten compliance thresholds for gas-fired commercial cooking equipment. Municipal solid-fuel bans in Milan's dense urban core structurally cap addressable market for traditional wood-fired installations.
Germany
Energy efficiency mandates accelerate replacement cycles in commercial kitchens. CE marking requirements and EU Ecodesign regulations govern appliance energy efficiency and emissions profiles. Industrial fabricators in North Rhine-Westphalia redirect research and development toward staged combustion systems.
India
Underpenetrated organized pizza chain infrastructure in tier-2 cities presents white space for conveyor and deck oven deployment. The country's national food safety regulator enforces commercial kitchen equipment standards. Quick-service format proliferation in Maharashtra and Karnataka drives equipment procurement cycles.
United Kingdom
Municipal ordinances restricting wood combustion in London's dense core constrain traditional wood-fired deployment strategies. The country's national building safety regulator enforces ventilation and flue specifications for commercial cooking equipment. Ghost kitchen operators in Greater Manchester and Birmingham favor compact electric configurations.
Pizza Oven Market Key Industry Players
Global majors compete with regional champions across equipment fabrication and distribution channels, producing a tiered structure where scale-driven conglomerates, artisan heritage fabricators, and portable-specialist disruptors occupy distinct competitive spaces. Market consolidation remains moderate, with portfolio breadth and manufacturing heritage serving as primary differentiation vectors. Strategic moves center on channel disintermediation toward food truck operators and backward integration into refractory material supply.
Within the artisan heritage tier, Marra Forni and Morello Forni Italia exemplify Italian manufacturing traditions that anchor premium wood-fired positioning in North American foodservice channels. Middleby Corporation occupies a position among scale-driven conglomerates with portfolio breadth across conveyor and gas-fired systems. Ooni Pizza Ovens represents the portable-specialist archetype, competing aggressively in compact configurations targeting residential users and mobile dining formats.
| Leading Market Players |
|---|
| Morello Forni Italia |
| Forno Bravo |
| Wood Stone Corporation |
| Marra Forni |
| Middleby Corporation |
| Le Panyol |
| EarthStone Wood-Fire Ovens |
| Ooni Pizza Ovens |
| Gozney |
| Others |
Cost & Logistics Intelligence
EU Ecodesign mandates for commercial cooking equipment are forcing manufacturers to absorb certification and combustion-redesign costs, compressing margins on mid-tier gas-fired lines while premium wood-fired systems maintain pricing power through artisan scarcity. This regulatory pressure cascades into supply chain decisions as fabricators consolidate supplier relationships around specialized ceramic fiber manufacturers capable of delivering compliant insulation at scale.
Pricing Analysis
Input-cost pass-through from refractory ceramic fiber and high-grade alumina-silicate sourcing is intensifying price pressure across mid-market oven tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance specifications, with NSF/ANSI 4 sanitation certification commanding substantial premiums. Cost compression in standard-tier gas-fired systems reflects buyer consolidation among quick-service chains, while artisan wood-fired configurations retain pricing resilience due to limited Italian fabrication capacity and specialized masonry labor scarcity.
Supply Chain Analysis
Specialized refractory masons in Modena, Reggio Emilia, and select Spanish fabrication centers face shrinking labor pools, extending project timelines and compressing output capacity for traditional wood-fired construction. Supply chains draw from concentrated Italian and Chinese sources for high-grade alumina-silicate ceramics, with secondary dependencies on North American steel for atmospheric burner housings and conveyor frames. Single-source vulnerability around ceramic fiber insulation creates exposure to input cost volatility, while distribution runs through foodservice equipment distributors facing disintermediation pressure from direct food truck procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pizza oven manufacturing hinges on ceramic fiber insulation standardization reducing thermal mass costs, while premium-tier shifts toward certified low-emission gas systems capture subsidy flows from efficiency incentive programs.
For Market Incumbents: Anchor defensive positioning through backward integration into refractory ceramic fiber supply and captive installation certification programs. Middleby Corporation's portfolio breadth demonstrates how conveyor-system standardization defends against portable-specialist disruption. Prioritize CE marking compliance investment ahead of EU Ecodesign threshold tightening to lock out smaller Italian competitors lacking R&D scale. For New Entrants and Emerging Players: Food truck operators unbundling equipment procurement from vehicle fit-out contracts represent the most penetrable buyer archetype for direct manufacturer relationships. Texas, California, and Florida permit density creates geographic concentration for mobile-configured product line investment. Ghost kitchen operators in space-constrained urban cores offer secondary white-space for compact electric deck oven deployment with rapid-installation protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with portable-specialist manufacturers possessing direct-to-operator channel infrastructure and multi-fuel combustion IP. Long-term viability favors acquisition targets with defensible positions in ceramic fiber insulation partnerships or food truck distribution relationships. Watch municipal solid-fuel ban acceleration in dense urban cores as inflection indicator for gas-fired equipment demand reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Fiber Insulation Partnership | Captive supply agreements with Modena-based refractory manufacturers secure input cost stability for high-volume pizzeria chains. |
| Mobile-Configured Product Line Launch | Dedicated food truck oven designs bypass distributor margin capture in Texas and California permit-dense markets. |
| CE Marking Compliance Investment | Staged combustion certification maintains European market access as EU Ecodesign thresholds tighten on NOx emissions. |
| Direct-to-Operator Channel Buildout | Bypassing foodservice distributors captures margin compression from food truck operator procurement unbundling. |
| NSF/ANSI 4 Certification Acceleration | Sanitation certification unlocks quick-service chain procurement cycles in United States franchise expansion timelines. |
Research Approach
Bottom-up restaurant and foodservice operator modeling reconciled against top-down refractory material and equipment shipment tracking forms the analytical core of this study. Primary interviews with commercial kitchen equipment procurement directors, food truck fleet operators, Italian oven fabricators, and NSF certification consultants combined with secondary validation from SEC filings of publicly traded foodservice equipment manufacturers, EU Ecodesign regulatory databases, and municipal permit records for mobile food units across Texas, California, and Florida. Triangulation between demand-side capital expenditure patterns and supply-side production capacity announcements ensures consistency across estimation procedures.
Input-output matrices map refractory material flows through Italian and Chinese ceramic manufacturers to finished equipment assembly in Modena, Reggio Emilia, and North American fabrication facilities. Segmentation dimensions include fuel type, installation permanence, capacity tier, and end-user scale, with CAGRs derived from regression analysis against commercial kitchen construction permits and quick-service franchise expansion announcements. Industry-specific forecast inputs incorporate EU Ecodesign compliance cost trajectories and food truck permit density growth patterns across the projection horizon.
Inputs from equipment procurement databases and municipal regulatory filings were available through the study window; gaps in ghost kitchen operator capital expenditure disclosure introduce uncertainty bands around compact electric oven demand estimates. Forecasts reflect documented assumptions regarding refractory material cost trajectories and municipal solid-fuel ban propagation rates. Material deviation in EU Ecodesign enforcement intensity or ceramic fiber supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Germany Foodservice Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
A La Carte Market
Food Service
China Food Service Market
Food Service
Commercial Sink Market
Food Service
Beverage Vending Machine Market
Food Service
Europe Barbeque Grill Market
Food Service
Tabletop Pizza Oven Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Europe Food Service Market
Food Service
Bahrain Food Service Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Commercial Burger Grill Market
Food Service
United Kingdom Foodservice Market
Food Service
Commercial Steam Table Market