
 Air Fryer Meal Kits Market | 2026-2036
Air Fryer Meal Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Air Fryer Meal Kits Market Analysis
Buyer concentration among time-pressed households is realigning toward subscription-based meal solutions that eliminate planning friction. HelloFresh leverages its fulfillment network density to sustain next-day delivery promises in major metros. Marley Spoon differentiates through chef-curated recipe complexity that anchors higher-margin customer cohorts. Purple Carrot specializes in plant-forward formulations that occupy a defensible niche against protein-centric rivals.
Air fryer meal kits combine pre-portioned ingredients with recipes engineered specifically for convection-based countertop cooking, typically requiring oil volumes below 15% of conventional frying methods. The product category serves commercial and residential end users seeking crisp texture profiles without deep-fryer infrastructure or cleanup burden. Protein Kits dominate current revenue contribution due to mainstream palate alignment, while Vegetarian Kits represent the fastest-growing product type as flexitarian dietary patterns expand. Family Packs command premium positioning through portion scaling, though Single-Serve Packs are gaining traction among urban solo dwellers. Online Retailers control the primary distribution channel, yet Meal Delivery Services are capturing repeat purchase frequency through integrated subscription mechanics.
The FDA's Food Safety Modernization Act mandates ingredient traceability from farm to fulfillment center, elevating compliance costs for kit assemblers. USDA organic certification requirements shape supplier qualification and limit sourcing flexibility for premium-positioned brands. State-level packaging waste regulations in California and New York are forcing material transitions that affect cost structures. Stakeholders must monitor how evolving energy-efficiency labeling for countertop appliances intersects with consumer purchase decisions for the cooking hardware that enables kit consumption.
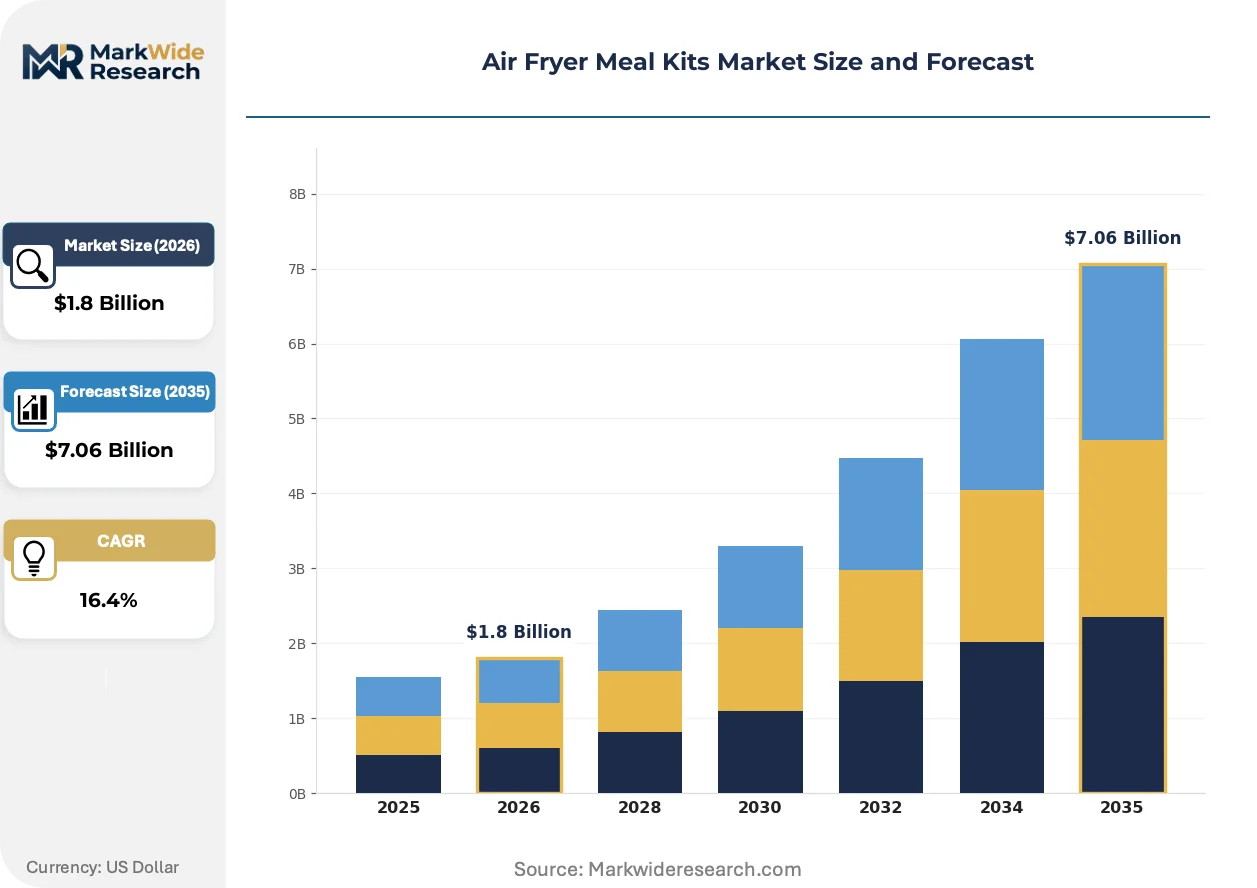
Market Dynamics
The FDA's Food Safety Modernization Act traceability mandates are compressing supplier qualification timelines while elevating compliance infrastructure costs across meal kit assembly networks. This regulatory pressure intersects with working-parent demand concentration to reshape competitive moats around fulfillment velocity and ingredient provenance documentation.
Growth Catalysts
- Time-compressed household meal preparation:Dual-income families with children under 12 are prioritizing subscription solutions that eliminate planning friction and reduce active cooking time below 25 minutes.
- USDA organic certification pipeline expansion:Premium-positioned brands are locking in certified supplier contracts three to five years forward to secure ingredient traceability compliance.
- Air fryer countertop appliance penetration:Convection-based cooking hardware adoption in North American and Western European residential kitchens is creating installed-base demand for compatible ingredient formats.
Market Restraints
- Perishable ingredient spoilage rates:Cold-chain integrity failures during last-mile delivery generate waste costs that compress net margins for protein-centric kit configurations.
- Single-source packaging material dependencies:California and New York state-level waste regulations are forcing transitions to compostable substrates with limited qualified supplier bases.
- Deep-fried texture substitution ceiling:Oil-volume reduction below 15% of conventional frying methods creates sensory gaps that limit category expansion into traditional comfort-food occasions.
Strategic Opportunities
- Urban solo-dweller segment penetration:Single-serve pack formats remain underdeveloped relative to family-pack scaling economics in dense metropolitan cores.
- Plant-forward flexitarian formulation:Vegetarian kit development captures dietary-transition households seeking protein alternatives without full vegetarian commitment.
- Energy-efficiency appliance labeling convergence:EPA Energy Star certification for air fryer hardware creates co-marketing pathways with kit brands targeting sustainability-motivated purchasers.
Industry Challenges
- Farm-to-fulfillment traceability system integration:FDA-mandated record-keeping requirements demand ERP upgrades that strain mid-tier assemblers with legacy inventory platforms.
- Recipe-to-appliance calibration precision:Convection airflow variability across air fryer brands requires iterative testing protocols that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Fryer Meal Kits Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian Kits, Protein Kits, Snack Kits, Dessert Kits Packaging Type: Single-Serve Packs, Family Packs, Bulk Packs, Combo Packs End User: Families, Single Households, Health-Conscious Consumers, Busy Professionals Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Meal Delivery Services |
| Companies Covered | Purple Carrot, Marley Spoon, HelloFresh, EveryPlate, Dinnerly, Blue Apron, Sun Basket, Freshly, Green Chef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Fryer Meal Kits Market Emerging Trajectories
Active packaging technologies and subscription mechanic refinements are compressing customer acquisition costs while extending lifetime value metrics. These developments intersect with regulatory traceability mandates to reshape operational infrastructure investments.
Smart packaging with time-temperature indicators is expanding into premium-tier meal kit configurations to reduce spoilage disputes and insurance claims. Quick-service restaurant chains evaluating residential meal solutions are piloting these formats for corporate subscription programs. The technology is expanding into mid-market positioning as unit economics improve through scale procurement of sensor substrates.
California's SB 54 packaging waste regulations are forcing material transitions to fiber-based trays and compostable films by 2032. Meal kit assemblers with West Coast fulfillment concentration face accelerated compliance timelines relative to national competitors. Protein kit suppliers with multi-state distribution networks are consolidating packaging specifications to avoid SKU proliferation.
Subscription bundling with countertop appliance financing is displacing standalone hardware purchases in urban household formation cohorts. Retail channel partners with integrated credit programs are capturing this shift through point-of-sale integration. United States metropolitan markets with high apartment-dweller density show the strongest attachment rates for combined hardware-ingredient subscription contracts.
Air Fryer Meal Kits Market Segmentation
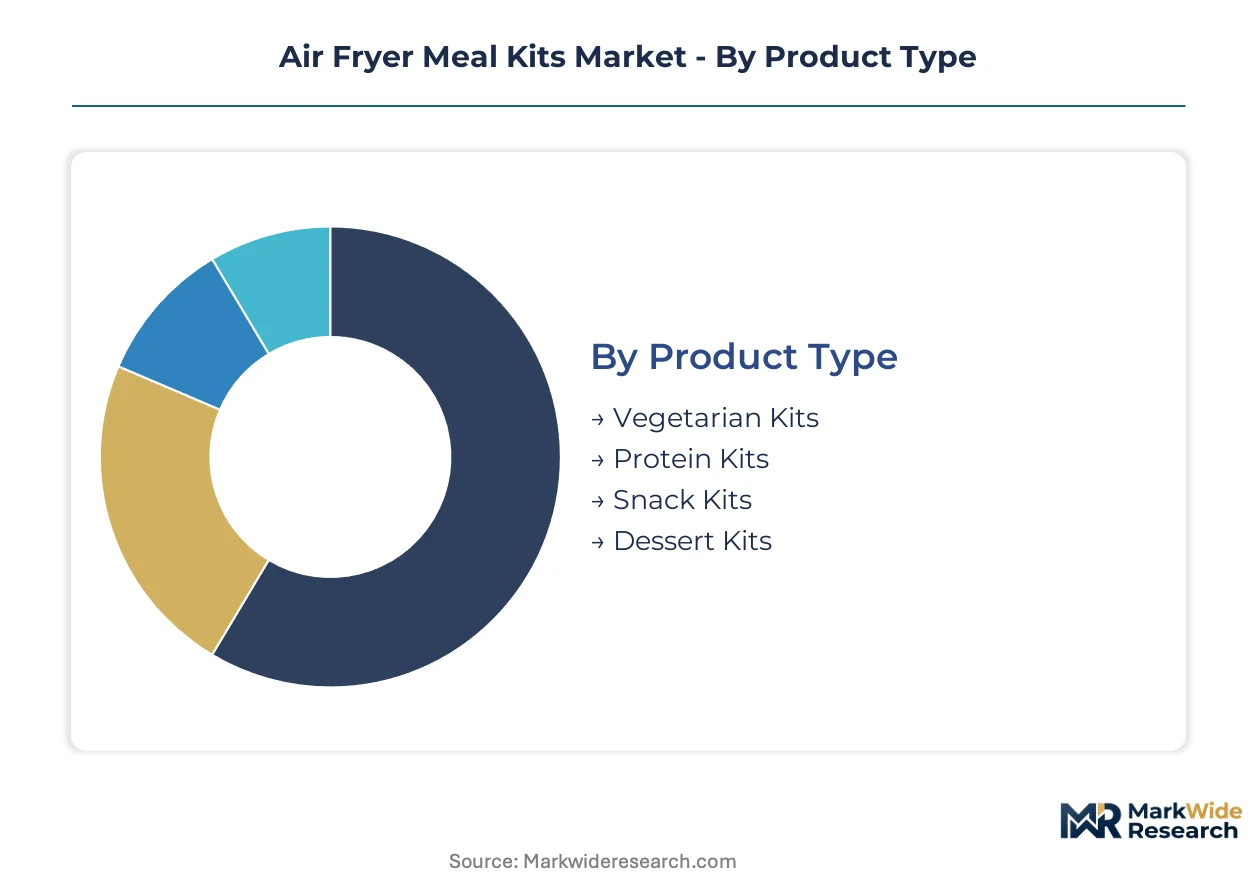
Segmentation in air fryer meal kits reflects divergent optimization paths: protein-centric formulations chase mainstream volume while plant-forward variants capture dietary-transition households. Packaging formats and channel strategies further fragment as urban density and subscription mechanics reshape fulfillment economics.
Product Type:
Customization spans from chef-curated complexity to standardized convenience, with protein-forward and plant-based formulations anchoring opposite ends of the development spectrum.
- Protein Kits:Center-cut meats and seafood portions arrive pre-marinated with convection-optimized coatings that crisp at reduced oil volumes. Demand concentrates in United States suburban households where air fryer penetration exceeds other developed markets and weeknight cooking time constraints peak.
- Vegetarian Kits:Plant-forward formulations featuring tempeh, cauliflower steaks, and legume-based proteins engineered for Maillard browning in circulating hot air. Flexitarian households in dense metropolitan cores drive fastest expansion as partial protein substitution gains cultural acceptance without full vegetarian commitment.
- Snack Kits:Finger-food assemblies with pre-cut vegetables, cheese bites, and breaded items calibrated for rapid air fryer batching.
- Dessert Kits:Portioned doughs, batters, and fruit preparations designed for countertop convection finishing with minimal added fat.
Leading the category by volume: Protein Kits. Growing fastest: Vegetarian Kits.
Packaging Type:
Unit economics and portion precision diverge sharply as household composition and storage constraints dictate format selection.
- Family Packs:Multi-portion configurations with scaled ingredient volumes and recipe cards serving four to six diners. United States suburban markets with children under twelve anchor demand as dual-income parents prioritize single-purchase solutions covering multiple meals.
- Single-Serve Packs:Individual portions with minimized packaging footprint and refrigerator-space efficiency. Urban solo dwellers in high-rent districts with compact kitchens represent the steepest expansion trajectory as apartment-dwelling rates climb in metropolitan cores.
- Bulk Packs:Unassembled ingredient bundles for batch preparation and freezer stocking.
- Combo Packs:Mixed-format offerings combining single-serve and family portions for flexible household scheduling.
Highest margin capture: Family Packs. Most underdeveloped relative to addressable demand: Single-Serve Packs.
End User:
Time scarcity and health motivation segment the buyer base across divergent life-stage and occupational pressures.
- Families:Multi-diner households prioritizing speed-to-table and minimal cleanup. United States markets with school-age children concentrate demand as extracurricular scheduling compresses evening meal preparation windows.
- Busy Professionals:Time-compressed wage earners seeking sub-twenty-five-minute active cooking with restaurant-quality outcomes. Dense urban corridors with high single-person household formation show strongest attachment to subscription-integrated delivery.
- Single Households:Solo occupants optimizing for portion control and waste minimization.
- Health-Conscious Consumers:Buyers prioritizing reduced oil consumption and ingredient transparency in dietary management.
Largest addressable base: Families. Fastest-growing cohort: Busy Professionals.
Distribution Channel:
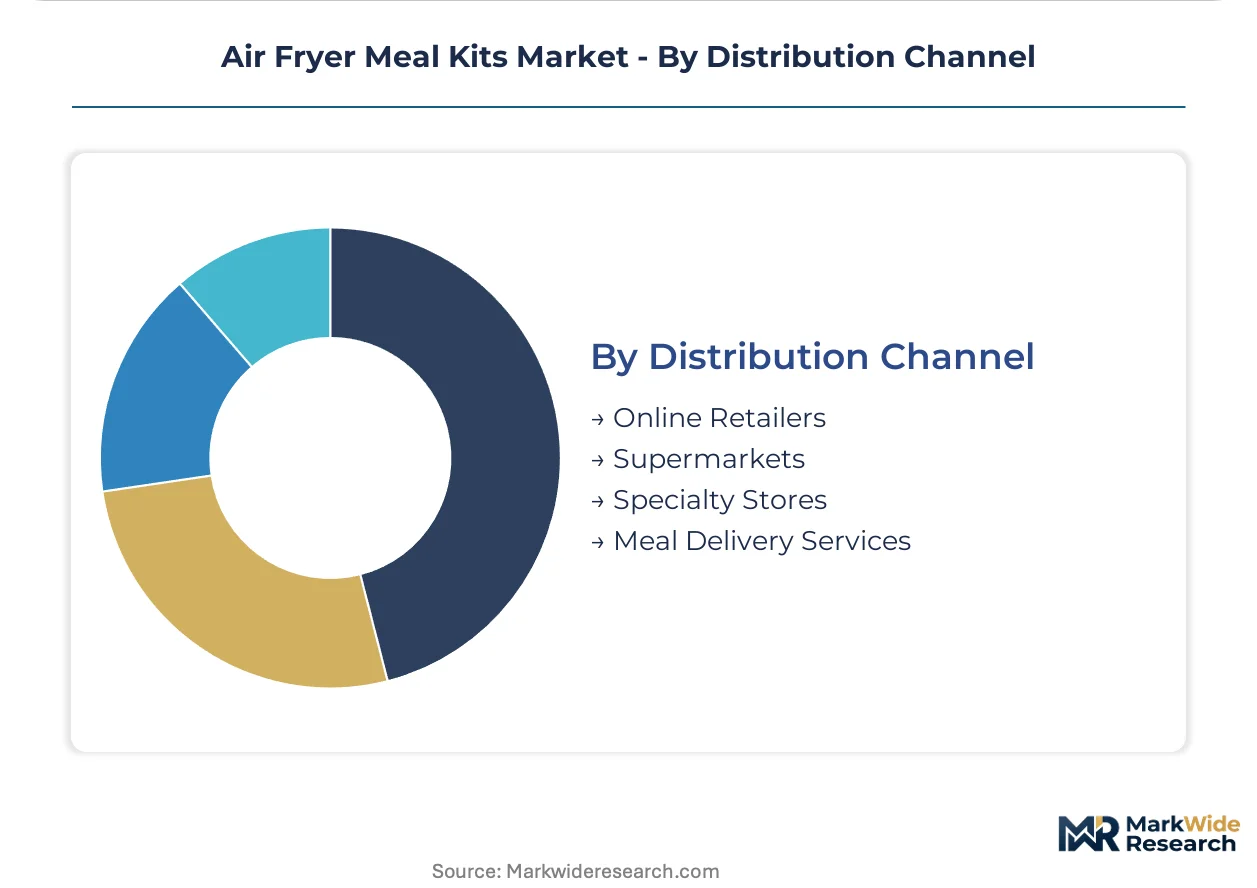
Channel selection determines repeat purchase mechanics and customer acquisition cost structures.
- Meal Delivery Services:Subscription-integrated fulfillment with predictive inventory and automated reordering. United States metropolitan markets with established cold-chain density sustain lowest churn rates through habit-formation tooling and flexible skip mechanisms.
- Online Retailers:Third-party marketplace listings with variable shipping economics and limited subscription integration. Broad geographic reach compensates for higher per-order acquisition costs in non-metro postal codes.
- Supermarkets:In-store refrigerated sections with impulse-purchase positioning and same-day availability.
- Specialty Stores:Curated retail environments targeting organic-certification seekers and dietary-restriction buyers.
Dominant volume channel: Online Retailers. Superior retention mechanics: Meal Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working parents in the United States drive the steepest demand concentration for air fryer meal kits, with dual-income households prioritizing sub-twenty-five-minute preparation windows. Subscription penetration overlaps most densely where countertop appliance adoption and time-compressed lifestyles intersect.
United States
Suburban households with school-age children anchor protein kit demand as extracurricular scheduling compresses evening meal windows. The FDA's Food Safety Modernization Act mandates farm-to-fulfillment traceability that elevates compliance infrastructure costs for kit assemblers. Cold-chain density in metropolitan corridors sustains lowest churn rates for subscription-integrated delivery services.
Germany
Flexitarian dietary patterns in dense urban cores accelerate vegetarian kit expansion as partial protein substitution gains cultural traction. The EU Green Deal packaging waste directives force transitions to compostable substrates that limit qualified supplier bases. The Rhine-Ruhr metropolitan region concentrates fulfillment network investments from meal delivery services seeking central European hub positioning.
United Kingdom
Single-serve pack formats find steepest traction among urban solo dwellers in high-rent districts with compact kitchen constraints. Food Standards Agency allergen labeling requirements shape recipe card design and ingredient segregation protocols. Greater London's subscription attachment rates exceed national averages as apartment-dwelling rates climb and hardware-ingredient bundling gains traction.
France
Chef-curated recipe complexity anchors premium positioning for households seeking restaurant-quality outcomes without active cooking time exceeding thirty minutes. ANSM food contact material regulations govern packaging substrate approvals for refrigerated distribution. The Île-de-France region concentrates demand for family pack configurations as dual-income parents prioritize single-purchase solutions covering multiple meals.
Canada
Health-conscious consumers in Ontario and British Columbia drive reduced-oil cooking adoption as dietary management priorities intersect with convenience seeking. Health Canada and PMRA joint oversight of novel food ingredients affects plant-forward formulation approval timelines. The Toronto metropolitan corridor shows strongest attachment to energy-efficiency appliance labeling convergence between EPA Energy Star and equivalent Canadian certification programs.
Air Fryer Meal Kits Market Vendor Landscape
United States producers anchor the subscription-integrated tier; European specialists hold positions in chef-curated and plant-forward niches. Market structure tilts toward consolidated subscription mechanics with fragmented specialty positioning. Three archetypes dominate: fulfillment network scale players, chef-credential differentiation specialists, and defensible niche occupiers in dietary-transition segments. Competitive moves concentrate on cold-chain infrastructure expansion and packaging material compliance acceleration ahead of regulatory deadlines.
Among subscription-scale operators, HelloFresh and Marley Spoon exemplify divergent strategic positioning within the same archetype. Purple Carrot occupies a distinct tier as a plant-forward specialist. HelloFresh represents fulfillment velocity optimization through network density. Marley Spoon anchors chef-curated complexity that sustains higher-margin cohorts. Purple Carrot exemplifies defensible niche construction against protein-centric rivals. Each sits within a competitive tier defined by customer acquisition cost structures and lifetime value mechanics rather than product overlap.
| Leading Market Players |
|---|
| Purple Carrot |
| Marley Spoon |
| HelloFresh |
| EveryPlate |
| Dinnerly |
| Blue Apron |
| Sun Basket |
| Freshly |
| Green Chef |
| Others |
Supply Flow & Price Mechanics
California's SB 54 packaging waste mandate gates qualified supply for premium-tier air fryer meal kits, restricting substrate approvals to compostable fiber trays and certified films that limit supplier pools and sustain price premiums for compliant brands. This environmental compliance threshold concentrates sourcing leverage among assemblers with multi-year supplier contracts, while non-compliant competitors face margin compression from accelerated material transitions or exclusion from West Coast metropolitan markets.
Pricing Analysis
Volume concentrates in protein-centric family packs while margins concentrate in chef-curated vegetarian configurations. Three-tier pricing structure across premium, standard, and economy levels differentiates by USDA organic certification status and recipe complexity tier. Pricing pressure stems from single-serve pack underdevelopment relative to addressable urban demand. Busy professionals in dense metropolitan cores show lowest price sensitivity; suburban families with multiple children exhibit highest sensitivity to per-portion economics.
Supply Chain Analysis
Domestic-content preferences in USDA organic certification pipelines are reshaping sourcing toward United States-based produce suppliers and North American protein processors. Cold-chain infrastructure concentrates in the United States, Germany, and the United Kingdom. Ingredient inputs hinge on pre-portioned produce, convection-optimized protein coatings, and compostable packaging substrates. Single-source vulnerability runs through limited qualified compostable film suppliers facing California and New York regulatory deadlines. Distribution runs through subscription-integrated meal delivery services with predictive inventory systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostable packaging substrate scarcity props pricing power for compliant air fryer meal kit assemblers, with qualified supplier concentration creating a capacity bottleneck that sustains premium-tier positioning through the analysis window.
For Market Incumbents: Hedge against FDA Food Safety Modernization Act compliance cost escalation by locking three-to-five-year forward contracts with certified organic suppliers. Accelerate ERP traceability system upgrades before 2026 enforcement windows strain mid-tier competitors with legacy platforms. Vertical integration into cold-chain fulfillment nodes in the Rhine-Ruhr and Greater Toronto corridors defends against last-mile spoilage rate compression. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription mechanics targeting urban solo dwellers in high-rent districts with compact kitchen constraints. Single-serve vegetarian packs in dense metropolitan cores represent the most penetrable white space, as flexitarian dietary patterns expand without incumbent saturation. Energy-efficiency appliance labeling convergence with EPA Energy Star certification creates co-marketing pathways for bundled hardware-ingredient subscription contracts. For Investors and Strategic Acquirers: FDA enforcement action on traceability compliance is the leading indicator that mid-tier assemblers with legacy inventory platforms will face acquisition pressure or exit. Long-term viability across the five-to-ten-year window favors vertically integrated operators with captive cold-chain density and multi-state packaging specification consolidation. Target acquisition archetypes include plant-forward specialists with defensible flexitarian positioning and West Coast fulfillment concentration ahead of SB 54 deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Packaging Transition | California SB 54 compliance secures West Coast market access for premium-tier assemblers. |
| Cold-Chain Fulfillment Expansion | Rhine-Ruhr hub positioning captures central European flexitarian demand concentration. |
| Single-Serve Format Development | Urban solo-dweller penetration addresses the most underdeveloped segment relative to demand. |
| Energy Star Co-Marketing Program | Appliance-ingredient bundling targets sustainability-motivated household formation cohorts. |
| ERP Traceability Upgrade | FDA Food Safety Modernization Act compliance defends against enforcement-driven margin compression. |
Methodological Framework
Independent corroboration across meal kit operations executives, cold-chain logistics directors, USDA organic certification specialists, and supermarket category buyers underwrites the qualitative findings. Primary interviews with subscription platform engineers and packaging procurement leads at tier-one assemblers combined with secondary validation from FDA traceability guidance documents, California SB 54 regulatory filings, EPA Energy Star certification databases, and customs records of compostable substrate imports. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition separates appliance penetration effects from subscription mechanic adoption curves across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-user life stage, and distribution channel, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from fitted growth curves against historical subscription penetration patterns. Forecast inputs incorporate air fryer household penetration trajectories and flexitarian dietary transition rates.
Regulatory enforcement timing shifts, compostable substrate supply disruptions, and air fryer hardware replacement cycle elongation are the dominant revision risks. Forecasts reflect assumptions about compliance cost pass-through elasticity and cold-chain infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Service Gloves Market
Food Service
Haute Cuisine Market
Food Service
Online Grocery Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Indonesia Foodservice Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
France Foodservice Market
Food Service
Global Vending Machine Market
Food Service
Steam Tables and Food Well Market
Food Service
Healthy Takeout Market
Food Service
Global Waffle Maker Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Quick-Service Restaurants Market
Food Service
Commercial Bar Supplies Market
Food Service
Global Online Food Ordering Market
Food Service
Commercial Pizza Oven Market