
 GCC Business Jet Market | 2026-2036
GCC Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Business Jet Market Foresight
GCAA emissions disclosure requirements for business aviation is hardening operational standards across the Gulf. Textron Inc. leverages its light jet manufacturing scale to serve charter operators seeking fuel-efficient fleet renewal. Gulfstream Aerospace Corporation anchors the heavy jet segment through long-range cabin platforms favored by sovereign buyers. Bombardier Inc. competes on transcontinental range specifications that align with Dubai-to-London and Riyadh-to-New York routing demands.
A business jet denotes a fixed-wing aircraft configured for private or executive transport, typically pressurized with a maximum takeoff weight below 100,000 pounds and cabin altitudes engineered for passenger comfort above 40,000 feet. These assets serve time-sensitive corporate mobility, medical evacuation, and government priority transport missions where schedule control outweighs commercial airline constraints. Heavy jets capture premium margin pools due to intercontinental range and bespoke cabin completion economics. Light jets sustain the fastest fleet turnover as charter operators modernize toward more efficient powerplants. Fractional ownership models are expanding addressable demand among mid-tier private companies previously excluded from full-asset acquisition.
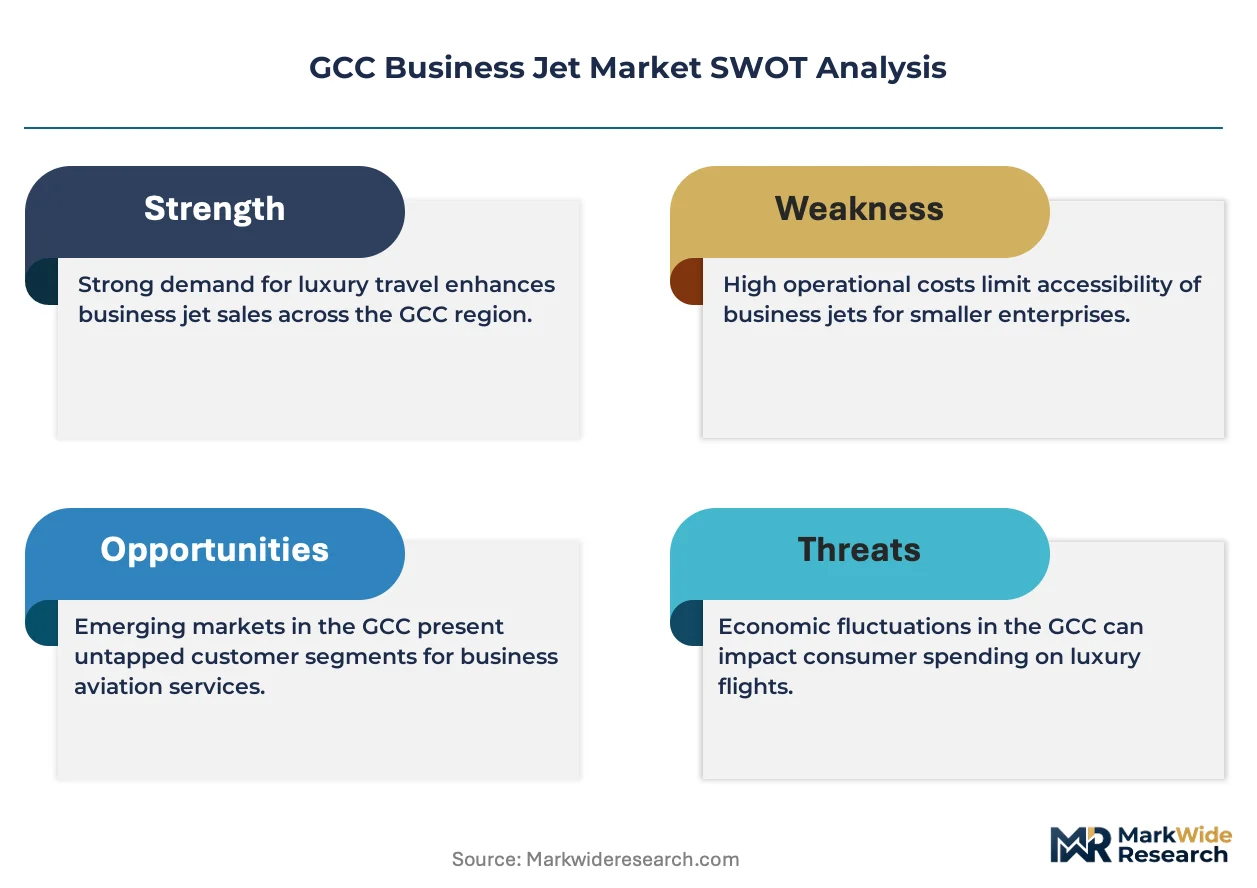
GCAA operational directives, Saudi GACA airworthiness protocols, and Qatar CAA slot coordination frameworks collectively shape market access and fleet eligibility across the Gulf. GCAA mandates on NextGen avionics compatibility are accelerating retirement of legacy aircraft lacking required navigation performance capability. Stakeholders must monitor sovereign aviation authority alignment with ICAO carbon offsetting thresholds as compliance costs will reshape fleet economics and resale values.
Market Dynamics
GCAA emissions disclosure mandates and sovereign wealth fund portfolio diversification are compressing fleet renewal cycles while expanding fractional ownership addressability across the six Gulf states.
Growth Catalysts
- Sovereign wealth fund capital deployment:Saudi Public Investment Fund allocations into aviation infrastructure are creating dedicated FBO capacity and MRO facilities that lower operational barriers for private fleet operators.
- GCAA NextGen avionics mandates:Required navigation performance specifications are accelerating retirement of legacy aircraft lacking precision approach capability, forcing replacement demand into the order book pipeline.
- Medical evacuation service expansion:Private hospital networks in Dubai and Riyadh are contracting dedicated air ambulance configurations, opening a mission-specific segment with premium equipment specifications.
Market Restraints
- Jet fuel price volatility:Gulf refining capacity concentration leaves operators exposed to regional supply disruptions and hedging complexity in dirham and riyal-denominated contracts.
- Slot coordination scarcity:Qatar CAA landing permit allocation frameworks at Doha Hamad International restrict peak-hour access for non-scheduled operations, compressing utilization rates.
- Pilot certification pipeline:GCAA type rating capacity constraints and training backlogs limit qualified crew availability for new aircraft deliveries.
Strategic Opportunities
- Kuwait underpenetration:Family office density relative to installed business jet base indicates latent demand for fractional programs and managed fleet services.
- Sustainable aviation fuel infrastructure:ADNOC and Saudi Aramco low-carbon fuel pilot projects at Abu Dhabi and Jeddah airports create first-mover positioning for emissions-compliant operators.
- Helicopter-to-fixed-wing conversion:Offshore energy executives previously reliant on rotary platforms are migrating to light jet shuttle services for inter-emirate connectivity.
Industry Challenges
- Airworthiness directive compliance timelines:Saudi GACA accelerated inspection intervals for aging airframes are compressing maintenance windows and requiring spare engine pooling investments.
- Cabin completion certification delays:Bespoke interior approvals from Bahrain's national aviation regulator extend delivery schedules by four to six months for heavy jet configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Business Jet Market |
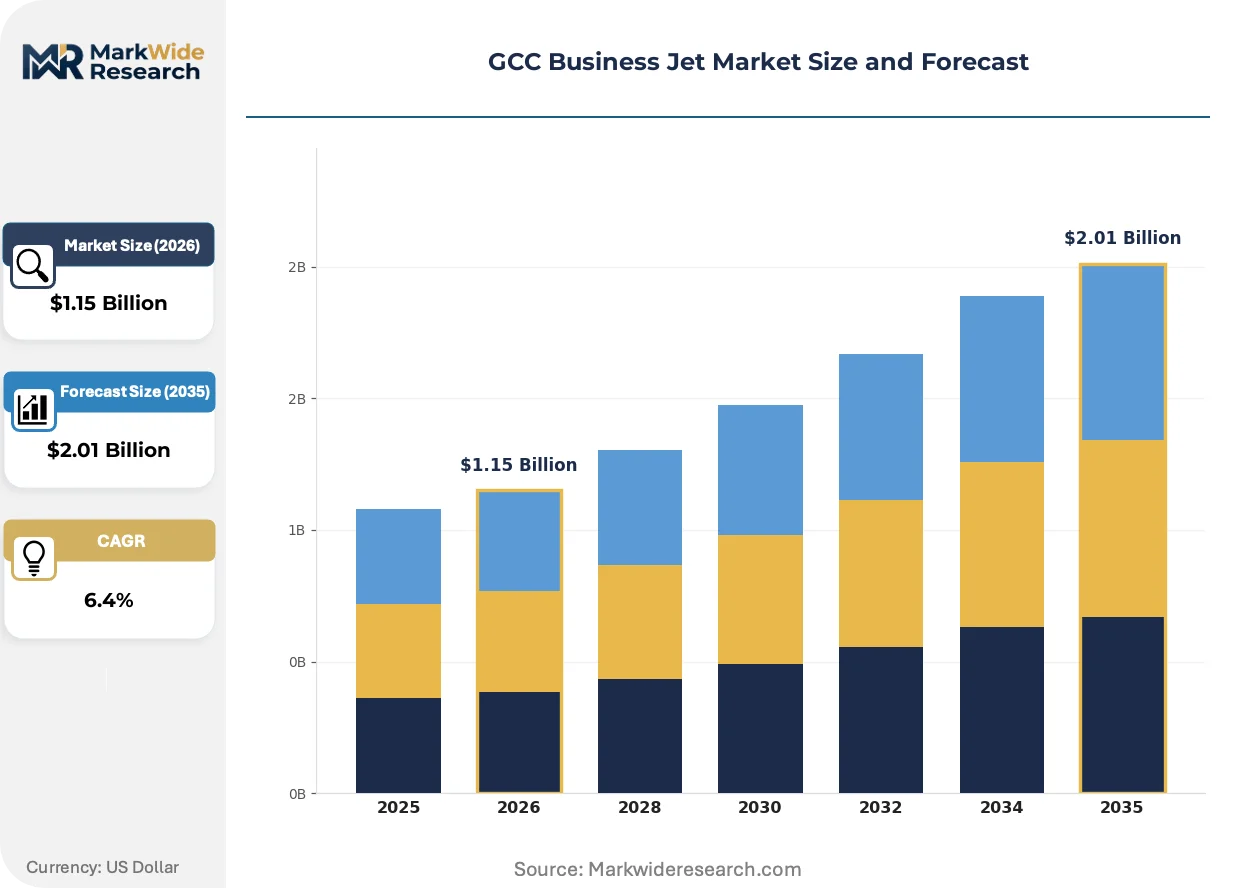
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Jets, Midsize Jets, Heavy Jets, Very Light Jets Application: Corporate Travel, Air Ambulance, VIP Transport, Charter Services, Government Operations End User: Private Companies, Charter Operators, Medical Institutions, Government Agencies Deployment: On-Demand, Fractional Ownership, Full Ownership, Leasing |
| Companies Covered | Textron Inc., Empire Aviation Group, Gulfstream Aerospace Corporation, Royal Jet LLC, DC Aviation Al-Futtaim, Bombardier Inc., Embraer SA, Qatar Executive, Dassault Aviation SA, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Business Jet Market Shifts & Advancements
Connectivity architecture and propulsion efficiency are reshaping aircraft specification priorities, while regulatory disclosure requirements are forcing operational transparency into ownership structures previously shielded from scrutiny.
Connected aircraft systems integrating real-time health monitoring and predictive maintenance algorithms are decentralizing MRO service delivery away from manufacturer-controlled networks. Charter operators and flight departments in Dubai are adopting these platforms fastest, drawn by reduced AOG exposure and parts inventory compression. The structural consequence is loosening OEM aftermarket capture and enabling third-party technical service providers to bid engine and avionics overhaul work previously reserved for factory service centers.
GCAA mandates on continuous emissions monitoring and carbon offsetting disclosure are hardening compliance documentation requirements for business aviation operators. The industrial consequence is forcing fleet managers to retrofit data acquisition systems or face operational restrictions in UAE-controlled airspace. Heavy jet owners undertaking transcontinental missions face the steepest compliance burden, with several Riyadh-based flight departments accelerating SAFA-compliant powerplant upgrades to avoid European route penalties.
Fractional ownership platforms are displacing traditional whole-aircraft acquisition among mid-tier corporate flight departments previously excluded from direct asset ownership. This model is fragmenting the buyer base and compressing sales cycle duration, as Saudi family offices and Bahraini investment groups seek capital efficiency without operational crew burden. The shift is most visible in the light jet segment, where King Fahd International and Dubai South FBOs report expanding shared-usage hangar configurations.
GCC Business Jet Market Segmentation
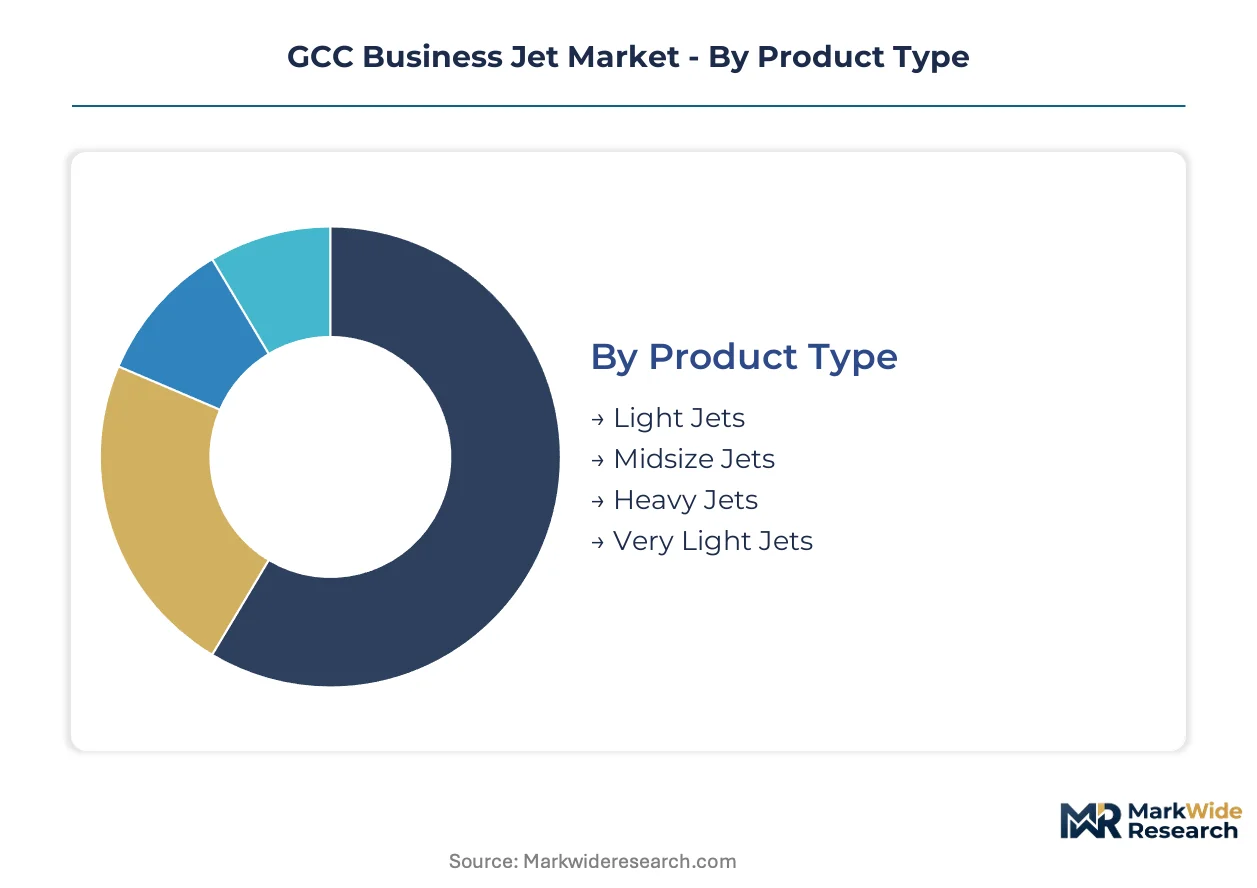
GCC fleet procurement patterns diverge sharply by mission profile and capital commitment. Sovereign buyers favor bespoke heavy platforms while charter operators optimize for asset utilization across standardized configurations.
Product Type:
Customization intensity spans from standardized light platforms to fully bespoke heavy cabins, with manufacturing economics and completion timelines varying by an order of magnitude.
- Light Jets:Single-pilot-certified aircraft with maximum takeoff weights below 20,000 pounds and range envelopes of 1,500-2,500 nautical miles. Charter operators at Dubai South and King Fahd International are consolidating fleets around these platforms to reduce per-hour operating costs and simplify crew scheduling.
- Heavy Jets:Intercontinental-range platforms exceeding 40,000 pounds MTOW with stand-up cabins and 6,000+ nautical mile reach. Saudi sovereign buyers and Abu Dhabi royal flight departments commission these for direct Riyadh-to-New York and Dubai-to-London missions, absorbing six-to-eight-month completion delays for bespoke interiors.
- Midsize Jets:Transcontinental-range assets bridging the Atlantic without the operating economics penalty of heavy platforms. Kuwaiti family offices are gravitating toward this segment for European connectivity.
- Very Light Jets:Entry-level personal aircraft with limited pressurization and 1,000-nautical-mile practical range. Bahrain-based private pilots acquire these for intra-Gulf shuttle missions.
Leading the category by volume: Light Jets. Growing fastest: Heavy Jets.
Application:
Mission criticality determines specification rigor, from time-deficient corporate mobility to life-sustaining medical evacuation.
- Corporate Travel:Scheduled executive transport between headquarters and project sites where commercial airline frequencies fail. Saudi Aramco and ADNOC flight departments operate dedicated fleets for remote site access.
- Air Ambulance:Intensive-care-configured aircraft with ventilator redundancy and isolation capabilities. Dubai's private hospital networks are contracting dedicated medevac platforms for African and Central Asian patient retrieval.
- VIP Transport:Royal and ministerial travel with security-hardened communications and defensive systems. Qatar Amiri Flight maintains specialized heavy jet configurations for head-of-state missions.
- Charter Services:On-demand brokerage fulfilling fragmented demand from companies lacking captive fleet economics. Dubai-based operators are expanding shared-usage hangar infrastructure at Al Maktoum International.
- Government Operations:Border patrol, customs surveillance, and priority personnel movement under sovereign aviation authority tasking. UAE Ministry of Interior operates modified platforms for maritime patrol.
Corporate Travel commands the largest fleet allocation. Air Ambulance is expanding most quickly.
End User:
Capital structure and operational risk tolerance separate entities that self-operate from those outsourcing crew and maintenance burden.
- Private Companies:Mid-tier Saudi and UAE corporates with annual flight-hour requirements below 200. These entities are migrating from ad hoc charter toward fractional ownership to secure schedule control without asset balance-sheet impact.
- Charter Operators:Fleet-owning entities selling block-hour programs and on-demand brokerage. Dubai-based operators are consolidating through acquisition to achieve scale economies in crew training and insurance.
- Medical Institutions:Hospital networks and specialized aeromedical providers. Saudi German Hospital and American Hospital Dubai are contracting dedicated air ambulance configurations.
- Government Agencies:Sovereign flight departments and ministry-operated fleets. Qatar Amiri Flight and UAE Presidential Flight operate outside commercial regulatory frameworks.
Charter Operators deploy the most airframes. Private Companies are gaining share fastest.
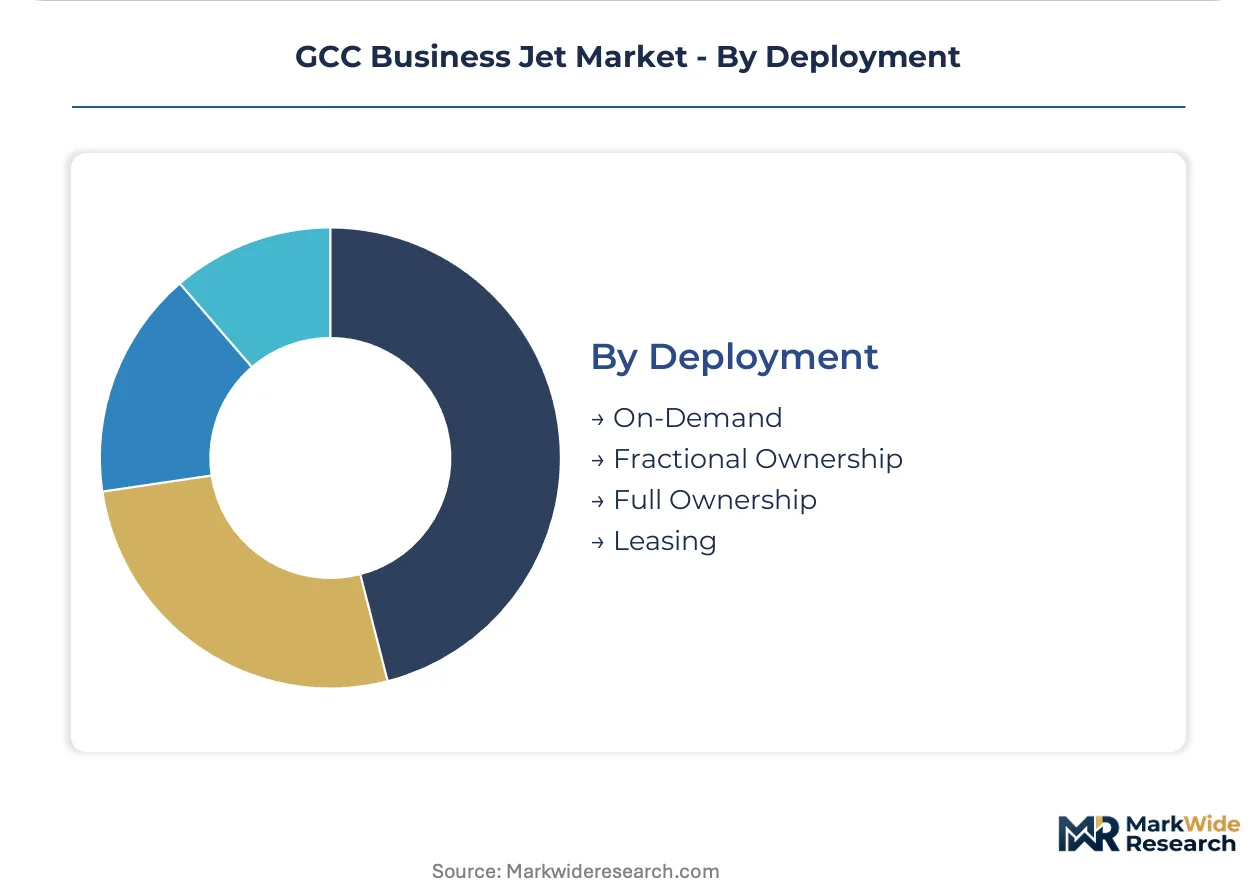
Deployment:
Ownership structure determines capital efficiency, operational control, and regulatory compliance burden distribution.
- Full Ownership:Complete asset control with captive crew and maintenance infrastructure. Sovereign wealth fund portfolios and ultra-high-net-worth family offices in Saudi Arabia favor this model for heavy jet acquisitions.
- Fractional Ownership:Title-sharing across multiple users with professional management of crew, maintenance, and scheduling. This model is penetrating the Kuwaiti market where family office density exceeds installed fleet base.
- Leasing:Dry or wet lease structures providing aircraft without residual value risk. Regional banks are developing Islamic finance lease products for Sharia-compliant fleet expansion.
- On-Demand:Pure charter brokerage with no asset commitment. This entry point serves first-time business aviation users in Oman and Bahrain.
Full Ownership retains the largest installed base. Fractional Ownership is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors GCC business jet activity through Al Maktoum International Airport infrastructure expansion and dedicated FBO capacity serving sovereign and charter demand.
Saudi Arabia
Sovereign wealth fund aviation allocations and ultra-high-net-worth family office expansion are accelerating fractional ownership penetration. Saudi GACA airworthiness protocols mandate accelerated inspection intervals for aging airframes. Riyadh-based flight departments at King Khalid International are commissioning heavy jet configurations for transcontinental missions.
United Arab Emirates
Dubai South FBOs and Abu Dhabi Royal Jet operations concentrate charter brokerage and VIP transport demand. GCAA emissions disclosure mandates and NextGen avionics compatibility requirements are hardening operational standards. Al Maktoum International infrastructure upgrades are reshaping hub-and-spoke logistics for inter-emirate connectivity.
Qatar
Qatar Executive and Amiri Flight operations sustain premium heavy jet utilization for head-of-state and corporate missions. Qatar CAA slot coordination frameworks restrict peak-hour access at Doha Hamad International for non-scheduled operations. Doha-based operators are consolidating shared-usage hangar configurations to optimize fleet deployment.
Kuwait
Family office density relative to installed business jet base indicates latent demand for fractional programs and managed fleet services. The country's national aviation authority maintains alignment with ICAO carbon offsetting thresholds for operational compliance. Kuwait International Airport FBO capacity is expanding to capture underpenetrated corporate flight demand.
Bahrain
Private pilot acquisition of very light jets for intra-Gulf shuttle missions is sustaining entry-level segment activity. Bahrain's national aviation regulator cabin completion certification timelines extend heavy jet delivery schedules. Sakhir Air Base proximity to financial district clusters supports executive transport mission profiles.
GCC Business Jet Market Competitive Landscape
The competitive structure tilts toward integrated OEM-manufacturer and charter-operator archetypes rather than pure brokerage models. Heavy jet manufacturing concentrates around long-range cabin platforms favored by sovereign buyers, while light jet supply fragments across fuel-efficient fleet renewal demand. Three archetypes dominate: airframe OEMs with completion capabilities, full-service charter operators with captive fleets, and fractional ownership platform managers. Consolidation through acquisition and sustainable aviation fuel infrastructure partnerships represent the dominant competitive vectors.
Within the OEM tier, Textron Inc. and Gulfstream Aerospace Corporation anchor manufacturing supply for light and heavy jet segments respectively. Bombardier Inc. occupies a position exemplifying transcontinental-range platform specialization. Among regional service operators, Empire Aviation Group and Royal Jet LLC represent integrated charter and management archetypes, while Qatar Executive sits within the sovereign-linked premium service tier.
| Leading Market Players |
|---|
| Textron Inc. |
| Empire Aviation Group |
| Gulfstream Aerospace Corporation |
| Royal Jet LLC |
| DC Aviation Al-Futtaim |
| Bombardier Inc. |
| Embraer SA |
| Qatar Executive |
| Dassault Aviation SA |
| Others |
Supply & Pricing Matrix
Captive MRO infrastructure at Dubai South and King Fahd International anchors both supply positioning and pricing power for heavy jet operators, creating tiered access economics that separate sovereign buyers from charter-dependent mid-market participants.
Pricing Analysis
Range-performance pricing anchors transaction values across the GCC fleet procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates bespoke heavy jet completions from standardized light jet configurations and entry-level very light platforms. Price differentiation rests on cabin completion certification grade and sovereign buyer customization intensity. Cost compression in the light jet segment is intensifying as charter operators consolidate fleet renewal around fuel-efficient powerplants. Private companies pursuing fractional ownership demonstrate highest price sensitivity; sovereign wealth fund portfolios show minimal elasticity.
Supply Chain Analysis
Aerospace engineering talent scarcity in Wichita, Savannah, and Montreal constrains airframe delivery schedules for Gulf-bound orders. Manufacturing concentration draws from US Gulf Coast composites facilities, Canadian wing assembly plants, and Brazilian regional jet platforms. Raw material dependencies center on titanium forgings, avionics semiconductor packages, and specialty interior fabrics. Single-source vulnerability in precision engine component machining creates delivery risk for Saudi GACA-mandated fleet renewal timelines. Distribution runs through manufacturer-authorized service centers at Al Maktoum International and King Khalid International.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCAA type rating capacity constraints create a supply-constrained market structure, with pilot certification backlogs propping pricing power for qualified crew services and managed fleet operators.
For Market Incumbents: Anticipate fractional ownership platform proliferation by securing hangar capacity at underutilized FBOs in Kuwait and Oman. Consolidate technical service capabilities through backward integration into avionics overhaul functions previously outsourced to OEM networks. Defend against emerging digital-native charter brokers by embedding predictive maintenance algorithms that reduce AOG exposure for corporate flight departments. For New Entrants and Emerging Players: Digital charter marketplaces offer the lowest-friction entry vector for capturing fragmented demand in Bahrain and Oman. White-space targets include medical evacuation service contracts with Saudi German Hospital and American Hospital Dubai, plus sustainable aviation fuel compliance consulting for Riyadh-based flight departments. A managed-fleet-as-a-service model bypasses capital-intensive aircraft acquisition while capturing recurring revenue from mid-tier private companies. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by sovereign wealth fund aviation platforms seeking integrated charter-MRO capabilities. Long-term viability favors operators with locked-in FBO access and GCAA regulatory relationships. Acquisition target archetype: regional charter operators with 15-30 airframe fleets and established sovereign client relationships. Watch SAFA-compliant powerplant upgrade penetration rates as inflection indicator for European route access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Infrastructure Partnership | ADNOC and Saudi Aramco pilot projects at Abu Dhabi and Jeddah airports create first-mover emissions compliance positioning. |
| Fractional Ownership Platform Launch | Kuwaiti family office density relative to installed fleet base indicates addressable demand for capital-efficient access models. |
| Third-Party MRO Capability Buildout | Connected aircraft systems decentralizing technical service delivery loosen OEM aftermarket capture for engine overhaul work. |
| Medical Evacuation Fleet Configuration | Dubai private hospital networks contracting dedicated air ambulance platforms open premium equipment specification segment. |
| NextGen Avionics Retrofit Program | GCAA mandates on required navigation performance accelerate replacement demand for legacy aircraft lacking precision approach capability. |
Research Methodology
GCAA regulatory filings, Saudi GACA airworthiness directives, and OEM delivery disclosures formed the secondary backbone for this assessment. Primary interviews with flight department managers, FBO operations directors, charter brokerage heads, and sovereign aviation authority officials combined with secondary validation across customs records and airport authority infrastructure announcements. Bottom-up fleet inventory analysis triangulated against top-down sovereign wealth fund capital deployment tracking.
Bottom-up modeling anchored projections across the analysis window. Segmentation dimensions included aircraft weight class, mission profile, ownership structure, and regulatory compliance tier. CAGRs derived from airframe delivery pipeline analysis and retirement curve modeling for legacy fleets. Forecast inputs incorporated GCAA NextGen avionics mandate timelines and Saudi GACA accelerated inspection interval impacts on replacement cycles.
The model holds under stable regulatory compliance cost trajectories; deviation in sovereign aviation authority alignment with ICAO carbon offsetting thresholds would shift fleet economics and resale value assumptions. Material deviation in SAFA enforcement intensity or sustainable aviation fuel infrastructure deployment timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airplane Landing Gear Market
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Europe Attack Helicopter Market
Aircraft
US Military Aviation Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Wind Tunnel Market
Aircraft
Afterburner Market
Aircraft
Europe General Aviation Market
Aircraft
Australia Aviation Market
Aircraft
Sailplane Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Aircraft Fairings Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Air Speed Indicator Market
Aircraft
Docking System Market