
 Commercial Air Fryer Market | 2026-2036
Commercial Air Fryer Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Air Fryer Market Outlook
Chinese OEM capacity for commercial kitchen equipment is recalibrating regional supply dynamics as manufacturers expand dedicated production lines for foodservice-grade air frying systems. Koninklijke Philips N.V. leverages its European R&D infrastructure to sustain premium positioning in countertop units for European cafe chains. Groupe SEB anchors its competitive stance through deep manufacturing scale in France and controlled distribution across Western European hospitality channels. SharkNinja Operating LLC differentiates via aggressive channel control in North American foodservice supply chains.
A commercial air fryer is a foodservice-grade electric cooking appliance that circulates superheated air between 150°C and 200°C through a compact chamber to produce crisped exteriors without submersion in oil, designed for continuous-duty cycles in professional kitchens. The equipment serves quick-service restaurants, catering operations, and mobile food vendors seeking throughput consistency with reduced fat content and elimination of fryer-oil handling costs. Countertop air fryers dominate current foodservice procurement volumes due to low capital outlay and flexible placement, while commercial air frying systems capture expanding margin pools in centralized ghost kitchen installations requiring batch consistency at scale. Oven air fryers occupy a maturing niche among full-service restaurants retrofitting existing convection lines, though rapid air technology leads new equipment specifications for speed-focused operators.
The FDA's Food Code provisions on commercial cooking equipment sanitation directly shape product design requirements and certification pathways for manufacturers targeting United States foodservice deployment. CE marking under EU appliance safety directives governs access to European hospitality procurement channels, with additional layer requirements from EFSA guidance on acrylamide reduction in heated food processing. China's SAMR enforces GB standards for commercial electrical kitchen equipment that determine factory audit outcomes for OEM exporters. Stakeholders must monitor divergence between regional efficiency mandates and emerging food safety protocols as equipment specifications fragment across major procurement jurisdictions.
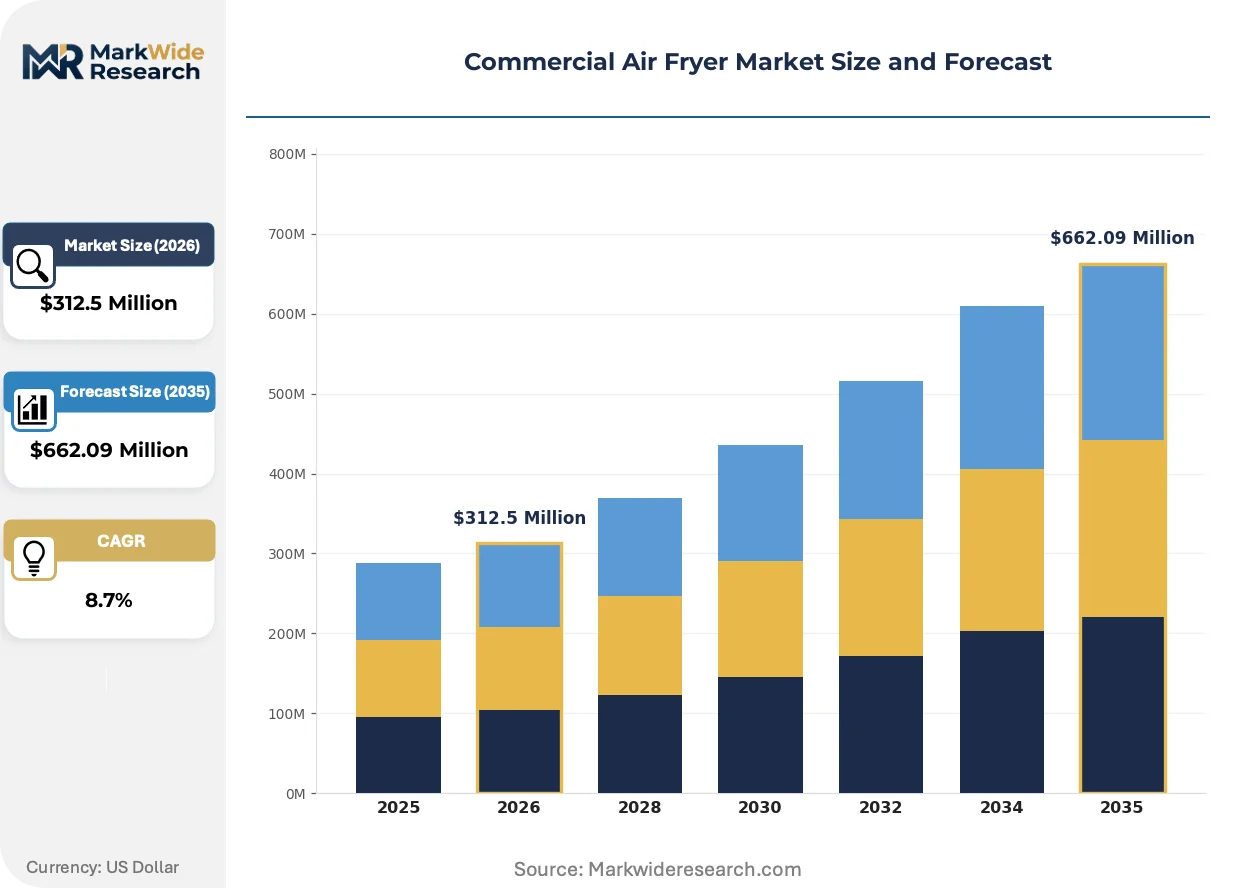
Market Dynamics
Centralized ghost kitchen installations are compressing procurement cycles for batch-consistent equipment, forcing manufacturers to engineer for throughput density rather than countertop flexibility alone.
Growth Catalysts
- Acrylamide reduction mandates:EFSA guidance on heated food processing is accelerating specifications for oil-free cooking platforms across European hospitality procurement channels.
- Quick-service restaurant expansion:United States QSR chains are retrofitting kitchen footprints with high-throughput air frying systems to eliminate fryer-oil handling costs.
- Coastal manufacturing clusters:China's Jiangsu and Zhejiang provinces have scaled dedicated production lines for foodservice-grade air frying equipment, shortening OEM lead times for export markets.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 sheet metal pricing swings compress margin stability for continuous-duty chamber fabrication.
- Regional certification fragmentation:Divergent FDA Food Code sanitation requirements, CE marking appliance safety directives, and China's GB standards force redundant testing protocols.
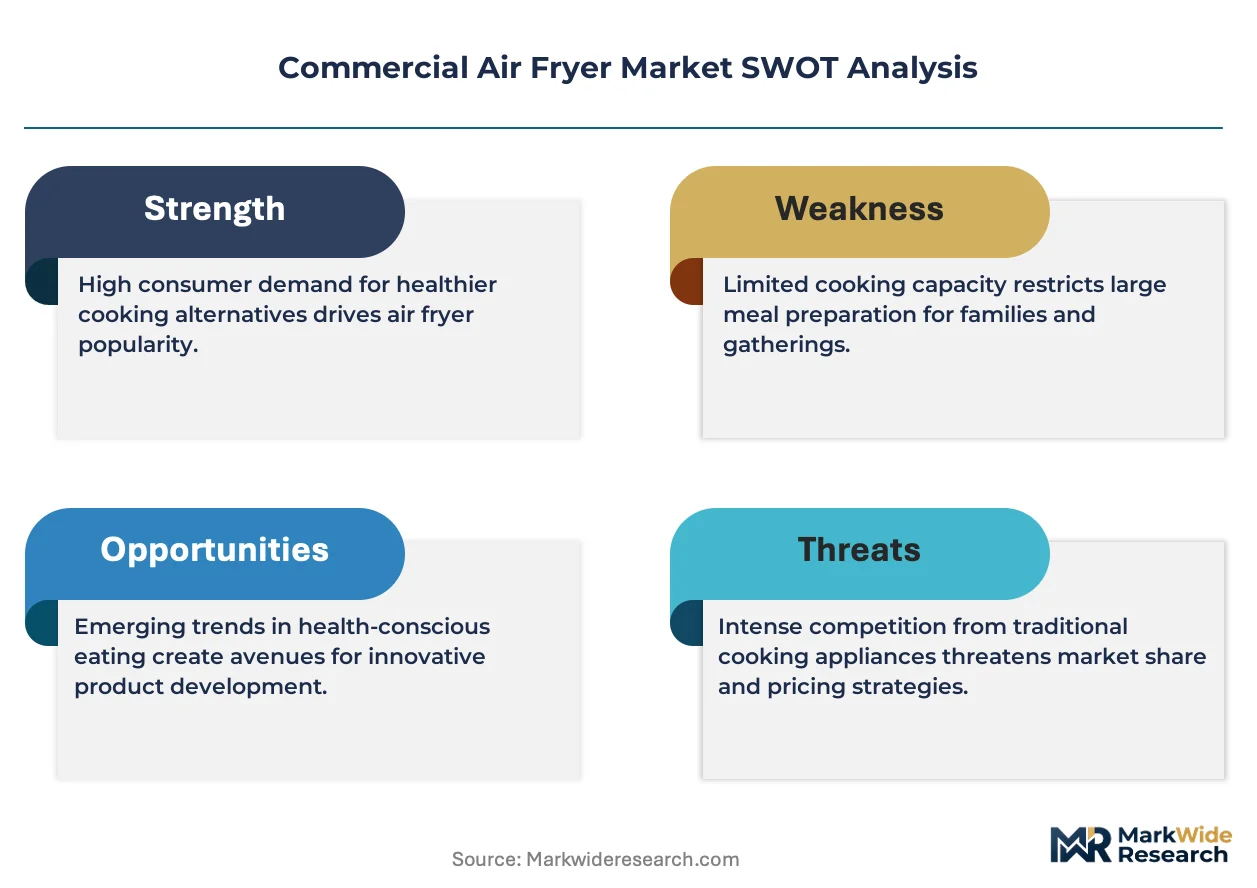
- Convection oven substitution:Full-service restaurants with existing convection infrastructure face low switching incentives for dedicated air frying units.
Strategic Opportunities
- Ghost kitchen centralization:Third-party delivery fulfillment centers in urban United States corridors present untapped demand for batch-consistent equipment at scale.
- Energy efficiency incentives:The EU Green Deal's commercial kitchen equipment efficiency targets create procurement tailwinds for oil-free cooking platforms.
- Mobile food vendor channel:Compact countertop units are penetrating food truck and festival catering operations previously served by propane fryers.
Industry Challenges
- Cross-functional engineering talent scarcity:Manufacturers struggle to recruit thermal dynamics specialists with simultaneous food safety compliance expertise.
- Multi-jurisdiction certification timelines:Simultaneous FDA, CE, and SAMR approval processes extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Air Fryer Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Air Fryer, Oven Air Fryer, Commercial Air Frying System, High-Pressure Air Fryer End User: Restaurants, Cafes, Catering Services, Food Trucks Capacity: Small Capacity, Medium Capacity, Large Capacity, Extra Large Capacity Technology: Rapid Air Technology, Convection Technology, Infrared Technology, Induction Technology |
| Companies Covered | Koninklijke Philips N.V., Stanley Black & Decker, Inc., Breville Group Limited, Groupe SEB, SharkNinja Operating LLC, Cuisinart Corporation, Meyer Manufacturing Company Limited, GoWISE USA, NuWave, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Air Fryer Market Strategic Shifts
Rapid air circulation engineering is bifurcating equipment design philosophies between speed-optimized ghost kitchen systems and precision-controlled premium countertop units.
Impeller-driven rapid air technology is expanding into commercial kitchen specifications previously dominated by impingement ovens. Ghost kitchen operators in the United States are specifying these systems for 90-second cycle targets on protein batches. The technology is expanding into margin pools that convection equipment previously captured in centralized production environments.
China's SAMR enforcement of revised GB standards for commercial electrical kitchen equipment is compressing factory audit timelines for OEM exporters. Manufacturers must now document thermal cycling durability under continuous-duty protocols. European importers are responding by pre-qualifying production lines in Jiangsu province before contract finalization.
Foodservice procurement teams are consolidating vendor relationships around equipment suppliers offering bundled sanitation certification support. Independent distributors are losing share to manufacturer-direct channels with embedded compliance documentation. This consolidation is most visible in United States QSR chains negotiating enterprise-wide equipment standards across franchise networks.
Commercial Air Fryer Market Segmentation
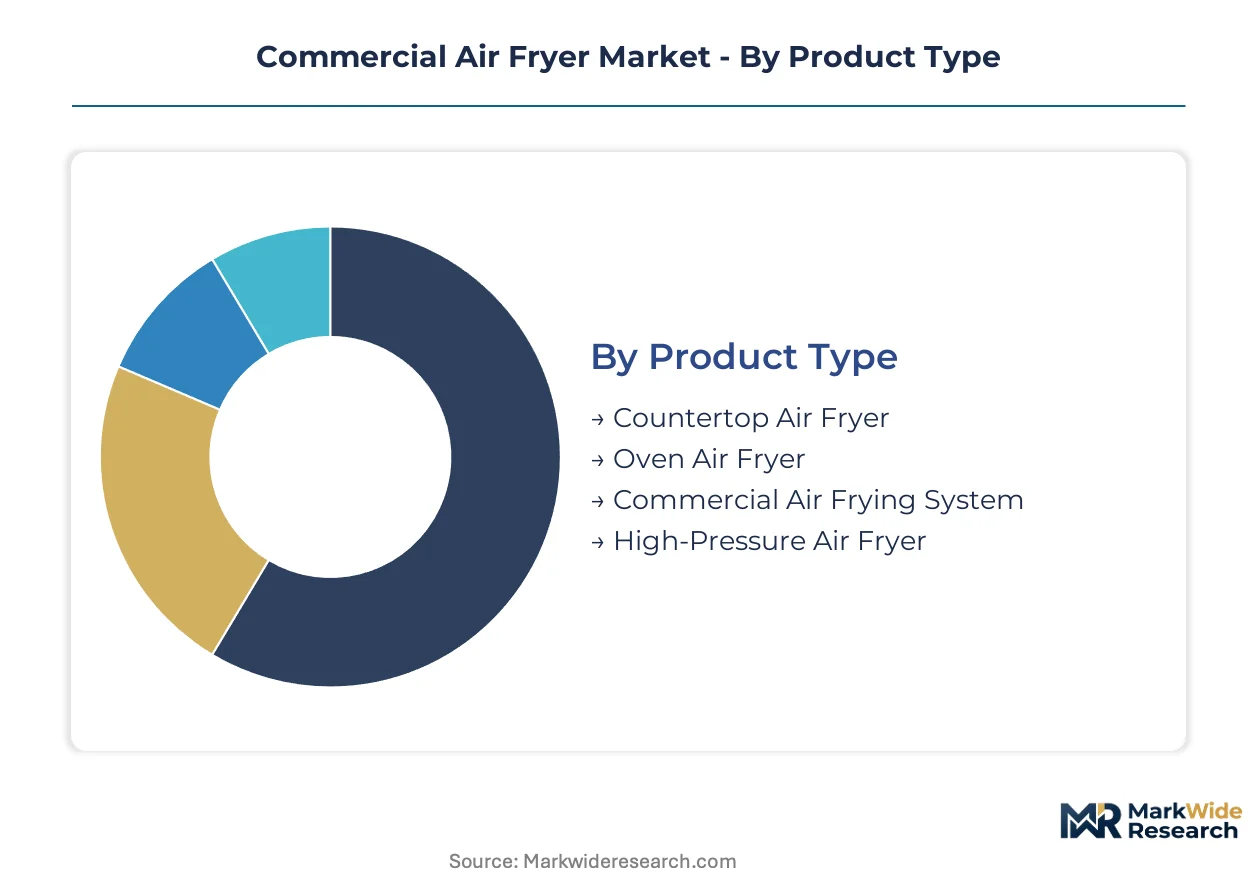
Equipment procurement patterns in commercial air frying diverge sharply across installation constraints, throughput requirements, and thermal engineering specifications. Kitchen operators select configurations based on capital deployment flexibility, batch volume targets, and integration with existing ventilation infrastructure.
Product Type:
Upgrade cycles accelerate where countertop flexibility conflicts with ghost kitchen throughput demands, forcing operators to reassess equipment portfolios.
- Countertop Air Fryer:Compact electric units deploy on existing surfaces without ducting modifications. Quick-service restaurants in the United States favor these for franchise rollout speed despite throughput ceiling constraints.
- Commercial Air Frying System:Integrated rack-based configurations process 50+ protein portions per cycle for centralized fulfillment centers. Ghost kitchen operators in urban United States corridors specify these for batch consistency at scale.
- Oven Air Fryer:Full-size convection retrofits serve full-service restaurants with existing hood infrastructure.
- High-Pressure Air Fryer:Pressurized chamber designs accelerate protein cooking cycles for high-volume catering operations.
Volume placements concentrate in Countertop Air Fryer; the faster expansion belongs to Commercial Air Frying System.
End User:
Customer procurement authority varies from centralized franchise equipment committees to independent owner-operators with spot purchasing discretion.
- Restaurants:Full-service and limited-service establishments drive specifications for NSF-certified continuous-duty cycles. United States QSR chains negotiate enterprise-wide equipment standards across franchise networks to eliminate fryer-oil handling costs.
- Food Trucks:Mobile operators demand compact footprint units with generator-compatible power draws. Festival catering operations in coastal United States markets are displacing propane fryers with electric air frying platforms.
- Cafes:European cafe chains prioritize countertop precision for premium menu positioning.
- Catering Services:Event-focused operators specify medium-batch equipment for off-premise production.
Procurement volume clusters with Restaurants; Food Trucks are gaining share fastest among end-user categories.
Capacity:
Batch size selection tracks kitchen square footage, peak hour demand curves, and menu complexity rather than simple headcount metrics.
- Medium Capacity:10-20 liter chambers balance throughput and footprint for independent restaurants. China's Jiangsu province OEMs have scaled dedicated production lines for this specification tier serving export markets.
- Large Capacity:30-50 liter configurations serve centralized ghost kitchens with 200+ daily batch cycles. United States third-party delivery fulfillment centers specify these for protein consistency across multi-brand operations.
- Small Capacity:Under 10 liter units target mobile vendors and micro-kitchens.
- Extra Large Capacity:60+ liter systems serve institutional catering and stadium concessions.
Medium Capacity dominates current procurement volumes; Large Capacity shows the steepest expansion trajectory.
Technology:
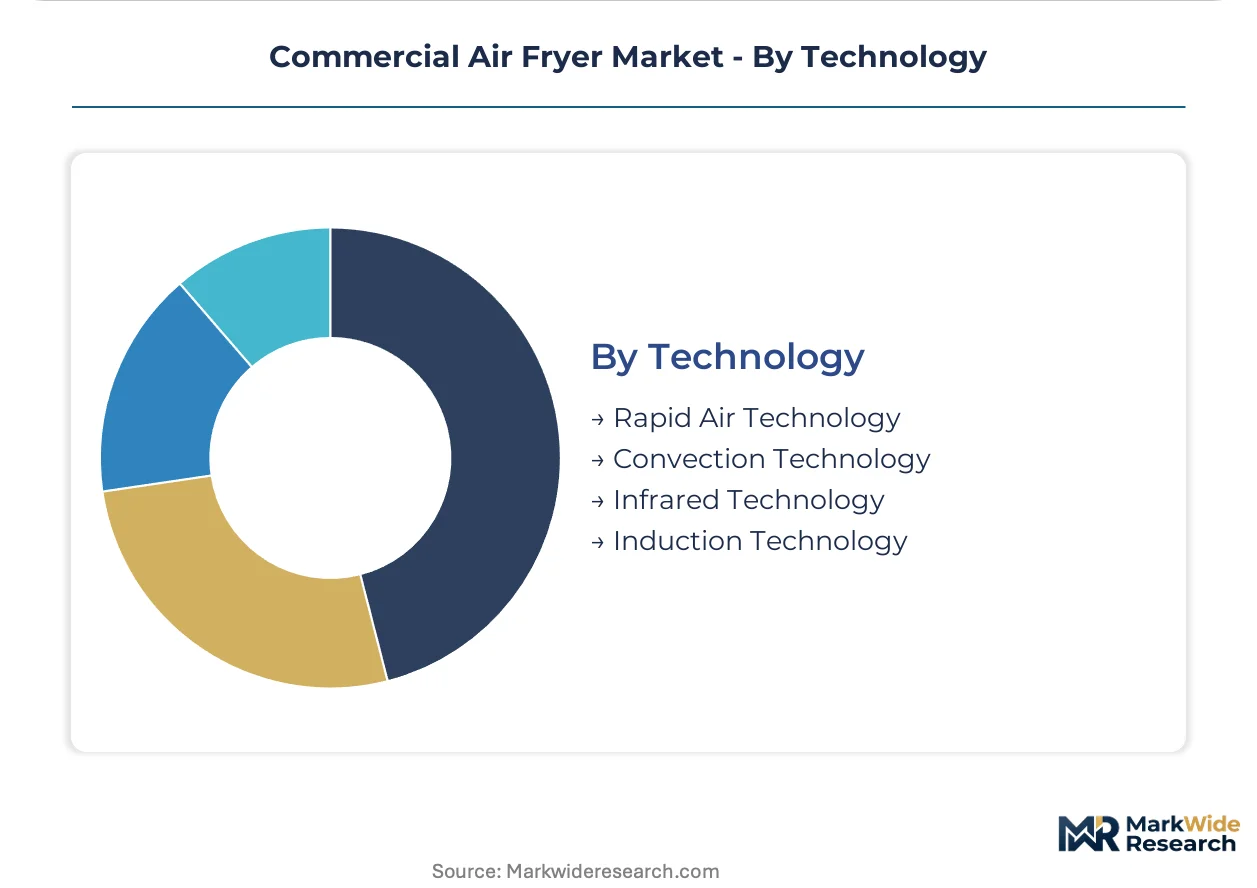
Thermal engineering selection determines energy efficiency certification eligibility, cycle speed targets, and acrylamide reduction compliance.
- Rapid Air Technology:Impeller-driven systems circulate superheated air at 150°C-200°C through compact chambers. EFSA guidance on acrylamide reduction in heated food processing is accelerating specifications for these oil-free platforms across European hospitality procurement channels.
- Convection Technology:Fan-assisted heat distribution occupies maturing niche among full-service restaurants retrofitting existing equipment lines. United States operators with sunk capital in convection infrastructure face low switching incentives for dedicated air frying units.
- Infrared Technology:Radiant heat elements target surface crisping for premium protein applications.
- Induction Technology:Electromagnetic heating coils enable precise temperature control for pastry and delicate items.
Rapid Air Technology captures the dominant procurement share; Infrared Technology is climbing the fastest among emerging specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel sheet production in China's Jiangsu province anchors manufacturing capacity for commercial air fryer chambers, with coastal foundries supplying Grade 304 and 316 inputs to OEM fabricators across three continents.
United States
Quick-service restaurant chains are retrofitting kitchen footprints with high-throughput air frying systems to eliminate fryer-oil handling costs. The FDA's Food Code provisions on commercial cooking equipment sanitation shape product design requirements for foodservice deployment. Ghost kitchen operators in urban corridors specify batch-consistent equipment for third-party delivery fulfillment centers.
China
Jiangsu and Zhejiang provinces have scaled dedicated production lines for foodservice-grade air frying equipment, shortening OEM lead times for export markets. SAMR enforces revised GB standards for commercial electrical kitchen equipment, compressing factory audit timelines for exporters. Coastal manufacturing clusters in the Yangtze River Delta recalibrate regional supply dynamics as capacity expands.
Germany
Full-service restaurants with existing convection infrastructure face low switching incentives for dedicated air frying units, though energy efficiency targets create procurement tailwinds. The EU Green Deal's commercial kitchen equipment efficiency standards favor oil-free cooking platforms. Industrial fabricators in Baden-Württemberg supply precision thermal components to European OEMs.
France
European cafe chains prioritize countertop precision units for premium menu positioning in hospitality channels. EFSA guidance on acrylamide reduction in heated food processing accelerates specifications for oil-free platforms. Manufacturing scale in domestic production facilities anchors competitive positioning across Western European procurement networks.
Japan
Compact countertop units penetrate food truck and festival catering operations with generator-compatible power draws. METI efficiency standards for commercial electrical appliances influence product development priorities for export-oriented manufacturers. Thermal engineering specialists in the Chubu region develop rapid air circulation systems for precision-controlled applications.
Commercial Air Fryer Market Competitive Environment
Global majors compete with regional champions across certification pathways and distribution channel control. The vendor base stratifies between European R&D-intensive premium specialists, Asian OEM scale players, and North American channel-dominant operators. Three archetypes define competitive positioning: thermal engineering specialists with deep appliance heritage, contract manufacturing platforms with coastal China production assets, and brand-led distributors with embedded foodservice relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers seek to compress multi-jurisdiction certification timelines.
Within the premium-tier vector, Koninklijke Philips N.V. and Groupe SEB occupy positions anchored by European R&D infrastructure and controlled hospitality distribution. SharkNinja Operating LLC exemplifies the North American channel-control archetype with aggressive positioning in foodservice supply chains. These three named entities represent distinct strategic approaches to market development without overlapping geographic or segment focus.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Stanley Black & Decker, Inc. |
| Breville Group Limited |
| Groupe SEB |
| SharkNinja Operating LLC |
| Cuisinart Corporation |
| Meyer Manufacturing Company Limited |
| GoWISE USA |
| NuWave, LLC |
| Others |
Value Chain & Pricing Dynamics
Thermal engineering specialists concentrated in China's Jiangsu province command wage premiums that compress margin spreads between economy-grade countertop units and premium commercial air frying systems. Labor-cost differentials between coastal OEM clusters and European fabrication sites widen pricing-tier spreads as certification-intensive buyers absorb service-bundled premiums.
Pricing Analysis
Warranty and multi-year service contracts differentiate premium-tier offerings from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales coverage depth. Cost compression in economy tiers intensifies because stainless steel input volatility squeezes chamber fabrication margins. Food truck operators exhibit highest price sensitivity, while ghost kitchen procurement committees prioritize batch consistency over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from United States QSR chains force OEMs to qualify redundant production lines across Jiangsu and Zhejiang provinces. Supply draws from China for stainless steel sheet metal, Germany for precision thermal components, and France for control systems. Single-source vulnerability concentrates in Grade 304 and 316 sheet metal supply from coastal Chinese foundries. Distribution runs through manufacturer-direct channels with embedded compliance documentation, displacing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial air frying equipment sits in a technology-transition phase as rapid air circulation engineering displaces legacy convection infrastructure in ghost kitchen deployments. Impeller-driven systems are capturing margin pools that thermal-static equipment previously held.
For Market Incumbents: Deepen backward integration into stainless steel sheet supply to defend against Grade 304 pricing volatility. Expand dedicated production lines in Jiangsu province to compress SAMR audit timelines. Incumbent manufacturers must anchor channel control through bundled sanitation certification support as independent distributors lose procurement influence.
For New Entrants and Emerging Players: Infrared-enabled precision units offer a technology-first wedge into European cafe chain procurement where premium menu positioning commands price premiums. Target mobile food vendor channels in coastal United States markets where propane fryer displacement accelerates. Pursue direct-to-operator digital sales with generator-compatibility specifications as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with thermal engineering specialists holding simultaneous FDA and CE certification pathways given accelerating multi-jurisdiction compliance requirements. Long-term viability favors manufacturers with captive R&D infrastructure rather than contract assembly platforms. Watch EFSA acrylamide guidance enforcement intensity as the inflection indicator for European hospitality procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, CE, and SAMR pathways compress product launch windows by 8-14 months. |
| Backward Integration into Stainless Steel Supply | Captive Grade 304 and 316 sheet sourcing insulates margin stability from commodity volatility. |
| Ghost Kitchen Channel Partnership | United States third-party delivery fulfillment centers specify batch-consistent equipment at scale. |
| Rapid Air Technology R&D Expansion | Impeller-driven systems capture 90-second cycle specifications from speed-focused operators. |
| Mobile Vendor Distribution Network | Compact countertop units penetrate food truck operations previously served by propane fryers. |
Study Parameters
Trade databases, commercial kitchen equipment registries, and regulatory filing repositories formed the secondary backbone of this analysis. Primary interviews with ghost kitchen operators, QSR franchise equipment committees, food truck owner-operators, and thermal engineering specialists at OEMs combined with secondary validation. Bottom-up and top-down triangulation cross-checked procurement volume estimates against production capacity disclosures from Jiangsu and Zhejiang manufacturing clusters.
Bottom-up modeling aggregated segment-level equipment shipments across product type, end user, capacity tier, and thermal technology specifications. Top-down validation referenced macro-level foodservice capital expenditure patterns and regulatory compliance cost burdens. CAGRs derived from equipment replacement cycle analysis and ghost kitchen installation trajectories across the projection horizon. Energy efficiency incentive uptake under EU Green Deal frameworks and FDA Food Code enforcement intensity served as scenario-weighting inputs.
Several conditions sit outside the modeled scope, including black-swan commodity price spikes, abrupt regulatory harmonization between FDA and SAMR standards, and technology substitution by microwave-assisted air frying platforms. Forecasts reflect documented assumptions about stainless steel input stability and certification timeline continuity. Deviation in EFSA acrylamide reduction mandate enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Steam Tables and Food Well Market
Food Service
Sandwich Toasters Market
Food Service
Global Food Retail Market
Food Service
South Korea Foodservice Market
Food Service
West Africa Food Services Market
Food Service
Beverage Napkins Market
Food Service
United States Cafes & Bars Market
Food Service
Europe Barbeque Grill Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Turkey Food Service Market
Food Service
Europe Airline Catering Services Market
Food Service
Japan Foodservice Market
Food Service
Commercial Charbroiler Market
Food Service
Food Contract Manufacturing Market
Food Service
Commercial Rice Cooker Market
Food Service
Restaurants in Belgium Market