
 Commercial Rice Cooker Market | 2026-2036
Commercial Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Rice Cooker Market Insights
Buyer concentration in the restaurant sector is consolidating as multi-unit chains and ghost kitchen operators centralize equipment procurement through national supply agreements. Zojirushi Corporation leverages its microprocessor-controlled technology platform to anchor premium positioning in Japanese and North American commercial channels. Panasonic Corporation competes through manufacturing scale across Southeast Asian production bases, while Tiger Corporation differentiates via specialized gas-heating systems for traditional restaurant formats.
A commercial rice cooker is an electrically or gas-powered appliance designed to heat, cook, and maintain rice at serving temperature through thermostatic control, with capacities ranging from five liters to over thirty liters for high-volume foodservice operations. Units employ either resistive heating elements, induction coils, or direct flame burners to achieve precise temperature curves that gelatinize starch without scorching. Electric models dominate current volume owing to lower installation barriers, though induction variants capture expanding share where kitchen operators prioritize energy efficiency and rapid recovery cycles. Programmable technology segments attract premium pricing from hotels and institutional buyers seeking automated workflow integration, while manual units sustain volume in cost-sensitive catering markets.
The US FDA's Food Code provisions on time-temperature control and China's GB standards for commercial kitchen appliance safety shape baseline product requirements across major supply corridors. Japan's METI enforces Top Runner energy efficiency standards that push manufacturers toward induction and sensor-based architectures. Stakeholders must monitor how evolving efficiency benchmarks in East Asia migrate into procurement specifications for Western foodservice distributors.
Market Dynamics
Induction heating technology is compressing replacement cycles across Asia-Pacific commercial kitchens as energy-efficiency mandates from China's MIIT force specification upgrades at multi-unit restaurant chains.
Growth Catalysts
- Cloud kitchen proliferation:Ghost kitchen operators in metropolitan China and Japan are centralizing procurement of high-capacity electric units through national supply agreements.
- MIIT efficiency mandates:China's Ministry of Industry and Information Technology standards are accelerating induction cooker adoption in commercial foodservice operations.
- Resistive-to-induction conversion:Restaurant operators are replacing aging resistive heating platforms with coil-based architectures to reduce energy expenditure.
Market Restraints
- Induction coil supply concentration:Specialized copper winding and ferrite core production clusters heavily in East Asian component hubs, creating input bottlenecks.
- Installation infrastructure costs:Three-phase electrical requirements for high-wattage induction units impose retrofit expenses on older kitchen facilities.
- Gas-heating substitution resilience:Traditional restaurant formats in Japan and South Korea retain installed base of direct-flame burners due to familiar thermostatic control.
Strategic Opportunities
- India commercial kitchen modernization:Foodservice infrastructure investment in Mumbai, Bangalore, and Delhi NCR creates first-mover positioning for programmable electric platforms.
- Sensor-thermostat convergence:Microprocessor-controlled temperature curves combined with IoT connectivity enable predictive maintenance offerings for hotel chains.
- US FDA Food Code alignment:Time-temperature control provisions create specification pull for automated holding functions in North American institutional catering.
Industry Challenges
- Induction technician scarcity:Field service networks lack sufficient trained personnel for coil diagnostics and inverter board repair in distributed restaurant footprints.
- Multi-certification timelines:Simultaneous GB standards compliance for China, METI Top Runner for Japan, and CE marking for European export extends product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Rice Cooker Market |
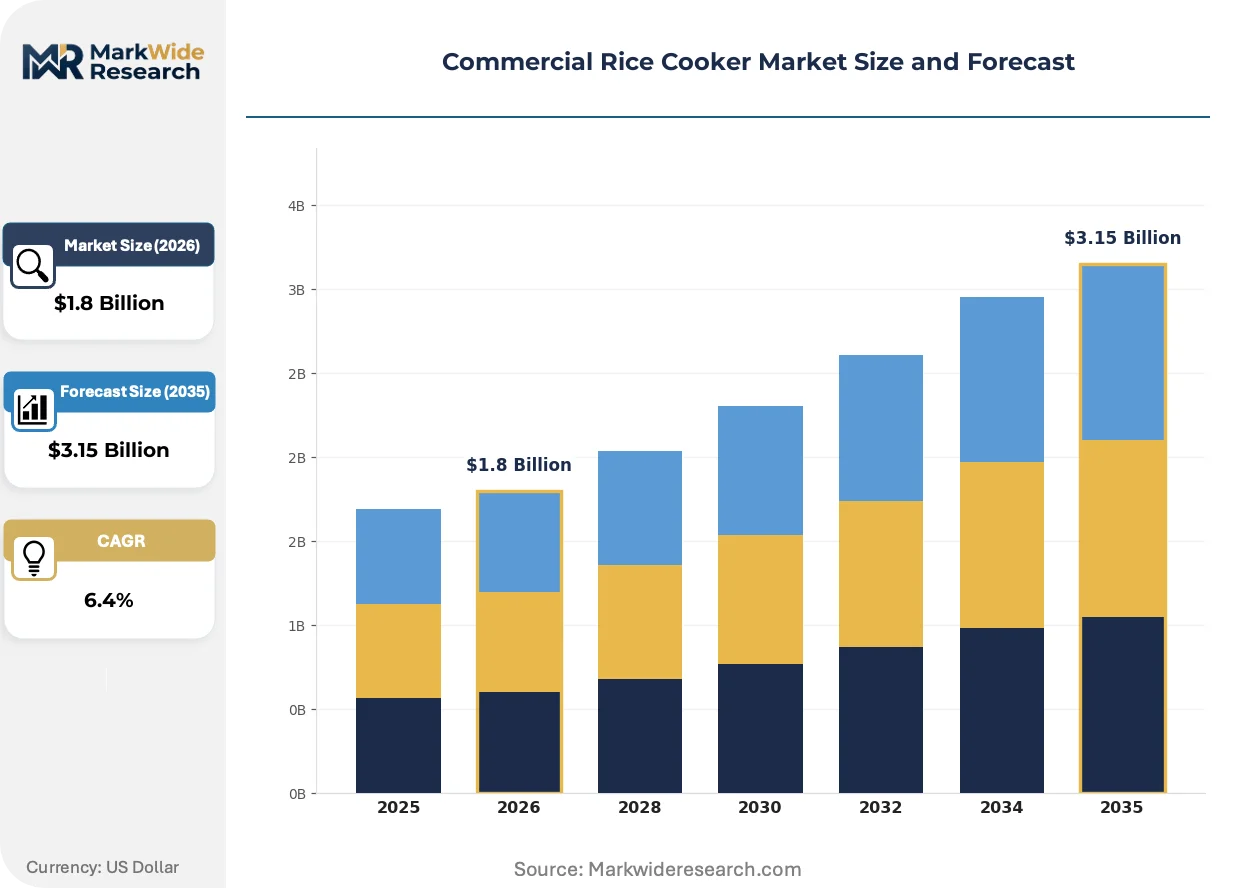
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Induction, Combination End User: Restaurants, Hotels, Catering Services, Institutions Capacity: 5-10 Liters, 11-20 Liters, 21-30 Liters, 31+ Liters Technology: Microprocessor-Controlled, Programmable, Manual, Sensor-Based |
| Companies Covered | Zojirushi Corporation, Panasonic Corporation, Tiger Corporation, Toshiba Corporation, Cuckoo Electronics Co., Ltd., Aroma Housewares, Town Food Service Equipment Co., Inc., Hamilton Beach Brands, Inc., Admiral Craft Equipment Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Rice Cooker Market Trends and Innovations
Commercial rice cooker architecture is bifurcating between premium sensor-driven platforms and stripped-down manual units as buyer sophistication polarizes across chain and independent segments.
Induction coil heating is electrifying temperature precision in high-volume operations. The technology replaces resistive elements with magnetic field excitation for faster recovery between cooking cycles. Full-service hotel chains in Japan are adopting these platforms aggressively. This shift is electrifying competitive positioning around energy metrics rather than capacity alone.
Japan's METI Top Runner program is tightening efficiency benchmarks for commercial kitchen equipment annually. Manufacturers must demonstrate measurable reductions in standby power and cooking-phase consumption to maintain market access. Premium programmable segments face the steepest compliance thresholds, compressing development cycles for sensor-integrated architectures.
Centralized procurement through ghost kitchen operators is fragmenting traditional distributor relationships. Multi-unit cloud kitchen brands are negotiating direct manufacturer contracts that bypass regional equipment dealers. This pattern is most visible in Shanghai, Seoul, and Singapore where virtual restaurant density concentrates buying power.
Commercial Rice Cooker Market Segmentation
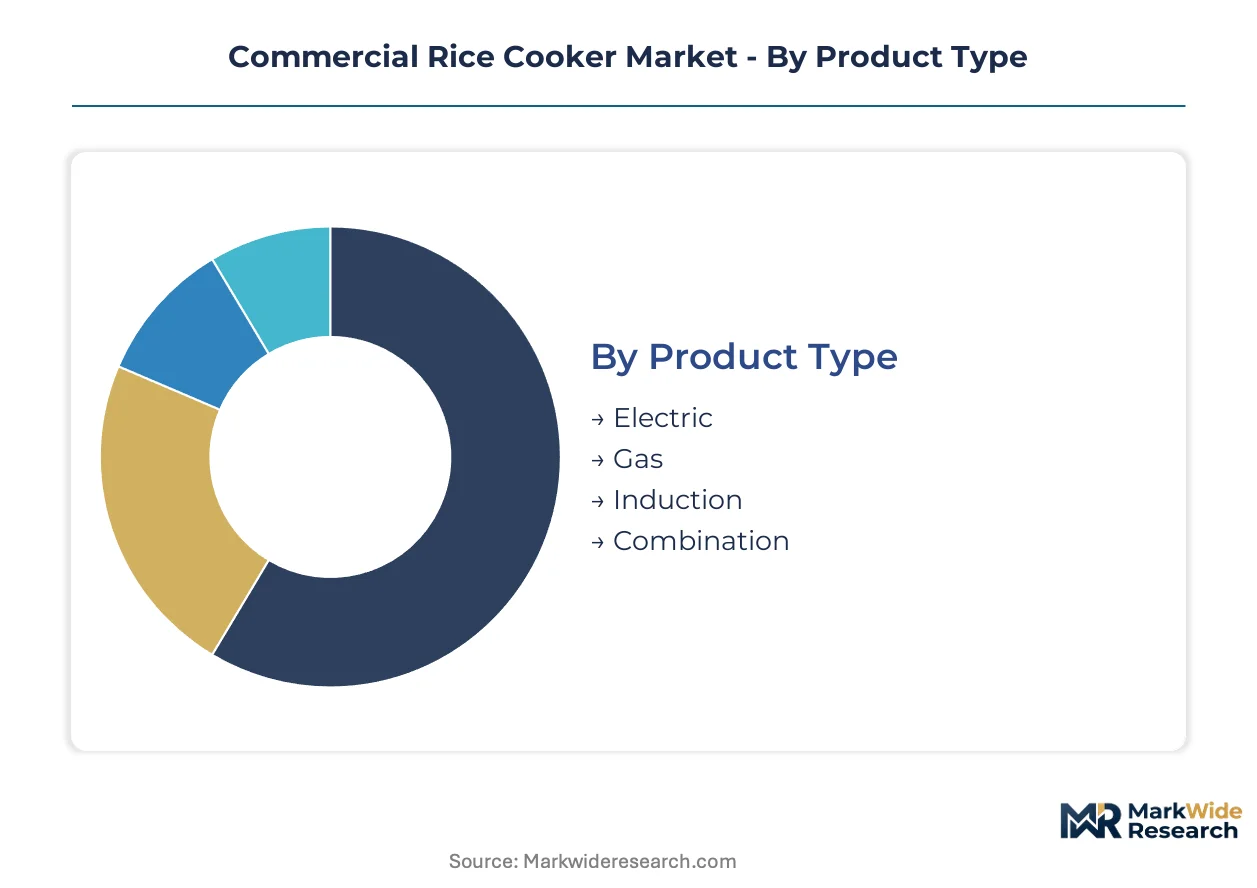
Commercial rice cooker procurement patterns diverge sharply across operational contexts, with heating platform selection and capacity tier directly determining replacement timelines and energy compliance exposure. Kitchen operators segment equipment investments by volume throughput, regulatory jurisdiction, and integration complexity with existing infrastructure.
Product Type:
Replacement cycles accelerate where efficiency mandates collide with aging resistive-element installed bases, forcing operators to reassess heating architecture against total cost of ownership.
- Electric:Resistive-element platforms dominate current volume through lower acquisition cost and single-phase installation compatibility. Chain restaurants in Japan and South Korea are retiring these units ahead of regulatory deadlines, compressing replacement windows from ten-year cycles to five-to-seven-year intervals.
- Induction:Magnetic field excitation delivers precise temperature curves and rapid recovery between cooking cycles. China's MIIT efficiency standards are mandating coil-based architectures at multi-unit foodservice operations in Shanghai, Beijing, and Guangzhou, with procurement concentrating through national supply agreements.
- Gas:Direct-flame burners sustain installed base in traditional Japanese and South Korean restaurant formats where chefs prioritize familiar thermostatic control and existing ventilation infrastructure.
- Combination:Hybrid platforms integrate electric holding with gas or induction cooking phases, serving institutional buyers seeking operational redundancy across high-volume catering contracts.
Volume placements concentrate in Electric; the faster expansion belongs to Induction.
End User:
Buyer sophistication and procurement centralization vary dramatically across foodservice formats, with cloud kitchen operators rewriting traditional distributor relationships.
- Restaurants:Full-service and quick-service chains anchor demand through standardized equipment specifications across multi-unit footprints. Ghost kitchen operators in metropolitan China and Japan are consolidating procurement through direct manufacturer contracts that bypass regional dealers.
- Hotels:Premium properties demand programmable platforms with automated workflow integration and IoT-enabled predictive maintenance capabilities.
- Catering Services:Cost-sensitive volume buyers sustain manual unit demand where labor substitution outweighs technology investment.
- Institutions:School and hospital foodservice operations prioritize capacity scale and holding temperature stability under US FDA Food Code time-temperature control provisions.
Restaurants capture the largest equipment placements; Institutions are climbing the fastest as healthcare and education infrastructure investment accelerates.
Capacity:
Throughput requirements and kitchen footprint constraints segment the market across liter-tier boundaries that align with peak service hour demand curves.
- 5-10 Liters:Compact units serve independent restaurants and satellite kitchen operations with limited production volume and space constraints.
- 11-20 Liters:Mid-capacity platforms balance throughput flexibility with equipment mobility, dominating cloud kitchen installations where menu breadth varies across virtual brands.
- 21-30 Liters:High-volume electric and induction configurations anchor central kitchen operations at hotel chains and institutional caterers in Japan and South Korea.
- 31+ Liters:Industrial-scale units with specialized three-phase electrical requirements serve stadium catering, airline commissaries, and centralized production facilities where batch consistency at volume overrides energy efficiency priorities.
11-20 Liter configurations lead current procurement volume; 31+ Liter systems are gaining share fastest as centralized production models expand across Asia-Pacific metropolitan clusters.
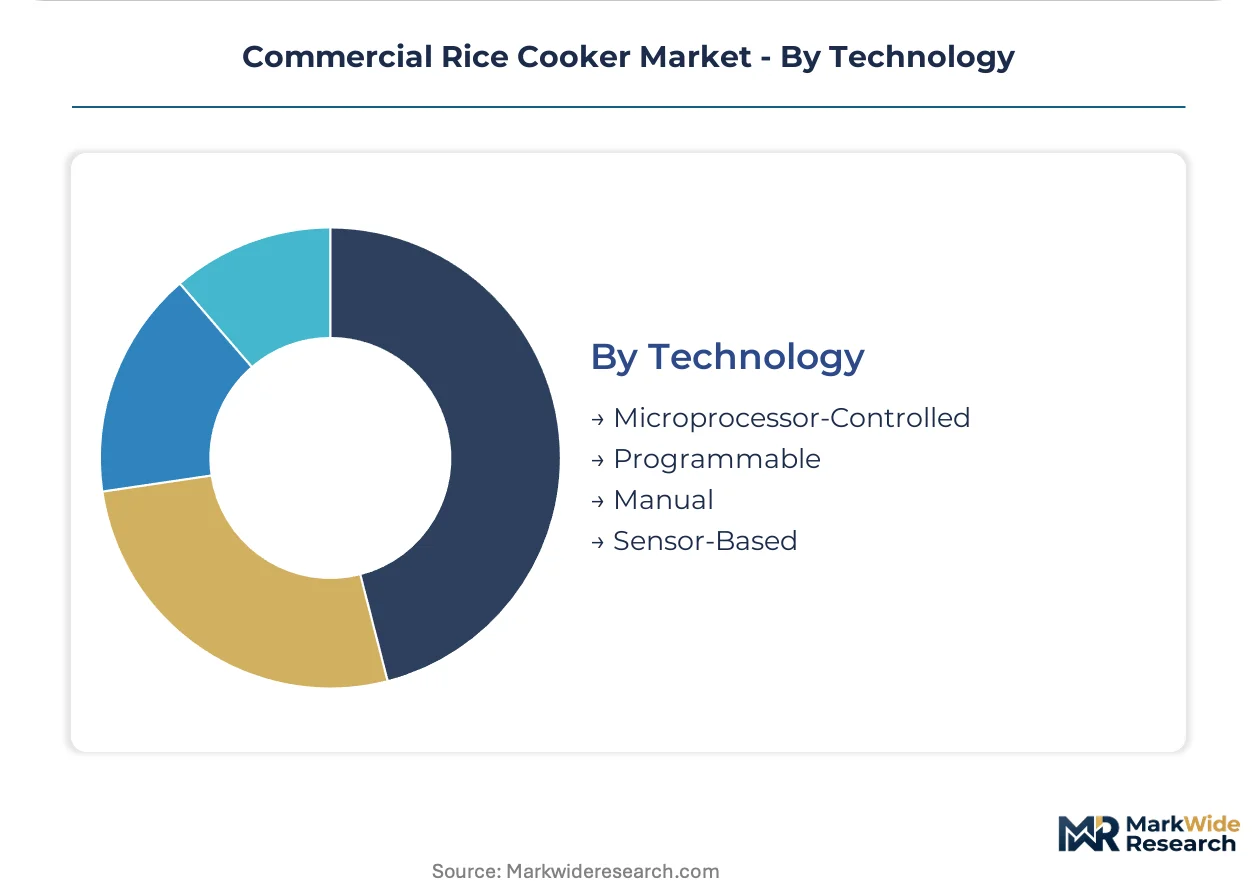
Technology:
Control architecture sophistication determines pricing tier and regulatory compliance trajectory, with sensor integration and connectivity features separating premium from commodity positioning.
- Microprocessor-Controlled:Digital temperature management with programmable cooking curves commands premium positioning in Japanese and North American commercial channels. Zojirushi Corporation anchors this segment through proprietary algorithm development.
- Programmable:Automated workflow integration with multi-stage cooking and holding sequences attracts hotel chains seeking labor efficiency and consistency documentation for quality audits.
- Manual:Basic thermostatic control sustains volume in cost-sensitive independent restaurants and catering markets where capital constraints limit technology investment.
- Sensor-Based:Real-time moisture detection and adaptive heating adjustment enable precise starch gelatinization without scorching, aligning with Japan's METI Top Runner efficiency benchmarks for standby power reduction.
Manual platforms retain the broadest installed base; Sensor-Based architectures are expanding most quickly as efficiency mandates tighten across East Asian procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper winding and ferrite core production clusters in East Asian component hubs anchor geographic concentration for commercial rice cooker manufacturing and procurement.
China
MIIT efficiency mandates are accelerating induction cooker adoption at multi-unit foodservice operations in Shanghai, Beijing, and Guangzhou. GB standards for commercial kitchen appliance safety shape baseline product requirements across domestic supply corridors. Procurement concentrates through national supply agreements negotiated directly with ghost kitchen operators in metropolitan clusters.
Japan
METI Top Runner energy efficiency standards push manufacturers toward induction and sensor-based architectures annually. Full-service hotel chains in Tokyo and Osaka adopt premium programmable platforms with automated workflow integration. Zojirushi Corporation anchors premium positioning in commercial channels through proprietary microprocessor-controlled technology.
South Korea
Cloud kitchen proliferation in Seoul and Busan drives centralized procurement of high-capacity electric units. Traditional restaurant formats retain installed base of direct-flame burners due to familiar thermostatic control. Manufacturing scale concentrates in industrial corridors supplying domestic foodservice modernization and export markets.
United States
FDA Food Code provisions on time-temperature control create specification pull for automated holding functions in institutional catering. School and hospital foodservice operations prioritize capacity scale and holding temperature stability. Regional distributor relationships face pressure from direct manufacturer contracts at multi-unit chain accounts.
India
Foodservice infrastructure investment in Mumbai, Bangalore, and Delhi NCR creates first-mover positioning for programmable electric platforms. BIS certification requirements shape product entry timelines for international manufacturers. Cloud kitchen density concentrates procurement decisions among virtual restaurant operators seeking standardized equipment specifications.
Commercial Rice Cooker Market Competitive Landscape
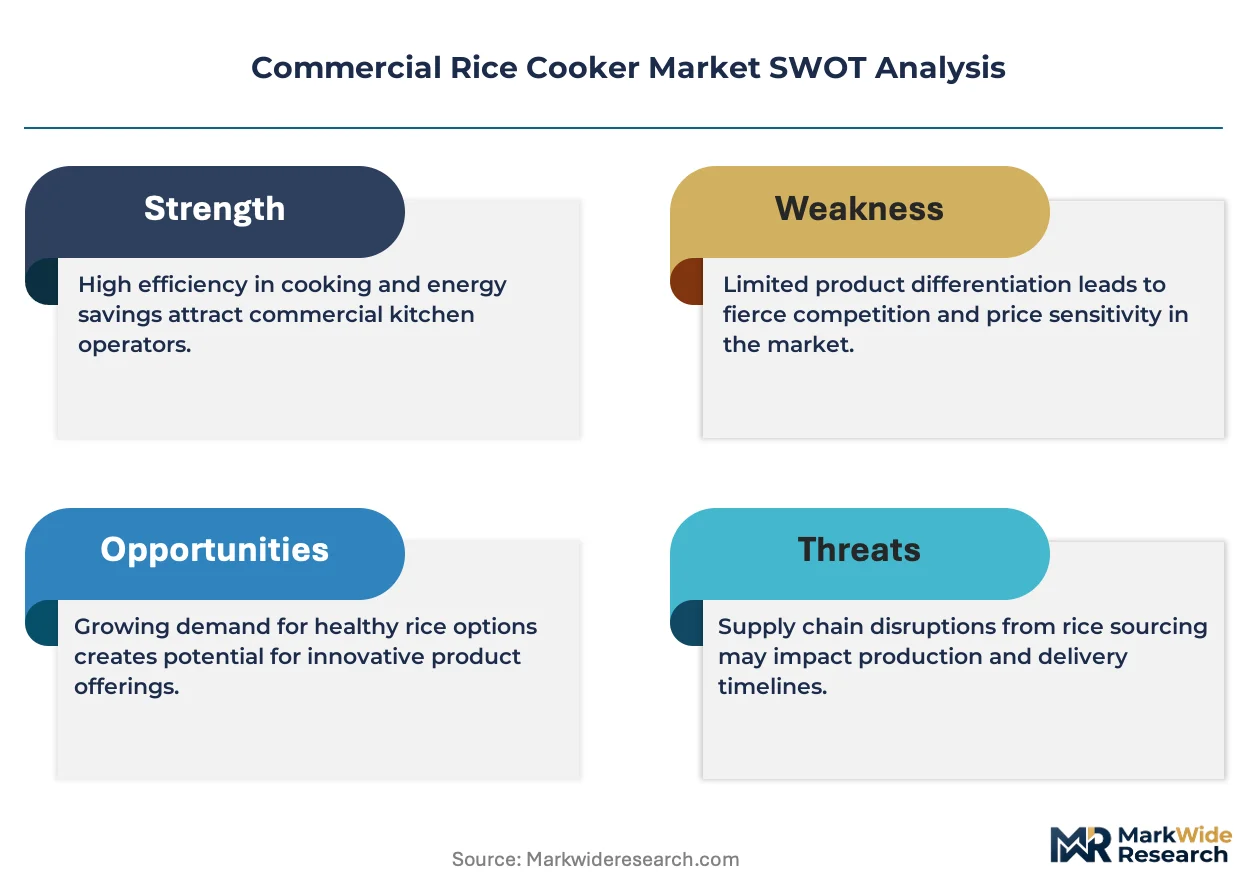
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and IoT-enabled adjacent spaces. The vendor base spans consolidated Japanese electronics conglomerates alongside specialized commercial kitchen equipment fabricators. Three archetypes dominate: technology-anchored premium specialists, scale-driven manufacturing conglomerates, and regional cost-optimized suppliers. Competitive moves concentrate on strategic partnerships with ghost kitchen operators and portfolio diversification into induction architectures.
Among Japanese-based manufacturers, Zojirushi Corporation, Panasonic Corporation, and Tiger Corporation exemplify distinct positioning vectors. Zojirushi Corporation occupies a technology-anchored tier through proprietary algorithm development. Panasonic Corporation represents scale-driven manufacturing across Southeast Asian production bases. Tiger Corporation sits within a specialization archetype focused on gas-heating systems for traditional restaurant formats.
| Leading Market Players |
|---|
| Zojirushi Corporation |
| Panasonic Corporation |
| Tiger Corporation |
| Toshiba Corporation |
| Cuckoo Electronics Co., Ltd. |
| Aroma Housewares |
| Town Food Service Equipment Co., Inc. |
| Hamilton Beach Brands, Inc. |
| Admiral Craft Equipment Corp. |
| Others |
Pricing and Supply Chain Analysis
Copper winding and ferrite core costs cascade through induction cooker pricing tiers, with specialized coil production clustering in East Asian component hubs forcing manufacturers to absorb input volatility or pass through to hotel and chain restaurant buyers.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium programmable platforms from stripped-down manual units in commercial rice cooker procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by sensor integration depth and METI Top Runner certification status. Cost compression in mid-capacity electric segments is intensifying because ghost kitchen operators are consolidating procurement through direct manufacturer contracts. Independent restaurants and catering services exhibit highest price sensitivity, while full-service hotel chains prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
GB standards compliance and METI Top Runner qualification gating filter component suppliers before assembly integration can proceed. Manufacturing concentrates in China, Japan, and South Korea, with induction coil winding and microprocessor module production drawing from specialized East Asian electronics corridors. Supply chain risk centers on single-source vulnerability for high-grade ferrite cores and copper litz wire. Distribution runs through national supply agreements at multi-unit chains, bypassing traditional regional equipment dealers in metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary sensor algorithm development and captive coil winding capacity is becoming the decisive competitive lever as efficiency mandates tighten across East Asian procurement specifications.
For Market Incumbents: Deploy backward integration into ferrite core and copper winding production to secure input supply against East Asian component bottlenecks. Deepen certification investment for simultaneous GB standards, METI Top Runner, and FDA Food Code alignment to compress multi-market launch timelines. Defensive consolidation must address emerging sensor-integrated entrants and cloud kitchen direct procurement models that disintermediate traditional distributor relationships. For New Entrants and Emerging Players: Capture first-mover positioning in India's commercial kitchen modernization across Mumbai, Bangalore, and Delhi NCR before established Japanese and Korean manufacturers scale local presence. White-space availability concentrates in programmable electric platforms for virtual restaurant operators seeking standardized equipment specifications. Go-to-market execution should leverage direct manufacturer contracts with ghost kitchen brands, mirroring the procurement consolidation pattern visible in Shanghai and Seoul. For Investors and Strategic Acquirers: MIIT efficiency mandate acceleration is the leading indicator that induction architecture adoption will outpace resistive-element replacement cycles, favoring targets with coil-based product portfolios. Long-term viability over a multi-year horizon rests on sensor-thermostat convergence capabilities and IoT-enabled predictive maintenance offerings. Acquisition target archetype: mid-cap specialists with proprietary microprocessor control algorithms and established direct relationships with hotel chains.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Coil Manufacturing Scale-Up | Captive ferrite core production reduces exposure to East Asian component bottlenecks and input price volatility. |
| Multi-Certification Parallel Pathway | Simultaneous GB standards, METI Top Runner, and FDA alignment compresses product launch schedules across supply corridors. |
| Direct Ghost Kitchen Partnership | Bypassing regional dealers secures volume commitments from cloud kitchen operators in Shanghai, Seoul, and Singapore. |
| Sensor-Thermostat Algorithm Development | Proprietary moisture detection and adaptive heating capabilities differentiate premium positioning against commodity competitors. |
| India Market Entry Localization | BIS certification and Mumbai-Delhi NCR distribution infrastructure establish foundation before incumbent scale-up. |
Research Methodology
Multi-period observation of MIIT efficiency mandate implementation, METI Top Runner benchmark tightening, and ghost kitchen procurement centralization anchored the trend analysis, supplemented by interviews with commercial kitchen equipment procurement directors, foodservice operations managers, hotel engineering executives, and regional distributor principals. Secondary validation drew from MIIT policy circulars, METI efficiency program documentation, FDA Food Code provisions, customs trade data for commercial kitchen appliance imports, and SEC filings of publicly traded manufacturers. Bottom-up demand modeling across restaurant, hotel, catering, and institutional end-use segments was triangulated against top-down market sizing.
Segment-weighting across heating platform type, capacity tier, control technology sophistication, and end-use format determined value distribution throughout the projection horizon. CAGRs were derived from replacement cycle compression analysis, regulatory mandate adoption curves, and infrastructure investment trajectories in target geographies. Industry-specific forecast inputs included cloud kitchen density metrics in metropolitan clusters and three-phase electrical retrofit penetration rates for induction unit installation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT mandate enforcement intensity, induction technician training pipeline expansion, and ghost kitchen operator consolidation patterns. Model assumptions reflect documented regulatory trajectories and procurement pattern shifts across the analysis window. A model refresh is warranted upon material change in China's dual carbon policy implementation timeline or significant ghost kitchen operator bankruptcy events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cutting Boards Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Peer-To-Peer Dining Market
Food Service
Cloud Kitchen Market
Food Service
Virtual Kitchen Market
Food Service
Mobile Food Services Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
Haute Cuisine Market
Food Service
Commercial Tandoor Oven Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Light Meal Market
Food Service
US Food Trucks Services Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
South America Free from Food Market
Food Service
Middle East Smokeless Indoor Grills Market