
 Restaurants in Belgium Market | 2026-2036
Restaurants in Belgium Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurants in Belgium Market Insights
The EU Green Deal is decoupling Belgian foodservice procurement from carbon-intensive supply chains, forcing operators to requalify vendors and reformulate menus. McDonald's Corporation leverages its scale to negotiate regenerative agriculture contracts across Wallonia and Flanders. Compass Group Belgium anchors its institutional catering business through long-term sustainability commitments with Belgian hospital networks and university campuses.
Restaurants in Belgium comprise commercial establishments preparing and serving meals to on-premise or off-premise consumers, typically operating under HACCP protocols with cold-chain integrity requirements of 0-4°C for fresh ingredients and minimum 65°C holding temperatures for hot service. The sector serves daily nutritional needs, corporate hospitality, and tourism-driven consumption across urban and peri-urban locations. Casual Dining and Fast Food command the largest revenue pools, though Fine Dining retains disproportionate margin concentration in Brussels and Antwerp. Delivery Services is the fastest-expanding delivery mode, reshaping kitchen layouts and labor allocation across mid-market chains.
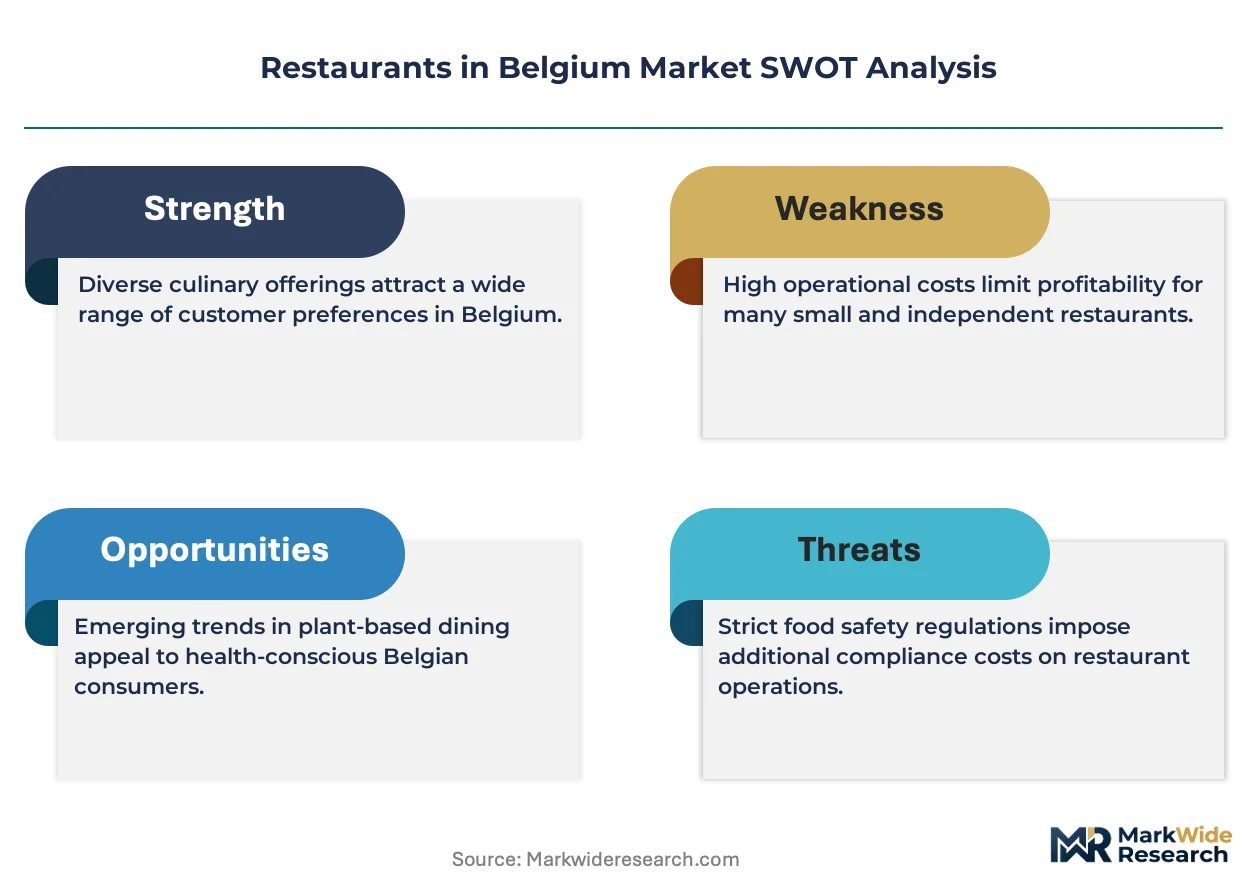
FASFC, the Belgian Federal Agency for the Safety of the Food Chain, enforces strict allergen labeling and traceability mandates that elevate compliance costs for independent operators. The EU Packaging and Packaging Waste Regulation, implemented through Belgian regional authorities, is phasing single-use plastics from takeaway operations, compelling capital investment in reusable container systems and compostable alternatives. Stakeholders must monitor how Flanders, Wallonia, and Brussels diverge in transposing EU directives into regional enforcement regimes, as compliance fragmentation will determine market access costs for multi-location operators.
Market Dynamics
The EU Green Deal is forcing Belgian foodservice operators to requalify their entire supplier base, decoupling procurement from carbon-intensive supply chains and triggering a wholesale reformulation of menus across Quick Service and Casual Dining segments.
Growth Catalysts
- EU Green Deal decarbonization mandates:Brussels, Flanders, and Wallonia are transposing these directives into regional enforcement regimes that favor operators with certified sustainable sourcing.
- Quick-service dining adoption:Belgian families are accelerating their shift toward convenience formats, expanding addressable demand for delivery-optimized kitchen configurations.
- Regenerative agriculture contracting:Large-scale operators are locking in long-term supply agreements with Walloon and Flemish farms to secure climate-compliant ingredient flows.
Market Restraints
- Input cost volatility:Energy prices and compostable packaging materials are squeezing margins for independent operators unable to negotiate volume discounts.
- Supply concentration risk:Belgium's cold-chain logistics depend on a limited pool of specialized refrigerated transport providers serving Brussels and Antwerp corridors.
- Regulatory friction:Divergent transpositions of EU Packaging and Packaging Waste Regulation across Flanders, Wallonia, and Brussels are fragmenting compliance costs for multi-location chains.
Strategic Opportunities
- Institutional catering expansion:Belgian hospital networks and university campuses are seeking long-term sustainability commitments from foodservice partners.
- Reusable container systems:The phase-out of single-use plastics is creating white space for operators investing in deposit-return infrastructure and washing logistics.
- Regional cuisine premiumization:Flemish urban corridors show underpenetrated demand for locally-sourced, carbon-labeled fine dining experiences.
Industry Challenges
- HACCP-certified kitchen labor scarcity:Operators struggle to recruit staff trained in cold-chain integrity protocols and allergen management systems.
- Capex intensity for compliance:FASFC traceability mandates require investment in digital inventory tracking and temperature logging infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurants in Belgium Market |
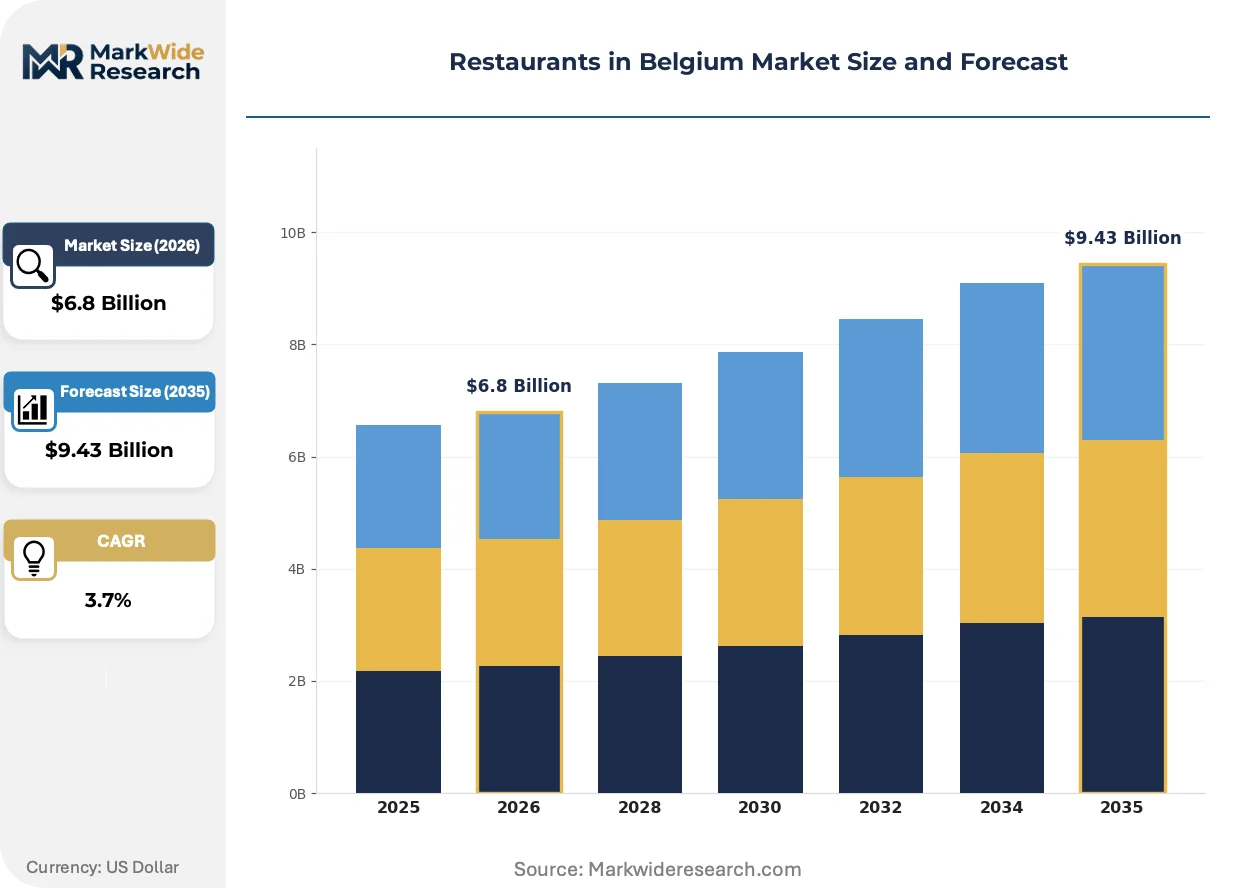
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Cafés Customer Type: Families, Tourists, Business Professionals, Students Cuisine Type: Belgian, French, Italian, Asian Delivery Mode: Takeout, Dine-in, Delivery Services, Catering |
| Companies Covered | McDonald's Corporation, Yum! Brands, Inc., Doctor's Associates Inc., Domino's Pizza, Inc., Restaurant Brands International Inc., Burger Brands, Quick, Compass Group Belgium, Starbucks Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurants in Belgium Market Trends and Innovations
Belgian foodservice is experiencing a structural compression of traditional operating models as sustainability mandates, digital kitchen integration, and delivery-first consumption patterns simultaneously reshape capital allocation and labor deployment.
Cloud-based kitchen management systems are integrating temperature monitoring, allergen tracking, and procurement analytics into unified platforms. Mid-market chains in Brussels and Antwerp are adopting these systems fastest, replacing fragmented paper-based compliance workflows. This technology is integrating previously siloed operational data streams, enabling real-time margin visibility that compresses decision cycles from weeks to hours.
The EU Packaging and Packaging Waste Regulation is mandating measurable reductions in single-use plastics across takeaway operations. Belgian regional authorities are enforcing divergent timelines, with Flanders moving fastest on compostable mandates. Quick-service operators are responding by redesigning packaging specifications and negotiating new supplier contracts before enforcement hardens.
Delivery-first consumption is displacing on-premise dining as the primary revenue driver for mid-market chains. Dark kitchens and ghost kitchen formats are proliferating in peri-urban zones around Ghent and Leuven, replacing traditional front-of-house investments with logistics-optimized production cells. This shift is most visible among family-oriented Quick Service brands seeking to capture suburban household demand without real estate-heavy footprint expansion.
Restaurants in Belgium Market Segmentation
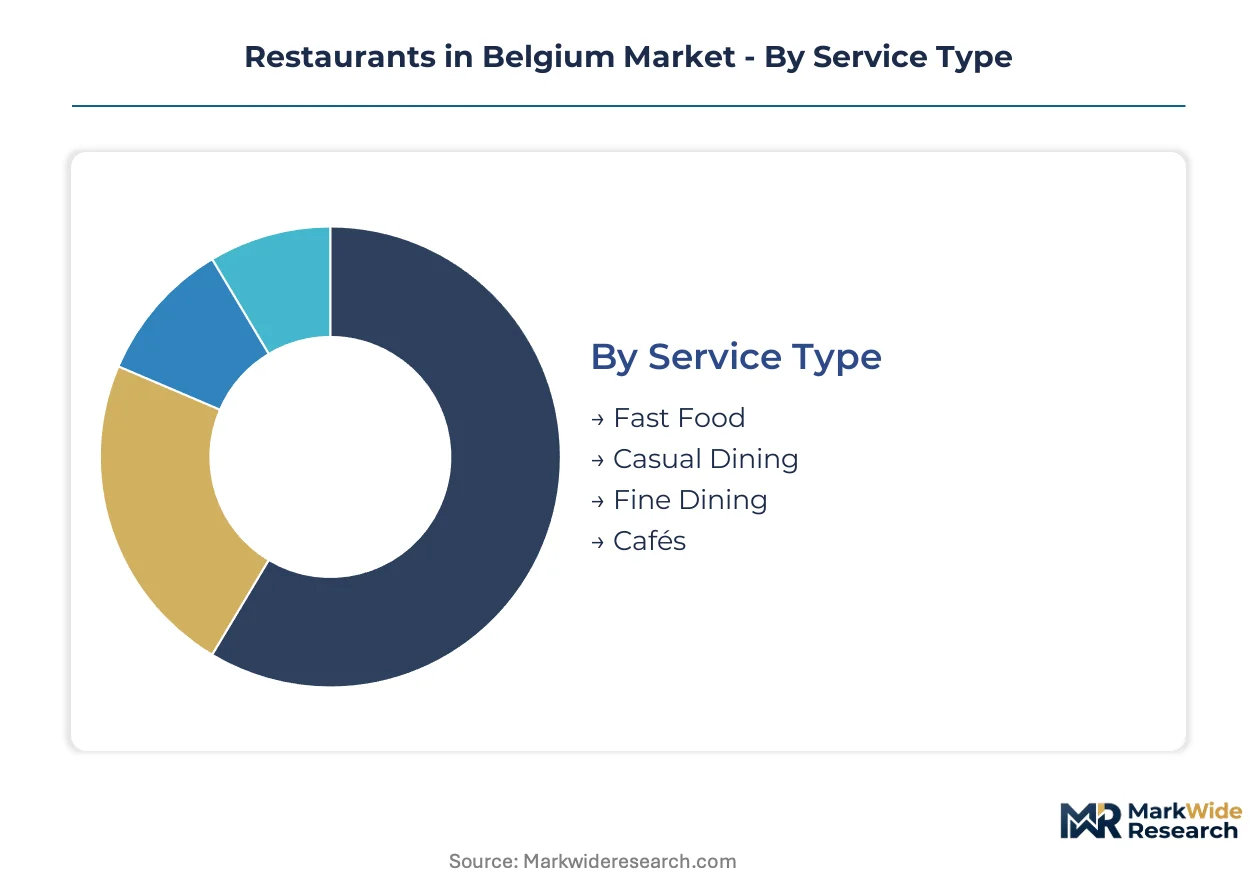
Segmentation in the Belgian foodservice market reveals how divergent customer occasions, operational formats, and procurement constraints fragment addressable demand. Operators must align kitchen configuration, labor models, and supply chain qualification to specific segment requirements or forfeit margin to specialized competitors.
Service Type:
Speed of service and price point separate Belgian consumers across occasions, from impulse convenience to celebratory dining.
- Fast Food:High-throughput formats with standardized menus and minimal front-of-house labor. Brussels and Antwerp corridors concentrate demand from time-constrained commuters and suburban families seeking value-engineered meals. EU Green Deal packaging mandates are forcing rapid capital redeployment into reusable container logistics.
- Casual Dining:Full-service experience with moderate check averages and flexible daypart coverage. Flemish urban corridors show strongest demand concentration as Belgian families trade up from fast food for weekend occasions. Labor scarcity in HACCP-certified kitchen roles constrains expansion velocity.
- Fine Dining:Chef-driven concepts with premium ingredient sourcing and extended service rituals. Margin concentration remains highest in Brussels and Antwerp despite limited volume.
- Cafés:Coffee-forward formats with light food attachment, concentrated in pedestrian zones and transport hubs.
Volume sits with Casual Dining; growth tilts toward Fast Food.
Customer Type:
Meal occasion and decision urgency shape procurement patterns more than demographics alone.
- Families:Value-sensitive multi-cover occasions demanding child-friendly menus and high-chair infrastructure. Quick-service adoption accelerates as Belgian households prioritize convenience over traditional sit-down formats.
- Tourists:Experience-seeking visitors concentrated in Brussels historic core and Bruges canal districts. Demand peaks correlate with seasonal hospitality flows rather than local economic cycles.
- Business Professionals:Expense-account dining and compressed lunch windows favoring speed and proximity to office clusters. Antwerp diamond district and Brussels EU quarter anchor demand.
- Students:Price-elastic demand concentrated around Ghent, Leuven, and Louvain-la-Neuve campuses. Volume scales through institutional catering contracts rather than individual transactions.
Business Professionals generate the densest revenue per square meter; Families are expanding most quickly.
Cuisine Type:
Ingredient sourcing complexity and labor skill requirements create divergent margin structures across culinary traditions.
- Belgian:Carbon-labeled local sourcing and heritage preparation methods command premium positioning in Flemish corridors. EU Green Deal traceability mandates advantage operators with established farm partnerships.
- French:Classical technique requirements elevate labor costs while sustaining margin in Brussels fine dining tier.
- Italian:Supply chain dependence on imported specialties exposes margins to currency and tariff volatility.
- Asian:Diverse sub-categories from quick-service sushi to full-service dim sum, with fastest format innovation in delivery-optimized concepts.
Belgian cuisine captures the highest sustainability premium; Asian formats show steepest expansion trajectory.
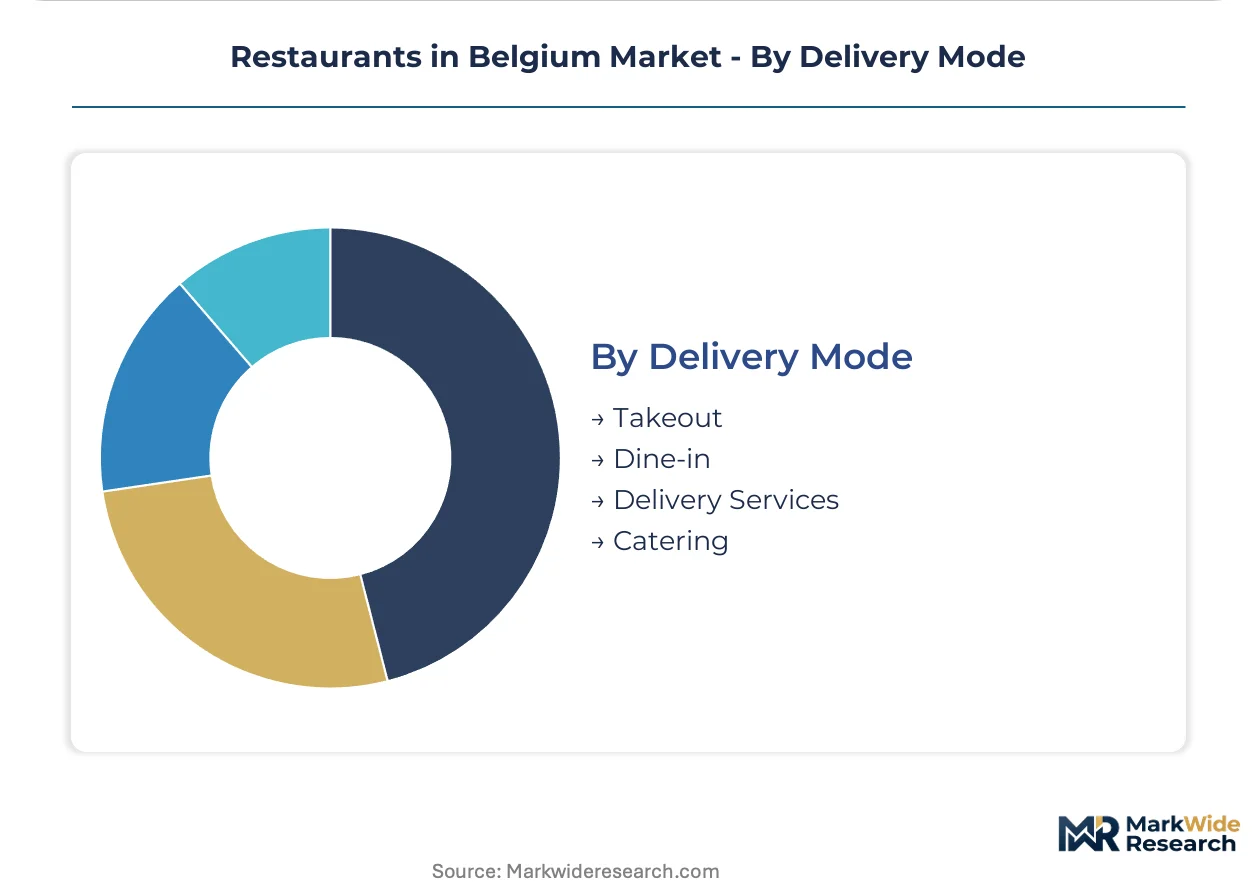
Delivery Mode:
Kitchen layout and real estate economics diverge sharply between on-premise and off-premise revenue capture.
- Takeout:Counter-service pickup with minimal labor overhead. FASFC allergen labeling mandates increase packaging complexity for multi-item orders.
- Dine-in:Traditional front-of-house service requiring full staffing and square footage allocation. Brussels and Antwerp rent inflation compresses viability for independent operators.
- Delivery Services:Third-party platform dependence with commission structures reshaping kitchen labor allocation. Dark kitchens proliferate in peri-urban Ghent and Leuven zones to capture suburban demand without storefront investment.
- Catering:Institutional and event-based volume with long contract cycles and sustainability qualification requirements.
Dine-in retains margin concentration; Delivery Services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brussels anchors Belgian foodservice demand through its concentration of EU institutions, international business travelers, and high-density office corridors. The capital generates disproportionate fine dining margins while Flemish urban corridors drive volume expansion through family-oriented quick-service adoption. Wallonia's industrial cities sustain institutional catering contracts with manufacturing and healthcare sectors.
Brussels-Capital Region
EU quarter office clusters and international tourism sustain premium dining demand across the historic core. FASFC allergen labeling mandates elevate compliance costs for independent bistros operating near Grand-Place. Dark kitchen proliferation concentrates in Anderlecht and Schaerbeek peri-urban zones to capture suburban delivery demand without storefront rents.
Flanders
Antwerp's diamond district and port logistics corridor anchor business professional lunch demand with compressed service windows. The EU Packaging and Packaging Waste Regulation transposes fastest here, with Ghent and Leuven municipalities advancing compostable mandate enforcement ahead of Wallonia. Quick-service chains expand along E40 and E17 highway corridors to capture commuting household traffic.
Wallonia
Liège and Charleroi industrial basins sustain institutional catering volume through hospital networks and manufacturing plant contracts. Regenerative agriculture partnerships concentrate in Hesbaye and Condroz farmland zones as Compass Group Belgium locks long-term supply agreements. Compliance costs diverge from Flemish timelines as regional authorities lag on single-use plastic phase-out enforcement.
Restaurants in Belgium Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sustainability certification and procurement scale dimensions. The Belgian foodservice market structures into three tiers: multinational quick-service chains with regenerative agriculture contracting power, institutional caterers with hospital and university network lock-in, and independent operators struggling with FASFC compliance capital requirements. Consolidation pressure concentrates among mid-market casual dining chains unable to negotiate volume discounts on compostable packaging. Dominant competitive moves include backward integration into farm partnerships and technology licensing for cloud-based kitchen management systems.
Among US-based quick-service giants, McDonald's Corporation and Yum! Brands, Inc. exemplify the scale-driven archetype through their Wallonia and Flanders procurement leverage. Domino's Pizza, Inc. occupies a position within delivery-optimized formats as dark kitchen proliferation reshapes peri-urban competitive dynamics. Compass Group Belgium anchors the institutional catering tier through its sustainability commitment contracting with Belgian hospital networks.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Yum! Brands, Inc. |
| Doctor's Associates Inc. |
| Domino's Pizza, Inc. |
| Restaurant Brands International Inc. |
| Burger Brands |
| Quick |
| Compass Group Belgium |
| Starbucks Corporation |
| Others |
Pricing and Supply Chain Analysis
HACCP-certified kitchen labor scarcity in Flanders and Wallonia widens pricing-tier spreads between premium fine-dining concepts and value-engineered quick-service formats, as wage differentials for cold-chain protocol expertise compound with FASFC compliance overhead.
Pricing Analysis
Value-based pricing anchored to carbon-labeled ingredient provenance and sustainability certification tier separates premium Belgian cuisine concepts from commodity fast-food operators. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU Green Deal sourcing compliance, with regenerative agriculture contracts commanding measurable uplifts. Cost compression in the mid-market casual dining tier intensifies because compostable packaging mandates and energy input volatility squeeze operators lacking volume-negotiation leverage. Families exhibit highest price sensitivity, while business professionals in Brussels EU quarter and Antwerp diamond district demonstrate lowest elasticity for convenience premiums.
Supply Chain Analysis
Direct-to-institutional channels handle hospital network and university campus procurement volume, while distributor-mediated flows serve fragmented independent restaurant bases across Brussels, Antwerp, and Ghent. Geographic supply concentration draws from Netherlands for dairy and protein inputs, France for wine and specialty ingredients, and domestic Walloon and Flemish farms for carbon-labeled produce under regenerative agriculture partnerships. Raw material dependencies rest on specialized refrigerated transport capacity, compostable packaging substrates, and allergen-free ingredient streams. Single-source vulnerability concentrates in cold-chain logistics providers serving the Brussels-Antwerp corridor. Distribution runs through regional foodservice wholesalers with HACCP-certified warehousing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Belgian foodservice market is becoming a vertical-integration race as operators pursue upstream control over regenerative agriculture supply to defend margin against input volatility and sustainability-mandate compliance costs.
For Market Incumbents: Lock in long-term regenerative agriculture contracts across Hesbaye and Condroz farmland zones before Wallonia tightens EU Green Deal enforcement timelines. Secure HACCP-certified kitchen labor through apprenticeship pipelines with Flemish hospitality institutes. Acquire cloud-based kitchen management platforms to compress FASFC traceability compliance costs below independent operator thresholds. For New Entrants and Emerging Players: Launch via dark kitchen formats in peri-urban Ghent and Leuven zones to capture suburban family delivery demand without Brussels-Antwerp rent exposure. Target the underpenetrated carbon-labeled fine dining segment in Flemish urban corridors where EU Green Deal traceability mandates advantage new entrants with clean sourcing narratives from inception. For Investors and Strategic Acquirers: Re-rating potential sits with institutional caterers holding hospital network and university campus sustainability commitments given the durability of long-contract revenue visibility. Acquire targets demonstrating backward integration into farm partnerships or proprietary reusable container logistics infrastructure. Monitor Flanders-Wallonia regulatory divergence on single-use plastic enforcement as an inflection signal for compliance-cost fragmentation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Contracting | Long-term supply agreements with Walloon and Flemish farms secure climate-compliant ingredient flows ahead of EU Green Deal enforcement hardening. |
| Reusable Container Infrastructure | Deposit-return logistics and washing systems capture white space created by EU Packaging and Packaging Waste Regulation single-use plastic phase-out mandates. |
| Cloud Kitchen Management Integration | Unified platforms for temperature monitoring, allergen tracking, and procurement analytics compress FASFC compliance decision cycles from weeks to hours. |
| Dark Kitchen Network Expansion | Peri-urban production cells around Ghent and Leuven capture suburban household delivery demand without real estate-heavy footprint expansion. |
| Institutional Sustainability Certification | Hospital network and university campus contract lock-in anchors revenue visibility through multi-year sustainability commitment frameworks. |
Research Methodology
Independent corroboration across primary interviews with restaurant operations directors, procurement leads at multi-location chains, FASFC compliance officers, and cold-chain logistics providers underwrites the qualitative findings. Secondary validation draws from Belgian Federal Agency for the Safety of the Food Chain enforcement bulletins, EU Green Deal directive transposition documents from Flanders, Wallonia, and Brussels-Capital regional authorities, and foodservice industry trade association procurement surveys. Bottom-up demand modeling across service type, customer occasion, cuisine category, and delivery mode segments triangulates against top-down macroeconomic consumption indicators.
Comparable-period anchoring to pre-EU Green Deal implementation baselines establishes the analytical framework for projection horizon modeling across the analysis window. Segmentation dimensions include service format tier, customer occasion type, cuisine origin, delivery mode, and regional regulatory cluster. CAGRs derive from trend extrapolation of quick-service adoption velocity, sustainability mandate compliance cost trajectories, and delivery-first consumption share shifts. Industry-specific forecast inputs incorporate FASFC allergen labeling enforcement intensity and divergent regional plastic packaging phase-out timelines.
The model assumes a particular technology adoption path for cloud-based kitchen management and reusable container logistics; alternative pathways for digital compliance automation or biodegradable packaging substrate breakthroughs would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement harmonization across Belgian regions, energy input price stabilization, and HACCP-certified labor supply elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Belgium HRI Market
Food Service
Malaysia Food Service Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Self-Heating Hot Pot Market
Food Service
Netherlands Food Service Market
Food Service
Global Digital Grocery Market
Food Service
North America Online Grocery Delivery Market
Food Service
Sandwich Toasters Market
Food Service
Food Logistics Market
Food Service
United States Full Service Restaurants Market
Food Service
Food Service Dairy Products Market
Food Service
Commercial Charbroiler Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Mobile Food Services Market
Food Service
Oman Food Service Market