
 Beverage Napkins Market | 2026-2036
Beverage Napkins Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Napkins Market Outlook
The capital-intensity gap between integrated pulp producers and converters is collapsing as raw material costs squeeze mid-tier operators. Georgia-Pacific LLC leverages its captive pulp supply to sustain margin stability across North American foodservice channels. Essity AB competes through specialized hygiene product portfolios that anchor premium positioning in European institutional markets.
Beverage napkins are single-use or limited-use absorbent sheets, typically measuring 5 by 5 inches, manufactured through air-laid or conventional wet-press processes from virgin or recycled pulp fibers, designed primarily for liquid containment and surface protection in food and drink service environments. Disposable pulp-based products dominate volume throughput in high-turnover restaurant settings where labor minimization overrides unit economics. Biodegradable and eco-friendly variants are capturing the fastest expansion trajectory as procurement teams across European and North American foodservice chains rewrite supplier qualification criteria around compostability certifications.
The US EPA oversees landfill diversion targets that directly shape pulp sourcing decisions for domestic manufacturers, while the EU Green Deal and REACH frameworks mandate composability thresholds and chemical disclosure for napkins entering European foodservice supply chains. India's BIS standards for paper hygiene products create additional compliance layers for exporters targeting its institutional catering sector. Stakeholders must monitor how divergent national packaging Extended Producer Responsibility schemes recalibrate cost structures for multinational suppliers operating across these jurisdictions.
Market Dynamics
The EU Green Deal's single-use plastics directive is compressing material substitution timelines across European foodservice supply chains, forcing pulp-based alternatives into procurement specifications ahead of cost parity.
Growth Catalysts
- Compostability Mandates:The EU Green Deal's single-use plastics directive is accelerating material shifts toward pulp-based alternatives in German restaurant and café channels.
- Urban Foodservice Density:India and Brazil are witnessing concentrated demand in metropolitan foodservice clusters where high-turnover establishments prioritize biodegradable beverage napkins.
- Air-laid Process Efficiency:Advanced manufacturing techniques are reducing unit production costs for absorbent sheets, expanding addressable volume in institutional catering.
Market Restraints
- Pulp Input Volatility:Virgin and recycled fiber costs fluctuate with energy-intensive drying processes, squeezing converter margins disproportionately.
- Supply Concentration Risk:Integrated pulp producers in North America and Scandinavia control upstream fiber supply, limiting negotiating leverage for mid-tier napkin converters.
- Performance Trade-offs:Biodegradable variants exhibit lower wet-strength durability compared to polymer-reinforced alternatives, restricting deployment in high-moisture service environments.
Strategic Opportunities
- Extended Producer Responsibility Schemes:France and Germany are implementing packaging EPR frameworks that reward compostable product lines with fee reductions.
- Direct-to-Chain Distribution:Bypassing traditional paper merchant networks, manufacturers are building dedicated supply relationships with pan-European quick-service restaurant operators.
- Digital Printing Integration:On-demand branding capabilities are converging with sustainable substrates, enabling customized napkin programs for boutique hospitality groups.
Industry Challenges
- Certification Timeline Compression:Obtaining OK Compost and BPI certifications requires 12-18 month validation cycles, delaying product launches behind regulatory deadlines.
- Legacy Equipment Retrofit Costs:Conventional wet-press lines demand capital-intensive modifications to handle higher-fiber-content biodegradable pulp formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Napkins Market |
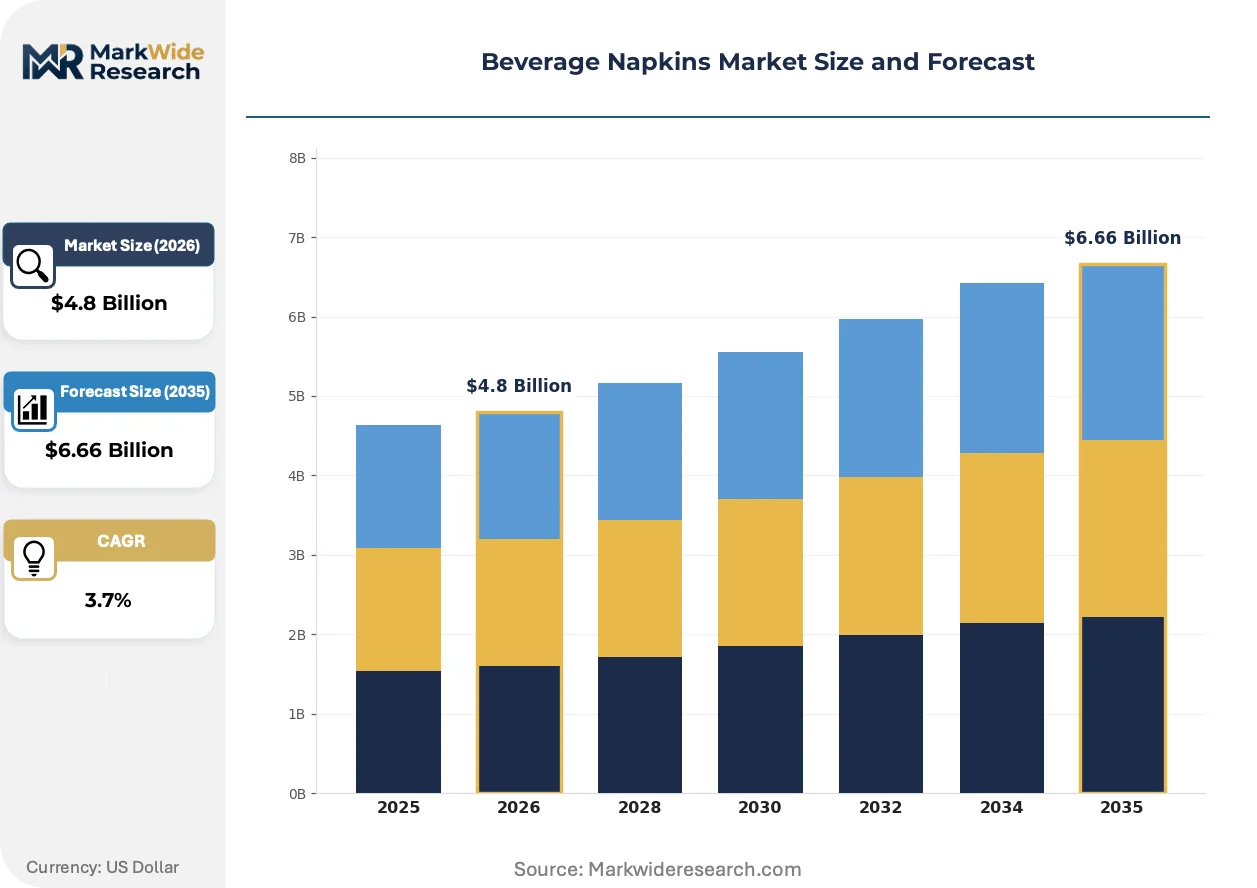
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Eco-Friendly Material: Pulp, Paper, Cloth, Plastic Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale End User: Restaurants, Cafés, Bars, Catering Services |
| Companies Covered | Kimberly-Clark Professional, Metsa Tissue GmbH, Pudumjee Paper Products, Asia Pulp and Paper Group, Amscan Inc., Georgia-Pacific LLC, Procter & Gamble, Cascades Inc., Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Napkins Market Strategic Shifts
Material science advances and regulatory compression are reshaping competitive positioning in beverage napkin manufacturing, with sustainability credentials now functioning as primary procurement filters rather than premium differentiators.
Air-laid pulp technology is miniaturizing fiber bonding requirements while maintaining absorbency performance. Quick-service restaurant chains in Germany and the Netherlands are adopting these lighter-weight substrates to reduce freight costs per unit. The technology is miniaturizing the performance gap between virgin and recycled fiber inputs, enabling cost-neutral sustainable procurement.
REACH chemical disclosure requirements are mandating full supply chain transparency for pulp additives entering European foodservice channels. Manufacturers must now document optical brighteners and wet-strength agents across tier-two suppliers. Institutional buyers in France and Belgium are responding by pre-qualifying only those converters with certified chemical management systems.
Consolidated procurement by multinational restaurant groups is displacing fragmented distributor relationships across urban foodservice clusters. Direct vendor-managed inventory programs are replacing traditional stock-and-sell arrangements in São Paulo and Mumbai metropolitan areas. This concentration is most visible in India, where institutional catering contracts now specify single-source biodegradable napkin supply with penalty clauses for non-compliance.
Beverage Napkins Market Segmentation
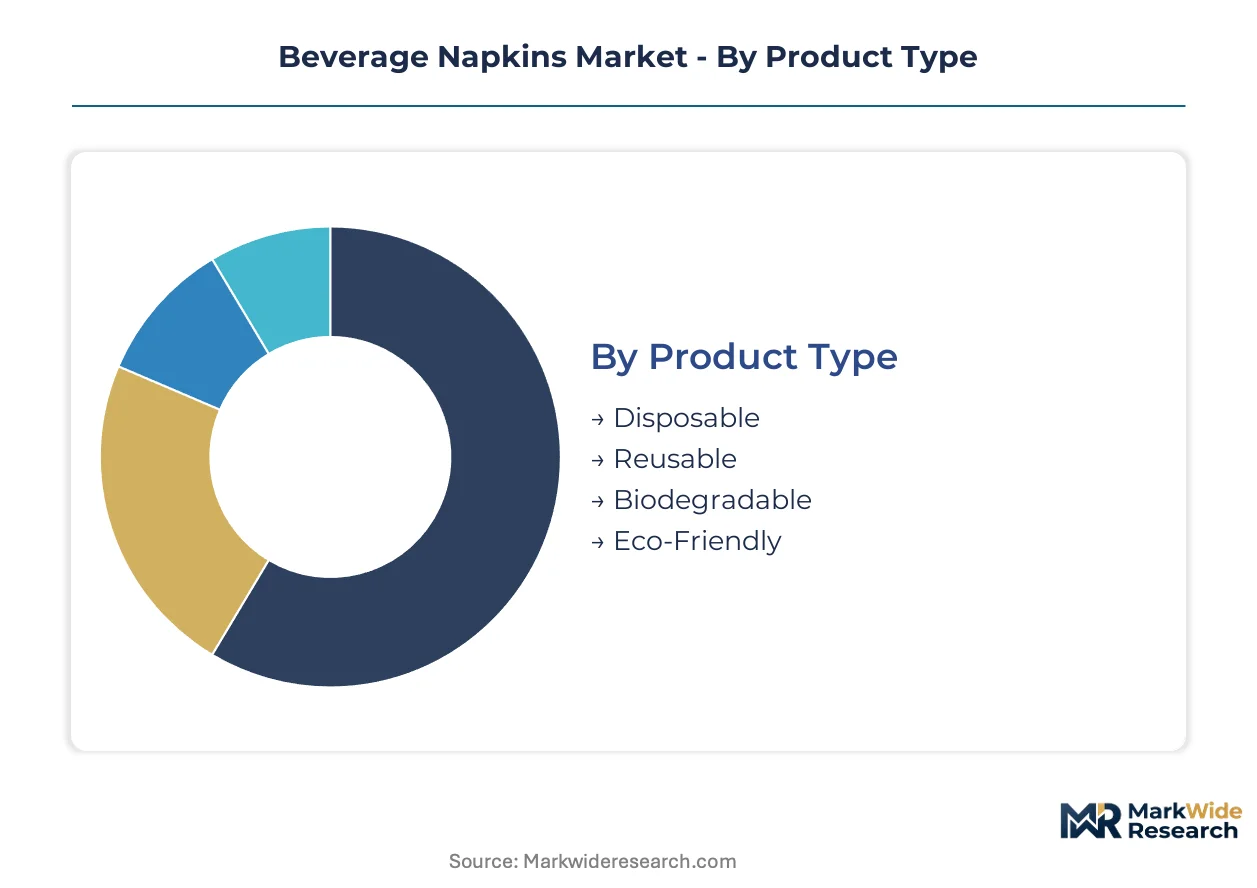
Beverage napkin procurement patterns diverge sharply across customer archetypes, with institutional buyers prioritizing unit economics while boutique hospitality operators chase brand differentiation through substrate selection. Segmentation reveals how regulatory pressure and supply chain configuration reshape competitive positioning within each slice of demand.
Product Type:
Disposable variants dominate domestic foodservice procurement in Germany and the United States, while biodegradable lines command premium positioning in export-led channels targeting EU Green Deal compliance.
- Disposable:Air-laid pulp sheets manufactured through high-speed wet-press processes deliver absorbency at sub-cent unit costs. Quick-service restaurant chains in São Paulo and Mumbai metropolitan clusters specify these for high-turnover beverage service where labor minimization overrides substrate sustainability credentials.
- Biodegradable:Compostable pulp formulations certified under OK Compost or BPI protocols absorb liquid through enhanced fiber bonding without polymer reinforcement. German restaurant and café channels are rewriting procurement specifications to mandate these ahead of EU single-use plastics directive deadlines, accepting wet-strength trade-offs in standard service environments.
- Reusable:Cotton and linen-blend napkins serve white-tablecloth establishments in Paris and Milan where per-cover laundry economics justify higher acquisition costs.
- Eco-Friendly:Recycled fiber content exceeding 50 percent appeals to North American institutional catering contracts requiring EPA landfill diversion documentation.
Disposable commands the established base. The steepest expansion runs through biodegradable.
Material:
Cost tier stratification separates virgin pulp at the premium end from plastic substrates facing regulatory compression across European foodservice channels.
- Pulp:Virgin and recycled wood fibers processed through air-laid or conventional pressing yield the absorbent core for 90 percent of foodservice volume. Georgia-Pacific and Essity anchor supply through captive fiber integration, squeezing converter margins when energy-intensive drying costs spike.
- Paper: Lower-basis-weight sheets target cost-sensitive institutional catering in India, where BIS hygiene standards create compliance layers for domestic and imported supply alike.
- Cloth:Linen and cotton blends persist in European fine-dining segments where tactile quality supports per-check pricing power.
- Plastic:Polymer-reinforced alternatives face accelerating displacement as France and Germany implement packaging Extended Producer Responsibility schemes that penalize non-compostable lines.
Pulp anchors volume throughput. Cloth holds the premium pricing tier.
Distribution Channel:
Customer type concentration determines channel viability, with wholesale dominating institutional procurement while digital routes capture boutique hospitality fragmentation.
- Wholesale:Pan-European quick-service restaurant operators bypass traditional paper merchant networks through direct vendor-managed inventory programs, consolidating procurement across German, Dutch, and Belgian metropolitan clusters.
- Supermarkets:Multi-pack retail formats serve small independent cafés in Brazilian urban foodservice corridors where cash-flow constraints favor just-in-time replenishment.
- Online Retail:Digital platforms enable customized napkin programs for boutique hospitality groups requiring on-demand branding with sustainable substrates.
- Convenience Stores:Emergency replenishment channels capture spillover demand from Mumbai and São Paulo foodservice operators facing supply disruptions.
Wholesale locks in institutional volume. Online retail is gaining share fastest among differentiated buyers.
End User:
Application maturity separates high-volume restaurant chains from fragmented catering services where procurement standardization lags.
- Restaurants:Full-service and quick-service operators generate the bulk of beverage napkin consumption, with German chains specifying compostable lines under EU Green Deal procurement mandates and Indian metropolitan clusters demanding biodegradable supply with contractual penalty clauses.
- Cafés:Coffee-focused establishments in Amsterdam and Berlin prioritize lighter-weight air-laid substrates to reduce freight costs per unit while maintaining absorbency for high-moisture beverage service.
- Bars:High-moisture environments create performance tension, as biodegradable variants exhibit lower wet-strength durability compared to polymer-reinforced alternatives.
- Catering Services:Event-based demand concentrates in Brazilian and Indian urban clusters where single-use specifications dominate for logistical simplicity.
Restaurants command the established base. The steepest expansion runs through cafés.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command pricing power over Indian counterparts due to EU Green Deal procurement mandates, while Brazilian operators face margin compression from pulp import dependency. This asymmetry shapes investment flows and capacity decisions across manufacturing bases.
United States
Quick-service restaurant chains and institutional catering contracts drive absorbent sheet procurement volumes. The EPA oversees landfill diversion targets that directly shape pulp sourcing decisions for domestic manufacturers. Georgia-Pacific anchors supply from integrated pulp facilities across the Southeast, sustaining margin stability when energy-intensive drying costs spike.
Germany
Restaurant and café channels are rewriting procurement specifications to mandate compostable beverage napkins ahead of EU single-use plastics directive deadlines. The EU Green Deal's packaging EPR frameworks reward certified product lines with fee reductions. Berlin and Hamburg metropolitan clusters concentrate demand where high-turnover establishments prioritize biodegradable supply.
India
Urban foodservice density in Mumbai and Delhi-NCR generates concentrated demand for biodegradable beverage napkins with contractual penalty clauses for non-compliance. The BIS standards for paper hygiene products create additional compliance layers for exporters targeting institutional catering. Maharashtra and Karnataka host manufacturing clusters serving domestic and export channels.
Brazil
São Paulo metropolitan foodservice operators specify single-use biodegradable supply for logistical simplicity in high-turnover environments. ANVISA hygiene regulations govern imported and domestic pulp-based products entering foodservice channels. The Southeast region concentrates converter capacity, though pulp fiber dependency on imports squeezes margins when currency volatility hits.
Japan
Specialty coffee chains and boutique hospitality operators in Tokyo and Osaka prioritize lighter-weight air-laid substrates to reduce freight costs per unit. METI energy efficiency standards shape drying process investments for domestic manufacturers. The Kanto region anchors premium-tier procurement where tactile quality supports per-check pricing power.
Beverage Napkins Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the beverage napkins market. Integrated pulp producers leverage captive fiber supply to sustain margin stability, while specialized converters compete through certification speed and customized branding capabilities. Three archetypes dominate: upstream-integrated multinationals, regional hygiene specialists, and boutique sustainability-focused converters. Competitive moves concentrate on direct-to-chain distribution partnerships and legacy equipment retrofits for biodegradable formulations.
Among North American integrated producers, Georgia-Pacific LLC exemplifies the upstream-control archetype through captive pulp supply. European hygiene specialists include Essity AB, which occupies a position in institutional market premium positioning. Asia-Pacific pulp conglomerates such as Asia Pulp and Paper Group represent scale-driven supply anchoring for regional converter networks. These three patterns illustrate how fiber access, certification velocity, and distribution configuration separate viable competitors from margin-squeezed mid-tier operators.
| Leading Market Players |
|---|
| Kimberly-Clark Professional |
| Metsa Tissue GmbH |
| Pudumjee Paper Products |
| Asia Pulp and Paper Group |
| Amscan Inc. |
| Georgia-Pacific LLC |
| Procter & Gamble |
| Cascades Inc. |
| Essity AB |
| Others |
Value Chain & Pricing Dynamics
Sixty-day certification timelines for OK Compost and BPI validation compress supplier selection windows and concentrate pricing power with pre-certified converters across German and Dutch foodservice channels. This lead-time rigidity forces procurement teams to accept premium positioning for certified biodegradable lines while squeezing mid-tier operators on standard disposable grades.
Pricing Analysis
The customization-premium spread between digital-print configured orders and standard wet-press bulk supply runs 15-25 percent across European boutique hospitality contracts. Contract-based long-term offtake dominates institutional procurement in São Paulo and Mumbai metropolitan clusters, where volume scale and certification grade drive price differentiation. Cost compression in standard disposable tiers is intensifying because pulp drying energy costs spike during European winter gas demand peaks. Quick-service restaurant chains exhibit highest price sensitivity, while white-tablecloth establishments in Paris and Milan accept premium positioning for tactile quality.
Supply Chain Analysis
Baltic Sea pulp transit congestion periodically chokes fiber supply to German and Dutch converters, amplifying cost volatility for air-laid substrate production. Upstream supply concentrates in Sweden, Finland, and Brazil, where integrated producers control virgin fiber extraction. Raw material dependencies center on softwood kraft pulp, recycled post-consumer fiber, and optical brightener chemistries subject to REACH disclosure mandates. Single-source vulnerability runs through Scandinavian pulp integration, as converters lack alternative fiber qualification pathways. Distribution runs through direct vendor-managed inventory programs replacing traditional paper merchant networks across pan-European quick-service restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compostable supply programs function as a service-attach layer expanding faster than base substrate volume, as procurement teams pay recurring compliance-validation premiums beyond per-unit napkin costs. This recurring-revenue architecture rewards converters with pre-established certification velocity.
For Market Incumbents: Shield margin stability through captive pulp supply integration and accelerated OK Compost certification pipelines ahead of EU single-use plastics directive enforcement. Retrofit legacy wet-press equipment for higher-fiber-content biodegradable formulations to defend against specialized sustainability-focused converters capturing German restaurant channel share. Channel control through direct-to-chain distribution partnerships anchors volume retention against paper merchant displacement. For New Entrants and Emerging Players: Anchor in Brazilian São Paulo metropolitan foodservice clusters, where import-dependent pulp costs squeeze incumbent margins and create white-space for agile converters with localized fiber sourcing. Target Indian institutional catering contracts specifying biodegradable supply with penalty clauses, as BIS compliance layers filter out undercapitalized competitors. Pursue boutique hospitality digital-print customization as the most penetrable segment, leveraging on-demand branding capabilities with sustainable substrates. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent national Extended Producer Responsibility schemes recalibrate cost structures for multinational suppliers, rewarding geographic diversification. Acquisition target archetype: regional hygiene specialists with certified chemical management systems and established pan-European quick-service restaurant relationships. Watch EU packaging EPR fee-structure announcements as the inflection signal for compostable product line profitability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber access insulates Georgia-Pacific and Essity from energy-cost volatility in drying processes. |
| Direct-to-Chain Distribution Buildout | Vendor-managed inventory programs with German quick-service operators displace traditional paper merchant intermediaries. |
| Compostability Certification Acceleration | OK Compost and BPI pre-validation opens procurement doors ahead of EU single-use plastics directive deadlines. |
| Digital Printing Integration | On-demand branding capabilities capture boutique hospitality premium pricing in Amsterdam and Berlin clusters. |
| Legacy Equipment Retrofit for Biodegradable Formulations | Wet-press line modifications enable higher-fiber-content pulp handling without greenfield capacity investment. |
Study Parameters
A standing panel of foodservice procurement directors, pulp mill operations managers, paper merchant category buyers, and sustainability compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Green Deal directive filings, EPA landfill diversion documentation, BIS hygiene standard publications, and customs trade data for pulp fiber imports. Bottom-up volume modeling across German, Indian, and Brazilian metropolitan clusters triangulated with top-down absorbent sheet consumption estimates from institutional catering contract disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by product type, material formulation, distribution channel configuration, and end-user application maturity. CAGRs were derived from weighted regression across historical consumption patterns and regulatory-mandated substitution timelines. Industry-specific forecast inputs included air-laid process efficiency curves and EU packaging Extended Producer Responsibility fee-structure phase-ins.
Decision-makers should treat outputs as directional under assumptions of steady EU Green Deal enforcement and stable pulp fiber trade flows; material deviation in regulatory timelines or Baltic Sea logistics capacity would warrant model refresh. Practitioners should keep alternative scenarios live as national EPR scheme implementations and compostability certification backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food and Grocery Retail Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Rotisseries Market
Food Service
One-Off Chopsticks Market
Food Service
Benelux Foodservice Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
United States Full Service Restaurants Market
Food Service
GCC Online Grocery Market
Food Service
Restaurant Griddle Market
Food Service
Undercounter Ice Makers Market
Food Service
Limited-Service Restaurants Market
Food Service
Halal Food and Beverages Market
Food Service
UAE Food Service Market
Food Service
Global Digital Food Delivery Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Europe Out of Home (OOH) Delivery Market