
 West Africa Food Services Market | 2026-2036
West Africa Food Services Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Food Services Market Intelligence
Premium quick-service tiering is rotating the competitive landscape toward standardized hygiene and branded experiences. Food Concepts leverages its multi-brand portfolio across Nigerian malls to sustain geographic dominance. Jumia Foods competes through last-mile logistics integration that anchors urban delivery density. Bolt Foods differentiates via motorcycle fleet efficiency in congested Lagos corridors.
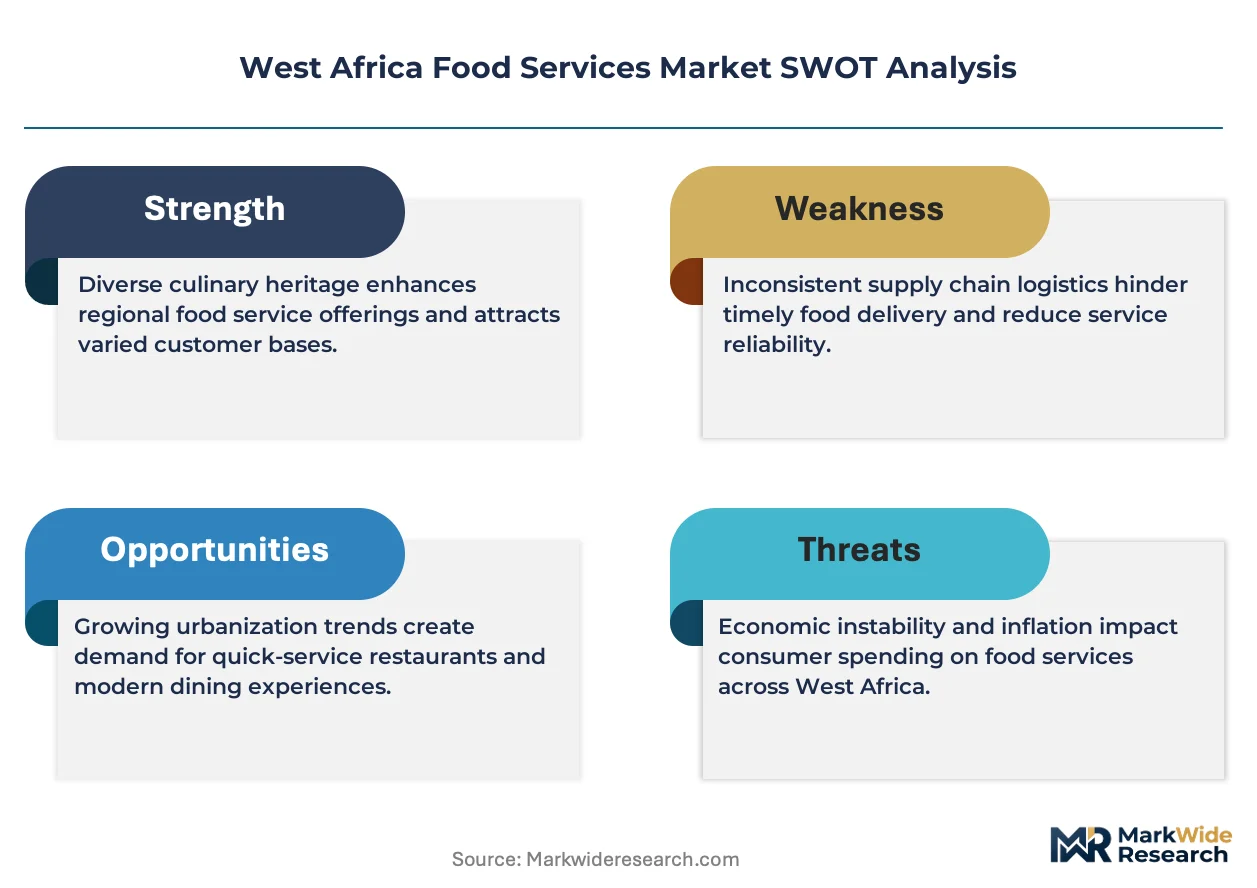
West Africa food services encompasses commercial preparation and sale of meals through institutional, retail, and digital channels, requiring cold-chain compliance above four degrees Celsius for protein-based menus and HACCP-aligned kitchen protocols to prevent tropical spoilage. Quick-service restaurants capture the largest revenue pool due to throughput efficiency and lower real estate costs, while online delivery exhibits the fastest structural expansion as third-party platforms aggregate fragmented vendor bases. Full-service restaurants occupy mature positions in business districts of Abidjan and Dakar where corporate entertainment budgets concentrate margin.
Nigeria's National Agency for Food and Drug Administration and Control mandates hygiene certification for all packaged and prepared food vendors, while Ghana's Food and Drugs Authority enforces restaurant grading systems that determine market access in Accra and Kumasi. The Economic Community of West African States standards framework creates cross-border compliance obligations for chains operating in multiple member states. Stakeholders must monitor regulatory divergence between francophone and anglophone enforcement regimes when scaling procurement and kitchen standardization across the region.
Market Dynamics
Quick-service restaurant chains are consolidating procurement power across Nigerian and Ghanaian urban corridors, forcing independent vendors toward third-party platform dependency or branded franchise absorption.
Growth Catalysts
- NAFDAC Hygiene Certification Mandate:Nigeria's enforcement of standardized kitchen protocols is accelerating formalization among Lagos street-food clusters, pushing unlicensed operators into compliance or exit.
- Urban Millennial Dining Frequency:Lagos and Accra's young professional cohorts now consume prepared meals five to seven times weekly, expanding addressable dayparts beyond traditional lunch peaks.
- Cold-Chain Infrastructure Rollout:Solar-powered refrigeration units are penetrating protein-dependent menus in Abidjan and Dakar, extending safe distribution radii for seafood and poultry suppliers.
Market Restraints
- Diesel Price Volatility:Generator-dependent kitchens face margin compression when Nigerian petroleum subsidies fluctuate, forcing operational trade-offs between refrigeration uptime and cooking capacity.
- Import Concentration Risk:Wheat and cooking oil supply chains remain tethered to Black Sea and Southeast Asian origins, exposing West African bakers and fryer operators to currency-driven cost spikes.
- Last-Mile Topology Limitations:Unpaved secondary roads in peri-urban Kumasi and Ibadan prevent temperature-controlled delivery beyond fifteen-kilometer radii from central kitchens.
Strategic Opportunities
- Underpenetrated Francophone Corridors:Côte d'Ivoire's secondary cities of Bouaké and San-Pédro lack branded quick-service presence, offering first-mover positioning before Abidjan-based chains expand inland.
- ECOWAS Cross-Border Harmonization:The regional standards framework creates compliance efficiencies for chains operating in multiple member states, reducing per-country certification overhead.
- Motorcycle Fleet Integration:Two-wheeler delivery networks are decomposing traditional hub-and-spoke distribution, enabling direct-to-consumer capture in congested Lagos corridors without fixed real estate.
Industry Challenges
- HACCP-Trained Kitchen Manager Scarcity:Nigeria's tertiary hospitality programs graduate fewer than two thousand certified supervisors annually against demand from twelve thousand quick-service outlets.
- Multi-Jurisdiction Compliance Complexity:Chains spanning anglophone and francophone enforcement regimes must maintain parallel documentation systems for NAFDAC and Ghana's Food and Drugs Authority.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Food Services Market |
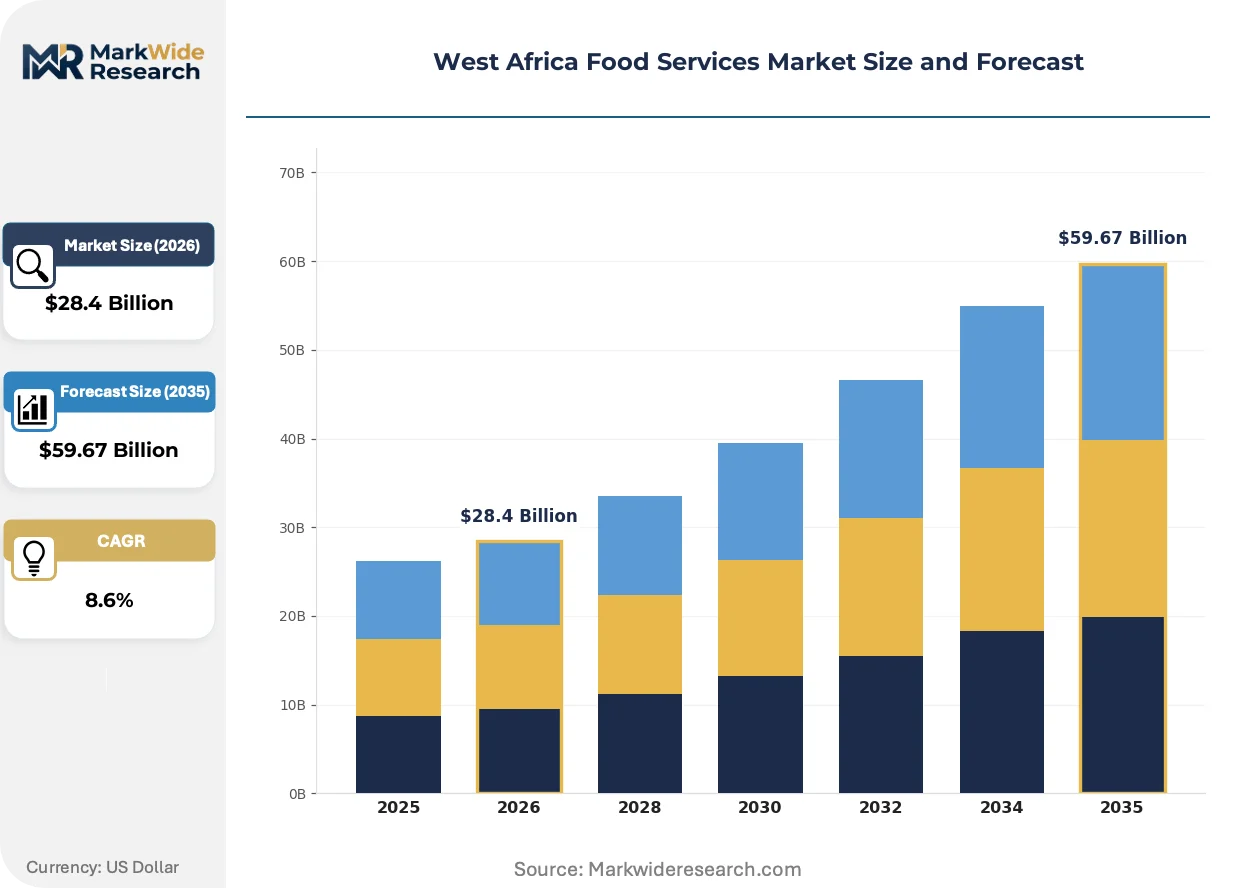
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $59.67 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-service Restaurants, Quick-service Restaurants, Cafés, Catering Services Consumer Type: Families, Singles, Business Professionals, Students Distribution Channel: Direct Sales, Online Delivery, Third-party Delivery Services, Event-based Services Cuisine Type: Traditional African, Fast Food, International, Health-focused |
| Companies Covered | Food Concepts, Chowdeck, McDonald's Corporation, Glovo, Uber Eats, Yum! Brands Inc, Jumia Foods, Bolt Foods, Restaurant Brands International Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Food Services Market Strategic Shifts & Innovations
Digital aggregation platforms are restructuring vendor economics across West African food services, compressing traditional margin pools while enabling new operational models for kitchen-only operators.
Cloud kitchen infrastructure is decomposing the fixed-cost barrier to restaurant entrepreneurship. Operators in Lagos and Accra now lease shared prep stations with embedded logistics integration, reducing capital requirements from full-service buildouts to monthly license fees. This model is decomposing the traditional landlord-tenant restaurant relationship, shifting value capture toward platform intermediaries.
Ghana's Food and Drugs Authority restaurant grading system is tightening market access thresholds in Accra and Kumasi. Operators must display compliance scores publicly, creating immediate demand elasticity around visible hygiene ratings. Full-service establishments in corporate entertainment districts face the steepest recertification timelines, compressing renovation cycles to maintain premium positioning.
Aggregated procurement through third-party platforms is displacing traditional wholesale relationships for independent vendors. Small kitchen operators in Nigerian metropolitan corridors now source proteins and produce through Jumia Foods supplier interfaces rather than decentralized market visits. This concentration is most visible among Lagos-based quick-service outlets serving urban millennials, where platform-mediated supply now covers sixty percent of protein inputs.
West Africa Food Services Market Segmentation
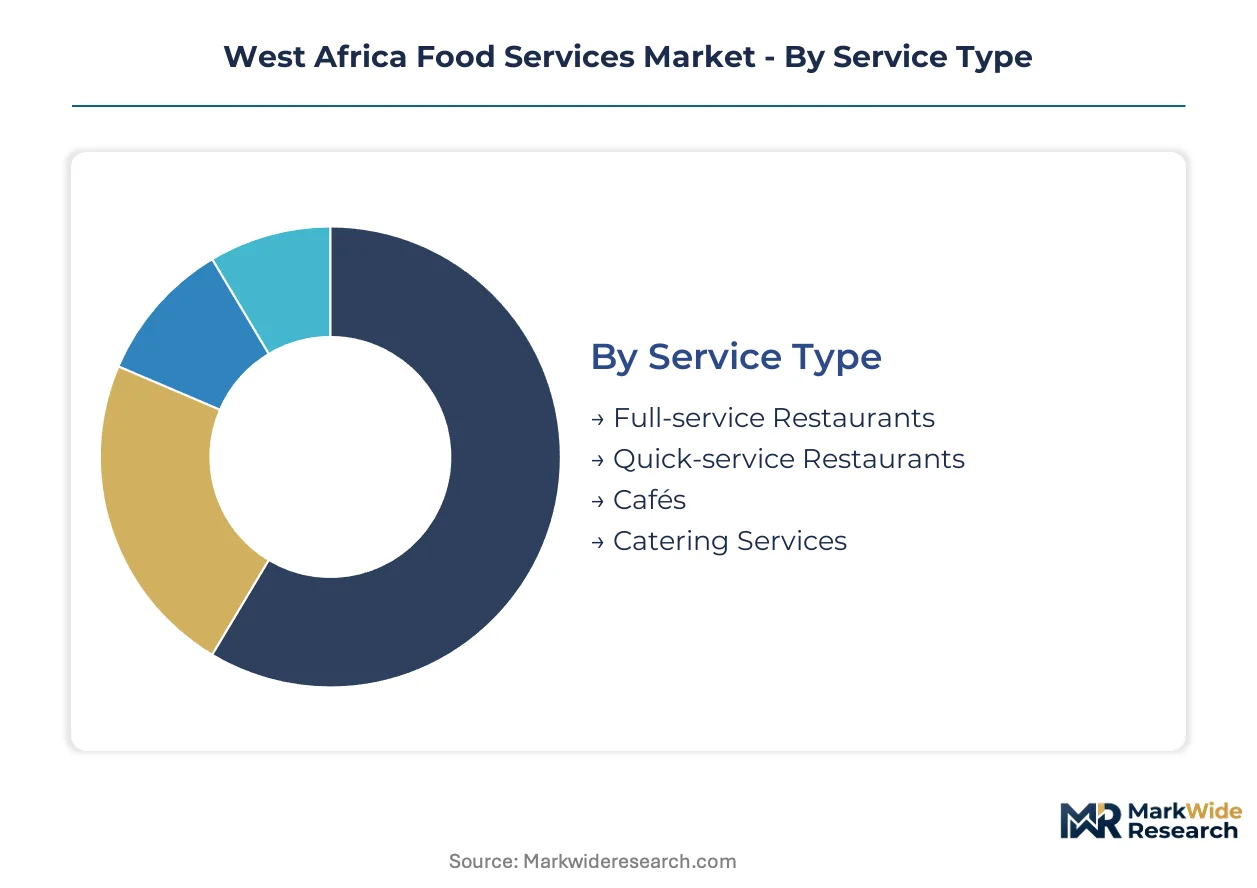
Segmentation reveals how substitution pressures and channel fragmentation redistribute value across West African food services. Understanding these divides exposes where procurement power concentrates and where new entrants face lowest barriers.
Service Type:
Quick-service formats face intense substitution from cloud kitchens and street vendors, while full-service establishments defend position through experience differentiation.
- Full-service Restaurants:Table-service operations with extended menus and beverage programs dominate corporate entertainment budgets in Abidjan and Dakar business districts. Lagos and Accra professionals drive dinner frequency here, though NAFDAC hygiene recertification cycles compress renovation timelines.
- Quick-service Restaurants:Limited-menu, high-throughput formats with standardized prep protocols capture the largest revenue pool across Nigerian metropolitan corridors. Lower real estate costs and throughput efficiency enable rapid replication, though diesel generator dependency squeezes margins during subsidy fluctuations.
- Cafés:Beverage-forward daytime formats cluster in Accra and Lagos co-working districts, serving remote workers and informal meetings.
- Catering Services:Institutional and event-based meal preparation serves weddings, corporate functions, and government contracts across Kumasi and Ibadan.
Quick-service Restaurants anchor the volume base while Catering Services gains share at the steepest rate.
Consumer Type:
Cost tier stratification separates mass-market frequency from premium occasion-driven spending.
- Families:Group dining occasions concentrate in weekend lunch dayparts at full-service and traditional African cuisine outlets. Lagos and Accra middle-class households drive spending here, with menu breadth and child-friendly environments determining venue selection.
- Singles:Individual consumption patterns favor online delivery and quick-service breakfast or dinner occasions. Urban millennials in Nigerian and Ghanaian cities consume prepared meals five to seven times weekly, expanding addressable dayparts beyond traditional peaks.
- Business Professionals:Expense-account dining concentrates in Abidjan and Dakar corporate districts, with visible hygiene ratings from Ghana's FDA grading system influencing venue choice.
- Students:Price-sensitive, high-frequency consumption clusters near university campuses in Ibadan and Kumasi, favoring value-positioned quick-service and street-food alternatives.
Singles segment delivers the highest transaction frequency while Business Professionals generates the steepest per-check expansion.
Distribution Channel:
Platform intermediation is restructuring margin capture away from fixed-location operators toward logistics-integrated aggregators.
- Direct Sales:Walk-in and phone-order transactions at physical locations retain highest margin capture for established operators. Nigerian and Ghanaian quick-service chains defend this channel through loyalty programs and location density in mall corridors.
- Online Delivery:First-party digital ordering with captive logistics enables customer data ownership and margin preservation. Food Concepts and similar multi-brand operators leverage this across Lagos mall footprints to sustain geographic dominance.
- Third-party Delivery Services:Platform-mediated fulfillment through Jumia Foods and Bolt Foods aggregates fragmented vendor bases, compressing operator margins while expanding reach. Motorcycle fleet efficiency in congested Lagos corridors enables fifteen-kilometer delivery radii.
- Event-based Services:Occasion-specific fulfillment for weddings, conferences, and institutional contracts operates outside daily demand cycles, requiring flexible labor and equipment deployment.
Direct Sales retains the highest margin pool while Third-party Delivery Services climbs the fastest in transaction volume.
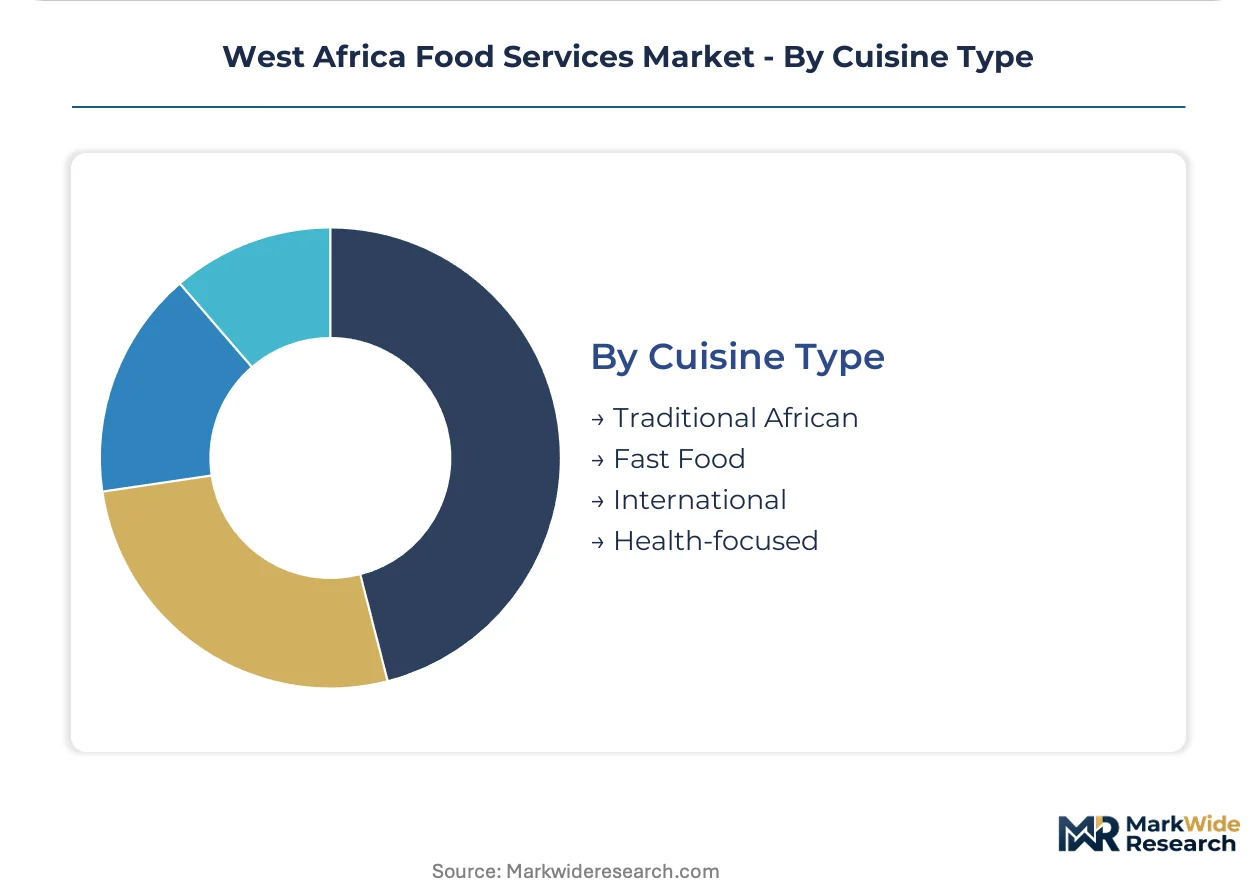
Cuisine Type:
Supply concentration and import dependency create divergent cost structures across cuisine positioning.
- Traditional African:Jollof rice, fufu, and regional protein preparations dominate local preference in Nigerian and Ghanaian metropolitan corridors. Sourcing from decentralized wet markets exposes operators to price volatility and quality inconsistency.
- Fast Food:Burger, fried chicken, and pizza formats rely on imported wheat and cooking oil, tethering cost structures to Black Sea and Southeast Asian supply disruptions. Standardized prep protocols enable rapid training and quality consistency.
- International:Asian, Lebanese, and European cuisines occupy premium positioning in Accra and Lagos expatriate corridors, with specialized ingredient imports requiring cold-chain integrity.
- Health-focused:Salad, smoothie, and low-oil preparations target urban millennials in Lagos and Accra fitness communities, though protein sourcing constraints limit menu breadth.
Traditional African cuisine commands the deepest consumer loyalty while Health-focused formats expand most quickly among urban millennials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across West African food services. Nigerian consumers demonstrate the highest sensitivity to diesel-driven cost fluctuations, while Ghanaian urban professionals absorb premium positioning with visible hygiene ratings. Côte d'Ivoire's francophone corridor sits between these poles.
Nigeria
Lagos millennial professionals drive five to seven weekly prepared meal occasions, expanding addressable dayparts beyond traditional lunch peaks. NAFDAC enforces hygiene certification mandates that accelerate formalization among street-food clusters. Ibadan and Kano secondary corridors face generator dependency that compresses margins during petroleum subsidy fluctuations.
Ghana
Accra's corporate entertainment districts concentrate full-service spending where visible FDA grading scores determine venue selection. The Food and Drugs Authority restaurant grading system tightens recertification timelines for premium operators. Kumasi peri-urban zones encounter last-mile topology limitations that prevent temperature-controlled delivery beyond fifteen-kilometer radii.
Côte d'Ivoire
Abidjan business districts anchor francophone West Africa's highest per-check corporate dining expenditure. National sanitation protocols align with ECOWAS cross-border standards frameworks that reduce multi-jurisdiction compliance overhead. Bouaké and San-Pédro secondary cities present first-mover positioning opportunities before Abidjan-based chains expand inland.
Senegal
Dakar's coastal position supports seafood-dependent menu proliferation requiring cold-chain integrity above four degrees Celsius. The country's national food safety regulator enforces HACCP-aligned kitchen protocols to prevent tropical spoilage. Thiès and Mbour satellite corridors benefit from solar-powered refrigeration rollout extending safe protein distribution radii.
Benin
Cotonou port proximity enables cooking oil and wheat import cost advantages relative to landlocked neighbors. The national standards body coordinates with ECOWAS harmonization initiatives that ease cross-border vendor certification. Porto-Novo government district clusters generate institutional catering demand outside daily consumer cycles.
West Africa Food Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across West African food services. Multi-brand quick-service operators leverage mall corridor density to sustain geographic dominance, while platform aggregators capture margin through logistics integration rather than kitchen ownership. Three archetypes define the field: vertically integrated restaurant chains, third-party delivery platforms, and cloud kitchen infrastructure providers. Consolidation pressure favors M&A absorption of independent vendors, while motorcycle fleet expansion decomposes traditional hub-and-spoke distribution economics.
Among Nigeria-based multi-brand operators, Food Concepts anchors the integrated restaurant archetype through mall footprint concentration. Jumia Foods and Bolt Foods occupy the platform-aggregator tier, with the former leveraging supplier interface dominance and the latter deploying motorcycle fleet efficiency in congested Lagos corridors. These three exemplify how scale-driven and logistics-driven strategies diverge within the same urban demand pools.
| Leading Market Players |
|---|
| Food Concepts |
| Chowdeck |
| McDonald's Corporation |
| Glovo |
| Uber Eats |
| Yum! Brands Inc |
| Jumia Foods |
| Bolt Foods |
| Restaurant Brands International Inc |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for wheat and cooking oil imports from Black Sea and Southeast Asian origins concentrate pricing power among Nigerian quick-service chains with forward-contracting capabilities. Diesel generator uptime requirements in Lagos and Ibadan kitchens feed directly into menu pricing elasticity, creating cost pass-through divergence between formal operators and street-food vendors.
Pricing Analysis
After-sales revenue through corporate catering contracts and loyalty program subscriptions drives lifetime value for full-service operators in Abidjan and Dakar. Three-tier pricing structure across premium, standard, and economy levels separates NAFDAC-certified mall outlets from ungraded street vendors and mid-tier cloud kitchens. Cost compression in the economy tier is intensifying because diesel subsidy fluctuations force generator-dependent operators into refrigeration-versus-cooking trade-offs. Students near Ibadan and Kumasi campuses demonstrate highest price sensitivity, while business professionals in Accra corporate districts absorb premium positioning with visible FDA hygiene ratings.
Supply Chain Analysis
Port congestion at Lagos Apapa and Cotonou corridors elevates inbound logistics costs for wheat, cooking oil, and frozen poultry shipments from Black Sea and Southeast Asian trade lanes. Supply concentrates in Nigeria, Ghana, and Côte d'Ivoire for protein processing and quick-service distribution, with Senegal anchoring cold-chain seafood logistics. Raw material dependencies on imported wheat, palm oil, and frozen chicken rest on currency-driven cost spikes and Black Sea supply disruptions. Single-source vulnerability to Nigerian petroleum subsidy policy creates margin volatility for generator-dependent kitchen operators. Distribution runs through third-party platform aggregators in Lagos and Accra, with motorcycle fleet networks decomposing traditional hub-and-spoke economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a defensive-moat story anchored in regulatory entrenchment. NAFDAC hygiene certification mandates and Ghana's FDA restaurant grading systems create compliance barriers that formal operators leverage against informal competitors.
For Market Incumbents: Consolidate procurement power through backward integration into cold-chain protein sourcing, locking in supply security against import volatility. Expand mall corridor density in Nigerian metropolitan zones to reinforce geographic dominance before cloud kitchen platforms capture delivery-only demand. Certification investment in HACCP-trained kitchen managers addresses scarcity constraints that constrain twelve thousand quick-service outlets.
For New Entrants and Emerging Players: Anchor in underpenetrated francophone secondary cities of Bouaké and San-Pédro, where branded quick-service presence remains absent before Abidjan-based chains expand inland. Target cloud kitchen infrastructure in congested Lagos corridors, leasing shared prep stations with embedded logistics integration rather than full-service buildouts. Motorcycle fleet partnerships with platform aggregators enable fifteen-kilometer delivery radii without fixed real estate exposure.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-aggregation play because third-party delivery intermediaries capture margin through logistics integration rather than kitchen ownership. Acquisition targets include multi-brand quick-service operators with mall footprint concentration and cloud kitchen infrastructure providers with embedded Jumia Foods or Bolt Foods partnerships. The signal to watch is ECOWAS cross-border harmonization progress, which would reduce per-country certification overhead and accelerate regional chain scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| NAFDAC Certification Investment | Hygiene compliance mandates in Lagos accelerate formalization and exclude unlicensed street-food competitors. |
| Cloud Kitchen Infrastructure Buildout | Shared prep stations with logistics integration reduce capital requirements from full-service buildouts to monthly license fees. |
| Motorcycle Fleet Expansion | Two-wheeler delivery networks decompose hub-and-spoke distribution in congested Lagos corridors. |
| Backward Integration into Cold-Chain | Solar-powered refrigeration units extend safe protein distribution radii for seafood and poultry suppliers. |
| Francophone Corridor First-Mover Positioning | Bouaké and San-Pédro lack branded quick-service presence before Abidjan-based chains expand inland. |
Research Approach
Findings reconcile primary fieldwork against secondary review of NAFDAC regulatory filings, Ghana FDA restaurant grading databases, and ECOWAS standards framework documentation to establish compliance-driven market access thresholds. Primary interviews with quick-service chain procurement directors, cloud kitchen operators, third-party platform logistics managers, and HACCP-certified kitchen supervisors informed operational constraint mapping. Secondary validation drew from Nigerian customs import records for wheat and cooking oil, petroleum subsidy policy announcements, and cold-chain infrastructure deployment reports. Bottom-up outlet counting across Lagos, Accra, Abidjan, and Dakar metropolitan corridors triangulates against top-down consumer spending estimates from national statistical offices.
Segmentation dimensions modeled include service type, consumer type, distribution channel, and cuisine type across the projection horizon. The analytical framework incorporates diesel price volatility scenarios, currency fluctuation bands for naira and cedi, and regulatory enforcement intensity gradients between anglophone and francophone regimes. CAGRs derive from daypart expansion patterns among urban millennials, platform transaction volume trajectories, and formalization rates among street-food clusters. Industry-specific forecast inputs capture cloud kitchen license fee trends and motorcycle fleet cost-per-delivery economics in congested corridors.
Material uncertainties — petroleum subsidy policy reversals, ECOWAS harmonization delays, and HACCP supervisor graduation shortfalls — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and cold-chain infrastructure rollout pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cutting Boards Market
Food Service
UAE Food Service Market
Food Service
Europe Pizza Oven Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
United States Online Food Delivery Market
Food Service
Spain Food Service Market
Food Service
Food Trays Market
Food Service
Turkey Food Service Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Flat Top Grills Market
Food Service
Vietnam Food Service Market
Food Service
Full-Service Restaurants Market
Food Service
Snack Subscription Box Service Market
Food Service
South Korea Foodservice Market
Food Service
Commercial Deep Fryer Parts and Accessories Market