
 Sandwich Toasters Market | 2026-2036
Sandwich Toasters Market Size, Share, and Industry Trends Forecast 2026-2036
Sandwich Toasters Market Analytics
Bundle configurations pairing sandwich toasters with interchangeable grill plates and waffle inserts is expanding buyer choice across retail channels. Philips leverages its kitchen appliance ecosystem to sustain premium positioning in European and Asian markets. Breville anchors its competitive stance through specialized high-wattage models targeting café-grade output. Hamilton Beach competes on volume manufacturing scale, occupying mass-market shelf space across North American big-box retailers.
A sandwich toaster is an electrically heated or manually operated countertop appliance with hinged clamshell plates, typically rated between 700 and 1500 watts, designed to seal, toast, or grill filled bread sandwiches through simultaneous top-and-bottom contact heating. Its primary commercial purpose spans residential breakfast preparation and food-service operations requiring rapid, consistent output with minimal operator skill. Electric variants dominate unit shipments given plug-and-play convenience, though multifunctional designs incorporating grill, waffle, and panini functions command higher margin pools. Stainless steel construction leads material preferences in commercial end-user segments for durability and sanitation compliance, while non-stick coatings retain residential share through ease-of-cleaning appeals.
CE marking under EU safety directives, FCC electromagnetic emissions standards in the United States, and BIS certification for Indian electrical goods collectively govern product compliance and market access. These frameworks elevate testing costs for new entrants while rewarding incumbents with established certification pipelines. Stakeholders must monitor evolving energy-efficiency thresholds and right-to-repair disclosure mandates that will reshape design priorities and aftermarket service obligations.
Market Dynamics
Energy-efficiency labeling mandates from the European Union and North America are forcing appliance manufacturers to redesign heating elements and insulation systems, compressing margin structures while accelerating R&D cycles for compliant product lines.
Growth Catalysts
- Cloud kitchen proliferation:Delivery-first food-service operators in India and Southeast Asia are standardizing compact, high-throughput sandwich toasters for rapid menu execution.
- CE marking convergence:Unified EU safety directives reduce retesting burdens for manufacturers selling across member states, streamlining cross-border market access.
- Interchangeable plate systems:Modular designs allowing grill, waffle, and panini functions in single units are expanding average selling prices in residential channels.
Market Restraints
- Stainless steel price volatility:Raw material input swings for commercial-grade housing construction compress margin predictability for durability-focused product lines.
- Non-stick coating supply concentration:Fluoropolymer supply chains cluster among limited specialty chemical producers, creating single-source vulnerability.
- Manual appliance substitution:Stovetop sandwich presses and cast-iron alternatives retain cost-sensitive segments in regions with unreliable electricity access.
Strategic Opportunities
- Right-to-repair mandates:Emerging EU disclosure requirements for spare parts availability create aftermarket service revenue streams for established brands with distribution networks.
- Urban electrification corridors:Tier-2 and Tier-3 Indian cities expanding grid connectivity represent underpenetrated addressable bases for entry-level electric units.
- Smart kitchen integration:Convergence of app-based temperature control with voice-assistant compatibility opens premium positioning in connected-home ecosystems.
Industry Challenges
- BIS certification timelines:Indian electrical goods testing protocols create 4-6 month approval delays that complicate new product launch scheduling.
- Heating element integration complexity:Embedding ceramic and infrared technologies into legacy clamshell architectures requires retooling manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandwich Toasters Market |
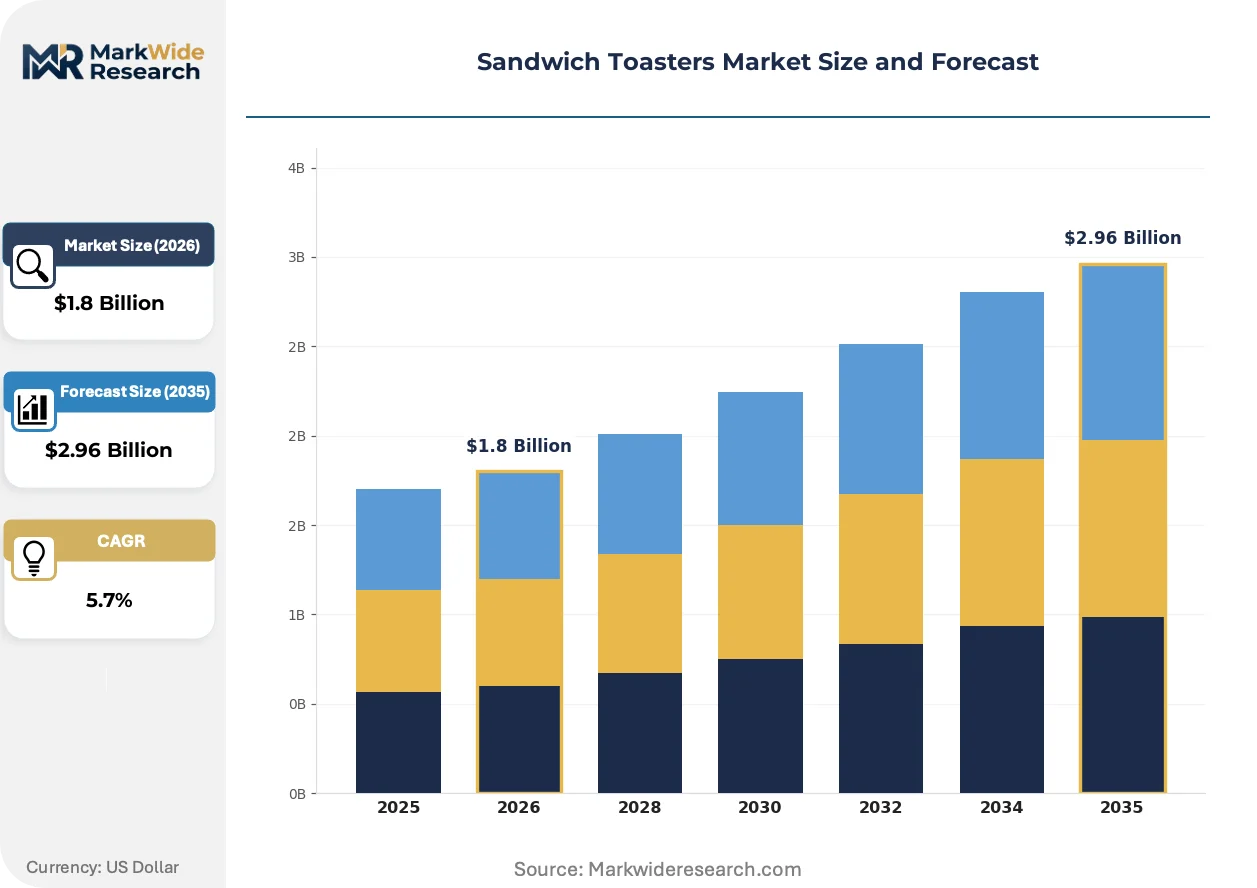
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Multifunctional, Commercial End User: Residential, Cafes, Restaurants, Food Trucks Design: Vertical, Horizontal, Compact, Unconventional Material: Stainless Steel, Non-stick, Aluminum, Plastic |
| Companies Covered | Philips, Breville, Panasonic, Hamilton Beach, De'Longhi, Russell Hobbs, Morphy Richards, Cuisinart, Bajaj Electricals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandwich Toasters Market Evolving Landscape
Ceramic infrared heating elements are displacing traditional coil systems across mid-tier and premium product lines, while regulatory pressure on energy consumption intensifies design constraints. These forces are compressing product lifecycles and rewarding agile supply chains.
Infrared quartz technology is rewriting thermal efficiency benchmarks in sandwich toaster engineering. Quick-service restaurants in Germany and the United Kingdom are adopting these systems at twice the rate of full-service establishments. The shift is compressing payback periods for energy-intensive commercial operators while raising barriers for manufacturers lacking ceramic sourcing relationships.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon use in insulating foams and refrigerant-adjacent components. Appliance manufacturers must reformulate thermal barrier materials or source alternative blowing agents. Commercial-grade product lines targeting Scandinavian markets face the steepest compliance costs due to earlier national implementation timelines.
Direct-to-cloud-kitchen distribution models are disintermediating traditional food-service equipment dealers in India and Indonesia. Procurement teams at delivery-aggregator-backed kitchens now source through B2B platforms with consolidated logistics. This channel compression is most visible in Bangalore and Jakarta, where centralized procurement hubs aggregate demand from 50-plus virtual brands under single purchasing agreements.
Sandwich Toasters Market Segmentation
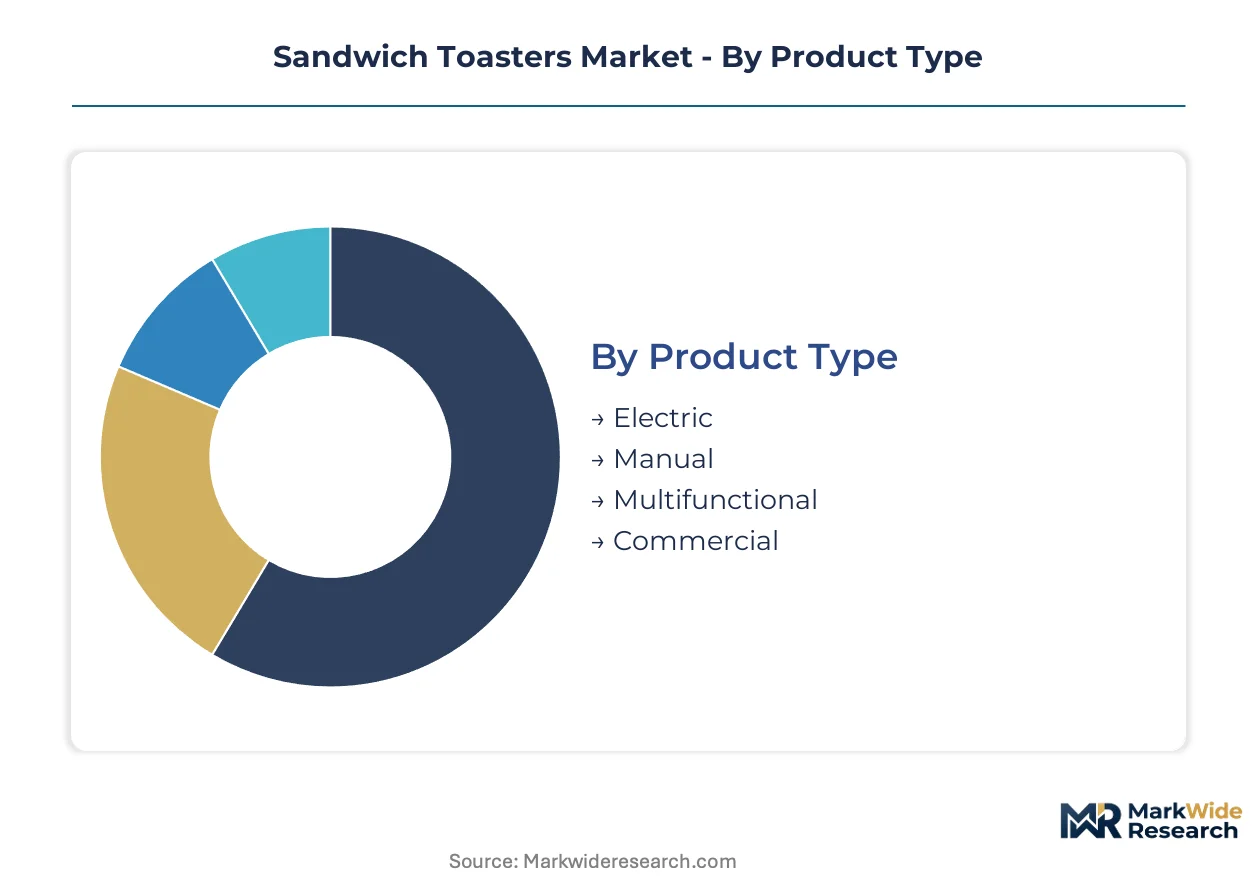
Segmentation in the sandwich toasters market reflects divergent thermal engineering requirements between home kitchens and commercial food-service environments. Product architecture, material selection, and power specifications vary sharply across these use cases, creating distinct margin pools and certification pathways.
Product Type:
Heating element technology defines the core specification axis, separating plug-in electric systems from manually operated alternatives.
- Electric:Coil or ceramic infrared elements rated 700–1500 watts dominate unit shipments. Cloud kitchens in India and Indonesia standardize these for rapid throughput with minimal operator training.
- Manual:Stovetop presses and cast-iron alternatives retain share in regions with unreliable grid access. Cost-sensitive households in rural Southeast Asia favor these for zero electricity dependency.
- Multifunctional:Modular plate systems enabling grill, waffle, and panini functions command premium pricing in European residential channels.
- Commercial:High-wattage stainless steel units with reinforced hinges target café-grade durability and sanitation compliance.
Electric leads on scale; multifunctional leads on momentum.
End User:
Volume concentration and procurement authority split sharply between dispersed residential buyers and consolidated food-service operators.
- Residential:Individual households purchasing through retail channels prioritize compact footprints and non-stick coatings for ease of cleaning.
- Cafes:Independent coffee shops in Germany and the United Kingdom drive demand for infrared quartz systems with compressed payback periods.
- Restaurants:Quick-service chains standardize high-throughput units with interchangeable plates for menu flexibility.
- Food Trucks:Mobile operators require compact vertical designs with low power draw for generator compatibility.
Residential commands absolute volume; food trucks are climbing fastest as delivery-aggregator fleets expand.
Design:
Spatial constraints in target environments dictate plate orientation and housing dimensions, with vertical formats gaining share in space-constrained settings.
- Vertical:Upright storage-friendly configurations suit small-apartment kitchens in Japanese and South Korean urban centers.
- Horizontal:Traditional clamshell layouts remain standard for commercial throughput where bench space is available.
- Compact:Single-serving units with reduced plate dimensions target solo households and office pantry installations.
- Unconventional:Triangular or circular plate geometries serve niche aesthetic preferences in design-forward European markets.
Horizontal retains installed base dominance; vertical formats gain share fastest in high-density Asian housing.
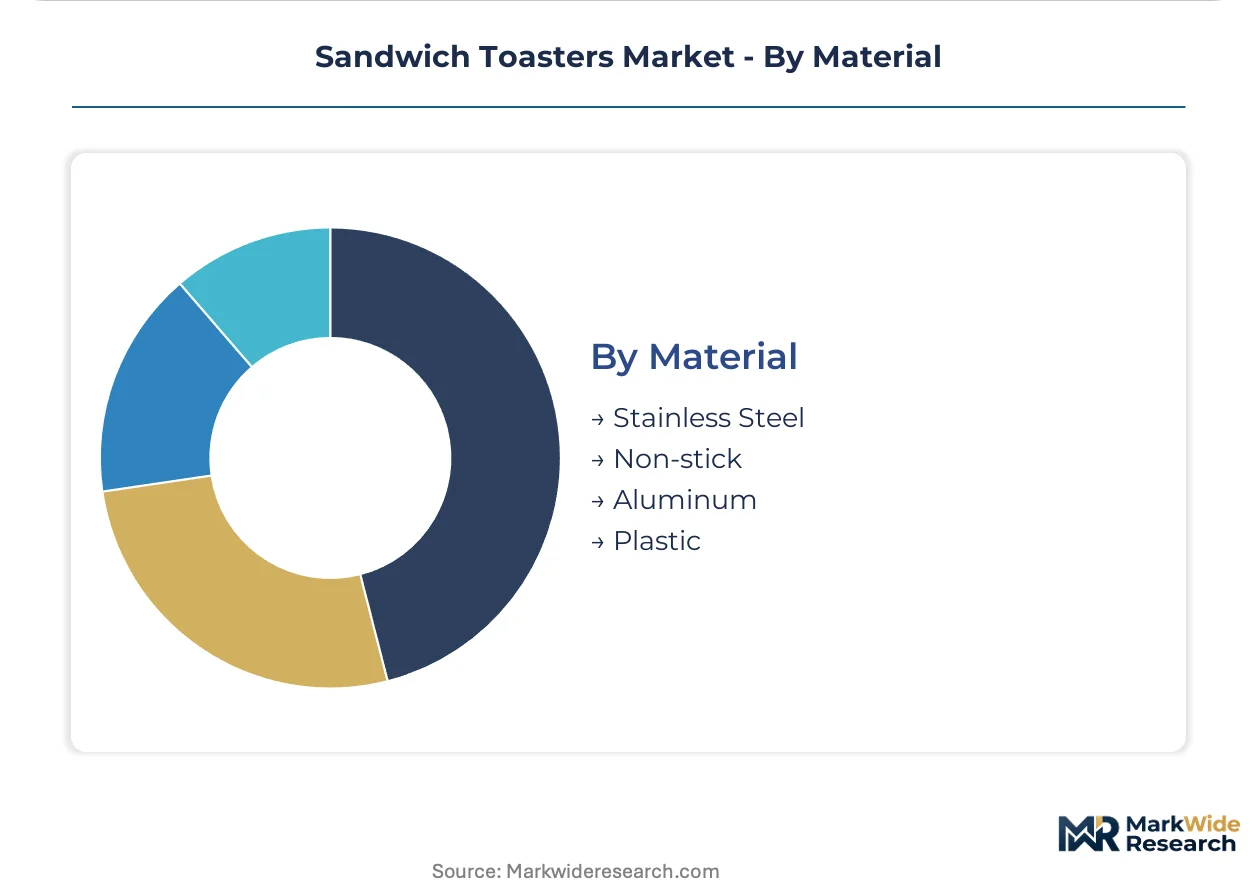
Material:
Durability requirements and regulatory exposure separate commercial-grade metal construction from residential polymer alternatives.
- Stainless Steel:AISI 304 and 430 grades dominate commercial end-use for corrosion resistance and dishwasher-safe sanitation compliance.
- Non-stick:Fluoropolymer and ceramic coatings reduce cleaning friction in residential settings, though EU F-Gas Regulation pressures reformulation.
- Aluminum:Die-cast housings offer thermal conductivity advantages at mid-tier price points for mass-market retail.
- Plastic:ABS and polypropylene exteriors minimize unit cost for entry-level electric models in price-sensitive Indian and Indonesian markets.
Stainless steel anchors commercial positioning; ceramic-coated alternatives are expanding most quickly amid fluoropolymer supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric sandwich toasters first achieved commercial scale in post-war American kitchens before diffusing through European appliance markets and finally penetrating electrifying Asian households during the late twentieth century.
United States
Cloud kitchen proliferation and quick-service restaurant standardization drive commercial procurement volumes. FCC electromagnetic emissions standards govern wireless-enabled smart models entering connected-home ecosystems. Equipment clusters concentrate in Chicago and Dallas logistics corridors serving national food-service distribution networks.
Germany
Café-grade infrared quartz adoption accelerates payback calculations for energy-intensive commercial operators. EU F-Gas Regulation phase-down schedules force thermal barrier material reformulation in insulating components. Manufacturing and R&D activity clusters around Stuttgart and Nuremberg precision engineering corridors.
India
Tier-2 and Tier-3 urban electrification expands addressable bases for entry-level electric units. BIS certification timelines create 4-6 month approval delays complicating new product launch scheduling. Bangalore and Jakarta procurement hubs aggregate demand from delivery-aggregator-backed virtual brands under centralized purchasing agreements.
United Kingdom
Independent coffee shops drive infrared quartz system adoption at twice the rate of full-service establishments. CE marking convergence under unified EU safety directives streamlines cross-border market access. London and Manchester distribution networks anchor B2B platform consolidation for food-service equipment procurement.
Indonesia
Delivery-first food-service operators standardize compact, high-throughput units for rapid menu execution. Manual stovetop presses retain cost-sensitive segments in regions with unreliable grid access. Jakarta centralized procurement hubs disintermediate traditional equipment dealers through direct-to-cloud-kitchen distribution models.
Sandwich Toasters Market Competitive Landscape
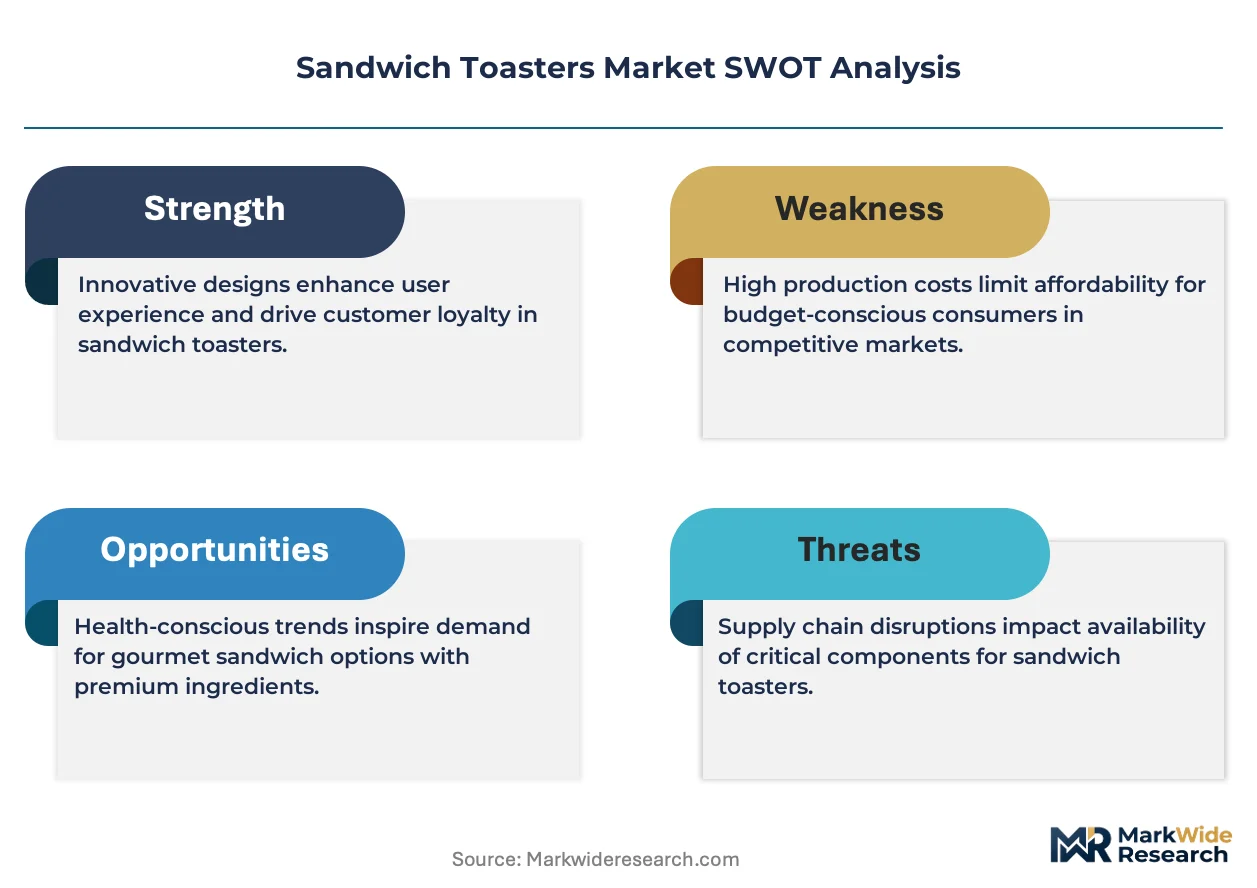
Premium-margin players sit above commodity-margin players across heating element technology and material specification tiers. The vendor base organizes around three strategic archetypes: diversified kitchen appliance conglomerates leveraging ecosystem synergies, specialized high-wattage commercial fabricators, and volume-scale mass-market manufacturers. Dominant competitive moves include portfolio diversification into modular plate systems and geographic expansion through B2B platform partnerships targeting cloud kitchen procurement hubs.
Among diversified appliance conglomerates, Philips and Panasonic exemplify ecosystem-anchored positioning across European and Asian residential channels. Breville occupies a specialist tier focused on café-grade output specifications. Hamilton Beach represents scale-driven mass-market penetration across North American big-box retail networks.
| Leading Market Players |
|---|
| Philips |
| Breville |
| Panasonic |
| Hamilton Beach |
| De'Longhi |
| Russell Hobbs |
| Morphy Richards |
| Cuisinart |
| Bajaj Electricals |
| Others |
Value Network & Pricing Analysis
Ceramic infrared heating element adoption simultaneously compresses production cost curves and concentrates supplier relationships among specialized thermal engineering firms in Germany and Japan. This technology transition rewards manufacturers with established ceramic sourcing pipelines while elevating qualification barriers for new entrants seeking equivalent thermal performance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates infrared quartz systems from coil-element mid-tier units and manual stovetop alternatives. Price differentiation hinges on wattage rating and CE certification tier, with EU F-Gas Regulation compliance adding cost layers to insulating components. Cost compression in economy tiers is intensifying because fluoropolymer supply constraints force coating reformulation. Cloud kitchen procurement teams in India exhibit highest price sensitivity; German café operators prioritize energy payback over upfront cost.
Supply Chain Analysis
Dual-sourcing requirements from major appliance OEMs mandate multi-supplier qualification for heating elements across China, Germany, and South Korea. Raw material dependencies center on ceramic substrates, stainless steel AISI 304, and fluoropolymer coatings. Single-source vulnerability concentrates in specialized infrared quartz manufacturing. Distribution runs through consolidated B2B platforms serving cloud kitchen hubs in Bangalore and Jakarta, bypassing traditional equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU energy-efficiency compliance costs and Indian electrification-driven volume expansion. Regulatory divergence creates manufacturing cost differentials exceeding material input variations.
For Market Incumbents: Hedge against fluoropolymer supply concentration by qualifying secondary ceramic-coating suppliers in Japan and South Korea. Deepen backward integration into heating element assembly to defend margin position amid stainless steel price volatility. Prioritize spare parts inventory buildout ahead of EU right-to-repair disclosure mandates. For New Entrants and Emerging Players: Launch via direct-to-cloud-kitchen distribution models in Tier-2 Indian cities where centralized procurement hubs aggregate demand from virtual brands. Target food truck and mobile operator segments with compact vertical designs; these buyers remain underserved by established brands focused on café-grade specifications. Emphasize generator-compatible low-wattage units as entry wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among manual appliance fabricators with established foundry relationships in rural Southeast Asia. Long-term viability favors electric unit manufacturers with BIS certification pipelines and ceramic element sourcing locked. Watch BIS approval timeline compression as inflection signal for Indian market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Infrared Technology Licensing | Accelerates payback periods for German café operators adopting energy-efficient heating systems. |
| Backward Integration into Heating Elements | Captures margin pool currently concentrated among Japanese and German thermal component specialists. |
| Cloud Kitchen Distribution Partnership | Locks procurement relationships with Bangalore and Jakarta aggregator-backed virtual brands. |
| EU Right-to-Repair Compliance Investment | Creates aftermarket service revenue streams through spare parts availability mandates. |
| Tier-2 India Manufacturing Footprint | Reduces landed cost for entry-level electric units serving electrifying urban households. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with appliance manufacturing executives, cloud kitchen procurement managers, thermal engineering specialists, and retail category buyers. Secondary validation draws from BIS certification databases, EU F-Gas Regulation filings, customs trade records, and food-service equipment distribution reports. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Granularity-level modeling disaggregates volume and value across heating element technology, end-user segment, material specification, and regional regulatory cluster throughout the forecast period. CAGRs derive from trend extrapolation of electrification rates, cloud kitchen proliferation curves, and energy-efficiency compliance cost trajectories. Industry-specific inputs include BIS approval timeline distributions and ceramic element adoption rates by commercial operator type.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions affecting stainless steel flows, abrupt fluoropolymer supply disruptions, and grid reliability deterioration in target electrification corridors. Forecasts reflect documented assumptions about regulatory implementation schedules and technology cost curves. Deviation in EU F-Gas Regulation enforcement intensity or Indian BIS streamlining would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Quick-Service Restaurants Market
Food Service
Meal Voucher Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Qatar Food Service Market
Food Service
Integrated Stove Market
Food Service
Europe Barbeque Grill Market
Food Service
Online Grocery Market
Food Service
Workplace Service Market
Food Service
Smokeless Grill Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
North America Food Service Disposable Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Flat Top Grills Market
Food Service
Stirrers Market
Food Service
South Korea Foodservice Market
Food Service
Europe Pizza Oven Market