
 Food Contract Manufacturing Market | 2026-2036
Food Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Food Contract Manufacturing Market Intelligence
The unbundling of manufacturing from brand ownership is hardening the divide between brand-focused CPG firms and specialized production partners. This allows food brands to focus on marketing while outsourcing complex production and supply chain logistics. Kerry Group Plc specializes in sophisticated formulation and ingredient systems for these brands. Archer Daniels Midland Company leverages its extensive agricultural commodity processing scale to offer cost-effective co-manufacturing solutions.
Food contract manufacturing involves outsourcing the production of food and beverage products to a third-party facility. These services range from specific processes like aseptic filling for beverages to full turnkey production, enabling brands to scale without capital investment in equipment. Within service types, private label manufacturing for supermarkets represents a mature, high-volume segment. Conversely, formulation services for novel products like functional snacks offer higher margin opportunities for specialized contractors.
Regulatory compliance is a critical function, governed by bodies like the US FDA and the European Food Safety Authority (EFSA). Adherence to global standards such as ISO 22000 is non-negotiable for market access and ensures food safety across outsourced supply chains. The key decision for food brands will be balancing cost-efficiency with the need for partners who possess advanced technological capabilities and robust quality assurance systems.
Market Dynamics
The shift toward asset-light business models among consumer packaged goods firms is the central force shaping the market. This trend accelerates demand for specialized partners capable of handling complex production for niche categories like plant-based foods, requiring both flexibility and stringent regulatory compliance.
Growth Catalysts
- Advanced Processing:High-Pressure Processing (HPP) extends shelf-life for clean-label products, driving demand for co-packers who have invested in this specialized equipment.
- DTC Brand Growth:Direct-to-consumer food brands require agile, small-batch production that is inefficient for large, self-owned manufacturing plants, fueling the need for flexible contractors.
- Allergen Management:Stricter regulations like the US FASTER Act push brands to outsource to certified, dedicated facilities to mitigate cross-contamination risks and ensure consumer safety.
Market Restraints
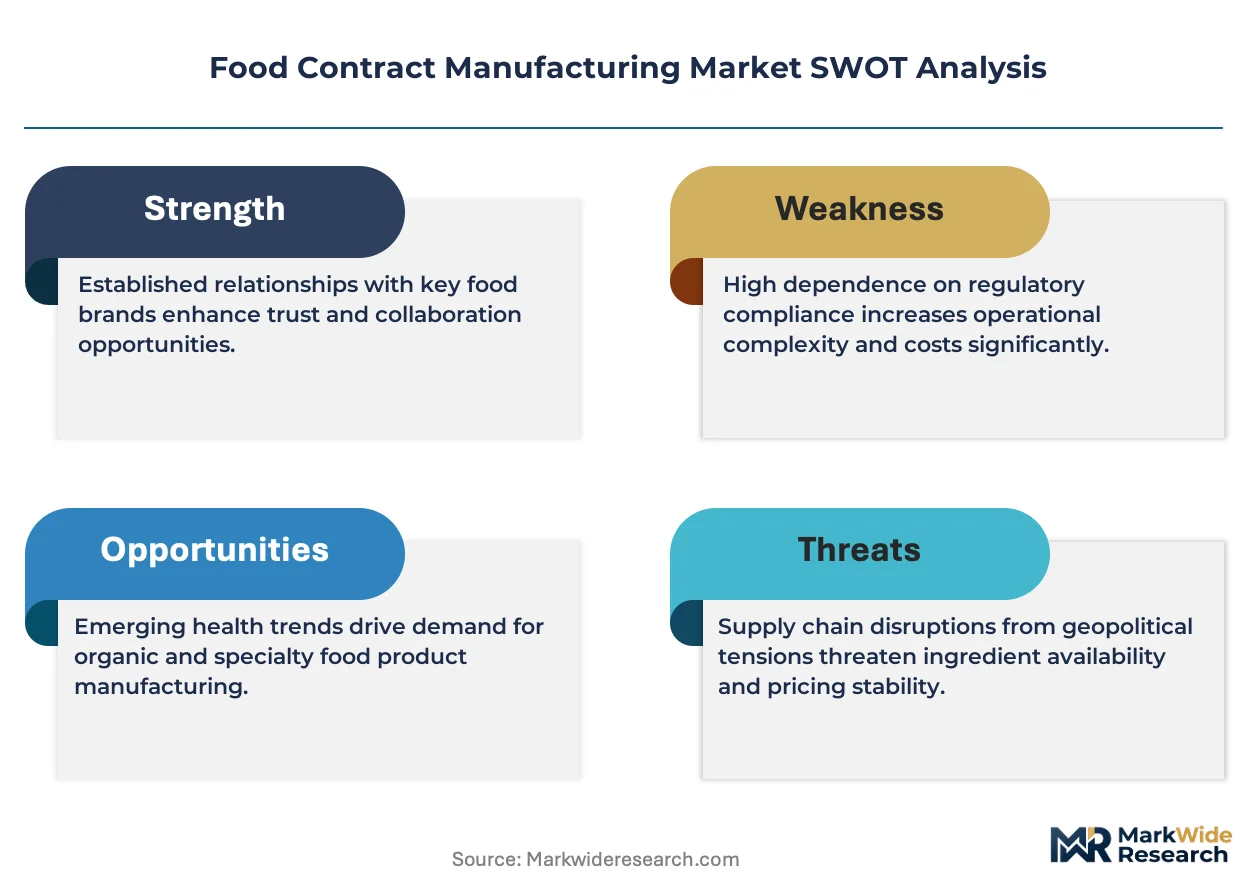
- Input Cost Volatility:Fluctuations in agricultural commodity and energy prices directly impact co-manufacturer margins, creating pricing instability for brand owners and complicating long-term contracts.
- Intellectual Property Risk:Fear of proprietary formulation or process theft remains a significant barrier for innovative brands considering outsourcing production to a third party.
- Capacity Constraints:A shortage of specialized capacity for aseptic filling or gluten-free baking creates production bottlenecks and limits partner choice for brands in high-growth segments.
Strategic Opportunities
- Geographic Expansion:Southeast Asian markets offer an underpenetrated region for sophisticated co-packing services, driven by rising local demand for convenience and processed foods.
- Service Expansion:Offering "concept-to-commercialization" services, including R&D and regulatory support, creates high-value partnerships beyond simple manufacturing.
- Traceability Technology:Integrating blockchain for supply chain traceability offers a premium service that meets brand and consumer demand for verifiable food safety data.
Industry Challenges
- Talent Scarcity:A persistent shortage of skilled food scientists and quality assurance professionals hampers the ability of contract manufacturers to scale operations effectively.
- Compliance Overhead:Maintaining certifications across multiple global standards like ISO 22000 and BRC requires significant investment in personnel and quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Contract Manufacturing Market |
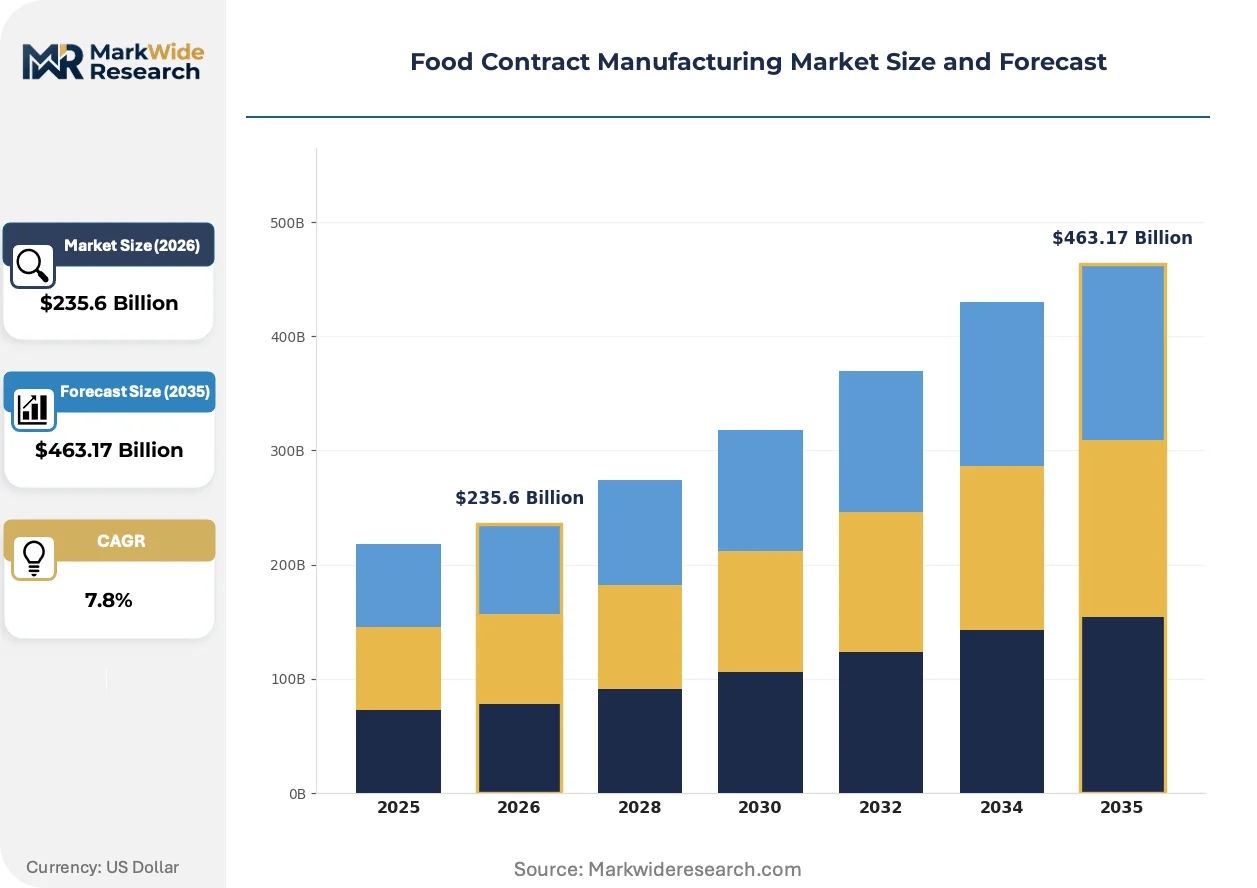
| Market Size in 2026 | $235.6 Billion |
| Market Size in 2035 | $463.17 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Dairy Products, Frozen Foods Service Type: Private Label, Co-Packing, Formulation, Packaging Distribution Channel: Online, Retail, Wholesale, Food Service End User: Restaurants, Supermarkets, Food Brands, E-commerce |
| Companies Covered | Kerry Group Plc, Döhler Group SE, Archer Daniels Midland Company, ConAgra Foods Inc., Bunge Limited, Cargill Inc., Nestlé S.A., Olam Nigeria Limited, Royal FrieslandCampina N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Contract Manufacturing Market Strategic Shifts & Innovations
Specialization and digitization are transforming the relationship between brands and their manufacturing partners. This evolution moves the dynamic from a transactional service to a deeply integrated, technology-enabled partnership focused on flexibility and speed to market.
Digital twin technology creates a virtual model of a production line to optimize processes and test new product runs without physical downtime. Large-scale co-manufacturers are adopting this to manage diverse client portfolios. This technology is modularizing production planning, allowing contractors to swap product configurations and packaging formats virtually before committing physical resources.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure on environmental and social impacts across value chains. This forces food brands to demand verifiable sustainability data from their manufacturing partners. Consequently, contract manufacturers must invest in carbon footprint tracking and ethical sourcing verification to retain contracts with large European CPG clients.
A clear shift from long-term, high-volume contracts toward flexible, on-demand service agreements is underway for new product introductions. This disrupts the traditional private label model, favoring agile contractors who can handle shorter, complex production runs. This pattern is most visible in North America’s functional beverage sector, where speed-to-market is a critical competitive advantage.
Food Contract Manufacturing Market Segmentation
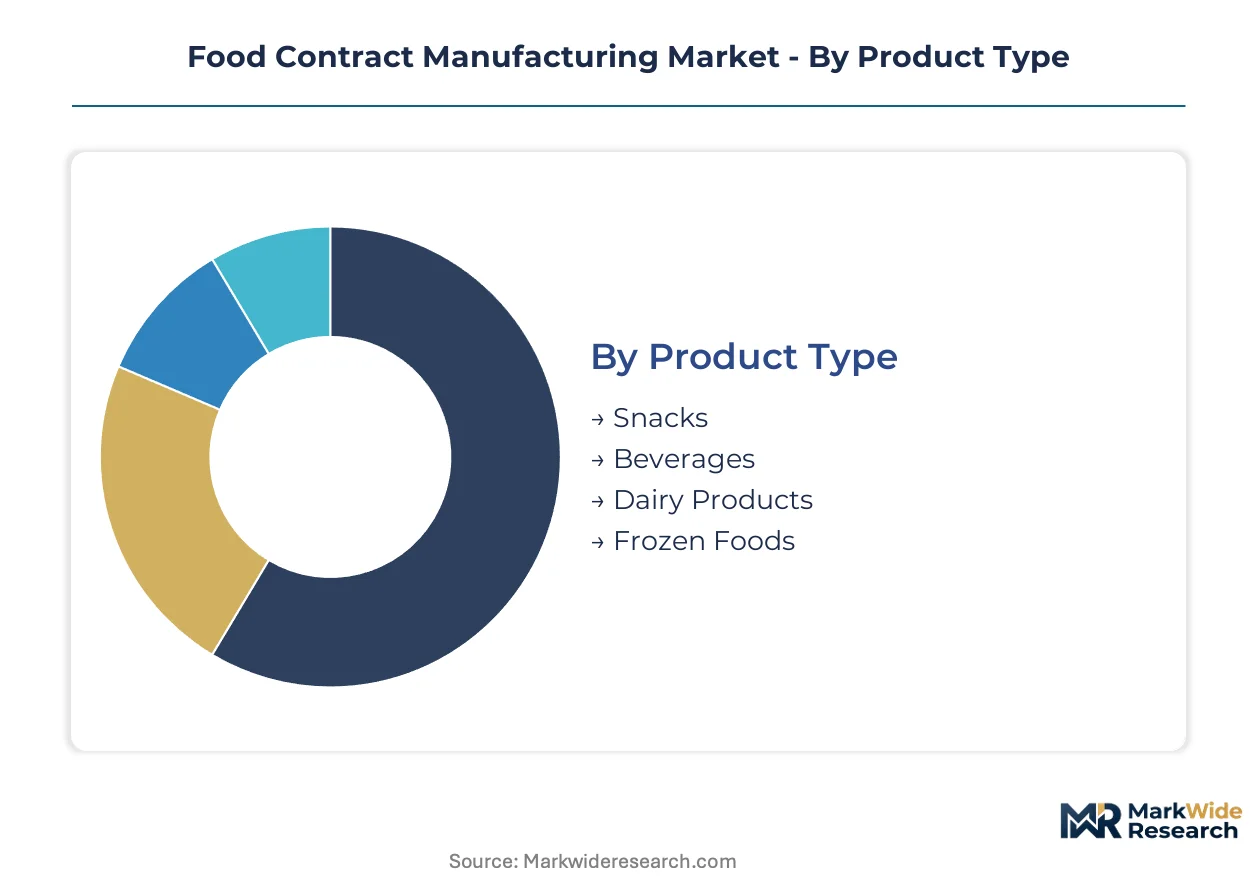
Understanding the varied segments within the food contract manufacturing market reveals distinct demand patterns and operational requirements. This segmentation highlights the diverse needs of food brands seeking external production capabilities. Each category offers unique opportunities for specialized service providers.
Product Type:
The product type segmentation highlights the customization versus standardization spectrum in outsourced food production.
- Snacks:Snack products encompass a broad range from extruded goods to baked items, often requiring specialized ingredient handling. Demand for clean-label, functional snacks drives co-manufacturers to invest in advanced processing technologies like HPP, particularly for agile DTC brands.
- Beverages:This segment includes carbonated drinks, juices, and plant-based milks, frequently needing aseptic filling or hot-fill capabilities. North American functional beverage brands prioritize partners offering flexible, small-batch runs to accelerate speed-to-market for novel product introductions.
- Dairy Products:Contract manufacturers handle a range of dairy items, from yogurt to cheese, requiring stringent cold chain management and specific processing equipment.
- Frozen Foods:This segment covers prepared meals, vegetables, and desserts, demanding specialized freezing technologies and efficient packaging lines.
Leading the category by volume: Snacks. Growing fastest: Beverages.
Service Type:
Service type segmentation differentiates offerings based on margin potential and operational complexity for contract manufacturers.
- Private Label:This high-volume segment involves producing goods under a retailer's brand, often for supermarkets, demanding cost-efficiency and consistent quality. It represents a mature market with established players, where scale and reliable supply chains are critical competitive factors.
- Co-Packing:Co-packing involves a third-party facility manufacturing and packaging products for a brand, allowing asset-light CPG firms to focus on marketing. Brands seek partners with specialized equipment and certifications for niche categories like plant-based foods, minimizing capital outlays.
- Formulation:This specialized service involves developing new product recipes or optimizing existing ones, offering higher margin opportunities for contractors with R&D capabilities.
- Packaging:Outsourced packaging services focus on final product presentation, including specialized formats and sustainable materials, crucial for brand differentiation.
The category sees significant activity in Co-Packing and Formulation.
Distribution Channel:
Distribution channel analysis segments the market by the primary route products take to reach the end consumer.
- Retail:This channel encompasses traditional grocery stores and specialty food retailers, requiring contract manufacturers to meet diverse packaging and logistics demands. European markets, particularly Germany, show strong demand for co-packing services tailored for retail, emphasizing efficiency.
- Online:The online channel includes direct-to-consumer sales and e-commerce platforms, necessitating agile production for smaller batches and robust fulfillment capabilities. DTC food brands rely on flexible contractors to manage production and packaging for direct shipment, bypassing traditional retail infrastructure.
- Wholesale:Wholesale distribution involves supplying large quantities to distributors or other businesses, often requiring bulk packaging and competitive pricing from manufacturers.
- Food Service:This channel serves restaurants, cafeterias, and institutional clients, demanding specific portion sizes, bulk formats, and consistent product quality.
Innovation is concentrated in Online, while Retail maintains its established presence.
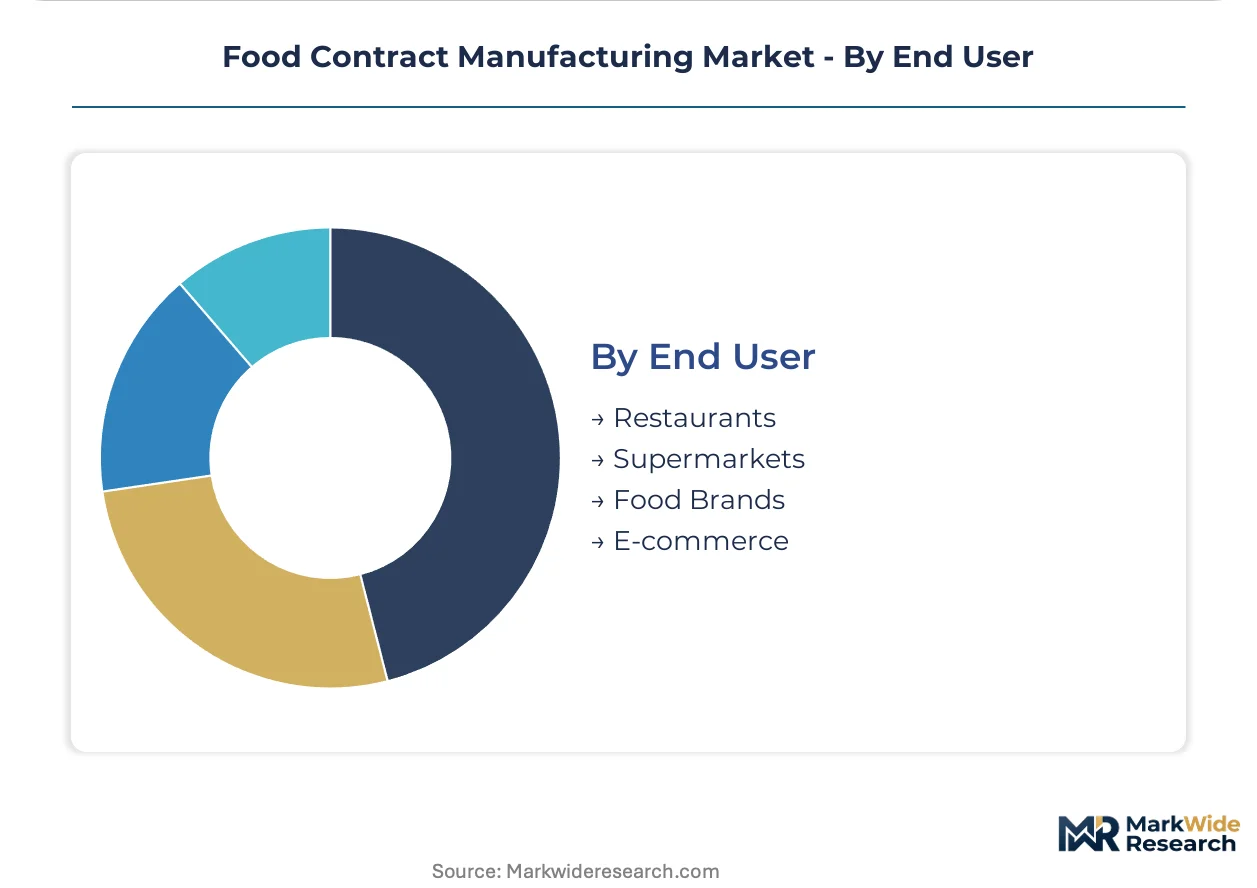
End User:
End user segmentation reflects the varying maturity levels and strategic priorities of different customer types in the market.
- Food Brands:These are CPG firms outsourcing production to focus on marketing, R&D, and brand development, seeking partners with advanced technological capabilities. The shift towards asset-light business models among these brands drives demand for specialized co-manufacturing services, especially for niche products.
- Supermarkets:Supermarkets utilize contract manufacturers primarily for private label products, allowing them to offer store-branded goods with competitive pricing and controlled quality. This segment represents a high-volume, mature demand base for standardized production, ensuring consistent supply for consumer staples.
- Restaurants:Restaurants outsource specific food preparations or ingredients to ensure consistency, reduce labor costs, and manage inventory efficiently.
- E-commerce:E-commerce platforms, often linked to DTC brands, rely on contract manufacturers for agile production and packaging suitable for direct customer fulfillment.
The segment's dynamism is driven by Food Brands, with Supermarkets representing a stable demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The food contract manufacturing market exhibits a distinct geographical split between regions with high consumption demand and those with strong production capabilities. This dynamic influences where brands seek specialized co-packing and where raw material processing is concentrated. Regulatory environments and consumer preferences further shape regional market development.
United States
Demand for specialized contract manufacturing in the United States is driven by DTC brands and plant-based innovation. The US FDA's Food Safety Modernization Act (FSMA) mandates stringent quality and traceability. California's food tech hubs foster agile co-packers for novel functional snacks.
Germany
Germany exhibits robust demand for sophisticated co-packing services, particularly within its mature private label and retail segments. Adherence to European Food Safety Authority (EFSA) regulations is critical for market access. The Rhine-Ruhr industrial region hosts numerous specialized contract manufacturers serving European supermarkets.
Thailand
Thailand's food contract manufacturing benefits from rising local convenience food demand and its export hub position. The Thai FDA enforces standards crucial for domestic and international market access. The Eastern Economic Corridor (EEC) develops modern food processing parks, drawing investment into advanced co-manufacturing.
India
India's market expansion stems from increasing packaged food consumption and the need for scalable production among emerging brands. The Food Safety and Standards Authority of India (FSSAI) sets comprehensive standards for safety and quality. Major food processing clusters in Maharashtra and Gujarat provide extensive contract manufacturing capabilities.
Brazil
Brazil's large domestic market and robust agricultural base drive demand for diverse food contract manufacturing services. The National Health Surveillance Agency (ANVISA) ensures compliance with health and safety regulations. São Paulo state concentrates significant food processing infrastructure, attracting numerous co-packing and private label operations.
Food Contract Manufacturing Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered competitive structure within the food contract manufacturing market. This landscape features global ingredient suppliers, specialized co-packers, and dedicated private label manufacturers. Companies pursue strategic partnerships to expand service offerings and invest in technology licensing for advanced processing capabilities. Many firms are also undertaking capacity expansion to meet growing demand for niche categories like plant-based foods.
At the scale-driven end of the market, players like Kerry Group Plc and Archer Daniels Midland Company exemplify large-scale agricultural commodity processing and sophisticated ingredient systems. Kerry Group Plc occupies a position as a leading provider of formulation and taste solutions, catering to complex product development needs. Archer Daniels Midland Company leverages its extensive global infrastructure for cost-effective co-manufacturing solutions, particularly for high-volume segments. Cargill Inc. also sits within this tier, providing broad agricultural and food ingredient services that enable comprehensive contract manufacturing capabilities for a wide range of food brands seeking integrated supply chain partners.
| Leading Market Players |
|---|
| Kerry Group Plc |
| Döhler Group SE |
| Archer Daniels Midland Company |
| ConAgra Foods Inc. |
| Bunge Limited |
| Cargill Inc. |
| Nestlé S.A. |
| Olam Nigeria Limited |
| Royal FrieslandCampina N.V. |
| Others |
Cost & Logistics Intelligence
Food Brands increasingly demand flexible, project-based pricing structures to manage new product introductions without significant capital outlay. This shift allows manufacturers to offer specialized services, influencing overall market pricing dynamics.
Pricing Analysis
Margin tightening in co-manufacturing reflects intense competition and input cost volatility. Contract-based long-term offtake dominates for private label, while project-based pricing suits novel product formulation. Advanced technological capabilities like High-Pressure Processing (HPP) and stringent certifications such as ISO 22000 justify premium rates. Supermarkets seeking private label products are highly price-sensitive, whereas Direct-to-Consumer (DTC) brands prioritize specialized capabilities and speed-to-market.
Supply Chain Analysis
Logistics and freight costs significantly influence ingredient sourcing and finished product delivery within food contract manufacturing. Manufacturing capabilities concentrate in regions like the US for plant-based innovation and Germany for retail co-packing. The industry depends on stable supplies of agricultural commodities and specialized packaging solutions. Capacity constraints in advanced processing, such as aseptic filling, present a structural risk. Distribution runs through established retail channels, alongside direct-to-consumer platforms for agile brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food contract manufacturing market operates under specific supply constraints, particularly for advanced processing technologies. Limited specialized capacity in aseptic filling for beverages props up pricing in this niche.
For Market Incumbents: Deepen technological investments in advanced processing capabilities like HPP and digital twin technology. Enhance R&D collaboration with Consumer Packaged Goods (CPG) brands for novel formulations. Input cost volatility and evolving regulatory compliance overhead present ongoing margin pressures. Invest in robust quality assurance systems and certifications like ISO 22000 to maintain market access.
For New Entrants and Emerging Players: Enter via specialized service offerings focusing on emerging categories like plant-based foods and functional snacks. Target underpenetrated Southeast Asian markets with sophisticated co-packing services. The North American functional beverage sector offers a penetrable segment for agile, small-batch production. Offer blockchain-enabled traceability as a premium service to meet consumer demand for verifiable food safety data.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized specialized co-manufacturers in European markets experiencing compliance overhead. The market exhibits strong long-term viability over a 5-10 year window, driven by CPG firms' asset-light strategies. Target firms with advanced processing capabilities or certifications for allergen management. Watch for increased merger and acquisition activity among ingredient suppliers acquiring co-packers, indicating vertical integration plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Niche Production | Meets growing demand for specialized categories like plant-based foods in the US. |
| Investment in Traceability Technology | Enhances supply chain transparency and meets regulatory demands from European clients. |
| "Concept-to-Commercialization" Services | Provides high-value partnerships for brands seeking full product development support. |
| Geographic Expansion into Southeast Asia | Captures rising local demand for processed foods in underpenetrated markets. |
| Digital Twin Technology Adoption | Optimizes production processes and allows virtual testing for diverse client portfolios. |
Research Approach
US FDA filings, European Food Safety Authority (EFSA) reports, and industry association publications formed the secondary backbone of this analysis. This was triangulated with primary interviews conducted with CPG brand managers, contract manufacturing plant managers, and food scientists. Insights from quality assurance professionals further validated market trends. A combination of bottom-up data aggregation and top-down market sizing ensured robust validation.
A bottom-up approach, validated by top-down market sizing, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included product type, service type, distribution channel, and end user. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Industry-specific forecast inputs included anticipated shifts in plant-based food consumption and regulatory compliance costs.
Revisions become necessary when significant shifts in agricultural commodity prices or major regulatory changes materialize. Forecasts reflect assumptions about market stability and technological adoption over the projection horizon. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Peer-To-Peer Dining Market
Food Service
Air Fryer Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Commercial Cutlery Market
Food Service
Shaker Bottles Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Onboard Rail Catering Market
Food Service
Food Truck Services Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Global Online Food Delivery Services Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Stirrers Market
Food Service
Smoker Grill Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Commercial Charbroiler Market
Food Service
Cutting Boards Market